
 China Architectural Coatings Market | 2026-2036
China Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
China Architectural Coatings Market Analysis
Color-matching software and digital specification services is consolidating what contractors and architects actually purchase, shifting transactions from commodity buckets to configured solutions. 3TREESGROUP leverages its domestic distribution depth to anchor project-specified volume in southern provinces. Nippon Paint Holdings Co., Ltd. sustains premium positioning through R&D intensity in antimicrobial and self-cleaning film technologies. Carpoly Chemical Group Co., Ltd. dominates the mid-tier interior segment through manufacturing scale and brand recognition in Guangdong province.
Architectural coatings are liquid or powder film-forming materials applied to building substrates for protection, decoration, and functional performance, typically comprising binders, pigments, solvents or water carriers, and additives that cure to form adherent layers between 25 and 150 microns dry-film thickness. Their primary commercial purpose is to extend substrate service life while meeting aesthetic and regulatory requirements in built environments. Interior coatings command the largest volume pool as residential renovation cycles compress, while water-based technology captures the fastest expansion trajectory as solvent-based systems face escalating environmental compliance costs. Specialty coatings concentrate margin pools where fire-resistance and anti-corrosion functionalities justify price premiums over standard decorative grades.
China's Ministry of Ecology and Environment enforces GB 18582 limits on VOC content in interior wall coatings, while SAMR administers mandatory product certification that gates market access for imported and domestic formulations alike. The dual carbon goals are forcing binder suppliers to reformulate away from petrochemical feedstocks toward bio-based and recycled-content alternatives. Stakeholders must monitor how provincial enforcement variance between Jiangsu, Zhejiang, and Guangdong shapes regional cost structures and product availability.
Market Dynamics
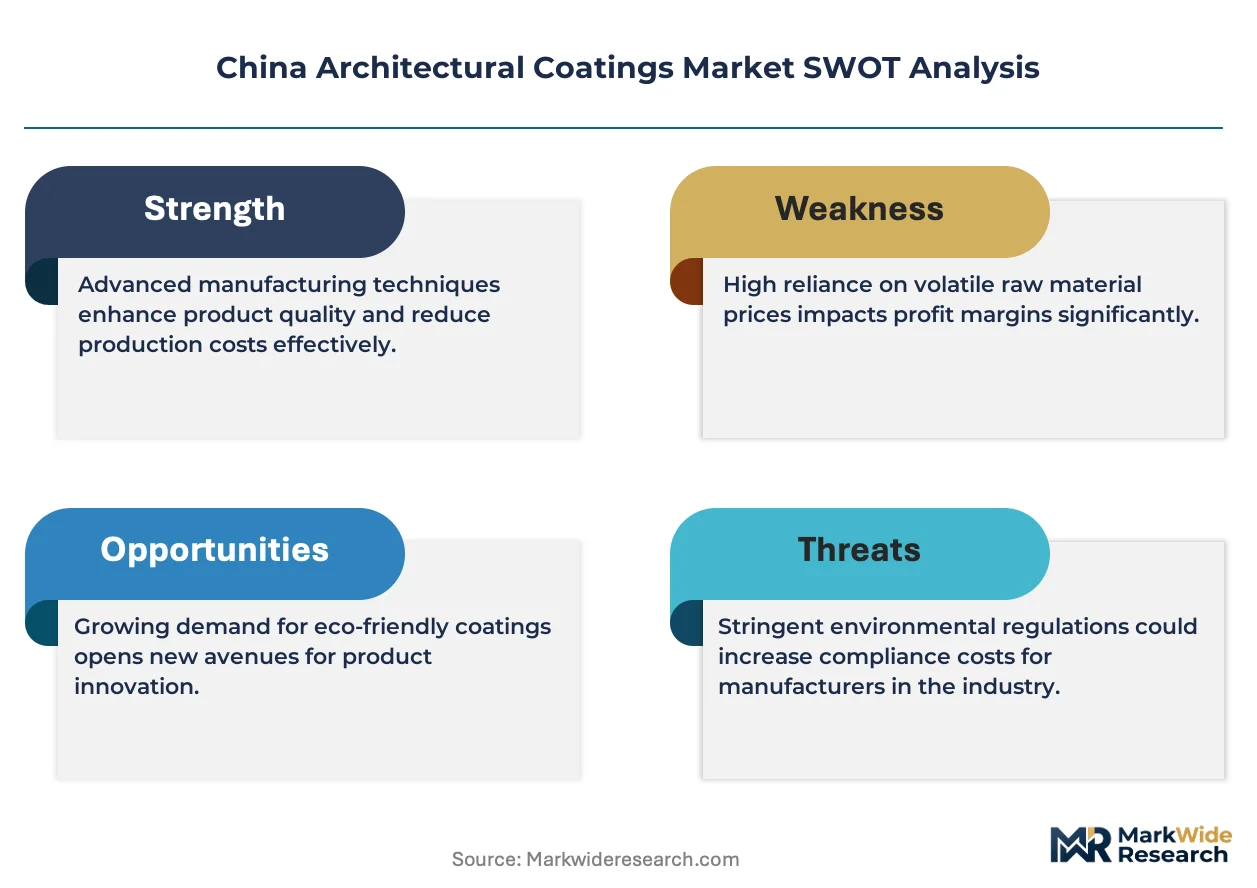
China's dual carbon goals and tightening GB standards on VOC emissions are forcing wholesale reformulation across the architectural coatings sector, compressing solvent-based capacity while accelerating capital redeployment toward water-based and bio-based binder systems.
Growth Catalysts
- Residential renovation cycles:Tier-two cities are accelerating interior refurbishment activity, pulling low-VOC wall coatings into renovation specifications that previously accepted standard grades.
- GB 18582 enforcement:MEE's progressively tighter VOC content ceilings for interior wall coatings is mandating technology upgrades that advantage compliant domestic producers.
- Yangtze River Delta concentration:Shanghai and surrounding Jiangsu-Zhejiang manufacturing clusters anchor both production scale and consumption density, reducing logistics friction for project-specified volume.
Market Restraints
- Petrochemical feedstock volatility:Binder raw material costs fluctuate with crude oil and propylene oxide pricing, compressing margin stability for water-based acrylic emulsion producers.
- Guangdong supply concentration:Southern province manufacturing dominance creates geographic risk exposure for national distributors dependent on Pearl River Delta production.
- Solvent-based legacy capacity:Existing investments in high-VOC production lines face accelerated obsolescence before depreciation cycles complete, stranding capital for mid-tier operators.
Strategic Opportunities
- Western China penetration:Chengdu-Chongqing urban corridor expansion offers underdeveloped specification channels for premium interior and exterior coating systems.
- Digital specification platforms:Color-matching software and cloud-based architect-contractor interfaces are creating new transaction layers between formulation houses and project owners.
- Dual carbon-aligned procurement:State-owned developer green building mandates are opening preferential access for coatings with verified recycled content and bio-based binder fractions.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise combining polymer science with regulatory compliance is concentrated among senior talent at established players, constraining R&D expansion.
- SAMR certification timelines:Mandatory product certification gates for imported and domestic formulations alike extend market entry cycles, particularly for novel bio-based chemistries lacking precedent dossiers.
- Provincial enforcement variance:Divergent implementation intensity between Jiangsu, Zhejiang, and Guangdong environmental authorities complicates national pricing and product portfolio standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Architectural Coatings Market |
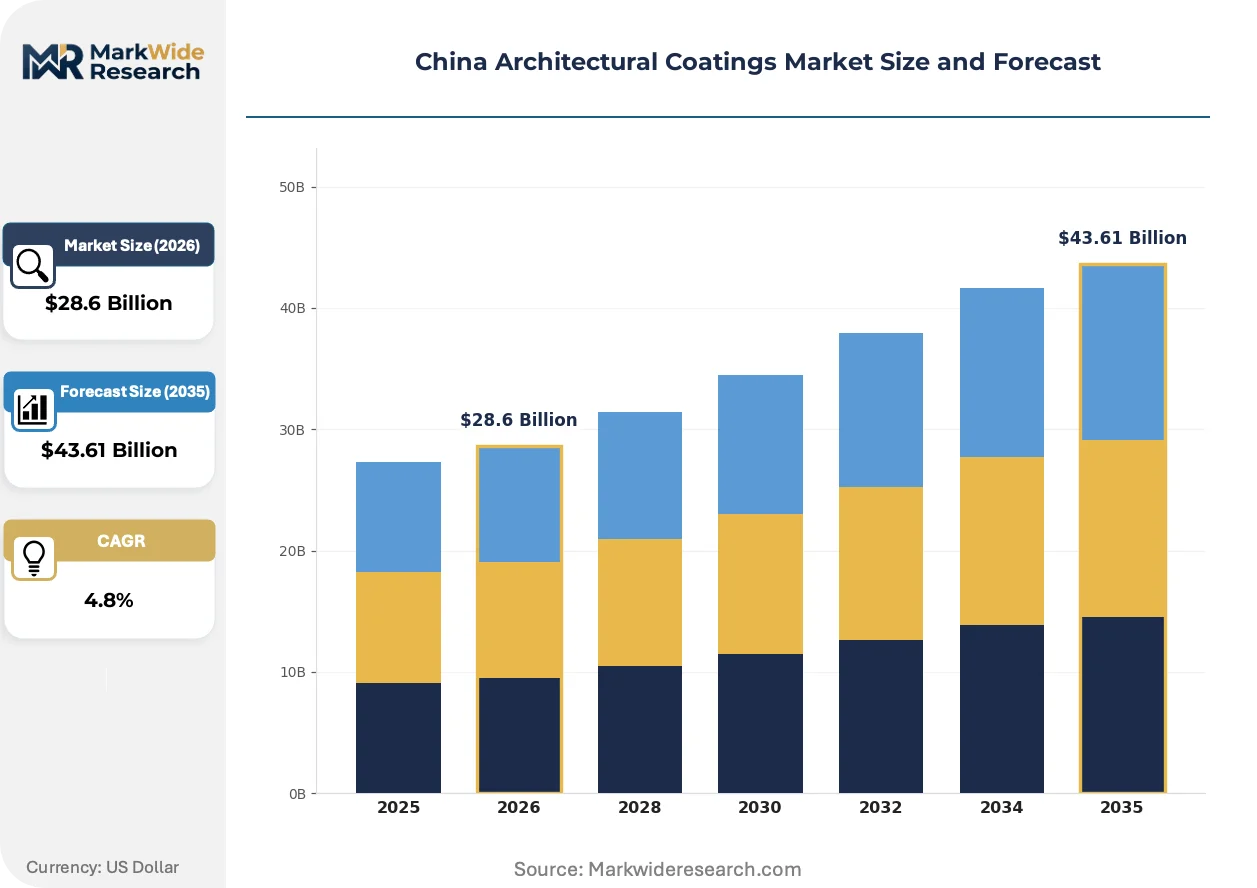
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Coatings, Exterior Coatings, Wood Finishes, Specialty Coatings Application: Residential, Commercial, Industrial, Educational Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Curable End User: Contractors, Homeowners, Architects, Builders |
| Companies Covered | Carpoly Chemical Group Co., Ltd., Guangdong Maydos Building Materials Limited Company, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Jotun, AkzoNobel N.V., 3TREESGROUP, Axalta Coating Systems, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Architectural Coatings Market Emerging Trajectories
Digital tools are restructuring how architectural coatings are specified, purchased, and delivered, collapsing traditional distributor layers while embedding performance data directly into building information modeling workflows.
Water-borne acrylic emulsion technology is overtaking solvent-based alkyd systems in metal protection and exterior masonry applications. Commercial developers in Shanghai and Shenzhen are specifying emulsion-based primers for high-rise facades at accelerating pace. This shift is compressing demand for mineral spirits-based inventory while expanding tank farm requirements for aqueous resin storage.
MEE's progressive tightening of GB 18582 VOC limits is forcing binder suppliers toward low-emission chemistries. Domestic producers are reformulating interior wall coatings to meet sub-50g/L thresholds ahead of enforcement windows. Guangdong and Jiangsu manufacturing clusters are absorbing the highest compliance costs as provincial authorities accelerate inspection frequency.
Architects and general contractors are consolidating purchase authority through digital specification platforms that embed color-matching software and performance databases. Traditional distributor relationships are fragmentating as project owners demand configured solutions rather than commodity buckets. This pattern concentrates in Yangtze River Delta commercial construction where specification complexity exceeds what standard distribution can support.
China Architectural Coatings Market Segmentation
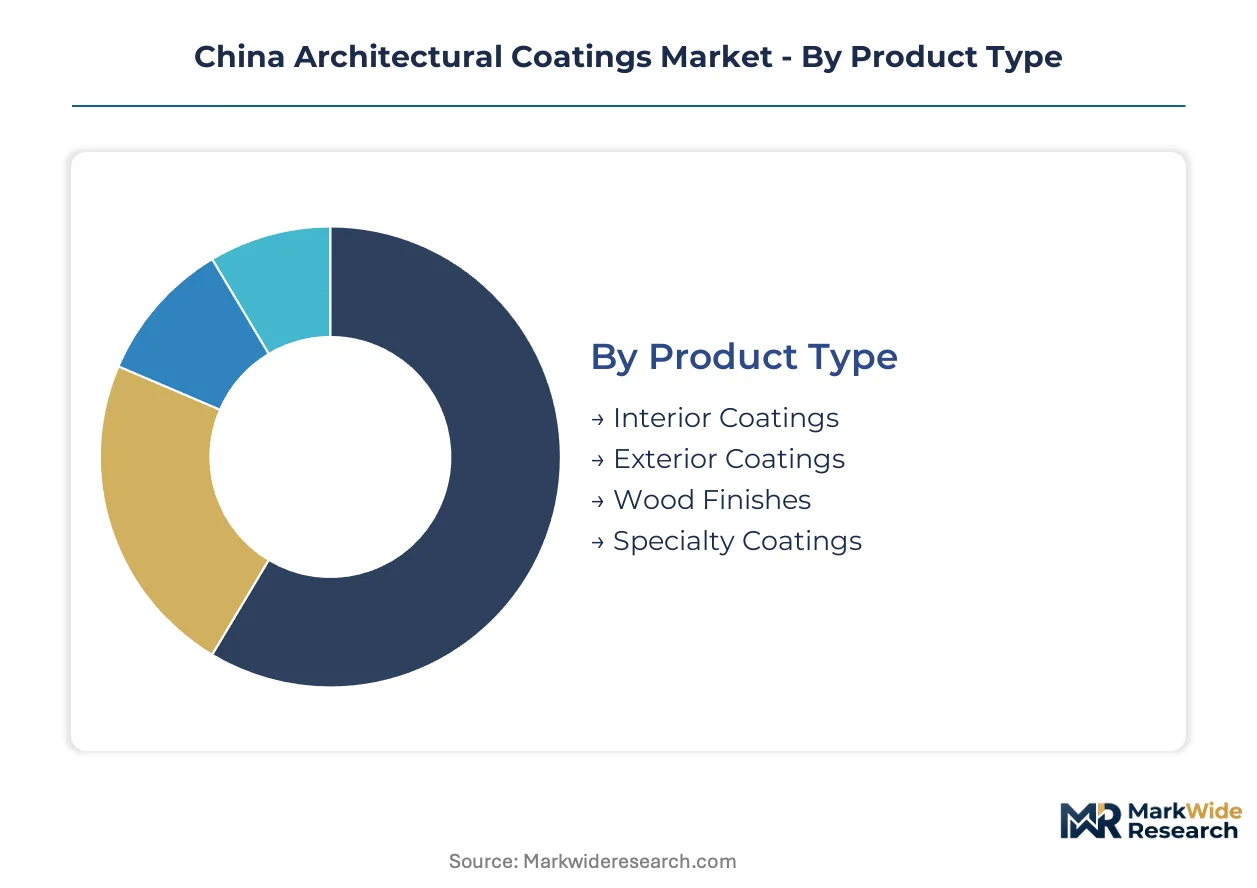
Architectural coatings in China fragment across formulation chemistry, substrate application, and procurement authority. Each segmentation axis reveals distinct margin structures and compliance exposure under tightening GB standards and dual carbon mandates.
Product Type:
Buyers select product categories based on substrate protection requirements and interior versus exterior exposure conditions.
- Interior Coatings:Water-based acrylic and vinyl-acetate emulsions formulated for wall and ceiling application in residential and commercial spaces. Demand concentrates in tier-two city renovation cycles across Jiangsu and Zhejiang provinces, where compressed refurbishment timelines favor low-VOC formulations that meet GB 18582 sub-50g/L thresholds ahead of enforcement windows.
- Exterior Coatings:Elastomeric acrylics, silicone-modified systems, and fluoropolymer-based finishes engineered for UV resistance and thermal cycling durability. Shanghai and Shenzhen commercial developers specify these for high-rise facades, pulling volume away from solvent-based alkyd alternatives as MEE inspection frequency accelerates in Yangtze River Delta manufacturing clusters.
- Wood Finishes:Polyurethane and nitrocellulose lacquers for interior trim, furniture, and decorative millwork applications.
- Specialty Coatings:Intumescent fire-resistance, anti-microbial, and self-cleaning film technologies commanding price premiums over standard decorative grades.
Interior Coatings leads on scale; Specialty Coatings leads on momentum.
Application:
Project type determines specification complexity, with commercial and institutional builds demanding certified performance data that residential renovation often bypasses.
- Residential:Interior wall and ceiling coatings for new construction and refurbishment, plus exterior masonry and trim finishes. Volume concentrates in tier-two cities where renovation cycles compress and homeowners prioritize low-emission products for occupied-space application.
- Commercial:High-performance facade systems, interior specification coatings, and fire-rated assemblies for office, retail, and hospitality developments. Shanghai and Shenzhen developers drive demand for emulsion-based primers and digital color-matching services that embed directly into building information modeling workflows.
- Industrial:Protective coatings for manufacturing facilities, warehouses, and infrastructure with corrosion and chemical resistance requirements.
- Educational:Anti-microbial and low-odor formulations for schools and universities, with procurement increasingly channeled through state-mandated green building frameworks.
Residential dominates absolute volume; Commercial shows the steepest specification upgrade trajectory.
Technology:
Environmental compliance cost differentials are accelerating platform shifts that reshape capital deployment across manufacturing assets.
- Water-Based:Acrylic, styrene-acrylic, and polyurethane dispersions using water as primary carrier, with VOC content typically below regulatory ceilings. Guangdong and Jiangsu producers absorb highest compliance costs as provincial MEE authorities accelerate inspection frequency, while Yangtze River Delta clusters expand tank farm capacity for aqueous resin storage.
- Solvent-Based:Alkyd, epoxy, and polyurethane systems using mineral spirits or oxygenated solvents as carriers. Legacy capacity faces accelerated obsolescence before depreciation cycles complete, stranding capital for mid-tier operators dependent on high-VOC production lines.
- Powder Coatings:Thermosetting resins applied electrostatically and cured without liquid carriers, eliminating VOC emissions entirely.
- UV-Curable:Acrylate oligomer systems polymerized by ultraviolet radiation, offering instant cure and minimal solvent content for specialized architectural applications.
Water-Based commands the largest volume pool; Powder Coatings gains share fastest in industrial-adjacent segments.
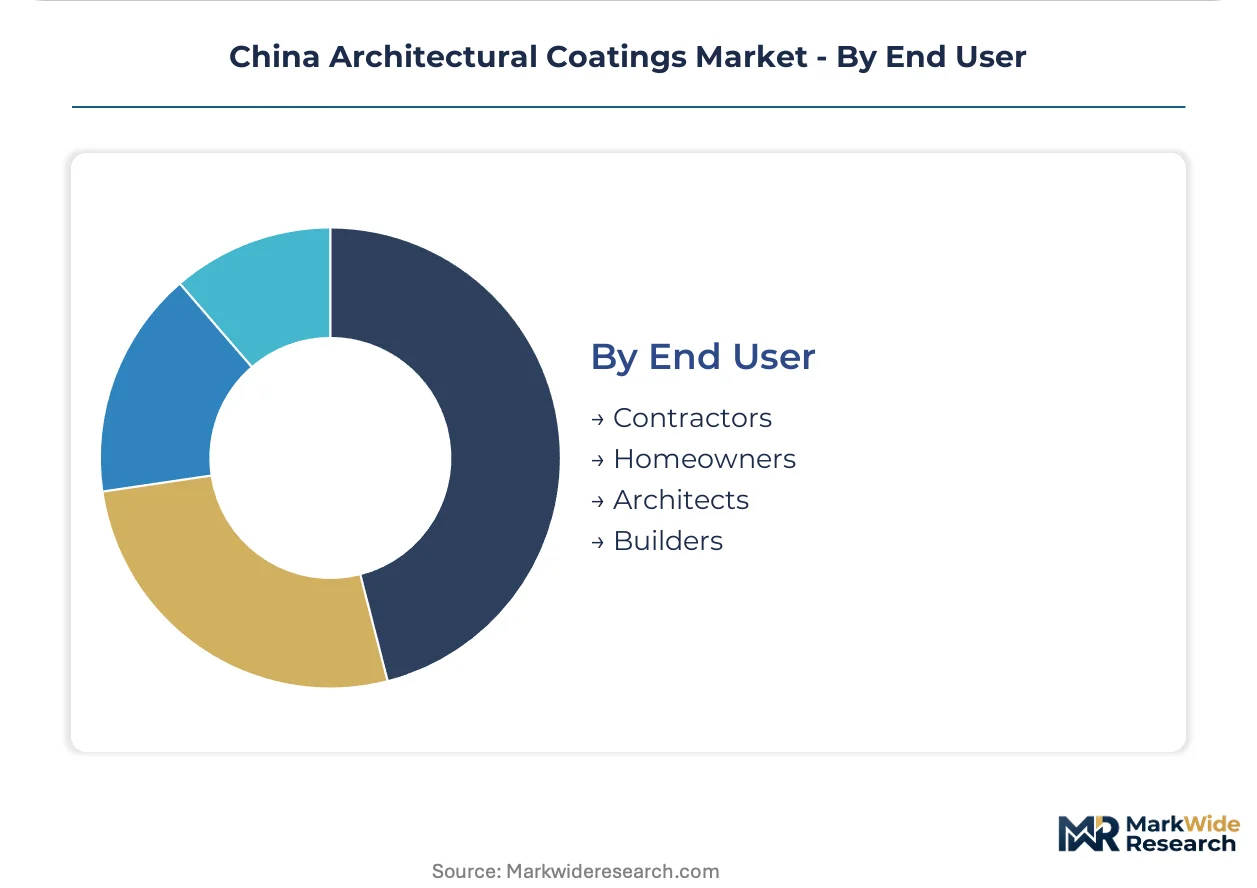
End User:
Procurement authority is consolidating toward specification professionals who configure solutions rather than accept commodity buckets.
- Contractors:General and specialty trades purchasing configured coating systems for project execution. Digital specification platforms and color-matching software are collapsing traditional distributor layers, embedding performance data directly into procurement workflows concentrated in Yangtze River Delta commercial construction.
- Architects:Design professionals specifying coating performance criteria, color standards, and sustainability credentials. SAMR certification requirements and GB standard compliance documentation gate market access for formulations lacking precedent dossiers.
- Homeowners:Retail purchasers of interior renovation products, increasingly influenced by low-VOC labeling and dual carbon-aligned green building awareness.
- Builders:Residential and commercial developers procuring at scale for new construction, with state-owned entities opening preferential access for coatings with verified recycled content and bio-based binder fractions.
Contractors anchor transaction volume; Architects control specification value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial enforcement variance on GB 18582 VOC limits is redirecting production investment toward Jiangsu and Zhejiang, where MEE inspection protocols create cost-of-compliance arbitrage against Guangdong's stricter implementation.
Yangtze River Delta
Shanghai and surrounding Jiangsu-Zhejiang manufacturing clusters anchor both production scale and consumption density for water-based acrylic emulsions. MEE's progressively tighter VOC content ceilings mandate technology upgrades that advantage compliant domestic producers clustered around Suzhou and Hangzhou. Yangtze River Delta tank farm capacity for aqueous resin storage is expanding as commercial developers specify emulsion-based primers for high-rise facades.
Pearl River Delta
Guangdong province manufacturing dominance creates geographic risk exposure for national distributors dependent on southern production bases. Provincial environmental authorities accelerate inspection frequency, compressing margin stability for water-based acrylic emulsion producers in Shenzhen and Foshan. Guangdong-based mid-tier operators face stranded capital as existing investments in high-VOC production lines face accelerated obsolescence.
Beijing-Tianjin-Hebei
State-owned developer green building mandates in the capital corridor open preferential access for coatings with verified recycled content. Dual carbon-aligned procurement frameworks from Beijing municipal authorities shape specification requirements for interior renovation in commercial and educational facilities. Tianjin port infrastructure supports import logistics for bio-based binder feedstocks.
Sichuan-Chongqing
Chengdu-Chongqing urban corridor expansion offers underdeveloped specification channels for premium interior and exterior coating systems. Western China penetration strategies concentrate on contractor education for digital color-matching platforms. Chongqing manufacturing investment lags coastal clusters but absorbs transferred capacity from compliance-stressed Guangdong operations.
Shandong Peninsula
Qingdao and Yantai chemical industry bases supply propylene oxide and acrylic monomer feedstocks to downstream emulsion producers. Petrochemical feedstock volatility from regional refinery operations compresses margin stability for water-based formulation houses. Shandong's industrial coatings heritage creates polymer science talent pools that coastal architectural specialists recruit for formulation chemistry expansion.
China Architectural Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with project-specified volume consolidating toward configuration-capable suppliers while commodity interior renovation accepts broader sourcing. The vendor base organizes around three tiers: multinational formulators with R&D intensity in functional film technologies, domestic scale players leveraging manufacturing depth in southern provinces, and regional specialists serving single-province contractor networks. Competitive moves concentrate on digital specification platform partnerships and backward integration into aqueous resin production.
Within the domestic scale tier, 3TREESGROUP leverages distribution depth to anchor project-specified volume, while Carpoly Chemical Group Co., Ltd. occupies a position exemplifying mid-tier interior segment concentration through Guangdong-based manufacturing scale. Nippon Paint Holdings Co., Ltd. represents the multinational formulator archetype, sustaining premium positioning through antimicrobial and self-cleaning film technology portfolios.
| Leading Market Players |
|---|
| Carpoly Chemical Group Co., Ltd. |
| Guangdong Maydos Building Materials Limited Company |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Jotun |
| AkzoNobel N.V. |
| 3TREESGROUP |
| Axalta Coating Systems |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and progressively tightened GB 18582 VOC ceilings gate both qualified supply and premium-tier pricing access, as only reformulation-capable producers can command project-specified volume while legacy solvent-based operators face margin compression from compliance costs.
Pricing Analysis
Distributor margin layers in China's architectural coatings sector compress as digital specification platforms collapse traditional channel structures, with project-based contracting replacing spot purchases for commercial developments. Pricing stratifies across premium functional grades with antimicrobial and self-cleaning certifications, standard water-based emulsions for residential renovation, and economy alkyd systems facing rapid demand erosion. Cost compression in mid-tier interior segments intensifies because Guangdong and Jiangsu manufacturers absorb disproportionate environmental compliance burdens. State-owned developers show lowest price sensitivity for dual carbon-aligned procurement, while independent contractors in tier-two cities remain most cost-conscious.
Supply Chain Analysis
GB 18582 certification and SAMR mandatory product certification gate market access for both imported and domestic formulations, extending entry cycles for novel bio-based chemistries lacking precedent dossiers. Manufacturing concentrates in China, with Jiangsu and Zhejiang clusters expanding aqueous resin storage capacity while Guangdong absorbs compliance-stressed transfers. Propylene oxide, acrylic monomers, and titanium dioxide feedstock costs fluctuate with regional refinery operations and import logistics through Tianjin port. Single-source vulnerability concentrates in Pearl River Delta production bases for national distributors. Distribution runs through project-specified digital platforms and traditional contractor networks serving Yangtze River Delta commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's architectural coatings sector offers margin expansion potential as water-based technology displacement concentrates volume with compliant producers capable of capturing premium-tier specification value.
For Market Incumbents: Anchor project-specified volume through backward integration into aqueous resin production and exclusive digital platform partnerships with Yangtze River Delta architects. Expand tank farm capacity in Jiangsu-Zhejiang clusters to secure logistics advantages as MEE inspection frequency accelerates. Defend against mid-tier solvent-based capacity stranding by accelerating depreciation recognition on legacy high-VOC production lines. For New Entrants and Emerging Players: The premium-economy price-point gap in western China creates white-space opportunity for specification-capable entrants targeting Chengdu-Chongqing commercial construction. Focus initial penetration on contractor education for color-matching software platforms, where incumbent coverage remains thin. Pursue state-owned developer green building mandates as the most penetrable procurement channel for verified bio-based binder fractions. For Investors and Strategic Acquirers: Roll-up economics work for domestic scale players with Guangdong manufacturing depth because provincial enforcement variance creates acquisition targets at compliance-discounted valuations. Five-to-ten year viability hinges on successful reformulation technology transfer and SAMR certification navigation. Watch for inflection when MEE announces sub-50g/L threshold acceleration timelines, which will strand non-compliant capacity and consolidate share toward certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aqueous Resin Production | Jiangsu-Zhejiang tank farm expansion secures supply security for Yangtze River Delta project volume. |
| Digital Specification Platform Partnership | Architect-contractor interface embedding consolidates transaction authority away from traditional distributors. |
| GB 18582 Compliance Certification Investment | MEE sub-50g/L threshold adherence gates market access for interior wall coating formulations. |
| Western China Distribution Buildout | Chengdu-Chongqing corridor penetration captures underdeveloped specification channel growth. |
| Bio-Based Binder Feedstock Sourcing | Dual carbon-aligned procurement preferences from state-owned developers open premium access. |
Methodological Framework
Direct dialogue with formulation chemists, procurement leads at state-owned developers, distribution channel partners, and MEE regional enforcement officers grounded this analysis, combined with secondary validation from SAMR certification databases, China Customs trade data, SEC 10-K filings of listed coatings producers, and provincial environmental authority inspection disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Segmentation outputs across formulation chemistry, substrate application, technology platform, and procurement authority dimensions were modeled throughout the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating residential renovation cycle compression, commercial specification upgrade trajectories, and water-based technology displacement rates. Industry-specific inputs included GB standard enforcement intensity indices and dual carbon procurement mandate adoption curves.
Caveats apply where MEE enforcement acceleration, petrochemical feedstock volatility, or SAMR certification timeline extensions could materially shift the outlook. A model refresh is warranted upon material change in provincial environmental authority inspection protocols or state-owned developer green building mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Granite Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Roof Cover Boards Market
Building Materials
Ireland Cement Market
Building Materials
United Kingdom White Cement Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Fireproof Cladding Market
Building Materials
Building Asphalt Market
Building Materials
Aluminum Door and Window Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Natural Stone Slab Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
East Africa White Cement Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market