
 North America Dry-Mix Mortar Market | 2026-2036
North America Dry-Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dry-Mix Mortar Market Analytics
Polymer-modified cementitious binders is rebalancing cost-performance tradeoffs across flooring and wall-covering applications. Sika AG leverages its modified polymer technology leadership to capture specification-driven projects in commercial construction. Saint-Gobain anchors its position through geographic dominance in plaster and joint filler distribution across the southeastern United States. LATICRETE International specializes in high-performance grout formulations for waterproofing applications where building code compliance is non-negotiable.
Dry-mix mortar comprises pre-blended cementitious or gypsum-based powders, typically incorporating graded aggregates, functional additives, and redispersible polymer powders at dosages between one and five percent by weight, designed for on-site mixing with water to achieve controlled rheology and bond strength for tile setting, plastering, or repair. Tile adhesive commands the largest product-type position due to relentless multifamily housing construction, while eco-friendly formulations represent the fastest-expanding technology segment as California Title 24 and similar codes drive low-VOC specification. Modified polymer systems capture premium margin pools in commercial flooring where deflection tolerance and extended open time justify higher material cost.
OSHA enforces permissible exposure limits on respirable crystalline silica during dry-mix handling, compelling manufacturers toward pre-wetted or dust-suppressed packaging formats. EPA regional offices coordinate with state-level environmental agencies to regulate VOC content in architectural coatings and related construction materials, directly affecting formulation choices for wall-covering and surface-repair products. The Federal Trade Commission monitors green marketing claims tied to eco-friendly formulation positioning, raising compliance stakes for product labeling. Stakeholders must track evolving state-adopted versions of ASHRAE standards and local amendments to International Building Code chapters governing exterior insulation and finish systems, as these will determine which plaster and adhesive technologies gain specification traction in climate-zone-specific construction.
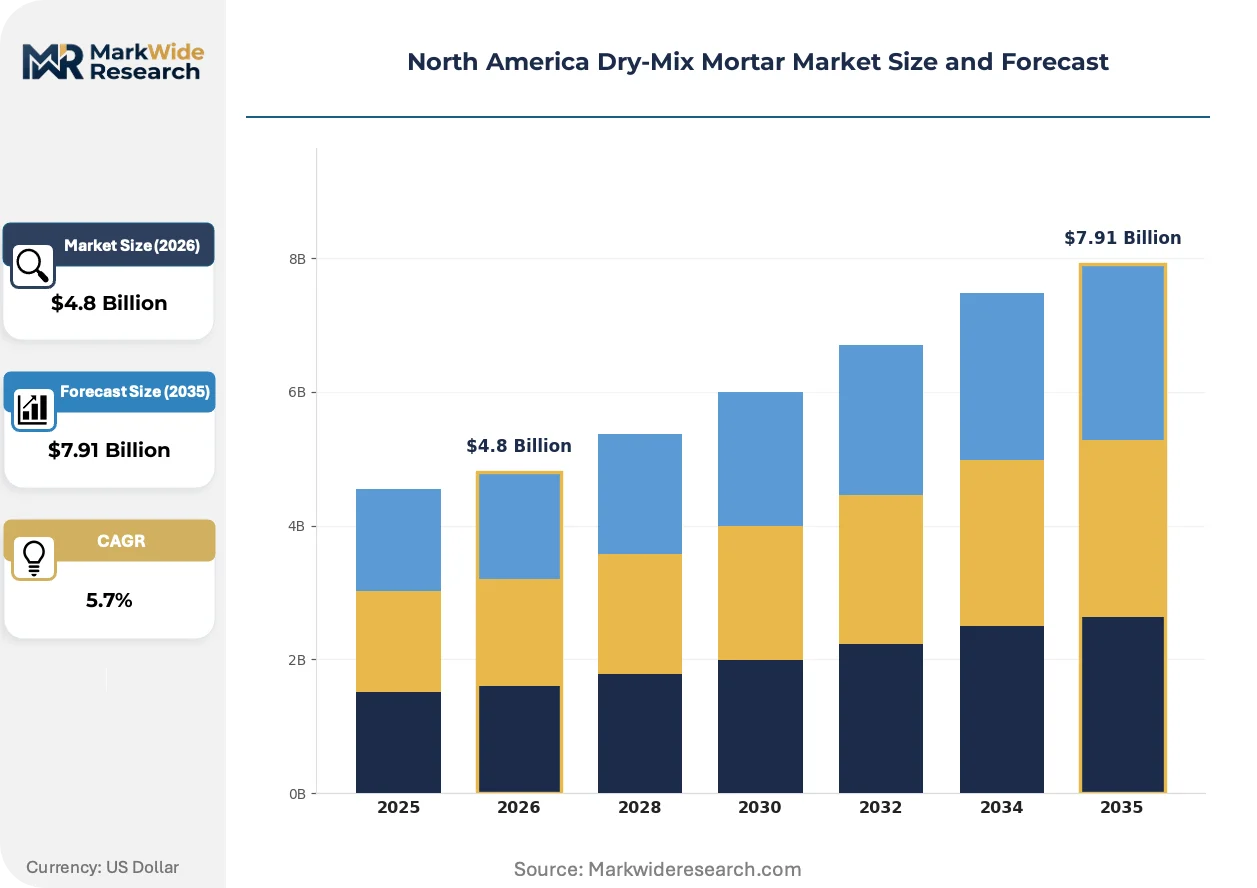
Market Dynamics
Polymer-modified formulation technology is compressing traditional cement-only product margins while OSHA silica regulations force packaging and handling infrastructure reinvestment across manufacturing footprints.
Growth Catalysts
- Multifamily Housing Starts:Texas, Florida, and California are absorbing record volumes of tile adhesive and self-leveling underlayment as rental construction accelerates.
- California Title 24:Low-VOC mandates for architectural coatings are cascading into dry-mix specification requirements, pulling eco-friendly formulations into mainstream commercial bidding.
- Infrastructure Retrofit Programs:Federal highway and bridge rehabilitation funding is expanding repair mortar demand across state transportation departments.
Market Restraints
- Redispersible Polymer Powder Concentration:Supply of VAE and EVA polymers concentrates among German and Chinese chemical producers, exposing formulators to freight and currency volatility.
- OSHA Permissible Exposure Limits:Respirable crystalline silica thresholds below 50 micrograms per cubic meter are forcing capital-intensive dust suppression systems at blending facilities.
- Site-Mixed Mortar Substitution:Large commercial contractors in cost-sensitive markets retain on-site batching capability, capping ready-mix penetration in industrial flooring.
Strategic Opportunities
- Canadian Climate Zones:Exterior insulation and finish system adoption in Ontario and British Columbia is outpacing local plaster manufacturing capacity.
- Pre-Wetted Packaging Formats:Dust-suppressed bags and silo-delivered wet mortars are opening specification pathways in hospital and school construction where silica liability is acute.
- Extended Open-Time Adhesives:Large-format tile installation is converging with radiant floor heating systems, creating demand for deformable, slow-setting binders in luxury residential.
Industry Challenges
- Formulation Chemist Scarcity:Blending operations struggle to hire technical staff capable of balancing rheology modifiers with polymer loadings across climate-specific SKU proliferation.
- State-Level VOC Fragmentation:California, New York, and Massachusetts maintain divergent testing protocols, forcing redundant certification runs for multi-state distribution.
- Silo Logistics Integration:Jobsite-ready delivery systems require real-time moisture control and GPS-tracked replenishment, stretching contractor procurement capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dry-Mix Mortar Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tile Adhesive, Joint Filler, Plaster, Grouts End User: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Development Application: Flooring, Wall Covering, Surface Repair, Waterproofing Technology: Standard Dry-Mix, Modified Polymer, Eco-Friendly Formulations, Custom Blends |
| Companies Covered | Sika AG, Saint-Gobain, Ardex Group, Holcim, CEMEX, LATICRETE International, MAPEI, Wacker Chemical Corporation, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dry-Mix Mortar Market Evolving Landscape
Dry-mix mortar technology is pivoting toward pre-engineered performance tiers as specification authority consolidates with general contractors and asset owners rather than subcontractor preference.
Redispersible polymer powder technology is consolidating quality tiers across flooring and tiling applications. Large-format tile contractors are specifying deformable adhesives with S1 or S2 classification under EN 12004 as default rather than upgrade. This shift is compressing economy-grade cement-only adhesive shelf space in distributor warehouses.
OSHA's silica enforcement memorandum is accelerating pre-wetted mortar adoption in commercial construction. The agency's emphasis on engineering controls over personal protective equipment is redirecting capital toward silo systems and dust-suppressed packaging lines. Hospital and education verticals in California and Texas are now specifying wet delivery as bid prerequisite.
Buying authority is migrating from subcontractor crews to general contractor procurement offices with centralized material certification databases. Master specification templates from major healthcare and retail developers are pre-approving polymer-modified systems, displacing field-level substitution. This concentration is most visible in Texas medical center expansions and Florida multifamily podium construction.
North America Dry-Mix Mortar Market Segmentation
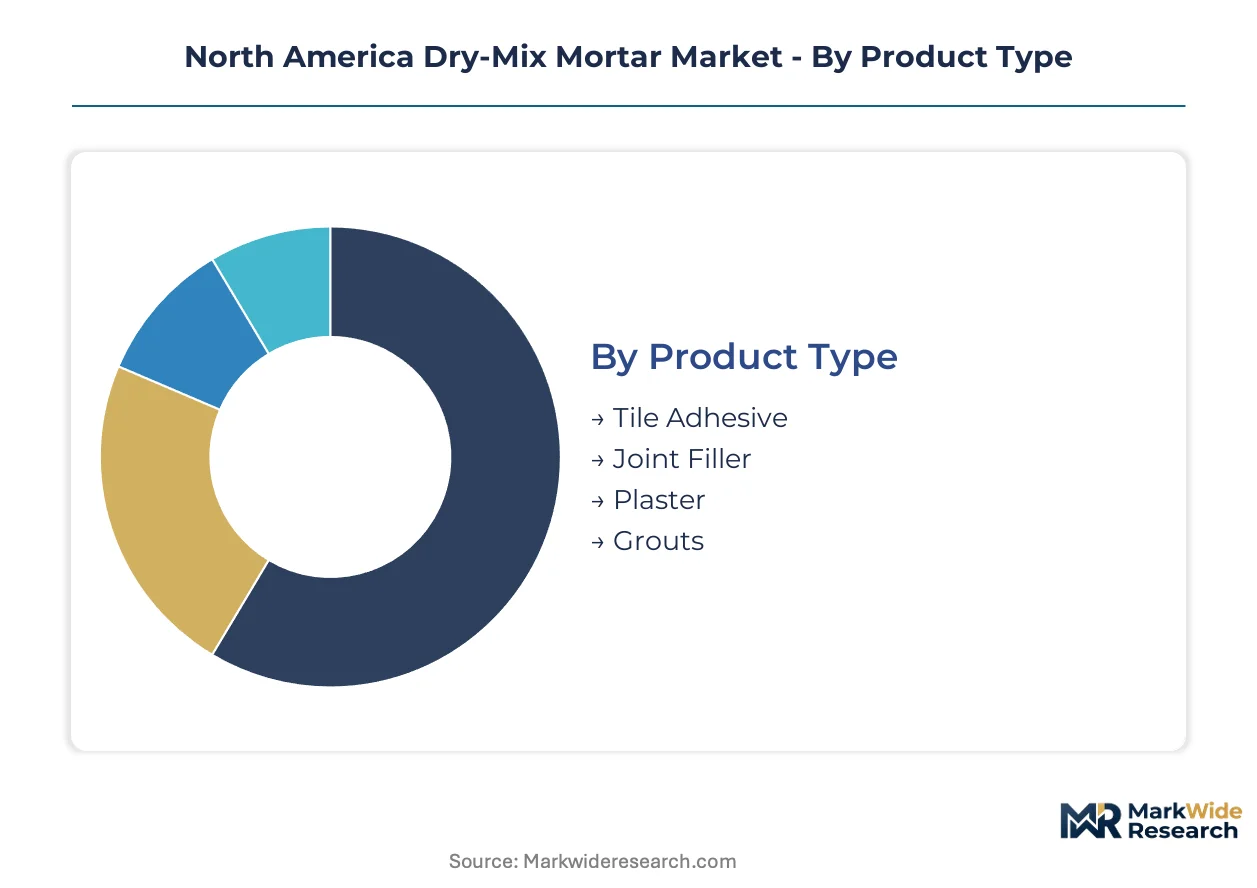
Dry-mix mortar procurement in North America increasingly flows through specification templates controlled by general contractors and asset owners. Segmentation reveals where polymer-modified technologies command premium positioning versus where cement-only formulations retain cost-driven volume.
Product Type:
Material selection hinges on substrate compatibility, deflection tolerance, and building code compliance across flooring and envelope applications.
- Tile Adhesive:Polymer-modified cementitious binders with redispersible powder loadings between one and five percent by weight deliver controlled open time and deformability. Multifamily housing starts across Texas, Florida, and California absorb record volumes as large-format tile specifications become standard in rental construction.
- Plaster:Gypsum or cement-based formulations for interior and exterior finish systems require climate-zone-specific aggregate grading. Exterior insulation and finish system adoption in Ontario and British Columbia is outpacing regional manufacturing capacity, creating supply bottlenecks for polymer-modified base coats.
- Joint Filler:Pre-blended compounds for gypsum board seams and exterior sheathing joints.
- Grouts:Cementitious or epoxy-based formulations for tile joint sealing with chemical resistance specifications.
Tile Adhesive leads on scale; Eco-friendly formulations lead on momentum across product type evolution.
End User:
Project scale and procurement centralization determine whether specification authority rests with subcontractor crews or general contractor offices.
- Residential Construction:Single-family and multifamily builders specify pre-blended mortars for speed and consistency. Southern United States absorption of polymer-modified tile adhesives is climbing fastest as production homebuilders standardize on deformable S1-classified systems.
- Commercial Construction:Healthcare, retail, and office developers deploy master specification templates with pre-approved polymer-modified systems. Texas medical center expansions and Florida multifamily podium construction demonstrate concentrated buying authority migrating to procurement offices with centralized certification databases.
- Industrial Construction:Manufacturing facilities and warehouses with heavy-duty flooring requirements.
- Infrastructure Development:State transportation departments deploy repair mortars for highway and bridge rehabilitation funded through federal programs.
Residential Construction leads on scale; Commercial Construction leads on momentum through specification consolidation.
Application:
Performance requirements vary sharply between structural bonding, aesthetic finish, and protective barrier functions.
- Flooring:Self-leveling underlayments and tile setting systems demand deflection tolerance and extended open time. Large-format tile installation converging with radiant floor heating systems is creating demand for deformable, slow-setting binders in luxury residential segments.
- Waterproofing:LATICRETE International specializes in high-performance grout formulations where building code compliance is non-negotiable. Hospital and school construction in California and Texas now specifies wet delivery as bid prerequisite due to silica liability concerns.
- Wall Covering:Plaster and adhesive systems for interior and exterior vertical surfaces.
- Surface Repair:Patching and rehabilitation mortars for concrete and masonry restoration.
Flooring leads on scale; Waterproofing leads on momentum through regulatory-driven specification upgrades.
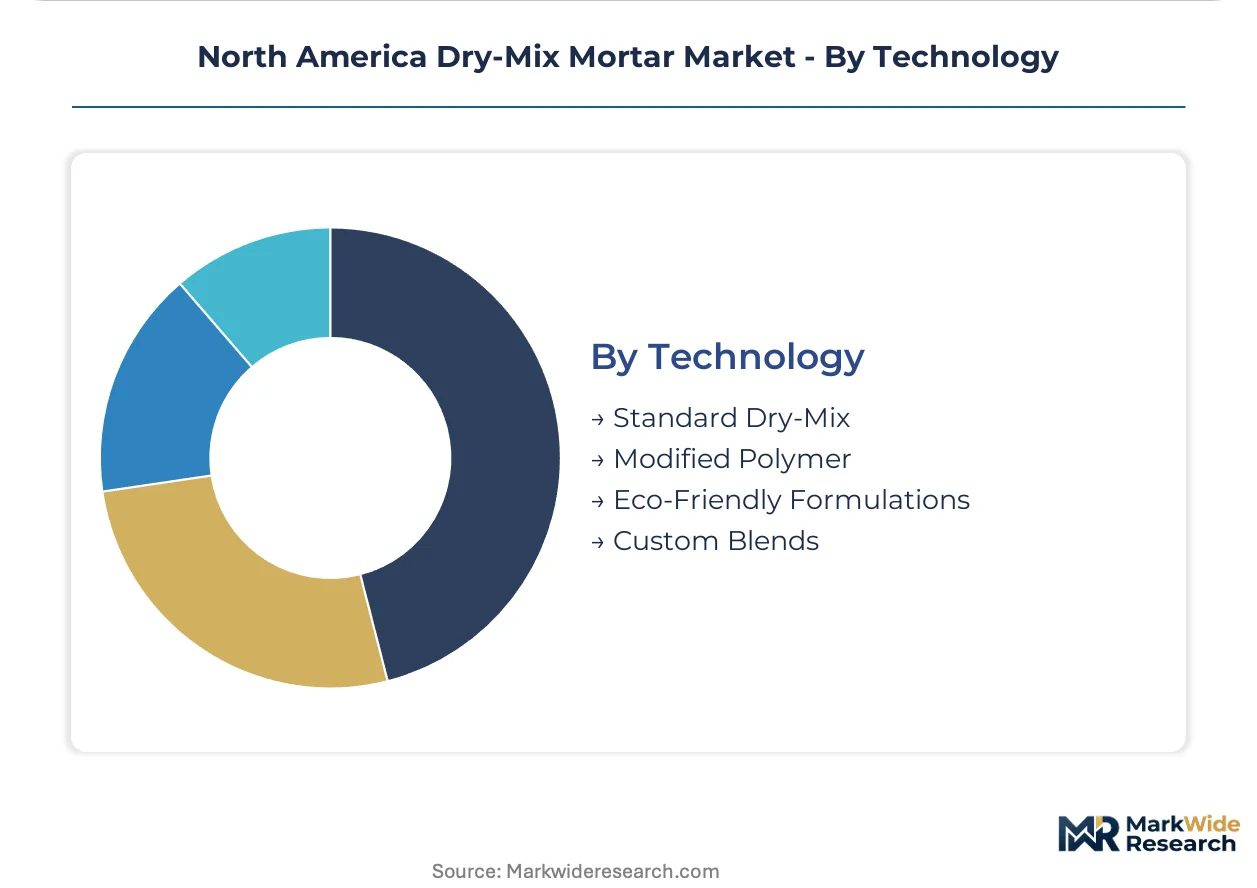
Technology:
Formulation chemistry determines cost structure, performance tier, and regulatory compliance pathway.
- Modified Polymer:Redispersible polymer powder technology consolidates quality tiers across flooring and tiling. Sika AG leverages modified polymer leadership to capture specification-driven commercial projects where deflection tolerance justifies material cost premiums.
- Eco-Friendly Formulations:Low-VOC binders align with California Title 24 and cascading state mandates. Saint-Gobain anchors position through geographic dominance in plaster distribution as environmental specifications pull eco-friendly options into mainstream bidding.
- Standard Dry-Mix:Traditional cement-only formulations for cost-sensitive applications.
- Custom Blends:Project-specific formulations for unique substrate or performance requirements.
Modified Polymer leads on scale; Eco-Friendly Formulations lead on momentum as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors North American dry-mix mortar formulation capacity, with Houston-area blending facilities supplying polymer-modified systems across the southern United States. Regional demand patterns concentrate in Sun Belt metropolitan zones where multifamily construction absorbs record volumes of tile adhesive and self-leveling underlayment.
United States
Texas, Florida, and California absorb the majority of regional tile adhesive volumes as multifamily housing starts accelerate. OSHA silica exposure limits below 50 micrograms per cubic meter are forcing capital-intensive dust suppression retrofits at blending facilities nationwide. Dallas-Fort Worth medical center expansions demonstrate concentrated procurement authority migrating to general contractor offices with centralized certification databases.
Canada
Ontario and British Columbia exterior insulation and finish system adoption is outpacing regional plaster manufacturing capacity. Health Canada coordinates with provincial regulators to enforce low-VOC specifications cascading from ASHRAE climate zone adaptations. Toronto commercial construction specifies pre-wetted mortar delivery as bid prerequisite due to silica liability concerns in hospital and education verticals.
Mexico
Nuevo León industrial corridor demand concentrates in manufacturing facility flooring and heavy-duty repair mortars. The country's national environmental regulator enforces evolving emissions standards affecting cementitious product formulation. Monterrey construction markets exhibit growing specification familiarity with polymer-modified systems as multinational contractor standards penetrate northern border states.
North America Dry-Mix Mortar Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution density, producing a tiered structure where polymer-modified specialists command premium positioning against commodity cement blenders. Market concentration splits between diversified construction chemical conglomerates and focused tile-setting system providers. Three archetypes dominate: vertically integrated raw material suppliers controlling redispersible polymer powder supply, specification-driven technology leaders capturing commercial flooring projects, and geographic specialists anchoring regional plaster distribution. Dominant competitive moves include strategic partnerships for silo logistics integration and portfolio diversification into pre-wetted packaging formats.
Within the technology-leadership tier, Sika AG exemplifies specification-driven positioning through modified polymer expertise, while Saint-Gobain anchors geographic dominance in plaster and joint filler distribution across the southeastern United States. LATICRETE International occupies a specialist position in high-performance grout formulations where building code compliance requirements are non-negotiable.
| Leading Market Players |
|---|
| Sika AG |
| Saint-Gobain |
| Ardex Group |
| Holcim |
| CEMEX |
| LATICRETE International |
| MAPEI |
| Wacker Chemical Corporation |
| Dow Inc. |
| Others |
Value Network & Pricing Analysis
Captive polymer powder supply from German and Chinese chemical producers anchors both formulation cost structures and margin defense for North American dry-mix mortar manufacturers. This upstream control determines whether blenders can absorb freight volatility or must pass through redispersible polymer cost swings to general contractor procurement offices.
Pricing Analysis
Redispersible polymer powder cost pass-through from VAE and EVA suppliers compresses margins on modified cementitious binders. Three-tier pricing structure across premium polymer-modified, standard cementitious, and economy-grade cement-only formulations separates specification-driven commercial projects from cost-sensitive residential volume. Pricing pressure stems from OSHA-mandated dust suppression capital investments at blending facilities. Residential production homebuilders exhibit highest price sensitivity, while healthcare developers accept material cost premiums for pre-wetted delivery systems.
Supply Chain Analysis
Redispersible polymer powder supply rests on German and Chinese specialty chemical producers, with VAE and EVA polymers forming critical formulation inputs. Cement, graded aggregates, and functional additives complete the raw material base. Single-source vulnerability concentrates in polymer powder feedstock, exposing formulators to currency and freight volatility. Distribution runs through regional blending facilities in Texas, Florida, and California, with silo-delivered wet mortars gaining traction in hospital and school construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA silica enforcement below 50 micrograms per cubic meter compounds demand for pre-wetted packaging and dust-suppressed delivery systems, creating specification barriers that favor capital-rich incumbents.
For Market Incumbents: Anticipate polymer powder supply concentration risk by securing long-term offtake agreements with German and Chinese chemical producers. Backward integration into captive redispersible polymer production defends margin position against freight volatility. Pre-wetted mortar capacity expansion in Texas and California captures specification-driven hospital and education verticals where silica liability drives bid prerequisites.
For New Entrants and Emerging Players: Regional plaster distributors in Ontario and British Columbia represent the most penetrable channel partner type for exterior insulation and finish system base coat supply. Canadian climate zone adoption outpaces local manufacturing capacity, creating white-space for silo logistics integration. Target multifamily podium construction in Florida through wet mortar delivery partnerships with general contractor procurement offices holding centralized certification databases.
For Investors and Strategic Acquirers: Roll-up economics work for regional blending operations with established silo logistics networks because specification authority is consolidating with general contractor procurement offices rather than subcontractor crews. Five-to-ten year viability favors facilities with pre-wetted packaging lines and dust suppression infrastructure already deployed. Watch OSHA regional enforcement memoranda as the signal for accelerated capital deployment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Powder | Captive VAE supply from German producers insulates margin against freight volatility. |
| Pre-Wetted Packaging Line Expansion | OSHA silica enforcement in California and Texas hospitals drives bid prerequisites. |
| Silo Logistics Network Buildout | GPS-tracked wet mortar delivery meets general contractor procurement centralization. |
| Canadian Manufacturing Capacity Addition | Ontario and British Columbia exterior insulation adoption outpaces regional supply. |
| Eco-Friendly Formulation Certification | California Title 24 low-VOC mandates cascade into mainstream commercial bidding. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines interviews with dry-mix mortar plant managers, procurement leads at general contractor offices, distribution channel partners, and technical R&D directors with secondary validation from OSHA enforcement memoranda, EPA regional filings, customs and trade data, and SEC 10-K disclosures from construction chemical conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across polymer-modified and cement-only formulation tiers.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including product type, end-use construction vertical, application function, and formulation technology chemistry. CAGRs derive from trend extrapolation of multifamily housing starts, infrastructure retrofit funding flows, and regulatory adoption curves for low-VOC and silica-suppressed specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OSHA enforcement intensity, polymer powder supply disruptions, and state-level VOC fragmentation. The analysis reflects assumptions on regulatory adoption timelines and contractor procurement centralization rates. A small set of named triggers warrants ongoing watch: OSHA regional silica inspection priorities, German chemical producer capacity announcements, and California Title 24 amendment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Market
Building Materials
Fly Ash Bricks Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
North America Construction Aggregates Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Long Steel Market
Building Materials
Natural Stone Market
Building Materials
Drywall Joint Tape Market