
 US Contract Glazing Market | 2026-2036
US Contract Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
US Contract Glazing Market Intelligence
Premium facade engineering is decoupling from commodity window installation across the US contract glazing landscape. Flynn Group of Companies leverages its national footprint to dominate large-scale commercial envelopes, while Enclos Corp. specializes in complex structural glazing systems for signature architecture. W&W Glass LLC anchors its position in the New York metropolitan corridor through deep relationships with institutional developers.
US contract glazing encompasses the design, fabrication, and installation of exterior glass systems for buildings, typically involving aluminum framing, silicone structural bonding, and thermal break assemblies engineered to manage wind loads, thermal transfer, and seismic movement. The application sector splits sharply: commercial buildings command the largest project values, yet institutional projects generate superior margins due to stringent performance specifications and extended warranty requirements. Low-E glass and unitized systems are capturing share from conventional stick-built methods as developers prioritize speed-to-enclosure and energy code compliance.
The Department of Energy enforces escalating performance benchmarks through model energy codes adopted at state level, while the Inflation Reduction Act channels tax incentives toward high-efficiency building envelopes. OSHA maintains fall-protection standards that shape installation labor costs and scheduling across multi-story projects. Stakeholders must track how state-level stretch codes and utility rebate programs redirect specification decisions before federal incentives phase down.
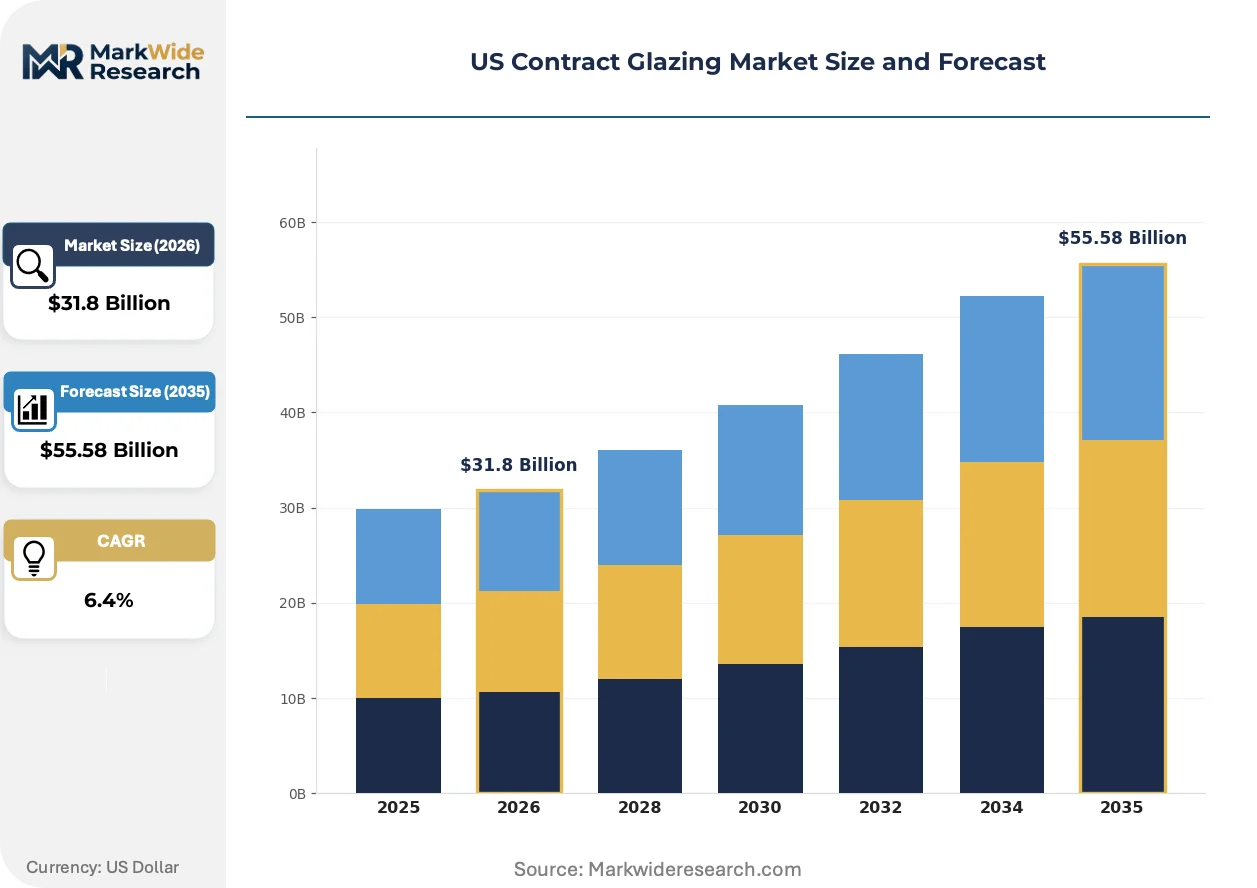
Market Dynamics
The Inflation Reduction Act's energy efficiency tax credits are compressing specification timelines across US commercial construction, forcing glazing contractors to certify thermal performance before federal incentives phase down.
Growth Catalysts
- Inflation Reduction Act envelope incentives:Federal tax deductions for high-performance building skins are accelerating specification of triple-glazed unitized systems in Class A office developments.
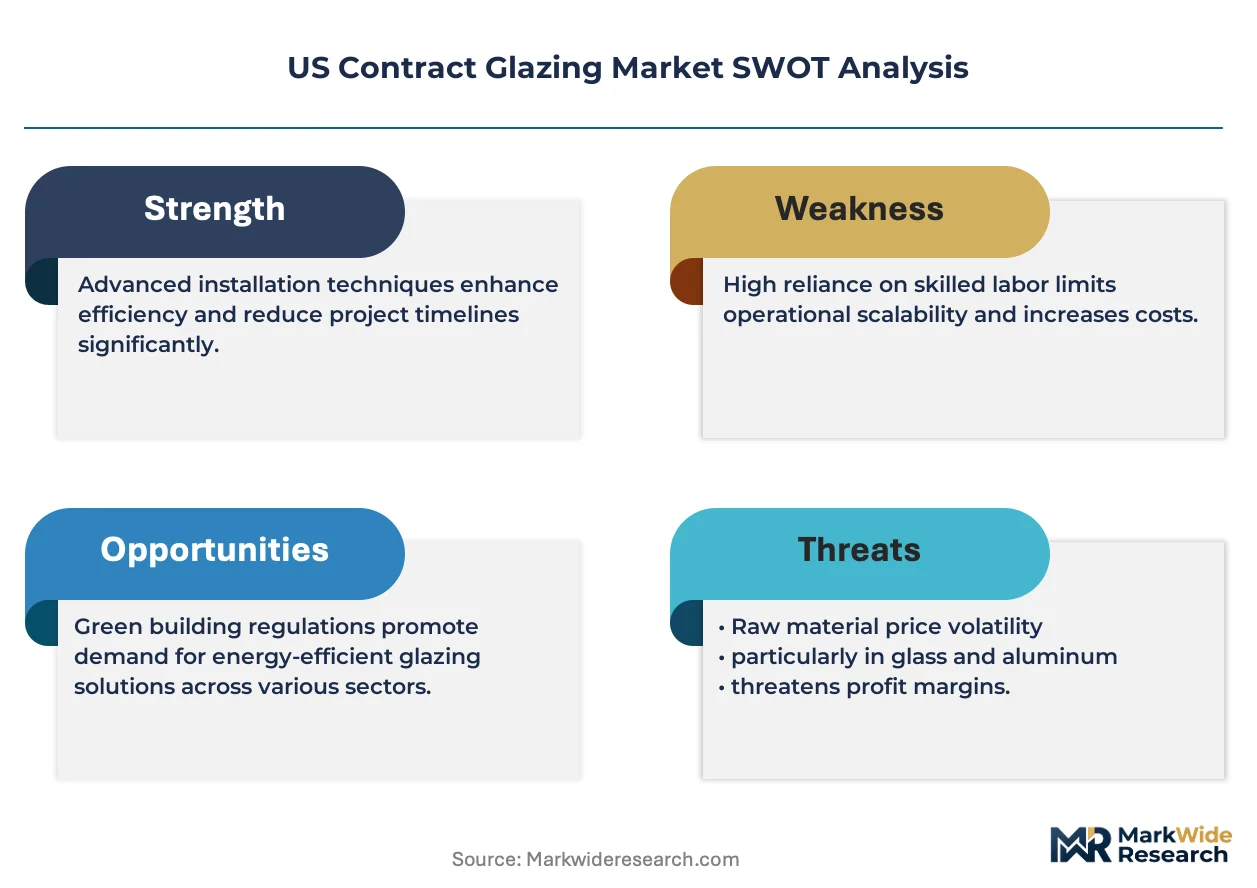
- Seismic zone construction:California's Title 24 energy code updates mandate dynamic glazing or advanced coatings on new high-rise construction, creating pull-through demand for structural silicone bonding systems.
- Urban density clustering:Mixed-use towers in Texas and Florida are specifying oversized glass lites requiring specialized rigging and installation capabilities that command premium project values.
Market Restraints
- Aluminum billet price volatility:Extrusion feedstock costs swing with Midwest spot aluminum markets, compressing fabrication margins on fixed-price commercial contracts.
- Silicone structural adhesive concentration:Three chemical suppliers control North American supply of high-modulus glazing sealants, creating single-source risk for unitized system fabricators.
- Skilled rigger scarcity:OSHA-certified high-rise installation crews command wage premiums that inflate labor cost share on projects above fifteen stories.
Strategic Opportunities
- Stretch code jurisdictions:Massachusetts and Washington state adoption of net-zero-ready building codes creates specification pull for vacuum-insulated glazing before federal baseline shifts.
- Facade retrofit acceleration:Deep energy retrofits of 1970s commercial stock in Chicago and New York are generating demand for overcladding systems that improve envelope performance without full demolition.
- Smart glass convergence:Electrochromic glazing integration with building management systems is opening premium specification tiers in healthcare and laboratory verticals.
Industry Challenges
- NFRC certification timelines:Thermal performance rating procedures for novel glazing assemblies delay product launch by eight to fourteen months, compressing window for incentive capture.
- Prefabrication facility capex:Unitized curtain wall production requires climate-controlled assembly halls and overhead cranes that demand seven-figure capital deployment before contract award.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Contract Glazing Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Tempered Glass, Laminated Glass, Insulated Glass, Low-E Glass Application Sector: Commercial Buildings, Residential Buildings, Institutional Projects, Industrial Facilities Installation Method: Stick System, Unitized System, Structural Glazing, Curtain Wall End User: Architects, Contractors, Developers, Builders |
| Companies Covered | Flynn Group of Companies, W&W Glass LLC, Harmon Inc., Pioneer Cladding & Glazing Systems Inc., Reflection Window + Wall, Enclos Corp., Crown Corr Inc., Giroux Glass Inc., New Hudson Facades, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Contract Glazing Market Strategic Shifts & Innovations
Digital fabrication and connected facade systems are compressing the traditional sequence between design intent and field installation. Specification decisions now flow through energy modeling software before reaching procurement.
Robotic glass handling is automating the cutting, edge deletion, and insulating glass unit assembly that previously required manual labor in fabrication plants. Large commercial glazing contractors in Texas and California are deploying six-axis manipulators for oversized lites. This capital deployment is compressing cycle times from glass delivery to unitized panel completion by roughly one-third.
OSHA's updated fall protection standards for construction above six stories are mandating permanent anchor systems and integrated safety rails on curtain wall frames before installation crews arrive. General contractors in Florida and coastal California are pre-installing these systems during steel erection. The regulation is accelerating demand for factory-integrated safety hardware that arrives pre-attached to unitized panels.
Owner-operators in the institutional and healthcare segments are unbundling facade performance from capital project delivery, signing long-term energy guarantee contracts with glazing specialists. Texas medical center developments and California university systems are piloting twenty-year thermal performance agreements. This shift is visible most acutely in public-private partnership structures where operational energy cost responsibility sits with the concession holder rather than the design-builder.
US Contract Glazing Market Segmentation
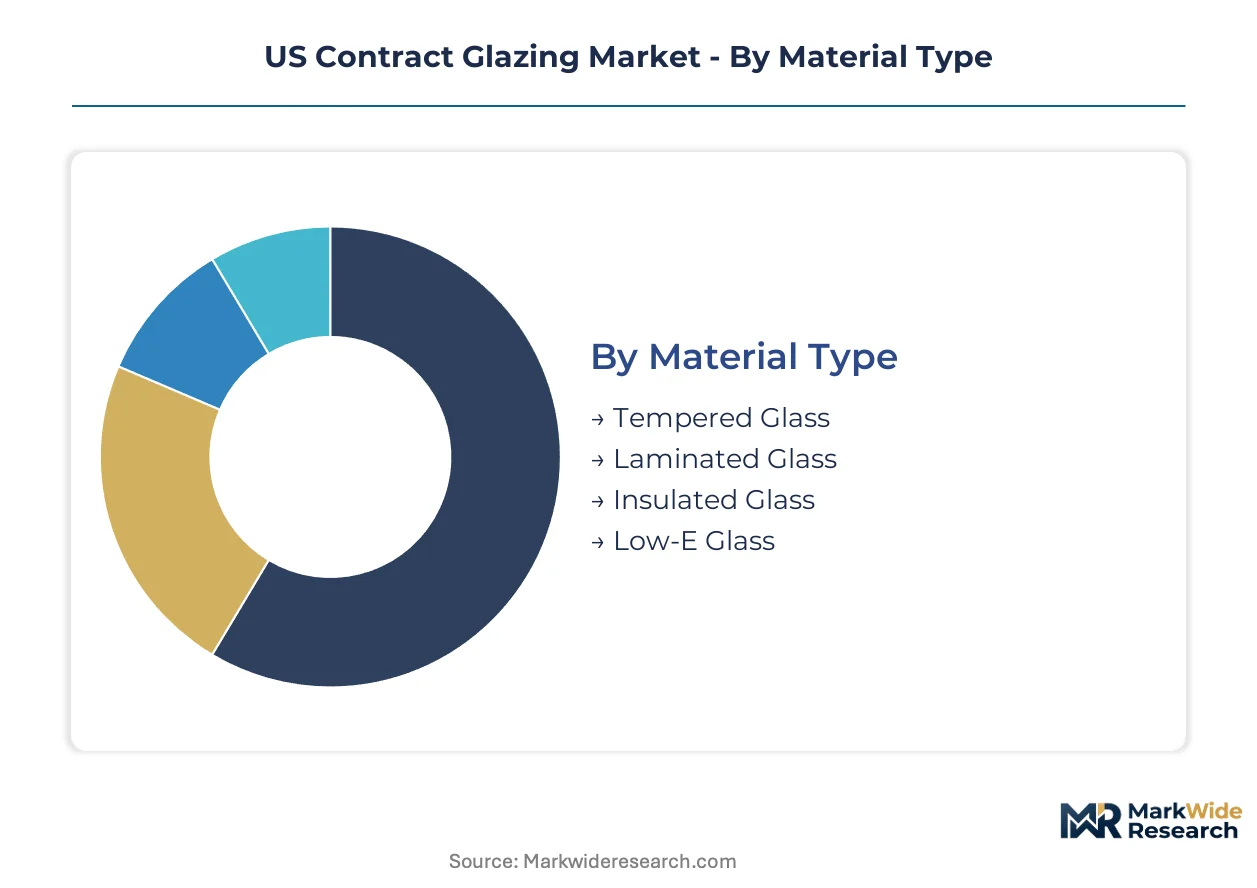
Segmentation in US contract glazing reveals how specification authority flows through distinct professional channels and how fabrication methods determine project economics. Material selection and installation technique together shape thermal performance outcomes that building codes now mandate.
Material Type:
Integration depth varies sharply across glazing materials, with some functioning as standalone safety barriers while others embed within multi-layer thermal assemblies.
- Low-E Glass:Microscopically thin metallic coatings reduce infrared transmission while preserving visible light, enabling Title 24 compliance in California high-rises without sacrificing floor-to-ceiling transparency. Developers in Texas medical towers specify double-silver coatings to manage cooling loads where glazing ratios exceed sixty percent.
- Insulated Glass:Factory-sealed dual or triple lites with argon fill and warm-edge spacers deliver center-of-glass U-factors below 0.25, satisfying Massachusetts stretch code requirements for net-zero-ready construction. Fabricators in Florida concentrate capacity here to serve hurricane-impact ratings alongside thermal performance.
- Tempered Glass:Heat-strengthened lites that fracture into granular pieces satisfy safety glazing mandates for doors and sidelights.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for post-breakage retention and acoustic dampening in urban cores.
Low-E glass leads volumes today; insulated glass is gaining share fastest.
Application Sector:
Cost tier stratification separates trophy assets from commodity construction, with specification budgets varying by an order of magnitude across sectors.
- Commercial Buildings:Class A office towers and mixed-use developments command the largest absolute project values, with curtain wall packages exceeding fifteen million dollars on signature high-rises. Institutional investors in Manhattan and Miami prioritize speed-to-enclosure through unitized systems that compress field installation schedules.
- Institutional Projects:University systems and healthcare networks generate superior margins through extended warranty terms and performance-based specifications that demand NFRC-certified assemblies. California public university bonds now require twenty-year thermal performance guarantees from glazing contractors.
- Residential Buildings:Mid-rise multifamily and luxury condominium projects specify oversized lites for views, with Florida coastal towers driving impact-rated demand.
- Industrial Facilities:Warehouses and distribution centers prioritize daylighting over thermal performance, specifying single-lite systems with minimal framing.
Commercial buildings dominate absolute revenue; institutional projects carry the highest margin profile.
Installation Method:
Supply concentration in factory fabrication versus field assembly determines capital intensity and geographic reach for glazing contractors.
- Unitized System:Factory-assembled panels with integrated framing, glazing, and gaskets arrive ready for crane-lifted installation, compressing high-rise enclosure schedules by forty percent versus stick-built alternatives. Texas and Florida tower developers specify these exclusively above fifteen stories where labor scarcity and wind exposure compound field risks.
- Stick System:Site-assembled framing with infill glass suits mid-rise construction where crane availability is constrained and panel weights exceed lifting capacity.
- Structural Glazing:Silicone-bonded glass without exterior caps creates flush facade aesthetics for signature architecture.
- Curtain Wall:Aluminum-framed systems spanning multiple floors anchor commercial high-rise envelopes.
Unitized systems command the steepest expansion trajectory; stick systems retain share in secondary markets.
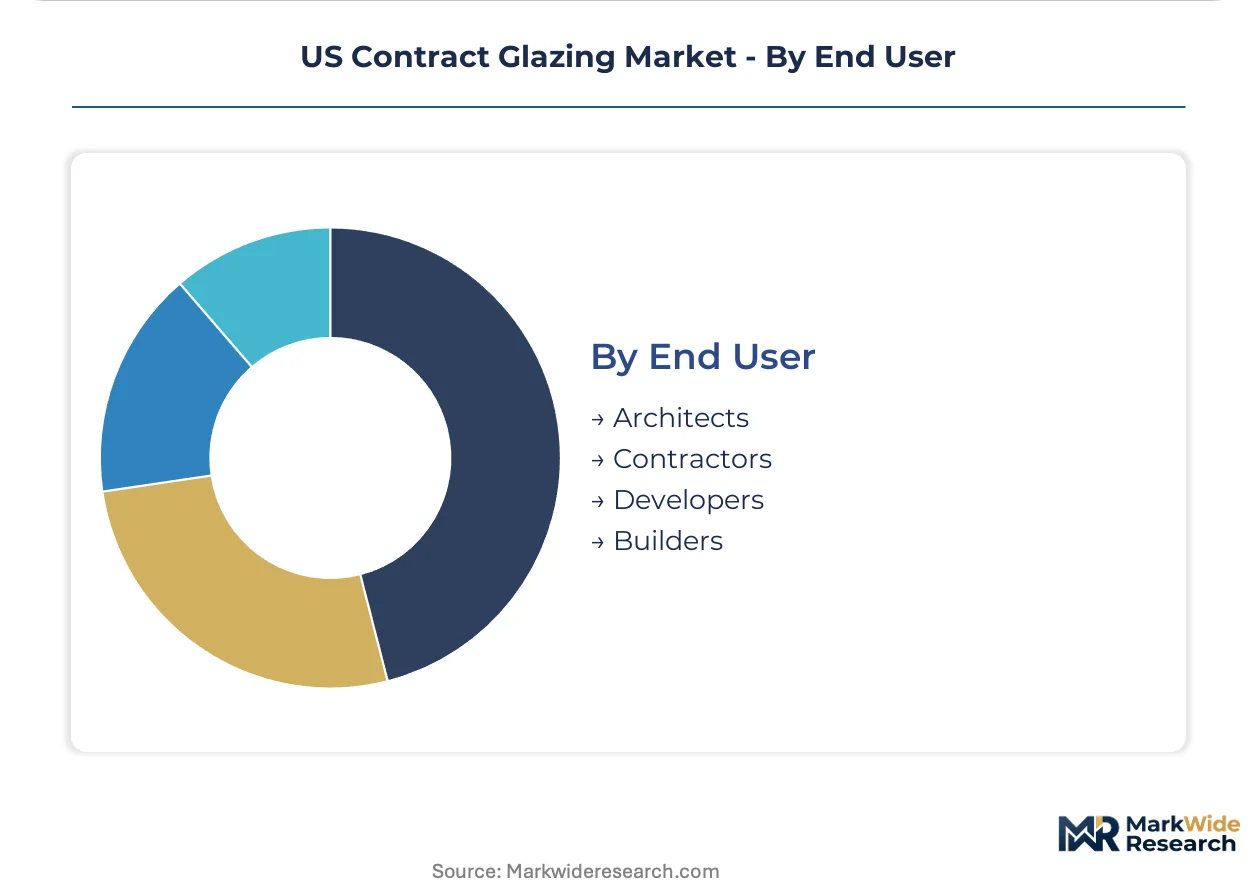
End User:
Procurement authority is fragmenting across professional roles as energy modeling software inserts new decision nodes before contract award.
- Developers:Equity sponsors and owner-operators now unbundle facade performance from capital delivery, signing long-term energy guarantee contracts that shift operational risk to glazing specialists. Texas medical center PPP structures exemplify this shift.
- Architects:Design firms specify thermal performance targets that flow into energy modeling software before procurement teams engage contractors.
- Contractors:General contractors manage envelope packages as critical path items, with Florida and California projects mandating pre-installed fall protection on unitized panels.
- Builders:Production homebuilders and multifamily developers specify standard assemblies through national distribution channels.
Developers lead specification authority today; architects are capturing upstream influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California dominate US contract glazing demand through divergent drivers—Texas via commercial high-rise velocity, California through Title 24 energy code mandates—while Florida and the Northeast corridor carve distinct specification niches.
Texas
Houston and Dallas medical center expansions drive oversized glass lite demand for trophy healthcare assets. Texas cities adopt IECC 2021 baselines without stretch code overlays, preserving specification flexibility for developers. Austin's mixed-use towers concentrate unitized system procurement, with contractors pre-installing OSHA-mandated fall protection during steel erection.
California
Los Angeles and San Francisco high-rises mandate dynamic glazing or advanced coatings under Title 24 updates, pulling structural silicone bonding systems. CalGreen Tier 1 and Tier 2 pathways reward envelope performance beyond code minimums. San Diego's life science clusters specify NFRC-certified assemblies with twenty-year thermal guarantees.
Florida
Miami's coastal towers combine hurricane impact ratings with thermal performance, forcing fabricators to dual-certify products. Florida Building Code Chapter 16 wind load requirements shape aluminum framing engineering. Orlando's hospitality developments concentrate stick system demand where crane access constrains unitized panel weights.
New York Metro
Manhattan Class A office retrofits generate overcladding demand for 1970s commercial stock without full demolition. Local Law 97 carbon caps redirect specification toward high-performance envelopes. Brooklyn and Queens multifamily towers specify laminated glass for acoustic dampening near transit corridors.
Illinois/Michigan/Ohio
Chicago's deep energy retrofit pipeline targets post-war commercial buildings with facade performance upgrades. Illinois stretch code adoption lags coastal states, preserving cost-driven specification. Detroit automotive headquarters and Cleveland healthcare expansions anchor institutional project margins in the region.
US Contract Glazing Market Key Industry Players
Top-tier vendors anchor national-scale commercial envelopes, while regional specialists capture institutional and signature architecture niches. The market structure concentrates around fabrication scale, installation capability, and energy performance certification. Three archetypes dominate: vertically integrated national contractors, structural glazing specialists, and regional envelope fabricators. Competitive moves center on prefabrication facility expansion and long-term energy guarantee contracting.
Among US-based contractors, Flynn Group of Companies, Enclos Corp., and W&W Glass LLC exemplify distinct strategic positions. Flynn represents the national-scale archetype with multi-state commercial envelope coverage. Enclos occupies the complex structural glazing tier for signature architectural projects. W&W Glass anchors the metropolitan corridor specialist model through concentrated institutional relationships in the Northeast.
| Leading Market Players |
|---|
| Flynn Group of Companies |
| W&W Glass LLC |
| Harmon Inc. |
| Pioneer Cladding & Glazing Systems Inc. |
| Reflection Window + Wall |
| Enclos Corp. |
| Crown Corr Inc. |
| Giroux Glass Inc. |
| New Hudson Facades |
| Others |
Cost & Logistics Intelligence
Backward integration into aluminum extrusion and silicone structural adhesive production anchors both supply security and margin control for tier-one glazing contractors serving federal incentive-driven projects. This captive supply model insulates fabricators from Midwest spot aluminum volatility while enabling performance-guarantee pricing that institutional developers now demand.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for unitized curtain wall systems as regional fabricators compete for medical center and mixed-use tower contracts. Project-based pricing stratifies across NFRC-certified premium tiers, standard IECC-compliant assemblies, and economy stick-built alternatives. Cost compression in the standard tier intensifies because aluminum billet volatility erodes fixed-price contract margins. Production homebuilders exhibit highest price sensitivity; institutional developers with energy guarantee contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with high-modulus silicone structural sealants concentrated among three North American chemical suppliers. Primary fabrication draws from domestic aluminum extrusion in Ohio and Tennessee, tempered glass from South Carolina and Pennsylvania, and specialized coatings from Massachusetts and California. Tariff exposure on Chinese aluminum feedstock threatens margin stability. Distribution runs through regional envelope specialists who coordinate crane logistics and field installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the Inflation Reduction Act's phase-down schedule forcing accelerated specification decisions that favor pre-certified contractors.
For Market Incumbents: Lock in fabrication capacity ahead of stretch code adoptions in Massachusetts and Washington state. Secure captive silicone adhesive supply through long-term offtake agreements with chemical suppliers. Vertical integration into robotic glass handling equipment insulates against OSHA-certified rigger wage inflation. For New Entrants and Emerging Players: Electrochromic glazing integration with building management systems offers a technology-first wedge into healthcare and laboratory verticals where premium specification tolerance runs highest. Target facade retrofit acceleration in Chicago and New York overcladding pipelines. Lead with energy modeling software partnerships that insert specification influence upstream of procurement teams. For Investors and Strategic Acquirers: Roll-up economics work for regional envelope fabricators with NFRC certification infrastructure because institutional warranty requirements create moats against commoditization. Five-to-ten-year viability hinges on positioning for net-zero-ready code adoption before federal baseline shifts. Monitor Massachusetts and Washington stretch code enforcement velocity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Facility Expansion | Climate-controlled unitized panel assembly in Texas and Florida compresses field schedules by forty percent. |
| Long-term Energy Guarantee Contracting | Twenty-year thermal performance agreements with California university systems shift operational risk from developers. |
| Robotic Glass Handling Deployment | Six-axis manipulators for oversized lites cut fabrication cycle times by one-third in high-volume plants. |
| NFRC Certification Investment | Pre-certified assemblies capture Inflation Reduction Act incentives before federal phase-down deadlines. |
| Silicone Adhesive Supply Agreement | Long-term offtake with chemical suppliers mitigates single-source concentration risk for unitized fabricators. |
Research Approach
Multiple input streams — primary interviews with glazing contractors and general contractors, secondary validation through NFRC certification databases and OSHA regulatory filings, and trade data from aluminum extrusion and glass manufacturing associations — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included envelope engineering directors, institutional procurement officers, facade consultants, and energy modeling specialists. Secondary sources comprised Department of Energy code adoption tracking, state stretch code registries, and industry association technical bulletins.
Data-stream reconciliation across the projection horizon employed a segmentation framework modeling material type, application sector, installation method, and end-user procurement authority. CAGRs were derived from trend extrapolation of unitized system penetration rates, energy code stringency indices, and federal incentive availability windows. Industry-specific forecast inputs included aluminum billet price volatility assumptions and OSHA-certified installation crew availability projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Inflation Reduction Act extension decisions, state stretch code adoption velocity, and silicone structural adhesive supply concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Sprayed Concrete Market
Building Materials
Building and Construction Sheets Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
China Cement Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Europe Cement Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
India Concrete Admixtures Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Qatar Cement Market
Building Materials
Brick Adhesive Market
Building Materials
Exterior Doors Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Italy Facade Market
Building Materials
GCC Concealed Cistern Market