
 Qatar Cement Market | 2026-2036
Qatar Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Cement Market Analytics
Mega-project contractors is unwinding the historical buyer mix that favored fragmented individual consumers and small builders. Qatar National Cement Company leverages backward integration into clinker production to secure feedstock certainty across its Mesaieed complex. LafargeHolcim anchors its position through specialized marine logistics serving offshore platform and port expansion projects. Al Khalij Cement Company differentiates via white cement output targeting Qatar's premium facade and interior finish segments.
Cement comprises finely ground hydraulic binders produced by calcining limestone, clay, and corrective materials at approximately 1450°C to form clinker, then intergrinding with gypsum to control setting time. The resulting powder hardens through hydration when mixed with water, forming the structural matrix for concrete in buildings, roads, and foundations. Ordinary Portland Cement dominates volume throughput across Qatar's batching plants serving infrastructure development, while Blended Cement gains specification share as engineers prioritize lower embodied carbon in Lusail Stadium district and Education City extensions. Waterproof Cement commands premium positioning in coastal and subterranean applications where groundwater intrusion risks escalate lifecycle costs.
The Ministry of Municipality and Environment administers construction material approvals aligned with Gulf Standardization Organization protocols, while Qatar General Organization for Standardization enforces product conformity marking for structural safety certification. These frameworks elevate quality thresholds for imported cement and incentivize domestic producers to maintain ISO-certified laboratory testing regimes. Stakeholders must track evolving carbon intensity benchmarks as Qatar Energy's power sector decarbonization commitments cascade into clinker kiln fuel substitution requirements.
Market Dynamics
Mega-project contractors now dominate Qatar's cement procurement, consolidating demand that previously fragmented across individual builders and small-scale developers. This structural concentration is reshaping pricing power, specification standards, and logistics requirements across the supply base.
Growth Catalysts
- Lusail City infrastructure buildout:The new city district generates sustained bulk demand for sulfate-resistant formulations across residential towers, commercial complexes, and utility tunnels.
- Gulf Standardization Organization coastal specifications:Mandatory sulfate-resistant cement for marine and subterranean applications creates premium product differentiation and technical barriers to import competition.
- Doha Metro corridor extensions:Underground rail infrastructure requires specialized low-heat and waterproof cement grades, expanding addressable market for technical formulations.
Market Restraints
- Clinker import dependency:Domestic limestone reserves constrain captive clinker output, exposing margins to international feedstock price volatility and currency fluctuation.
- Single-buyer concentration risk:Mega-project contractors now account for dominant procurement volumes, compressing supplier pricing leverage and extending payment cycles.
- Limited domestic waste fuel infrastructure:Qatar Energy's power sector decarbonization timeline outpaces cement kiln fuel substitution capabilities, locking in conventional fuel exposure.
Strategic Opportunities
- White cement premium segment:Qatar's facade and interior finish markets remain undersupplied for architectural-grade white cement, creating margin expansion potential.
- Carbon capture integration:Qatar Energy's CCUS infrastructure investments position domestic cement producers for early-mover low-carbon product certification.
- Marine logistics specialization:Offshore platform and port expansion projects require bulk marine delivery capabilities that few regional competitors possess.
Industry Challenges
- Kiln technician scarcity:Specialized pyroprocess engineering expertise for clinker production remains concentrated among a limited pool of expatriate professionals.
- ISO laboratory certification timelines:Gulf Standardization Organization conformity marking requires extended validation periods that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Cement Market |
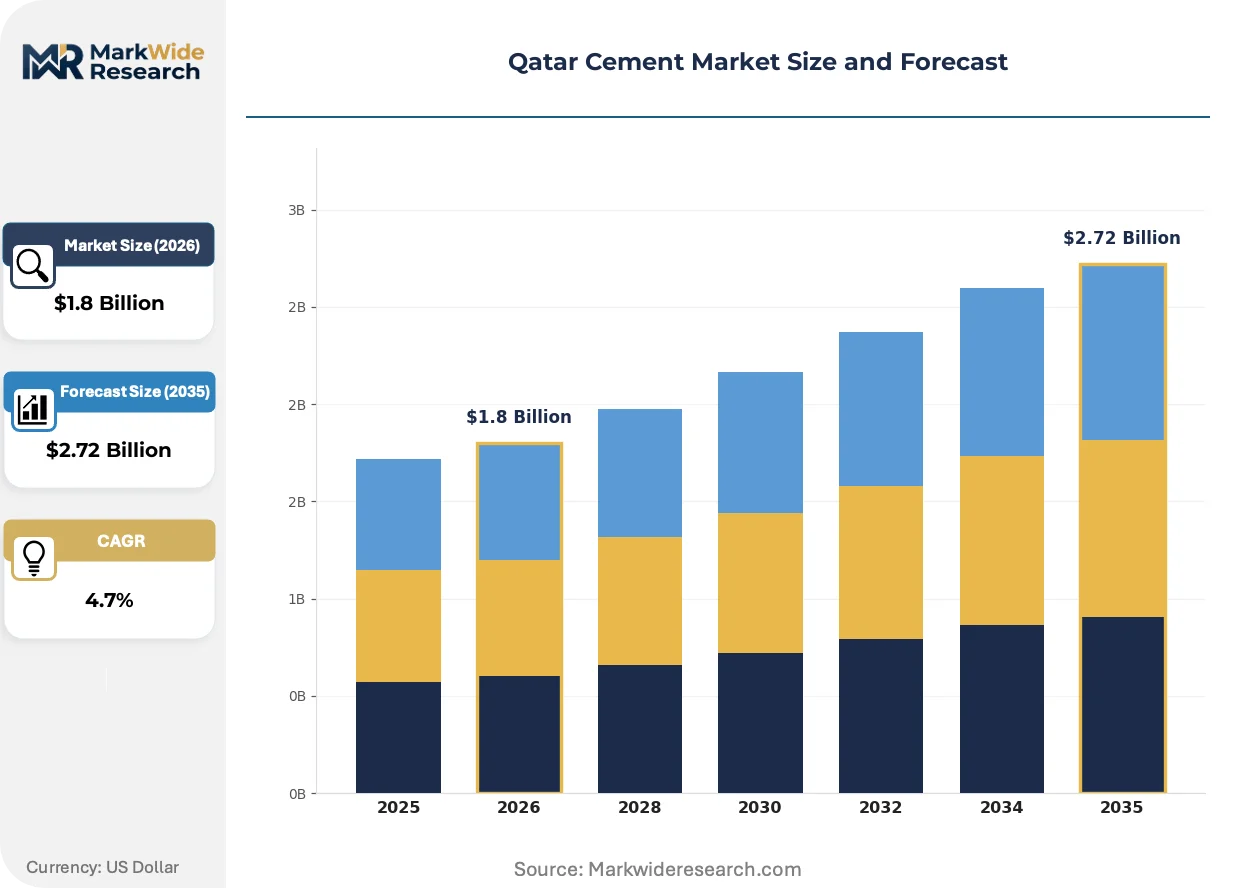
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, White Cement, Waterproof Cement Application: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Facilities Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms End User: Contractors, Builders, Government Projects, Individual Consumers |
| Companies Covered | Saudi Cement, LafargeHolcim, Qatar National Cement Company, Gulf Cement Company, Dubai Cement, Al Khalij Cement Company, Cemex, Kuwait Cement Company, Al-Jabor Cement Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Cement Market Evolving Landscape
Qatar's cement sector is pivoting toward technical differentiation as bulk commodity margins compress under contractor consolidation. Producers are racing to embed carbon efficiency and specialized performance into product architectures.
Blended cement formulations incorporating supplementary cementitious materials are bifurcating the market into conventional Ordinary Portland Cement and lower-carbon alternatives. Engineers at Lusail Stadium district and Education City extensions specify blended grades for embodied carbon reduction. This split is forcing domestic producers to dual-track clinker ratios and maintain parallel inventory lines.
Qatar General Organization for Standardization is tightening product conformity marking enforcement for structural safety certification. Imported cement faces elevated documentation burdens and extended approval timelines. Domestic producers with pre-certified ISO laboratory regimes capture preferential positioning in public tender processes.
Long-term offtake agreements are displacing spot-market transactions as mega-project contractors lock in volume security. Individual builders and small developers now face allocation rationing from distributors prioritizing bulk accounts. This channel compression concentrates in Doha Metro corridor extensions where contractor consortiums coordinate consolidated procurement.
Qatar Cement Market Segmentation
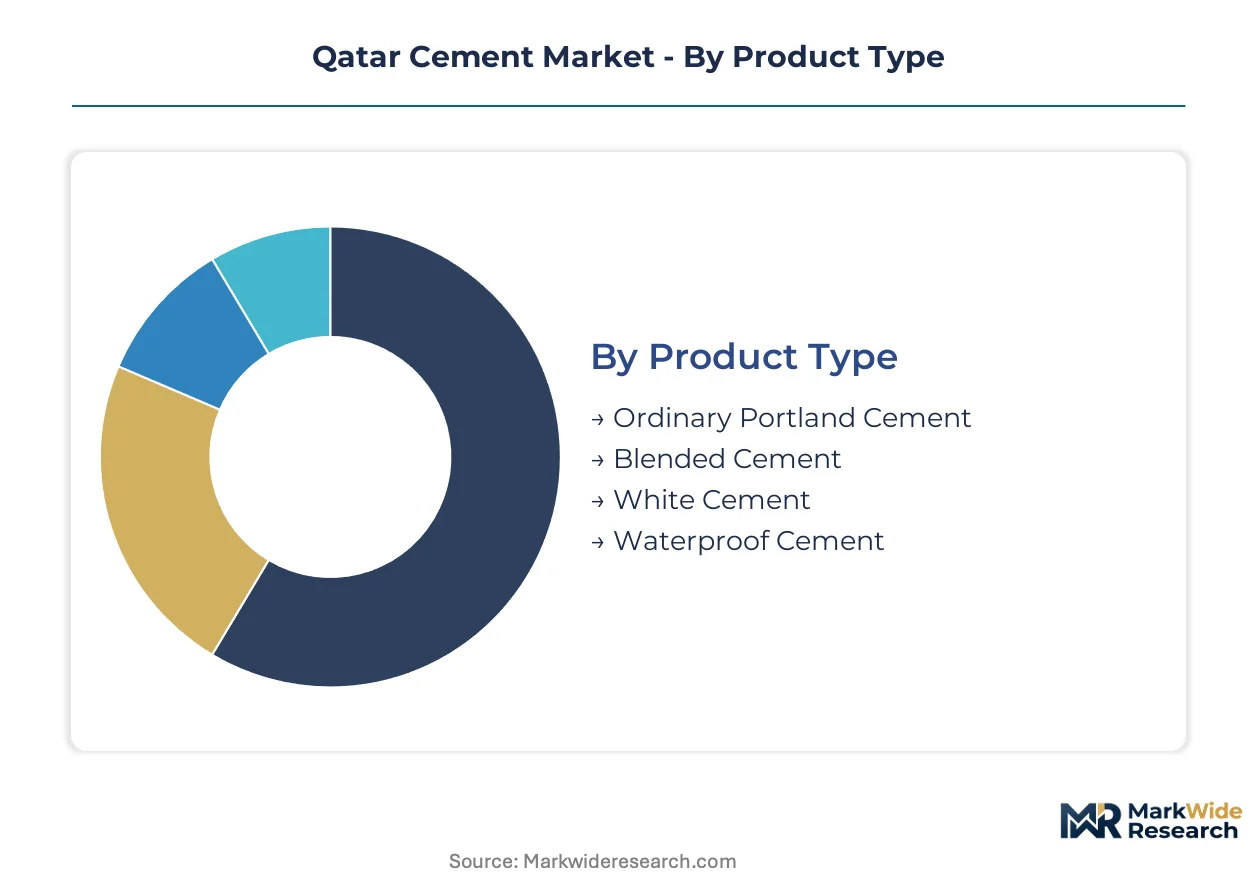
Cement segmentation in Qatar tracks the divergence between bulk commodity flows to mega-projects and specialized formulations for technical applications. Each dimension reveals how procurement consolidation and regulatory specification are restructuring commercial access.
Product Type:
Domestic production concentrates on standardized grades for infrastructure, while import dependency persists for niche architectural formulations. Export orientation remains minimal given captive demand from national development projects.
- Ordinary Portland Cement:Comprising calcium silicates and aluminates from clinker calcination, this grade delivers compressive strength of 42.5-52.5 MPa standard. Demand concentrates at Lusail City batching plants where contractor consortiums specify bulk volumes for structural concrete. The Ministry of Municipality and Environment mandates Gulf Standardization Organization compliance for all public tenders, locking in quality thresholds.
- Blended Cement:Interground with fly ash, slag, or limestone to reduce clinker factor, this formulation addresses embodied carbon targets at Lusail Stadium district and Education City extensions. Engineers specify these grades for LEED-equivalent certification requirements.
- White Cement:Low-iron clinker yields architectural brightness for Qatar's premium facade market.
- Waterproof Cement:Hydrophobic additives serve coastal and subterranean applications under groundwater pressure.
Ordinary Portland Cement commands the established base. The steepest expansion runs through Blended Cement.
Application:
Volume distribution follows the capital allocation sequencing of Qatar's national development blueprint, with infrastructure absorbing disproportionate share ahead of residential and commercial completions.
- Infrastructure Development:Doha Metro corridor extensions, port expansions, and utility tunnels drive specification of low-heat and sulfate-resistant formulations. Qatar General Organization for Standardization enforces Gulf Standardization Organization protocols for structural safety certification in all public works.
- Residential Construction:Lusail City towers and Pearl-Qatar developments specify standardized grades for structural frames and finishing works. Mega-project contractors consolidate procurement previously fragmented across individual developers.
- Commercial Construction:Office complexes and retail centers in West Bay and Msheireb Downtown Doha drive mid-tier volume demand.
- Industrial Facilities:Mesaieed industrial zone and Ras Laffan energy complexes require specialized refractory and oil-well cement grades.
Infrastructure Development absorbs the dominant procurement volumes. Residential Construction is gaining share fastest as Lusail City buildout accelerates toward completion milestones.
Distribution Channel:
Channel structure reflects the displacement of spot-market transactions by long-term offtake agreements, with direct contracting now dominant for volume accounts.
- Direct Sales:Mega-project contractors negotiate annual supply agreements with Qatar National Cement Company and Al Khalij Cement, bypassing intermediary margins. These arrangements specify delivery scheduling, quality testing protocols, and price adjustment mechanisms tied to clinker import costs.
- Distributors:Independent builders and smaller developers access cement through regional distributors serving Doha, Al Rayyan, and Al Wakrah. Allocation rationing intensifies as suppliers prioritize bulk accounts.
- Retailers:Hardware chains and construction material yards serve renovation and repair demand.
- Online Platforms:Emerging digital procurement channels target small contractors with transparent pricing and logistics coordination.
Direct Sales channels command the volume base. Distributor networks are expanding most quickly as secondary market participants seek supply security.
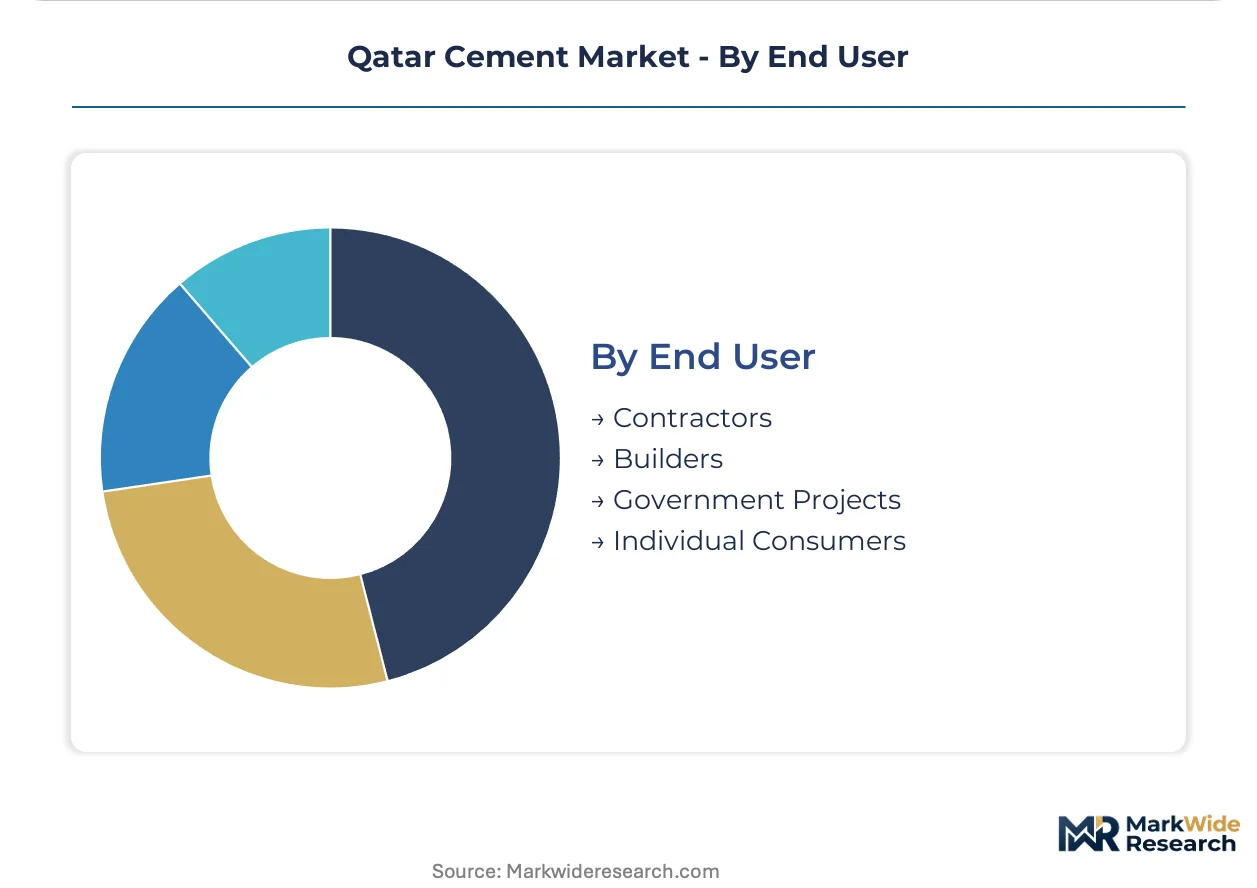
End User:
Buyer composition has inverted from fragmented individual consumers toward consolidated contractor procurement, restructuring pricing power and specification influence across the supply base.
- Contractors:Consolidated procurement by mega-project joint ventures now dominates Qatar's cement offtake. These entities specify technical grades, negotiate volume discounts, and coordinate logistics for Lusail City and Doha Metro sites. Payment cycle extension pressures supplier working capital.
- Government Projects:Qatar's Public Works Authority and Ashghal specify sulfate-resistant and waterproof grades for coastal infrastructure, enforcing Gulf Standardization Organization compliance through tender documentation.
- Builders:Mid-tier development firms face allocation constraints as distributors prioritize contractor volumes.
- Individual Consumers:Residential renovation and small-scale construction now encounter rationing and price premiums.
Contractor procurement commands the established demand base. Government Projects are climbing the fastest as sovereign development commitments accelerate execution timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamad Port expansion underwrites Qatar's cement distribution architecture, connecting Mesaieed production complexes to offshore platform and marine infrastructure projects. This maritime gateway channels sulfate-resistant and waterproof formulations toward coastal development zones.
Doha Metropolitan Area
Doha Metro corridor extensions and Msheireb Downtown Doha redevelopment absorb specialized low-heat cement grades. Qatar General Organization for Standardization enforces Gulf Standardization Organization protocols through tender documentation for all public works. West Bay commercial towers and Lusail Stadium district batching plants concentrate procurement volumes for blended cement specifications.
Lusail City
The new city district generates sustained bulk demand across residential towers, commercial complexes, and utility tunnels requiring sulfate-resistant formulations. Ministry of Municipality and Environment mandates govern all structural concrete approvals in this zone. Contractor consortiums coordinate consolidated procurement through direct supply agreements with domestic producers.
Al Rayyan and Al Wakrah
Secondary urban centers face allocation rationing as distributors prioritize mega-project contractor volumes. Independent builders access cement through regional distribution networks serving renovation and small-scale construction demand. Qatar National Cement Company's Mesaieed complex anchors supply logistics for these catchment areas.
Mesaieed Industrial Zone
Energy and industrial facilities require specialized refractory and oil-well cement grades distinct from construction formulations. Qatar Energy's power sector infrastructure shapes fuel substitution timelines for clinker kiln operations. Captive demand from Ras Laffan energy complexes limits export orientation for domestic producers.
Pearl-Qatar and Coastal Developments
Marine and subterranean applications under groundwater pressure command premium waterproof cement positioning. LafargeHolcim's specialized marine logistics serve offshore platform and port expansion projects in this corridor. Gulf Standardization Organization coastal specifications create technical barriers protecting domestic supply positions.
Qatar Cement Market Competitive Landscape
Concentration sits with state-affiliated producers and multinational cement groups operating integrated clinker-to-cement complexes. Qatar National Cement Company leverages backward integration into clinker production to secure feedstock certainty. LafargeHolcim anchors multinational presence through marine logistics specialization. Al Khalij Cement Company differentiates via white cement output. Capacity expansion and long-term offtake agreements constitute the dominant competitive moves as mega-project contractors consolidate procurement channels.
Among Qatar-based integrated producers, Qatar National Cement Company and Al Khalij Cement Company exemplify the state-affiliated archetype with captive clinker production and domestic distribution infrastructure. LafargeHolcim represents the multinational specialist tier, occupying a position defined by marine logistics capabilities and regional technical expertise. Gulf Cement Company and Al-Jabor Cement Industries Company sit within the diversified domestic producer category, serving infrastructure and industrial segments through standardized grade portfolios.
| Leading Market Players |
|---|
| Saudi Cement |
| LafargeHolcim |
| Qatar National Cement Company |
| Gulf Cement Company |
| Dubai Cement |
| Al Khalij Cement Company |
| Cemex |
| Kuwait Cement Company |
| Al-Jabor Cement Industries Company |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Qatar National Cement Company's Mesaieed complex shapes both supply concentration and price floors across the domestic market. Mega-project contractors leverage bulk procurement volumes to compress margins while smaller buyers face allocation rationing and premium pricing tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Qatar's cement market. Premium tiers capture sulfate-resistant and waterproof formulations specified for coastal infrastructure under Gulf Standardization Organization mandates, while standard grades serve Lusail City structural concrete and economy tiers address spot-market retail demand. Cost compression in standard grades is intensifying because mega-project contractors consolidate procurement and extend payment cycles. Individual builders exhibit highest price sensitivity as distributors prioritize bulk accounts, whereas government projects demonstrate lowest sensitivity due to specification-locked tender processes.
Supply Chain Analysis
Qatar and the United Arab Emirates anchor clinker grinding and cement blending capacity across the lower Gulf. Domestic production draws from imported clinker feedstock, gypsum for setting-time control, and supplementary cementitious materials including fly ash and slag. Single-source vulnerability concentrates in clinker import channels exposed to currency fluctuation and maritime logistics disruption. Distribution runs through direct sales agreements with mega-project contractors, bypassing intermediary networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's cement market is entering a cyclical recovery phase driven by Lusail City completion milestones and Doha Metro corridor extensions. Infrastructure capital allocation sequencing favors producers with certified laboratory regimes and long-term offtake agreements.
For Market Incumbents: Fortify backward integration into clinker production to secure feedstock certainty against import price volatility. Expand ISO-certified laboratory testing capacity to accelerate Gulf Standardization Organization conformity marking timelines and capture preferential positioning in public tenders. Counter single-buyer concentration risk by diversifying into white cement and waterproof formulations where technical differentiation sustains margin protection.
For New Entrants and Emerging Players: Gulf Standardization Organization fast-track certification pathways offer entry acceleration for specialized technical grades. Target the white cement premium segment serving Qatar's architectural facade market, currently undersupplied relative to premium residential and commercial development demand. Pursue marine logistics partnerships to serve offshore platform and port expansion projects where bulk delivery capabilities create technical barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with captive clinker capacity and carbon capture integration potential. Long-term viability over the coming decade hinges on fuel substitution capabilities aligned with Qatar Energy's power sector decarbonization trajectory. Watch clinker import cost spreads as the inflection indicator for margin compression versus expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Production | Qatar National Cement Company secures feedstock certainty against international price volatility. |
| ISO Laboratory Certification Investment | Accelerated Gulf Standardization Organization approval timelines unlock preferential public tender access. |
| White Cement Capacity Expansion | Al Khalij Cement Company addresses undersupply in Qatar's premium architectural facade segment. |
| Marine Logistics Specialization | LafargeHolcim captures offshore platform and port expansion demand through bulk delivery capabilities. |
| Carbon Capture Integration | Early-mover positioning aligns with Qatar Energy's CCUS infrastructure investments for low-carbon certification. |
Research Methodology
Desk research of trade flow databases, customs records, and Gulf Standardization Organization technical specifications preceded structured interviews with plant managers at integrated cement producers, procurement leads at mega-project contractors, and distribution channel partners serving secondary urban centers. Primary fieldwork with Qatar General Organization for Standardization officials and Ministry of Municipality and Environment technical reviewers validated regulatory compliance frameworks. Secondary sources included Qatar Energy power sector disclosures, construction project development databases, and ISO certification registries. Bottom-up volume modeling triangulated against top-down infrastructure capital allocation projections.
Variance decomposition across product type, application, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating clinker import cost trajectories, contractor procurement consolidation rates, and regulatory specification tightening schedules. Industry-specific forecast inputs captured Gulf Standardization Organization coastal specification adoption curves and Qatar Energy fuel substitution timeline commitments.
Decision-makers should treat outputs as directional under sustained infrastructure capital commitment and clinker import channel stability assumptions; material deviation would warrant model refresh. Recalibration cycles align with material shifts in mega-project contractor procurement patterns and Gulf Standardization Organization specification amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Concrete Admixtures Market
Building Materials
Solar Control Window Film Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Cement Market
Building Materials
Refractory Cement Market
Building Materials
Dry Mix Mortar Market
Building Materials
Italy Cement Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Drywall Joint Tape Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Concrete Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Steel Sleepers Market
Building Materials
Cellular Concrete Market