
 Europe Cement Market | 2026-2036
Europe Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cement Market Intelligence
Market Context
Multi-source procurement for alternative fuels and clinker substitutes is restructuring supply relationships across European cement markets. Heidelberg Materials leverages vertical integration into waste-derived fuels to secure thermal substitution rates above regional averages. Buzzi Unicem anchors its competitiveness through dense limestone quarry control in Italy and Germany. CRH navigates fragmented regulatory landscapes by operating distinct national subsidiaries with localized compliance capabilities.
Technical and Segment Dynamics
Cement is a hydraulic binder produced by grinding Portland cement clinker with gypsum and supplementary cementitious materials, typically achieving compressive strengths of 32.5–52.5 MPa under EN 197-1 classification standards. Portland cement dominates volume but faces margin compression from carbon costs, while blended cement with slag and fly ash captures growth as ETS compliance intensifies. Infrastructure applications lead absolute consumption, though precast concrete manufacturing offers superior margin pools through specification-grade pricing and just-in-time delivery requirements.
Regulatory Outlook
The EU Emissions Trading System and the EU Green Deal's carbon border adjustment mechanism are tightening cost structures for imports and domestic production alike. REACH compliance for chromium VI limits and the F-Gas Regulation on fluorinated compounds in foaming agents shape product formulation and market access protocols. Stakeholders must monitor the interaction between national building codes and EU-level decarbonization timelines to anticipate specification shifts in public procurement.
Market Dynamics
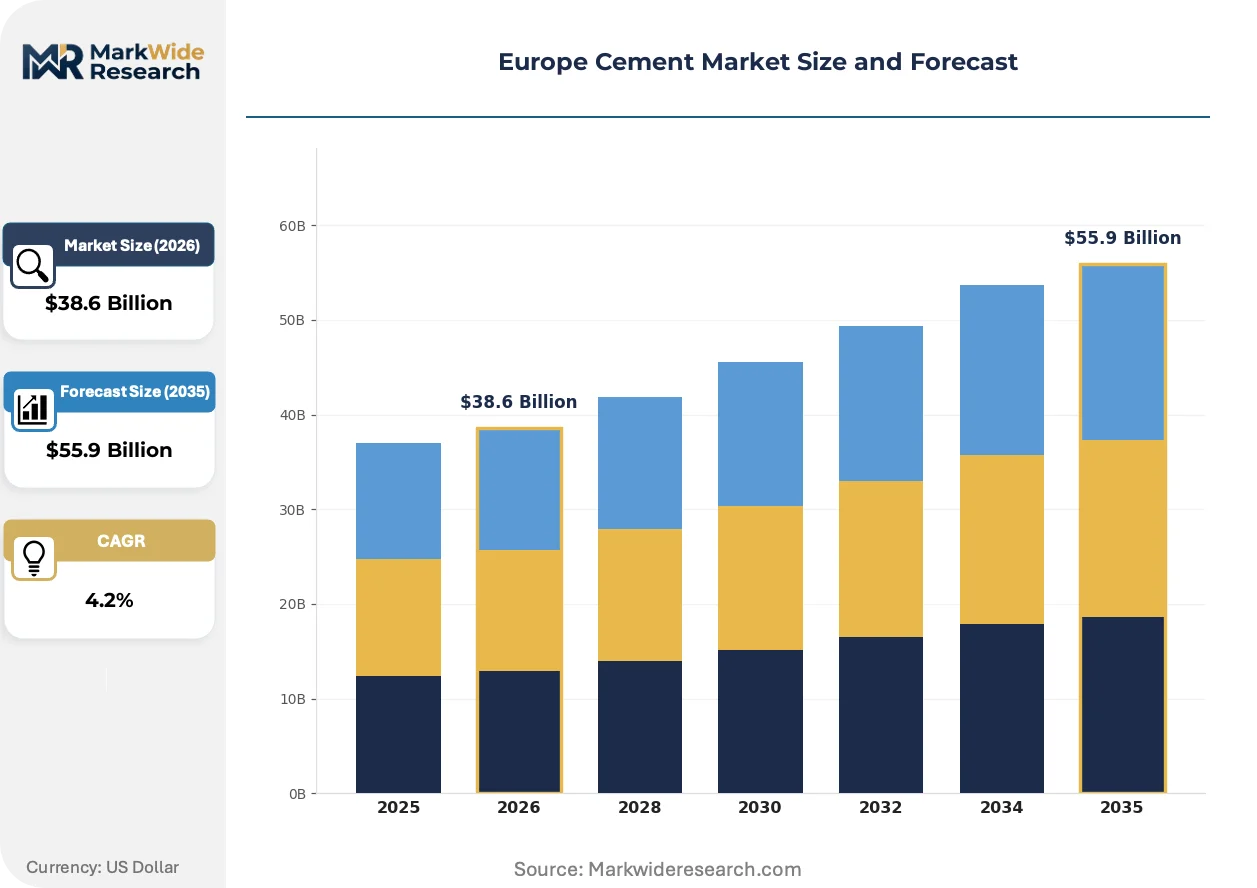
The EU Emissions Trading System is compressing margins for clinker-intensive production while simultaneously creating arbitrage opportunities for low-carbon cement substitutes. This regulatory pressure is restructuring capital allocation across the European cement value chain.
Growth Catalysts
- EU Cohesion Fund disbursements:Poland, Romania, and the Czech Republic are channeling infrastructure grants into transport corridors and energy retrofits, directly lifting bulk cement offtake.
- Clinker substitution mandates:The EU Green Deal's binding reduction targets for embodied carbon are accelerating specification-grade demand for slag and calcined clay blends.
- Carbon capture pilot deployment:Post-combustion amine scrubbing and oxyfuel kiln retrofits are attracting project finance for decarbonized clinker production.
Market Restraints
- Natural gas price volatility:Thermal substitution rates for alternative fuels remain capped by waste-derived fuel availability and quality consistency.
- Limestone quarry depletion:Southern Spain and parts of Italy face reserve exhaustion that elevates haulage costs for high-grade carbonate feedstock.
- Import competition from Turkey:Non-ETS exposed producers in the Eastern Mediterranean are landing cement at ports in Greece and Bulgaria below domestic production cost.
Strategic Opportunities
- Baltic States infrastructure gap:Estonia, Latvia, and Lithuania maintain per-capita cement consumption below half the EU average, with EU structural funds financing catch-up construction.
- 3D-printed concrete specification:Additive manufacturing for architectural elements is creating demand for ultra-fine, low-alkali cement formulations.
- Carbon border adjustment arbitrage:The CBAM phase-in creates first-mover advantage for domestic producers with verified low-emission product certification.
Industry Challenges
- Kiln process engineering talent:The retirement wave of pyroprocessing specialists is outpacing apprenticeship pipeline development.
- Legacy plant retrofit complexity:Pre-1990s vertical shaft kilns and wet-process lines require complete rebuilds to meet BAT conclusions under the Industrial Emissions Directive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cement Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, Blended Cement, Rapid Hardening Cement, White Cement End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Projects Distribution Channel: Direct Sales, Online Sales, Wholesale, Retail Application: Concrete Production, Mortar Production, Road Construction, Precast Concrete |
| Companies Covered | CEMEX, Titan Cement Group, Heidelberg Materials, EURO CEMENT, Vicat Group, Holcim, Buzzi Unicem, Duna-Drava Cement, CRH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cement Market Strategic Shifts & Innovations
Digital kiln control systems and alternative binder chemistry are converging to reduce the sector's clinker factor. These innovations are reshaping both production economics and product specification standards.
Artificial intelligence-driven predictive maintenance is automating temperature profile optimization in rotary kilns. Major integrated producers are deploying machine learning models across their Spanish and German plants to cut thermal energy consumption. This automation is compressing the performance gap between legacy assets and greenfield installations.
The EU Green Deal's carbon border adjustment mechanism is tightening compliance documentation requirements for imported clinker and cement. Domestic producers must secure verified emissions data through accredited third-party auditors. Blended cement categories with high supplementary cementitious material content are capturing specification preference in public procurement tenders.
Engineering firms are consolidating annual supply contracts with single-source cement suppliers to secure price certainty and priority allocation. This concentration is displacing spot-market purchasing for infrastructure megaprojects. The shift is most pronounced in Poland and Romania where EU-funded contracts dominate construction volume.
Europe Cement Market Segmentation
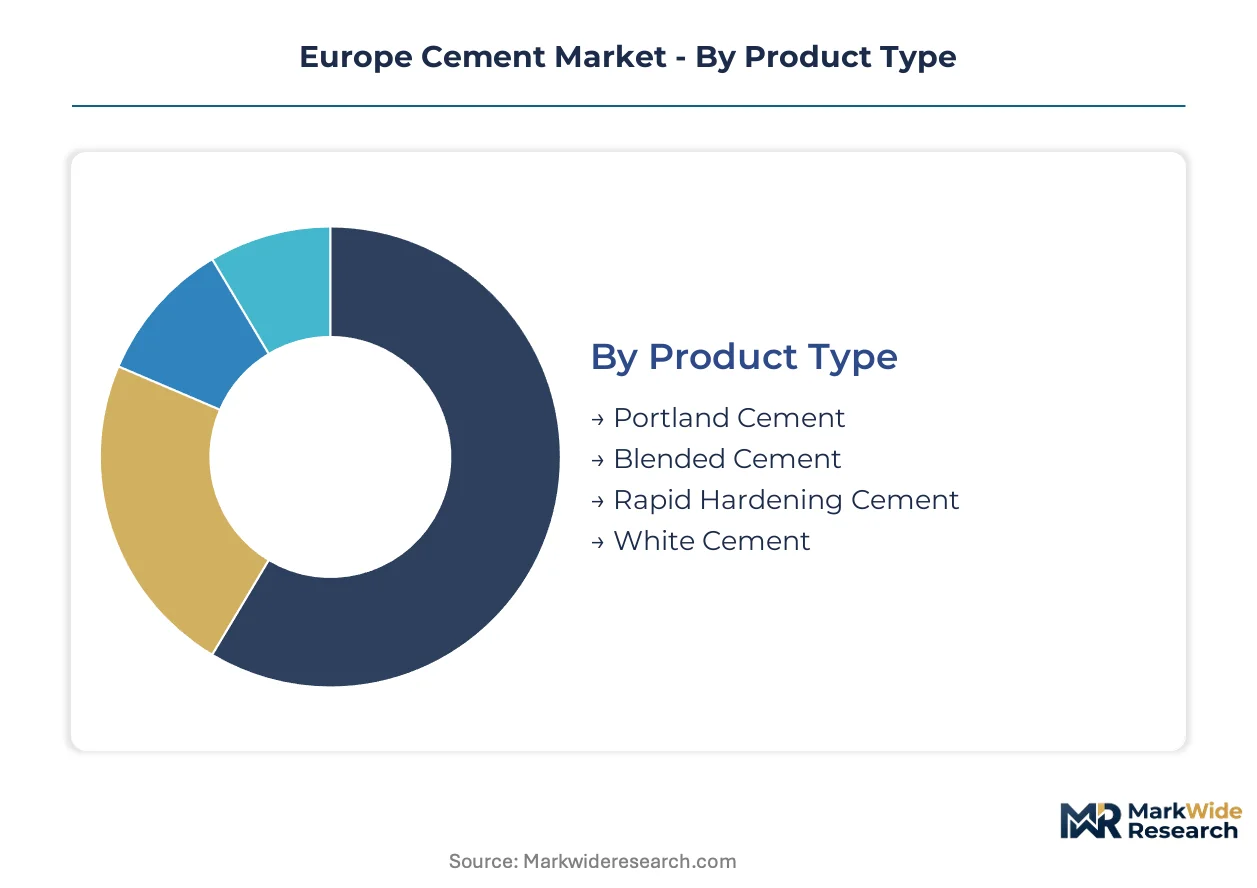
Cement specification diversity across Europe reflects divergent carbon compliance pathways and end-use performance requirements. Product formulation choices directly determine ETS exposure and procurement eligibility in public infrastructure tenders.
Product Type:
Supply concentration in clinker-intensive formulations is compressing margins under carbon pricing, while low-carbon alternatives capture specification premiums.
- Portland Cement:Standardized EN 197-1 CEM I formulations achieve 32.5–52.5 MPa compressive strength through high clinker content. Polish and Romanian infrastructure contractors specify this grade for structural concrete in EU-funded transport corridors, though ETS costs now exceed 15% of production expenditure.
- Blended Cement:CEM II–IV categories incorporate slag, fly ash, or calcined clay to reduce clinker factors below 65%. German and French precast manufacturers are shifting procurement toward these grades to meet embodied carbon limits in public tenders.
- Rapid Hardening Cement:CEM I 52.5 R and specialty formulations enable early formwork stripping in cold-climate construction. Nordic contractors specify this for compressed schedule requirements.
- White Cement:Low-iron clinker production delivers aesthetic finishes for architectural concrete and terrazzo. Italian and Spanish decorative applications sustain niche demand.
Portland cement absorbs the bulk of installed capacity; blended cement is expanding most quickly.
End User:
Customer type determines volume scale, delivery cadence, and specification stringency across national markets.
- Infrastructure:State-owned transport authorities and energy utilities command annual offtake exceeding 500,000 tonnes per project. Poland's General Directorate for National Roads and Motorways consolidates demand through framework agreements that prioritize low-carbon cement certification.
- Residential Construction:Fragmented single-family and multi-family developers purchase through merchant distributors. Czech and Hungarian housing starts are concentrating demand in regional batching plants.
- Commercial Construction:Office and retail developers specify ready-mix concrete through engineering-procurement-construction contractors. German commercial building energy retrofits are lifting blended cement consumption.
- Industrial Projects:Manufacturing facility foundations and process equipment bases require sulfate-resistant formulations. Romanian automotive plant expansions are driving specialty cement procurement.
Infrastructure commands the dominant volume share; residential construction shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects shipment scale, urgency, and buyer sophistication in fragmented national markets.
- Direct Sales:Integrated producers contract directly with infrastructure megaprojects and ready-mix chains. Heidelberg Materials and Buzzi Unicem operate dedicated account teams for Polish and Romanian public works.
- Wholesale:Regional distributors stock bulk and bagged product for construction merchants. This channel dominates Spanish and Italian residential supply.
- Retail:Builder merchants and DIY outlets serve renovation and small-contractor demand. Urban periphery locations capture bagged cement volume.
- Online Sales:Digital platforms facilitate price comparison and scheduled delivery for mid-size contractors. Uptake remains limited by logistics complexity.
Direct sales channelize the majority of tonnage; wholesale maintains deepest geographic penetration.
Application:
End-use performance requirements dictate cement chemistry, fineness, and supplementary material content.
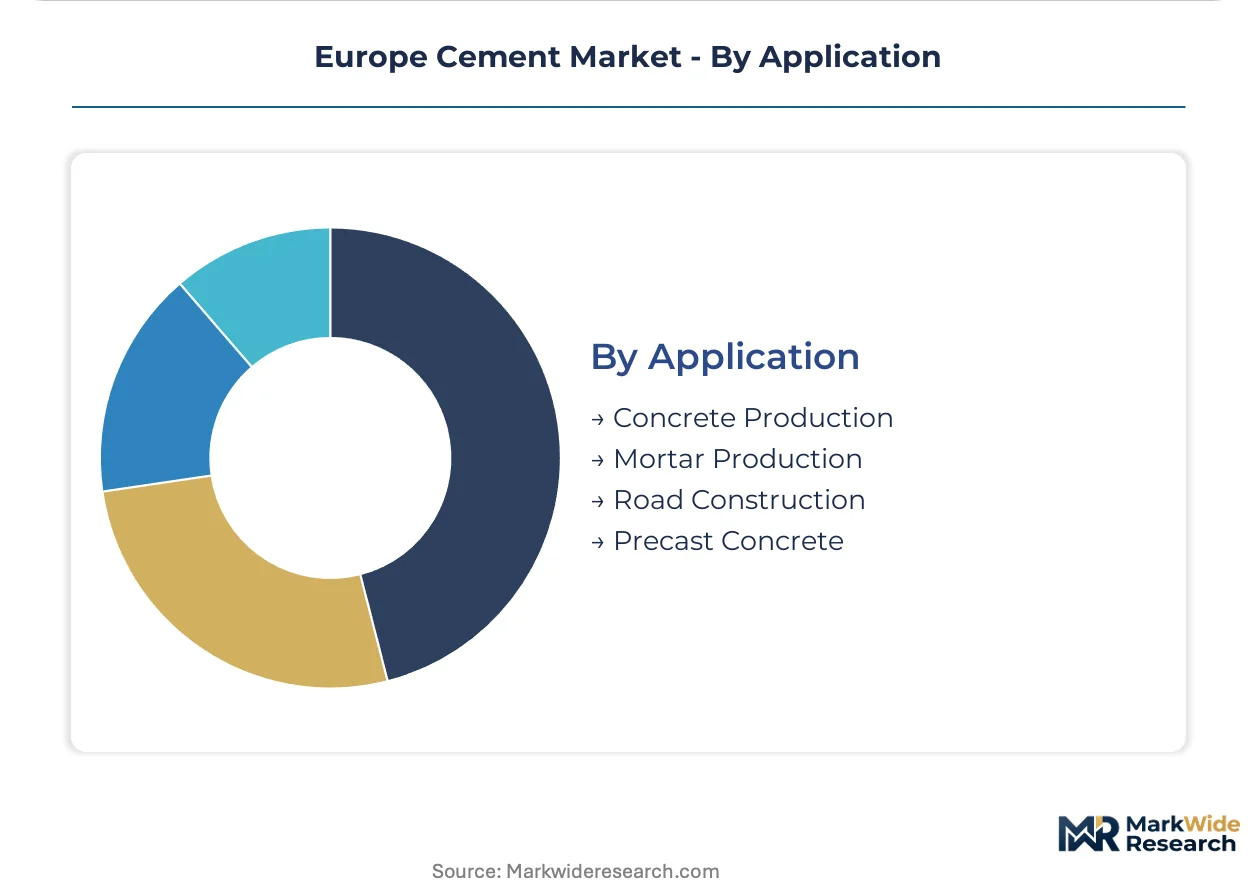
- Concrete Production:Ready-mix and site-batched concrete consumes over 70% of European cement volume. German and French precasters are specifying CEM III blast-furnace slag blends for bridge and tunnel segments.
- Precast Concrete:Factory-cured architectural and structural elements demand controlled setting times and surface finish quality. Italian cladding panel manufacturers pay specification premiums for white and low-alkali cements.
- Road Construction:Pavements and soil stabilization require rapid strength development and freeze-thaw resistance. Baltic States highway programs are accelerating demand for CEM I 42.5 N.
- Mortar Production:Masonry, rendering, and screed applications use finer-ground formulations with air-entrainment additives. Traditional lime-cement blends persist in heritage restoration across Southern Europe.
Concrete production anchors absolute consumption; precast concrete is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone deposits in the Jura Mountains and Bavarian Alps anchor Central European cement production capacity. These carbonate-rich formations feed integrated plants across Germany, Poland, and the Czech Republic. The regional production map follows the distribution of high-grade raw material accessibility and EU-funded infrastructure corridors.
Germany
Rhineland-Palatinate and North Rhine-Westphalia host dense clusters of integrated cement works serving the Benelux corridor. The Federal Immission Control Act implements Industrial Emissions Directive standards through state-level permitting. Heidelberg Materials operates multiple kilns in the Ennigerloh region where waste-derived fuel substitution exceeds national averages.
Poland
EU cohesion fund disbursements are accelerating motorway and rail corridor construction across Masovia and Silesia. The National Fund for Environmental Protection and Water Management channels support for alternative fuel infrastructure at cement plants. Górażdże and Nowiny anchor major production basins supplying Warsaw and Kraków construction markets.
France
Precast concrete manufacturing in Île-de-France and Auvergne-Rhône-Alpes drives specification-grade cement demand for transport infrastructure. The French Environment and Energy Management Agency administers carbon audit requirements under EU Green Deal implementation. Vicat maintains integrated operations in the Grenoble basin serving Alpine tunnel and viaduct projects.
Italy
White cement and specialty formulations for architectural concrete concentrate in Lombardy and Piedmont where marble-grade limestone permits low-iron clinker production. The National Institute for Insurance against Accidents at Work enforces kiln safety standards under EU harmonized rules. Buzzi Unicem's Bergamo-area plants supply northern Italian precasters and Mediterranean export markets.
Romania
Automotive plant expansions in Argeș and Prahova counties are lifting sulfate-resistant cement consumption for industrial foundations. The Ministry of Environment implements EU ETS allocation rules through national trading permits. Fieni and Medgidia cement works serve Bucharest-Brașov development corridor projects financed by structural funds.
Europe Cement Market Key Industry Players
Global majors compete with regional champions across production scale and carbon compliance capabilities. The European cement sector exhibits moderate consolidation with five integrated groups commanding majority capacity share alongside national specialists in Mediterranean and Eastern markets. Three archetypes dominate: vertically integrated multinationals with waste-fuel infrastructure, limestone-anchored regional producers, and coastal import-dependent distributors. Competitive dynamics center on kiln fuel substitution rates and clinker factor reduction rather than greenfield capacity expansion.
Among the integrated multinational tier, Heidelberg Materials, Buzzi Unicem, and CRH occupy positions defined by geographic footprint breadth and alternative fuel integration depth. Heidelberg Materials exemplifies the waste-to-fuel transition archetype through captive processing infrastructure. Buzzi Unicem represents limestone reserve control as a competitive anchor in Southern European markets. CRH sits within the multi-local operating model, managing distinct national subsidiaries with compliance capabilities tailored to member-state regulatory variations.
| Leading Market Players |
|---|
| CEMEX |
| Titan Cement Group |
| Heidelberg Materials |
| EURO CEMENT |
| Vicat Group |
| Holcim |
| Buzzi Unicem |
| Duna-Drava Cement |
| CRH |
| Others |
Cost & Logistics Intelligence
Pyroprocessing specialist concentration in Germany's Rhineland-Palatinate and Poland's Silesia feeds labor-cost differentials that widen pricing-tier spreads between premium low-carbon formulations and commodity-grade bulk cement. The EU ETS carbon cost pass-through mechanism amplifies these spreads as clinker-intensive production faces margin compression while blended alternatives capture specification premiums.
Pricing Analysis
Technical service bundling separates premium-grade cement suppliers offering carbon audit documentation and batch optimization support from unbundled commodity sellers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU Green Deal compliance tiers and volume scale in framework agreements. Pricing pressure stems from Turkish import competition landing at Greek and Bulgarian ports below domestic production cost. Infrastructure megaprojects demonstrate lowest price sensitivity due to specification-grade requirements and priority allocation premiums, while fragmented residential builders remain most cost-responsive.
Supply Chain Analysis
Limestone feedstock supply rests on quarry reserves in Germany's Bavarian Alps, Poland's Górażdże basin, and Italy's Lombardy region. Alternative fuels draw from municipal waste streams and industrial byproducts, while clinker substitutes hinge on blast-furnace slag availability from steelworks and fly ash from coal-fired generation. Single-source vulnerability concentrates in high-grade carbonate reserves facing depletion in Southern Spain and parts of Italy. Distribution runs through direct sales to ready-mix chains and infrastructure contractors, supplemented by wholesale networks serving regional construction merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinker kiln retrofit capacity constraints prop pricing power as legacy wet-process lines require complete rebuilds to meet Industrial Emissions Directive standards, limiting supply elasticity against EU-funded demand surges.
For Market Incumbents: Acquire waste-derived fuel processing infrastructure to secure thermal substitution rates above regional averages. Cement producers must anchor limestone quarry control in Poland and Romania where EU cohesion fund disbursements are accelerating transport corridor construction. Carbon capture pilot deployment at German and French integrated plants defends margin position against tightening EU ETS allocation rules.
For New Entrants and Emerging Players: Regional distributors in the Baltic States offer channel partnership pathways into Estonia, Latvia, and Lithuania where per-capita cement consumption sits below half the EU average. White-space concentration appears in specification-grade low-alkali formulations for 3D-printed concrete architectural elements. Engineering-procurement-construction contractor relationships provide the most penetrable go-to-market angle for mid-scale blended cement entrants.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated waste-fuel specialists given EU Green Deal clinker substitution mandates accelerating specification-grade demand. Long-term viability over a five-to-ten-year horizon favors producers with verified low-emission product certification and captive alternative fuel infrastructure. The signal to watch is carbon border adjustment mechanism phase-in timing and verification protocol adoption rates among domestic producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Infrastructure Buildout | Waste-derived thermal substitution secures cost advantage under EU ETS carbon pricing. |
| Clinker Factor Reduction Program | Calcined clay and slag blend development captures specification preference in public tenders. |
| Carbon Capture Pilot Deployment | Post-combustion amine scrubbing attracts project finance for decarbonized production. |
| Long-term Supply Agreement | Framework contracts with Polish and Romanian transport authorities lock volume certainty. |
| Joint Venture | Steelworks partnerships secure blast-furnace slag supply for CEM III blended cement expansion. |
Research Approach
Document review covered EU ETS allocation records, national building code specifications, and Industrial Emissions Directive permitting databases, complemented by interviews with plant operations directors at integrated cement works, procurement leads at ready-mix concrete chains, and technical directors at precast manufacturing facilities. Secondary validation drew from customs trade data, SEC filings of listed building materials groups, and Cefic sector reports. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic construction forecasts.
Historical volume trajectories cross-referenced against expert panel input on kiln fuel substitution rates and clinker factor reduction timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation tier, end-use application, distribution channel structure, and regional production hub clustering. CAGRs were derived from demand elasticity assumptions tied to EU cohesion fund disbursement schedules and carbon cost pass-through coefficients. Forecast inputs incorporated alternative fuel availability constraints and limestone reserve depletion curves.
Caveats apply where natural gas price volatility, Turkish import competition intensity, or carbon border adjustment mechanism enforcement timing could materially shift the outlook. Forecasts reflect documented assumptions on regulatory implementation pace and infrastructure investment commitment levels. A small set of named triggers—ETS price spikes, waste fuel quality disruptions, and Baltic States structural fund acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
France Architectural Coatings Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Roof Cover Boards Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Ductile Iron Pipe Market
Building Materials
United States Architectural Coatings Market
Building Materials
Concrete Admixtures Market
Building Materials
Steel Products Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Cement Market
Building Materials
Australia Architectural Coatings Market