

Masonry Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Masonry Cement Market Insights
The capital-intensity divergence between integrated kiln operators and regional blenders is unwinding competitive stability across the masonry cement sector. UltraTech Cement leverages captive limestone reserves and clinker capacity to sustain margin structures in South Asian markets. Cemex competes through logistics networks that dominate coastal distribution corridors in the Americas and Mediterranean basin. Dangote Cement anchors West African supply through integrated manufacturing clusters near Lagos and Ibese.
Masonry cement is a hydraulic cement product formulated from Portland cement clinker, limestone, gypsum, and air-entraining or water-retention additives, designed to bond masonry units with enhanced workability and reduced shrinkage. The material achieves compressive strengths typically ranging from 2,500 to 3,500 psi, serving primarily as the binding matrix for brick, block, and stone assemblies in structural and veneer applications. Portland Masonry Cement occupies the dominant volume position across residential and light commercial construction, while Masonry Cement with Water Retention Additives captures premium positioning in hot-climate markets where extended board life reduces labor rework. The Bricklaying application segment sustains the largest demand pool, though Stone Masonry commands higher per-ton pricing in heritage restoration and high-end architectural projects.
The US EPA regulates Portland cement kiln emissions under the National Emission Standards for Hazardous Air Pollutants, while ASTM C91 governs masonry cement physical specifications for North American projects. India's BIS mandates IS 3466 certification for masonry cement composition and performance, shaping import eligibility and domestic manufacturing compliance. China's MEE enforces GB standards for cement industry carbon intensity, redirecting capacity toward blended and additive-modified formulations. Stakeholders must monitor evolving clinker-to-cement ratio mandates and regional carbon border adjustments that will reshape sourcing economics and product formulation strategies.
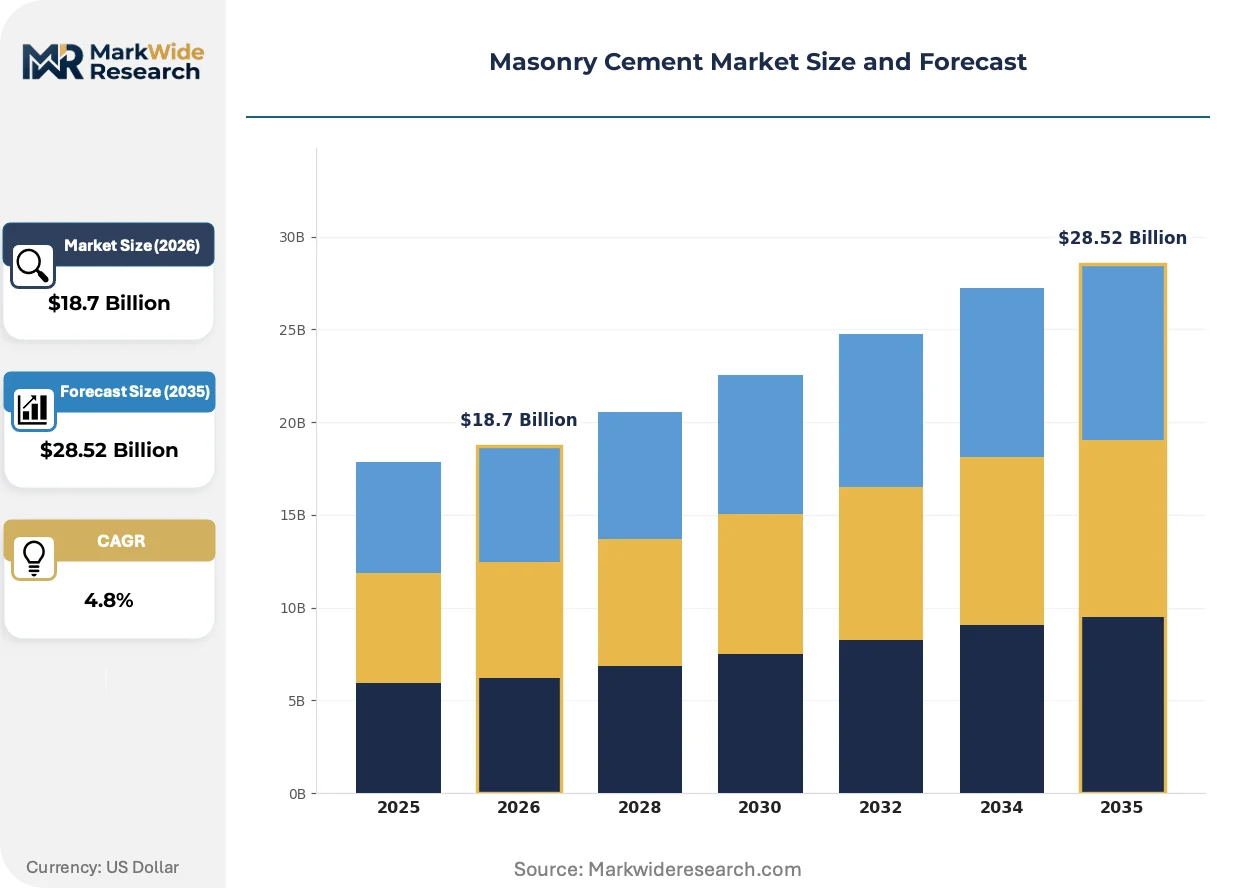
Market Dynamics
Clinker-to-cement ratio mandates are compressing traditional masonry cement economics while forcing rapid formulation pivots toward limestone calcined clay and supplementary cementitious materials. Regulatory pressure on kiln emissions is accelerating this structural shift across major manufacturing jurisdictions.
Growth Catalysts
- India's BIS IS 3466 certification tightening:Stricter composition standards are disqualifying low-grade imports and consolidating procurement around certified domestic producers, tightening supply discipline.
- Affordable housing schemes in Vietnam:State-backed residential construction from Ho Chi Minh City to Da Nang is concentrating bulk masonry cement demand into predictable, large-volume tenders.
- Limestone calcined clay technology:LC3 formulations are cutting clinker dependence by 50 percent while maintaining compressive performance, enabling margin recovery under carbon constraints.
Market Restraints
- Petcoke and thermal coal price volatility:Energy inputs represent 35-40 percent of production costs, with Indonesian and South African supply disruptions transmitting directly to margin compression.
- Clinker capacity concentration in China:Five integrated groups control 60 percent of global clinker exports, creating chokepoint risk for regional blenders dependent on seaborne supply.
- Technical ceiling on board-life extension:Water retention additives face diminishing returns beyond 72-hour workability, limiting premium pricing power in hot-climate markets.
Strategic Opportunities
- Heritage restoration in Italy and Spain:Stone masonry specifications for historic facades command 40-60 percent per-ton premiums over standard bricklaying grades, with EU Green Deal renovation wave funding expansion.
- Pre-blended dry mortar channel growth:Factory-controlled mixing is capturing share from site-batch practices in Germany and France, reducing waste claims and locking in specification adherence.
- Carbon border adjustment mechanism preparation:EU CBAM implementation is creating first-mover advantage for producers with verified low-clinker formulations and embedded carbon accounting systems.
Industry Challenges
- Kiln operator certification backlog:US EPA National Emission Standards compliance timelines are stretching 18-24 months, freezing capacity additions during demand recovery.
- SCM sourcing complexity:Securing consistent fly ash and slag quality requires multi-year offtake negotiations with power and steel producers, binding working capital.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masonry Cement Market Trends and Innovations
Carbon accounting integration is becoming a procurement gate rather than a marketing overlay, with embodied carbon thresholds now written into public infrastructure tenders across multiple jurisdictions. This is forcing simultaneous reformulation, certification, and supply chain reengineering.
Alkali-activated binders derived from industrial byproducts are supplanting conventional Portland-based masonry cements in non-structural applications. Nordic prefabricated wall panel manufacturers are adopting these formulations at commercial scale, attracted by 70 percent lower embodied carbon credentials that satisfy public procurement mandates. The technology is supplanting traditional supply relationships between blenders and clinker traders, compressing the intermediary layer in regional distribution.
China's MEE enforcement of GB standards for cement industry carbon intensity is redirecting capacity toward blended and additive-modified formulations. Kiln operators must now report Scope 1 emissions quarterly, with non-compliance triggering production curtailments. Export-oriented plants are accelerating LC3 line conversions to maintain access to Southeast Asian markets where carbon-conscious developers are pre-qualifying suppliers.
Developer procurement consolidation is compressing supplier rosters from fragmented local sourcing to approved-vendor lists with strict ESG criteria. Large residential contractors in Vietnam and Indonesia are mandating chain-of-custody documentation for all cementitious materials, displacing informal distributors. This concentration is most visible in Vietnam's urban corridor, where three national developers now account for the majority of masonry cement volume into high-rise residential projects.
Masonry Cement Market Segmentation
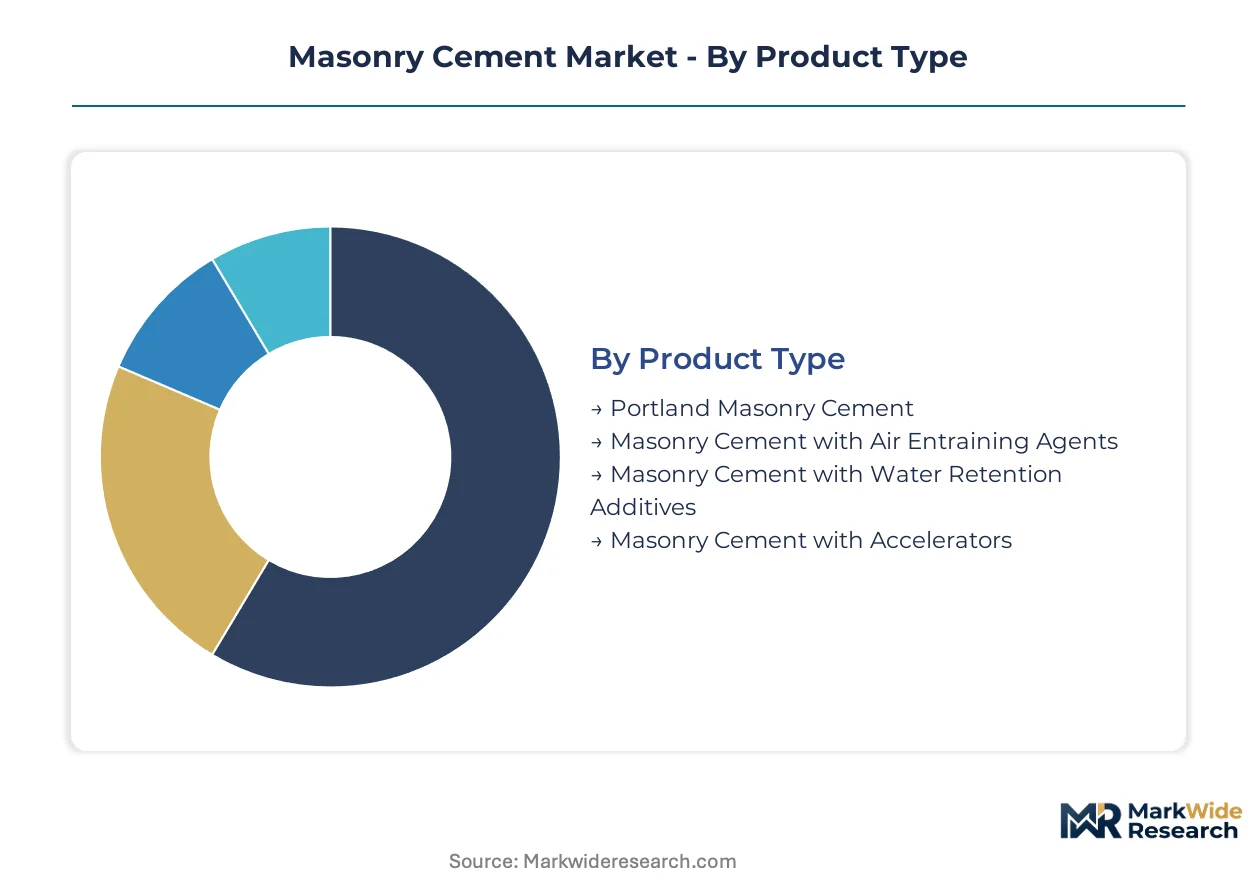
Masonry cement segmentation reveals how formulation chemistry, mixing technology, and construction application intersect with regulatory compliance and procurement economics. Understanding these category boundaries helps suppliers align certification investments with addressable demand pools.
Product Type:
ASTM C91, IS 3466, and GB standards each impose distinct compositional thresholds that segment product positioning across export markets.
- Portland Masonry Cement:Formulated from Portland cement clinker, limestone, and gypsum without specialty additives, this grade achieves compressive strengths of 2,500–3,500 psi. Residential developers in Vietnam's Ho Chi Minh City–Da Nang corridor specify this grade for high-volume affordable housing tenders where cost discipline dominates procurement.
- Masonry Cement with Water Retention Additives:Incorporates hydroxyethyl cellulose or similar polymers to extend board life beyond 48 hours in hot-climate conditions. Specialized masons in heritage restoration projects across Italy and Spain absorb premium pricing to reduce labor rework on intricate stone facades.
- Masonry Cement with Air Entraining Agents:Vinsol resin or synthetic surfactants create microscopic voids for freeze-thaw resistance.
- Masonry Cement with Accelerators:Calcium chloride or non-chloride formulations shorten set times for cold-weather scheduling.
Portland Masonry Cement handles the majority of throughput; Masonry Cement with Water Retention Additives is expanding most quickly on share.
Technology:
Mixing technology selection determines capital intensity, quality consistency, and carbon accounting traceability for downstream specification.
- Preblended:Factory-controlled proportioning of cement, lime, sand, and additives eliminates site-batch variability. German and French dry mortar channels are capturing share from traditional practices as waste reduction and specification adherence become procurement mandates.
- Dry Mixing:On-site blending of separate components persists in emerging markets with fragmented distributor networks.
- Hydration Controlled:Encapsulated cement particles delay water contact for extended workability windows.
- High Reactivity:Finely ground formulations accelerate early strength development for rapid construction cycles.
- Low Heat Emission:Modified clinker chemistry reduces thermal cracking risk in mass masonry placements.
Preblended technology commands the steepest expansion trajectory; Dry Mixing retains volume concentration in price-sensitive segments.
Application:
Application segmentation tracks how structural function, aesthetic requirements, and labor skill levels reshape formulation demand.
- Bricklaying:Bonding clay or concrete masonry units in structural walls and veneers represents the largest demand pool. India's tightening BIS IS 3466 certification is disqualifying low-grade imports and consolidating procurement around certified domestic producers for standard residential construction.
- Stone Masonry:Heritage restoration and high-end architectural specifications command 40–60 percent per-ton premiums over bricklaying grades. EU Green Deal renovation wave funding is expanding project pipelines across Italy and Spain.
- Block Laying:Concrete masonry unit construction for commercial and industrial shells.
- Tile Setting:Thin-bed applications for ceramic and natural stone finishes.
- Plastering:Base and finish coats for interior and exterior wall surfaces.
Bricklaying absorbs the dominant share of volume; Stone Masonry is climbing the fastest on pricing power.
End User:
End-user concentration reflects procurement consolidation trends and ESG documentation requirements that filter supplier eligibility.
- Residential Developers:Large national contractors in Vietnam and Indonesia now mandate chain-of-custody documentation, displacing informal distributors. Three Vietnamese developers account for the majority of masonry cement volume into high-rise residential projects.
- Specialized Masons:Skilled trades executing heritage restoration and architectural stone work absorb premium formulations.
- General Contractors:Diversified construction managers serving mixed project portfolios.
- Infrastructure Developers:Public works and transportation project sponsors with embodied carbon thresholds.
- Commercial Builders:Office, retail, and industrial facility constructors.
Residential Developers concentrate the largest procurement volumes; Specialized Masons are gaining share fastest on premium formulation pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy and Spain command 40-60 percent per-ton premiums in heritage stone masonry, while Vietnam's affordable housing corridor compresses margins through bulk procurement concentration.
United States
Residential construction recovery and infrastructure reinvestment are absorbing masonry cement volumes. US EPA National Emission Standards compliance timelines stretch 18-24 months, freezing kiln capacity additions. Texas and Florida construction corridors concentrate demand for freeze-thaw resistant formulations.
Germany
Pre-blended dry mortar channels are displacing site-batch practices in residential and commercial construction. EU Green Deal renovation wave funding expands heritage restoration pipelines. Bavaria and North Rhine-Westphalia manufacturing clusters supply factory-controlled mixing systems.
India
Affordable housing schemes and urban densification are consolidating procurement around certified domestic producers. BIS IS 3466 certification tightening disqualifies low-grade imports, tightening supply discipline. Maharashtra and Gujarat cement corridors anchor domestic manufacturing capacity.
Vietnam
State-backed residential construction from Ho Chi Minh City to Da Nang concentrates bulk demand into predictable, large-volume tenders. Developer procurement consolidation mandates chain-of-custody documentation, displacing informal distributors. Three national developers now account for the majority of high-rise residential volume.
Italy
Heritage restoration and high-end architectural stone masonry specifications command premium pricing over standard bricklaying grades. EU Green Deal renovation wave funding expands project pipelines. Lombardy and Veneto restoration specialists absorb water retention additive formulations for intricate facade work.
Masonry Cement Market Competitive Landscape
Concentration sits with integrated kiln operators controlling captive limestone reserves and clinker capacity. Regional blenders dependent on seaborne supply face margin compression from clinker capacity concentration. Three archetypes dominate: vertically integrated multinationals with quarry-to-distribution control, national champions anchored in protected domestic markets, and specialized blenders pivoting toward LC3 formulations. Competitive moves center on limestone calcined clay line conversions and logistics network consolidation.
Among integrated South Asian operators, UltraTech Cement exemplifies the quarry-captive archetype through clinker self-sufficiency. Cemex represents the logistics-dominant model with coastal distribution corridor control. Dangote Cement anchors the regional manufacturing cluster approach near Lagos and Ibese. These three occupy positions across distinct geographic strongholds rather than competing head-to-head.
| Leading Market Players |
|---|
| UltraTech Cement |
| Ambuja Cements |
| Anhui Conch |
| Buzzi Unicem |
| Cemex |
| China National Building Material Group |
| CRH |
| Dangote Cement |
| Holcim |
| Others |
Pricing and Supply Chain Analysis
Limestone calcined clay substitution for traditional clinker feedstocks is redrawing procurement geography toward calcined clay deposits in Vietnam and India while compressing per-ton production economics for integrated operators. This input shift simultaneously weakens the pricing power of concentrated Chinese clinker exporters and elevates regional blenders with captive LC3 technology.
Pricing Analysis
The customization-premium spread between heritage stone masonry specifications and standard bricklaying grades runs 40–60 percent on a per-ton basis, with water retention additive formulations commanding the upper tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—BIS IS 3466 compliance in India and ASTM C91 adherence in North America filter supplier eligibility and sustain price premiums. Pricing pressure stems from petcoke and thermal coal volatility transmitting directly to energy-intensive kiln operations, with Indonesian supply disruptions compressing margins fastest. Residential developers in Vietnam's affordable housing corridor exhibit highest price sensitivity through consolidated bulk tenders, while specialized masons executing Italian heritage restoration absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Inventory lead times for clinker-dependent blenders have elongated as Chinese kiln operators redirect capacity toward domestic carbon compliance, stretching seaborne availability windows. Supply concentrates in China, Vietnam, and India, with five integrated Chinese groups controlling the majority of global clinker exports and creating chokepoint vulnerability for regional blenders. Raw material dependencies center on Portland cement clinker, calcined clay, and gypsum, with fly ash and slag quality consistency binding working capital through multi-year offtake negotiations. Tariff exposure on cross-border clinker movements represents the dominant structural risk, particularly for Southeast Asian blenders sourcing from Chinese coastal kilns. Distribution runs through coastal bulk terminals and inland barge networks, with Cemex-style logistics-dominant operators capturing margin through corridor control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in the masonry cement market as three Vietnamese national developers now account for the majority of high-rise residential volume, shifting procurement leverage from fragmented local distributors toward consolidated approved-vendor programs with strict ESG documentation mandates.
For Market Incumbents: Secure captive limestone reserves and clinker capacity through backward integration into quarry assets near manufacturing clusters, insulating margin structures from Chinese export chokepoints. Accelerate LC3 line conversions to maintain specification eligibility under tightening carbon border adjustments, particularly for EU-bound shipments. Certification investment in BIS IS 3466 and ASTM C91 compliance creates switching costs that defend position against low-grade import competition.
For New Entrants and Emerging Players: Lead with carbon-accounting-enabled formulations targeting infrastructure developers with embodied carbon thresholds written into public tenders, bypassing incumbent relationships in residential construction. Heritage restoration in Italy and Spain offers the most penetrable premium segment, where EU Green Deal renovation wave funding expands project pipelines and specialized masons prioritize performance over scale economics. A go-to-market angle anchored in verified chain-of-custody documentation displaces informal distributors in Vietnam's consolidating procurement environment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional blenders lacking captive clinker supply but holding LC3 formulation expertise and coastal logistics infrastructure. Long-term viability across the analysis window favors operators with verified low-clinker credentials and embedded carbon accounting systems capable of meeting procurement pre-qualification standards. The signal to watch is EU CBAM implementation pace, which will determine first-mover advantage windows for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| LC3 Line Conversion | Reduces clinker dependence by half while maintaining ASTM C91 compressive performance standards. |
| Captive Limestone Acquisition | UltraTech-style quarry control insulates margin structures from seaborne clinker price volatility. |
| Carbon Accounting Integration | Embedded emissions tracking satisfies Vietnam developer chain-of-custody documentation mandates. |
| Heritage Restoration Specialization | Italian and Spanish stone masonry specifications command 40–60 percent per-ton premiums over bricklaying grades. |
| Pre-blended Dry Mortar Channel Buildout | German and French factory-controlled mixing reduces waste claims and locks specification adherence. |
Research Methodology
Cross-validation between executive interviews at integrated kiln operators and customs/trade data anchors the qualitative findings on clinker capacity concentration and regional sourcing patterns. Primary fieldwork engaged plant managers at Vietnamese and Indian manufacturing clusters, procurement leads at national residential developers, technical R&D directors formulating LC3 alternatives, and distribution channel partners managing coastal bulk terminals. Secondary validation drew from BIS certification registries, ASTM standard documentation, SEC 10-K filings from listed cement groups, and EU carbon border adjustment mechanism draft regulations. Bottom-up volume estimates from application-level consumption patterns triangulate against top-down capacity assessments from clinker kiln databases.
Sensitivity analysis on energy input costs and clinker-to-cement ratio mandates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type chemistry, mixing technology capital intensity, application structural function, and end-user procurement consolidation status. CAGRs derive from regression against construction output indices and housing start data, with specific weighting for India's affordable housing scheme disbursement trajectories and Vietnam's Ho Chi Minh City–Da Nang corridor investment flows.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of carbon intensity standards or abrupt clinker export restrictions from Chinese kiln operators would require recalibration. Forecasts reflect documented assumptions on energy price trajectories and certification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.