
 Honeycomb Sandwich Panels Market | 2026-2036
Honeycomb Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Honeycomb Sandwich Panels Market Foresight
Market Context
European aluminum honeycomb producers is shifting capacity toward thermoplastic variants to serve stricter EU Green Deal material-recycling requirements. Hexcel Corporation anchors North American aerospace supply through its proprietary carbon fiber honeycomb formulations. EconCore N.V. competes in automotive lightweighting with continuous thermoplastic honeycomb production lines. Schütz GmbH & Co. KGaA dominates European transportation markets through its glass-reinforced polypropylene core technology.
Technical Definition and Segments
Honeycomb sandwich panels bond thin, high-strength face sheets to hexagonal cellular cores, achieving specific compressive strengths above 1.5 MPa at densities below 50 kg/m³ for aerospace-grade aluminum configurations. The primary purpose is structural efficiency: maximizing stiffness-to-weight ratios in applications where every kilogram carries fuel or performance penalties. Metal Honeycomb leads aerospace revenue pools due to legacy airframe certification and extreme temperature tolerance, while Polymer cores represent the fastest-expanding category as automotive manufacturers adopt recyclable thermoplastics for electric vehicle battery enclosures and interior modules. Glass Fiber segments sustain construction demand in European facade systems where fire resistance ratings and thermal conductivity specifications govern building code compliance.
Regulatory Frame
FAA airworthiness directives and EASA CS-25 certification standards mandate flammability testing for cabin interior sandwich panels, effectively filtering uncertified suppliers from commercial aviation procurement chains. REACH chemical restrictions and the EU Green Deal circular-economy framework are forcing reformulation of adhesives and core resins across European manufacturing bases. Stakeholders must monitor evolving battery-safety regulations in automotive markets, where thermal runaway containment requirements for electric vehicle floors are rewriting load-bearing and insulation specifications for honeycomb sandwich configurations.
Market Dynamics
Aerospace OEMs are consolidating supplier bases around thermoplastic honeycomb cores as EU Green Deal mandates force material-recycling compliance across cabin interior procurement chains, compressing qualification timelines for legacy aluminum producers.
Growth Catalysts
- FAA and EASA flammability standards:Certification requirements for commercial aviation cabin interiors filter uncertified suppliers from procurement chains, concentrating demand among qualified honeycomb panel manufacturers.
- Electric vehicle battery enclosures:Automotive OEMs specify thermoplastic honeycomb cores for thermal runaway containment floors, creating new volume demand outside traditional aerospace applications.
- Aluminum-to-thermoplastic conversion:German and Chinese producers are retooling extrusion lines to serve recyclable core demand from European transportation OEMs facing REACH adhesive restrictions.
Market Restraints
- Aramid fiber price volatility:Aerospace-grade Nomex core input costs fluctuate with petrochemical feedstock markets, compressing margin stability for tier-two panel laminators.
- Supply concentration in Germany:European transportation-grade polypropylene honeycomb production clusters around Schütz GmbH's continuous extrusion capacity, creating single-source vulnerability for automotive programs.
- Legacy airframe certification lock-in:FAA Parts Manufacturer Approval timelines for new core materials extend 18-24 months, freezing out innovative thermoplastic formulations from retrofit markets.
Strategic Opportunities
- India commercial aviation MRO expansion:DGCA maintenance facility approvals are multiplying in Bangalore and Hyderabad, opening aftermarket cabin retrofit demand for fire-resistant honeycomb panels.
- Building-integrated photovoltaics:Glass-reinforced honeycomb cores are penetrating European facade systems where thermal conductivity specifications meet BIPV module mounting requirements.
- EU Green Deal circular-economy incentives:Recyclable thermoplastic core development qualifies for EIC Accelerator funding, accelerating R&D cost recovery for material startups.
Industry Challenges
- Adhesive formulation chemistry:REACH SVHC restrictions on epoxy hardeners force European laminators to requalify bonding systems, extending product development cycles.
- Thermoplastic welding technician scarcity:Continuous core production lines require operators trained in ultrasonic and infrared joining protocols, a skill set concentrated among German and Belgian technical institutes.
- Battery-safety certification timelines:UN ECE R100 thermal propagation testing for EV floor assemblies adds 8-12 months to honeycomb sandwich panel qualification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honeycomb Sandwich Panels Market |
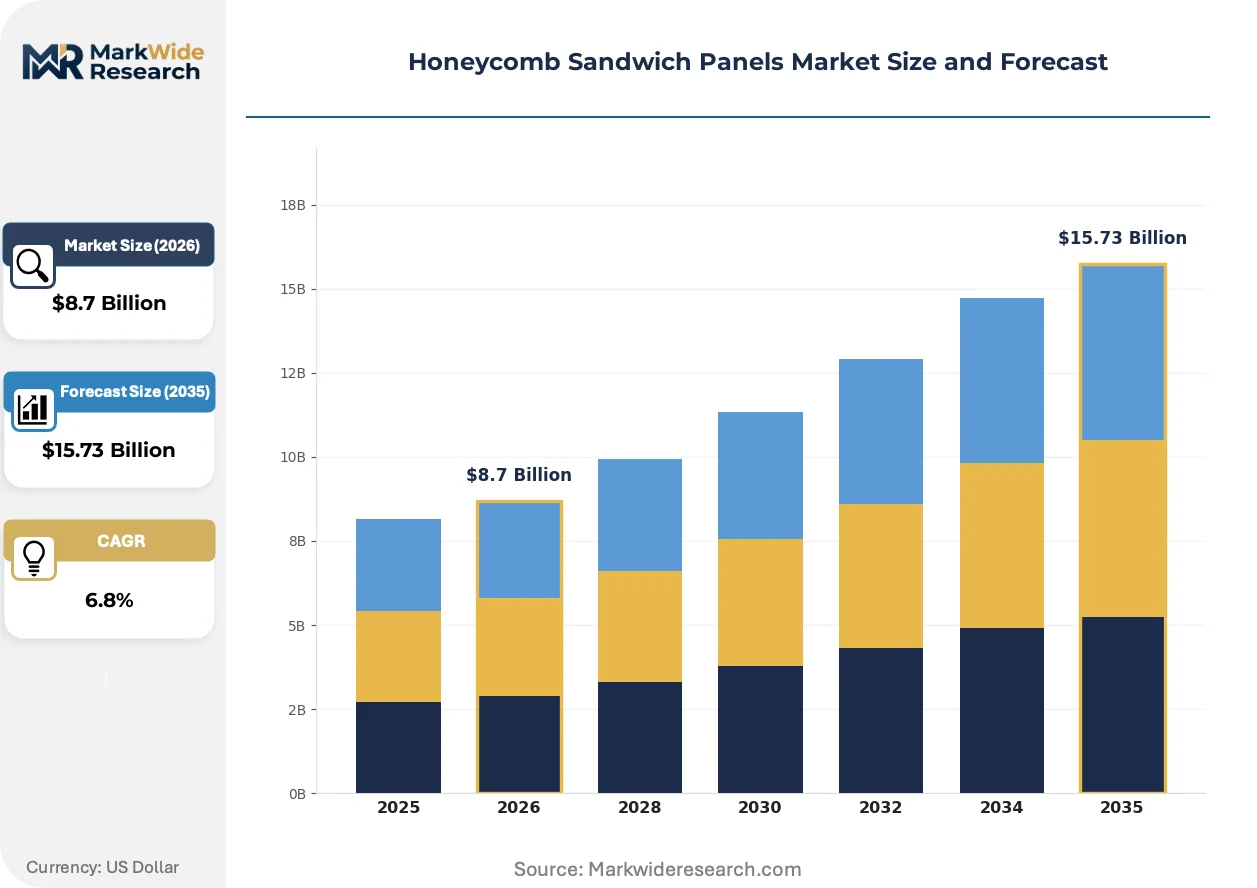
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Honeycomb, Glass Fiber, Structural Foam, Polymer End User: Aerospace, Automotive, Construction, Marine Application: Roofing, Wall Panels, Flooring, Insulation Technical Specification: Thermal Conductivity, Load-Bearing Capacity, Fire Resistance, Moisture Resistance |
| Companies Covered | Arconic, Schütz GmbH & Co. KGaA, Hexcel Corporation, Pacific Panels Inc, EconCore N.V., 3A Composites GmbH, Alucoil, Hunter Douglas, Plascore, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeycomb Sandwich Panels Market Shifts & Advancements
Material substitution and manufacturing automation are compressing traditional aerospace supply hierarchies while regulatory deadlines force simultaneous reformulation of core chemistries and adhesive systems across three continents.
Continuous thermoplastic honeycomb extrusion is automating cell formation through in-line thermal bonding of polypropylene films, eliminating the adhesive lamination bottleneck that constrains aluminum honeycomb cycle times. Automotive Tier-1 suppliers in Germany and China are installing these production lines to serve electric vehicle battery enclosure contracts. The technology is automating cost parity between thermoplastic and aluminum cores at production volumes above 500,000 square meters annually.
EU Green Deal circular-economy framework requirements are mandating end-of-life recyclability disclosures for cabin interior materials entering European-registered aircraft fleets. REACH restrictions on brominated flame retardants are forcing reformulation of polyimide and phenolic resin systems used in aerospace-grade cores. Panel laminators serving Airbus and Embraer programs are responding by qualifying thermoplastic alternatives that bypass thermoset disposal constraints.
Airline procurement departments are consolidating cabin interior contracts around full-service integrators capable of design, certification, and retrofit execution. This buyer concentration is displacing component-level honeycomb panel vendors from direct OEM relationships. The shift is most visible in North American narrow-body refurbishment programs, where American Airlines and Delta Air Lines have shifted to turnkey interior modification contracts with Lufthansa Technik and ST Engineering.
Honeycomb Sandwich Panels Market Segmentation
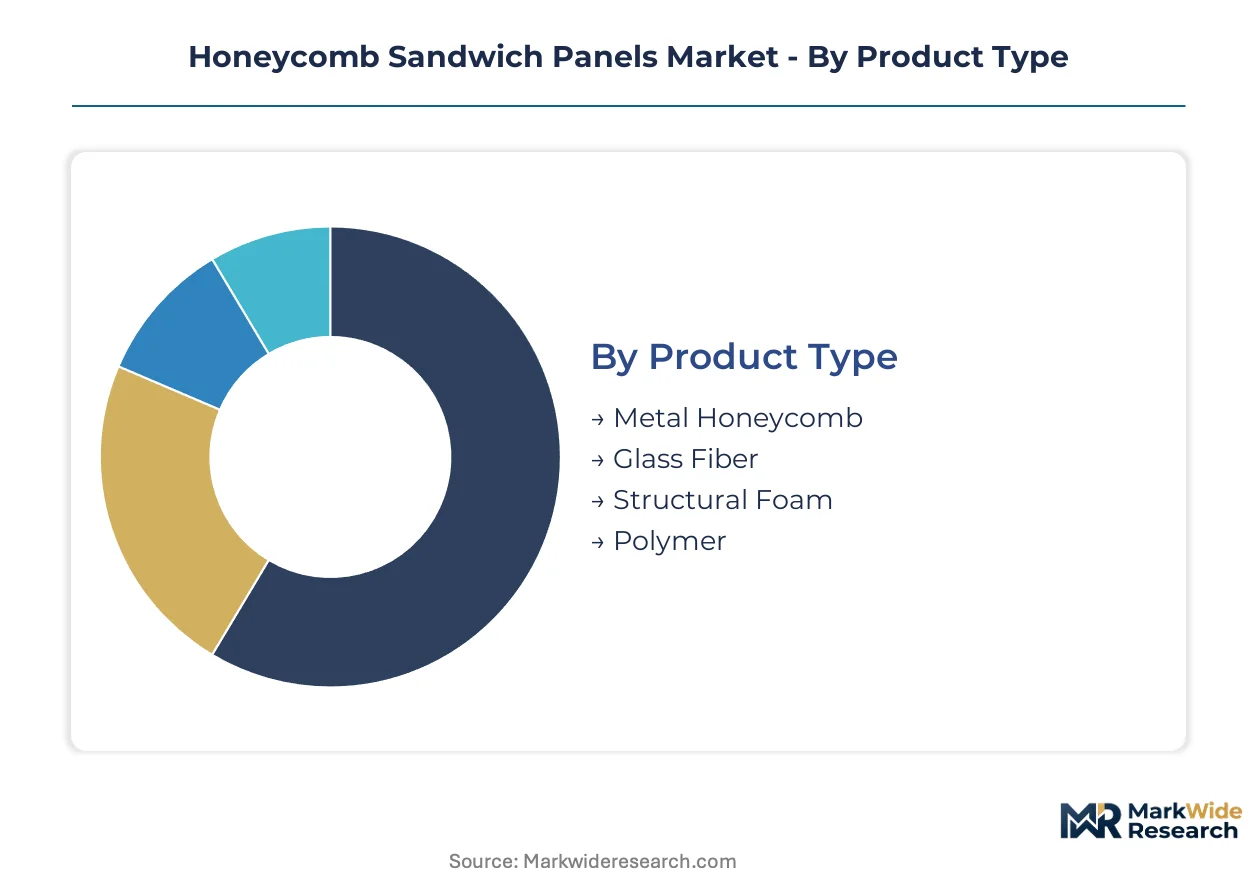
Material selection in honeycomb sandwich panels dictates certification pathways, end-use eligibility, and recyclability compliance. Buyers segment procurement by performance thresholds, regulatory jurisdiction, and integration complexity rather than commodity pricing alone.
Product Type:
Cost tier separates legacy aerospace buyers from automotive and construction purchasers seeking recyclable alternatives.
- Metal Honeycomb:Aluminum and stainless steel hexagonal cell structures achieve specific compressive strengths above 1.5 MPa at densities below 50 kg/m³. FAA and EASA airworthiness certification locks aerospace OEMs into aluminum cores for cabin interiors despite longer lead times. Metal Honeycomb leads volumes today; Polymer is gaining share fastest.
- Polymer:Thermoplastic polypropylene and polycarbonate cores enable continuous extrusion manufacturing with in-line thermal bonding. Automotive battery enclosure contracts in Germany and China are absorbing new production capacity as REACH adhesive restrictions displace thermoset alternatives.
- Glass Fiber:Glass-reinforced polypropylene and phenolic resin cores serve European facade systems where fire resistance ratings and thermal conductivity specifications govern building code compliance.
- Structural Foam:Rigid polyurethane and polymethacrylimide foam cores provide closed-cell moisture resistance for marine applications and secondary structural aircraft components.
Metal cores dominate aerospace revenue pools; thermoplastic formulations are climbing the fastest in automotive procurement.
End User:
Application maturity determines whether buyers prioritize legacy certification or rapid qualification cycles.
- Aerospace:Commercial aviation OEMs and MRO facilities specify fire-resistant cores meeting FAA flammability directives and EASA CS-25 standards. Fuel-efficiency mandates from the FAA and EASA are accelerating lightweight cabin interior procurement from North American and European suppliers.
- Automotive:Electric vehicle manufacturers specify thermoplastic honeycomb floors for thermal runaway containment under UN ECE R100 testing protocols. Battery enclosure demand is creating volume outside traditional aerospace applications.
- Construction:European building-integrated photovoltaic facades specify glass-reinforced cores where thermal conductivity and fire resistance ratings intersect with mounting requirements.
- Marine:Yacht and commercial vessel builders specify moisture-resistant structural foam cores for hull and deck applications where salt exposure degrades metal alternatives.
Aerospace commands premium pricing tiers; automotive volume expansion is reshaping supplier capacity allocation.
Application:
Structural loading requirements and regulatory exposure vary sharply across installation location.
- Wall Panels:Vertical facade applications in European construction prioritize thermal conductivity coefficients and fire resistance ratings under national building codes. BIPV integration is penetrating German and French markets where module mounting specifications favor glass-reinforced cores.
- Flooring:Aircraft cabin floors and EV battery enclosures demand compressive strength for distributed loading plus thermal insulation for fire containment. UN ECE R100 testing adds qualification timelines for automotive programs.
- Roofing:Lightweight sandwich configurations reduce structural steel requirements in commercial building projects across India and Southeast Asia.
- Insulation:Cold chain logistics and refrigerated transport specify moisture-resistant cores where thermal bridging must be minimized.
Wall panels sustain construction demand; flooring applications are expanding most quickly through automotive electrification.
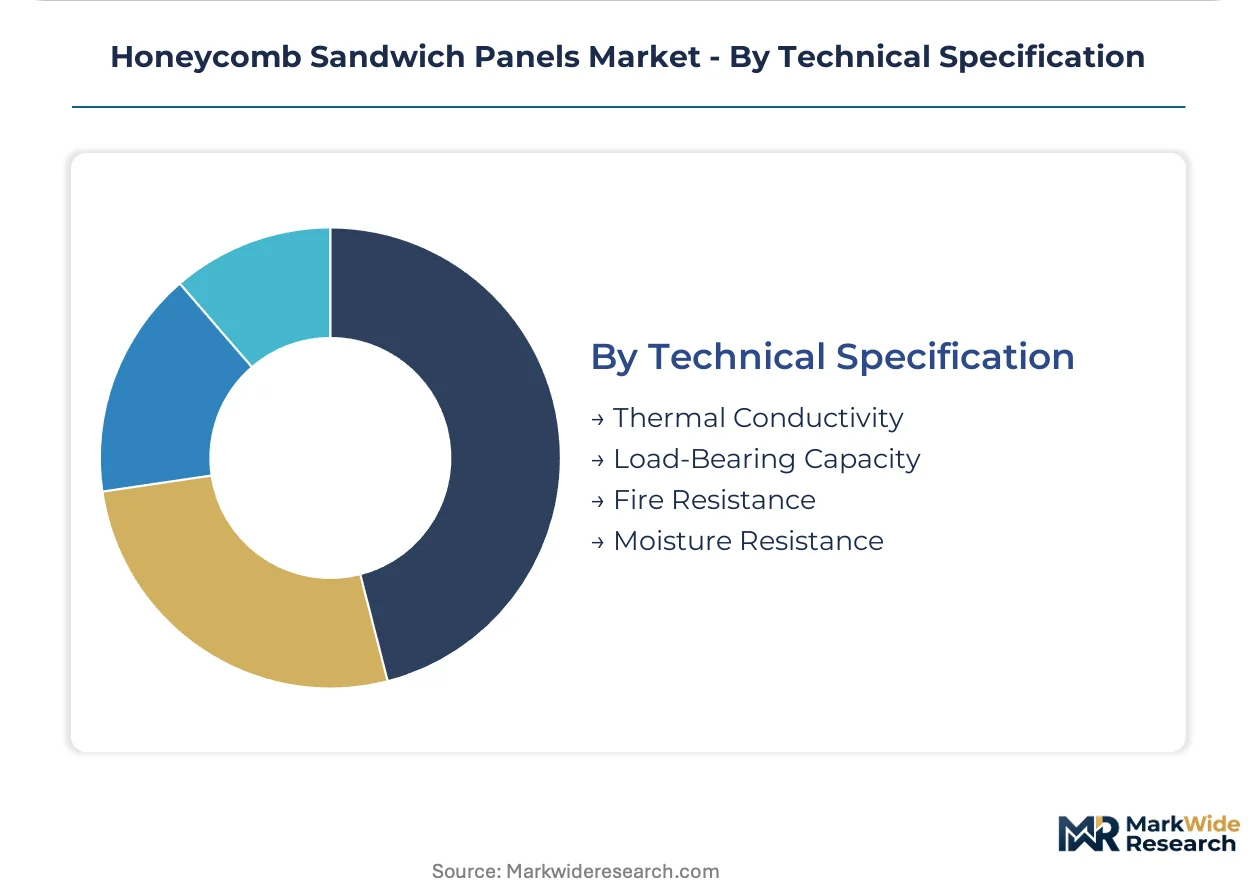
Technical Specification:
Certification grade separates qualified suppliers from commodity competitors in regulated end-uses.
- Fire Resistance:Brominated flame retardant restrictions under REACH are forcing reformulation of polyimide and phenolic resin systems used in aerospace-grade cores. Panel laminators serving Airbus programs are qualifying thermoplastic alternatives.
- Load-Bearing Capacity:Specific compressive strength thresholds determine eligibility for aircraft primary structure versus secondary cabin applications. FAA Parts Manufacturer Approval timelines extend qualification for new core materials.
- Thermal Conductivity:Facade system designers specify lambda values below 0.025 W/m·K for European energy efficiency compliance. BIPV mounting layers favor cores that insulate electrically while conducting thermally.
- Moisture Resistance:Closed-cell structural foam cores prevent water ingress in marine hull applications where aluminum honeycomb would corrode.
Fire resistance governs aerospace procurement; thermal conductivity specifications are driving fastest specification growth in construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing honeycomb sandwich panel production capacity toward jurisdictions with lower compliance costs for thermoplastic core manufacturing. Germany and China concentrate legacy aluminum capacity while newer thermoplastic extrusion lines cluster in Belgium and the United States to evade REACH adhesive restrictions.
United States
FAA airworthiness directives and fuel-efficiency mandates from the FAA are accelerating lightweight cabin interior procurement from aerospace OEMs. The FAA Parts Manufacturer Approval process locks qualified suppliers into long-term contracts for commercial aviation programs. Hexcel Corporation anchors North American aerospace supply through its proprietary carbon fiber honeycomb formulations manufactured in Colorado and Utah facilities.
Germany
EU Green Deal circular-economy requirements and REACH SVHC restrictions on epoxy hardeners are forcing reformulation of adhesive systems across manufacturing bases. The country's national aviation regulator enforces EASA CS-25 certification standards that mandate flammability testing for cabin interior panels. Schütz GmbH & Co. KGaA dominates European transportation markets through its continuous extrusion capacity concentrated in Selters.
China
Automotive OEMs specify thermoplastic honeycomb floors for electric vehicle battery enclosures under MIIT safety protocols. The country's dual carbon goals are pressuring manufacturers to adopt recyclable core materials in transportation applications. New production capacity for aluminum and thermoplastic honeycomb cores is concentrating in Jiangsu and Guangdong provinces to serve domestic EV battery enclosure contracts.
Belgium
REACH chemical restrictions are displacing thermoset adhesive formulations toward thermoplastic welding protocols that bypass disposal constraints. EconCore N.V. competes in automotive lightweighting with continuous thermoplastic honeycomb production lines based in Leuven. Technical institutes in Flanders supply operators trained in ultrasonic and infrared joining protocols that scarce across continental Europe.
India
DGCA maintenance facility approvals are multiplying in Bangalore and Hyderabad, opening aftermarket cabin retrofit demand for fire-resistant honeycomb panels. The country's national aviation regulator is expanding MRO certification capacity to capture regional narrow-body refurbishment programs. Local panel laminators are qualifying thermoplastic alternatives to serve Airbus and Boeing supply chains seeking cost-competitive secondary sourcing.
Honeycomb Sandwich Panels Market Competitive Landscape
German producers anchor one tier; North American specialists hold aerospace certification advantages. The vendor base splits between consolidated aerospace-grade suppliers and fragmented automotive entrants. Three archetypes dominate: legacy aluminum core manufacturers with FAA/EASA lock-in, continuous thermoplastic extrusion specialists, and diversified composites conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines freeze out new entrants from retrofit markets.
Among Germany-based fabricators, Schütz GmbH & Co. KGaA exemplifies the transportation-focused archetype through its glass-reinforced polypropylene core technology. Hexcel Corporation occupies a position within the aerospace-certification tier, representing North American carbon fiber honeycomb supply. EconCore N.V. sits within the thermoplastic innovation segment, exemplifying continuous extrusion capabilities that automate cost parity with aluminum alternatives.
| Leading Market Players |
|---|
| Arconic |
| Schütz GmbH & Co. KGaA |
| Hexcel Corporation |
| Pacific Panels Inc |
| EconCore N.V. |
| 3A Composites GmbH |
| Alucoil |
| Hunter Douglas |
| Plascore, Inc. |
| Others |
Supply & Pricing Matrix
Aramid fiber feedstock costs cascade through aerospace-grade Nomex core production into three-tier pricing structures across premium, standard, and economy levels, with REACH-compliant adhesive reformulations in Germany and Belgium compressing margins for European laminators serving Airbus and Embraer programs.
Pricing Analysis
Distributor margins for aerospace-certified honeycomb panels run 12-18 percent above automotive-grade equivalents, with price differentiation driven by FAA/EASA certification tier and volume scale. Cost compression in thermoplastic segments is intensifying because continuous extrusion lines in Belgium and China automate cell formation without adhesive lamination. Automotive OEMs exhibit highest price sensitivity, while commercial aviation MRO facilities absorb premiums for fire-resistant cabin retrofit materials.
Supply Chain Analysis
Domestic-content mandates under China's MIIT safety protocols and India's PLI scheme for advanced materials are reshaping sourcing, pressuring foreign suppliers to localize extrusion capacity. Raw material dependencies draw from petrochemical feedstocks for polypropylene cores, aluminum billet for aerospace grades, and glass fiber rovings for facade applications. Single-source vulnerability clusters around Schütz GmbH's continuous extrusion capacity in Germany. Distribution runs through Tier-1 laminators holding direct OEM contracts rather than spot-market commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH adhesive restrictions in Europe accelerate thermoplastic adoption costs 15-20 percent above comparable aluminum configurations in jurisdictions without circular-economy mandates.
For Market Incumbents: Anchor aerospace certification advantages through FAA Parts Manufacturer Approval investments that freeze out thermoplastic entrants from retrofit markets for 18-24 months. Defend against continuous extrusion specialists by acquiring Belgian or Chinese thermoplastic welding capability before qualification timelines compress. Prioritize backward integration into aramid fiber supply to buffer Nomex cost volatility.
For New Entrants and Emerging Players: Continuous thermoplastic honeycomb extrusion technology offers a technology-first wedge into automotive battery enclosure contracts where UN ECE R100 testing requirements have not yet locked in incumbent suppliers. Target Indian MRO facilities in Bangalore and Hyderabad where DGCA approvals are multiplying faster than qualified domestic panel laminators. Pursue EIC Accelerator funding for recyclable core development to offset European R&D cost recovery.
For Investors and Strategic Acquirers: Roll-up economics work for regional panel laminators with dormant FAA/EASA certifications because airline procurement consolidation around full-service integrators displaces component vendors from direct OEM relationships, creating distressed acquisition targets. Monitor DGCA maintenance facility approval velocity as the inflection signal for aftermarket cabin retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Thermoplastic Extrusion Scale-Up | Automates cost parity with aluminum cores above 500,000 square meters annual volume in Jiangsu and Guangdong. |
| FAA/EASA Certification Investment | Locks qualified suppliers into long-term commercial aviation contracts under CS-25 flammability mandates. |
| Backward Integration into Aramid Supply | Captive fiber sourcing buffers petrochemical feedstock volatility compressing tier-two laminator margins. |
| Indian MRO Facility Partnership | DGCA approvals in Bangalore and Hyderabad open aftermarket retrofit demand outside OEM procurement chains. |
| REACH-Compliant Adhesive Reformulation | SVHC restrictions on epoxy hardeners force bonding system requalification extending product development cycles. |
Research Methodology
Multiple input streams — primary interviews with aerospace procurement officers, automotive Tier-1 supplier engineers, and facade system architects; secondary validation through FAA airworthiness directives, EASA CS-25 certification databases, and EU Green Deal circular-economy disclosures; plus customs and trade flow data from German, Chinese, and Belgian port authorities — were reconciled through bottom-up and top-down triangulation.
Historical production capacity utilization was cross-referenced against panel input from laminators and extrusion equipment operators across the analysis window. Segmentation dimensions modeled include material type, end-use industry, application location, and technical specification tier. CAGRs were derived from slope analysis of normalized shipment volumes against macroeconomic drivers including aviation fuel-efficiency mandates and electric vehicle battery safety regulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aramid fiber price volatility, REACH chemical restriction expansion, and FAA certification timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Floor Screeds Market