
 North America Prefabricated Housing Market | 2026-2036
North America Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Prefabricated Housing Market Analytics
Multi-source procurement from specialized factory networks is decoupling from traditional site-built subcontracting in the North American residential construction supply chain. Clayton Homes leverages captive manufacturing scale across dozens of production facilities to control cost curves in the manufactured housing tier. Skyline Champion Corporation anchors its position through vertical integration into retail distribution, capturing margin pools that independent dealers once held. Cavco Industries specializes in regional product configurations tailored to wind-load and thermal codes across distinct climate zones.
Prefabricated housing comprises dwelling units produced in factory-controlled settings, transported to sites in modules or panels, and assembled on permanent foundations with structural connections meeting local building codes; wall assemblies typically achieve R-values between R-21 and R-30 through integrated insulation and air-sealing protocols. Modular homes occupy the highest-value tier within factory-built construction, commanding price premiums over manufactured units due to compliance with state and municipal codes rather than federal HUD standards. Panelized homes compete on customization flexibility, allowing field modifications that pure modular systems restrict. Steel frame technology leads in multi-story and commercial-adjacent applications where fire ratings and span requirements exceed wood capabilities.
The U.S. Department of Housing and Urban Development administers the federal manufactured housing construction and safety standards that govern roughly one-third of factory-built units, while state modular programs in California, Texas, and Florida impose supplementary structural and energy requirements that filter market access. The EPA Energy Star certification and DOE Zero Energy Ready Home standards are reshaping product specifications as utilities and municipalities tie incentive eligibility to performance thresholds. Stakeholders must monitor evolving code harmonization efforts between federal HUD and state modular programs, as regulatory fragmentation continues to dictate factory certification investments and geographic market entry decisions.
Market Dynamics
Workforce housing mandates across southwestern states and Ontario are compressing traditional site-built timelines, forcing developers toward factory-controlled production environments where labor availability and material costs stabilize procurement decisions.
Growth Catalysts
- California modular construction incentives:State-level tax credits and streamlined permitting for factory-built units accelerate developer adoption in high-cost coastal metros where conventional construction faces severe labor constraints.
- Cross-laminated timber (CLT) integration:Engineered wood panels reduce on-site framing duration by half while meeting seismic and fire ratings that expand modular eligibility into mid-rise residential applications.
- Texas workforce housing pipeline:Oilfield and logistics corridor expansion generates concentrated demand for rapid-deployment manufactured units serving transient worker populations.
Market Restraints
- OSB and dimensional lumber cost volatility:Commodity price swings of 40% within single quarters destabilize factory quoting mechanisms and erode margin predictability for fixed-bid projects.
- Transportation radius limitations:Module width restrictions on interstate highways constrain factory service territories to roughly 500-mile radii, fragmenting production scale advantages across dispersed regional markets.
- Federal HUD and state modular code misalignment:Dual certification requirements force manufacturers to maintain parallel compliance systems, inflating overhead for multi-jurisdictional operators.
Strategic Opportunities
- DOE Zero Energy Ready Home standards:Federal performance thresholds unlock utility rebate stacking and municipal density bonuses that command 15% price premiums in incentive-rich jurisdictions.
- Panelized systems for infill urban sites:Crane-accessible narrow lots in Toronto and Vancouver favor panel delivery over module constraints, opening customization-flexible market segments.
- Steel frame convergence with fire-rated assemblies:Hybrid structural systems penetrate multi-story affordable housing and student residence verticals where wood span limitations exclude pure modular solutions.
Industry Challenges
- Certified modular inspector scarcity:State-licensed third-party plan review and site inspection bottlenecks extend project timelines by 8-12 weeks in jurisdictions with understaffed building departments.
- Foundation-to-module tolerance alignment:Precision requirements for crane-set modules demand survey-grade site preparation that many regional contractors lack equipment to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Prefabricated Housing Market |
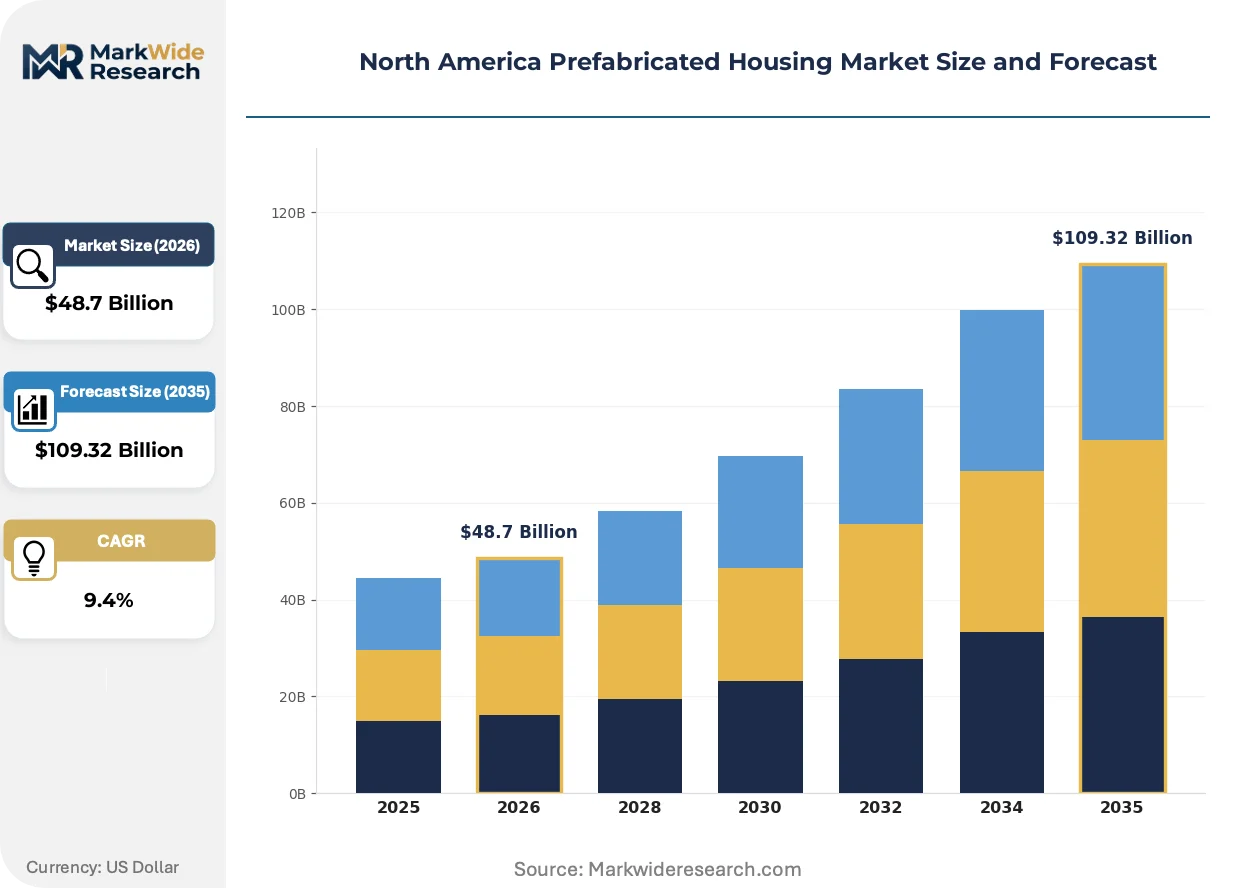
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-cut Homes, Hybrid Homes End User: Residential Developers, Homeowners, Investors, Contractors Technology: Wood Frame, Steel Frame, Concrete Frame, Eco-friendly Materials Distribution Channel: Direct Sales, Online Platforms, Retail Outlets, Wholesalers |
| Companies Covered | Clayton Homes, Skyline Champion Corporation, Cavco Industries, Champion Home Builders, Ritz-Craft Corporation, Guerdon Modular Buildings, FullStack Modular, Legacy Housing, Sekisui House, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Prefabricated Housing Market Evolving Landscape
Digital fabrication and performance-based certification are compressing the gap between factory-built and site-built quality perceptions while expanding the addressable market for controlled-environment construction.
Building information modeling (BIM) integration with CNC routing equipment is rewriting production economics in panelized and modular factories. Multi-family developers in Seattle and Denver now specify BIM-to-field workflows that eliminate dimensional conflicts before modules ship. The technology is rewriting risk allocation in design-build contracts by transferring liability for field-fit errors from general contractors to factory engineers.
The EPA Energy Star certification and companion DOE Zero Energy Ready Home standards are tightening thermal envelope specifications across factory-built production. Manufacturers serving California and Ontario must now integrate continuous insulation and advanced air-sealing protocols that add $8,000-$12,000 per unit in material costs. The Pacific Northwest and New England markets show strongest compliance response, with factory production lines retooled for triple-pane glazing and heat-recovery ventilation as standard specifications.
Institutional buyers including university housing authorities and municipal housing authorities are consolidating procurement through master service agreements that displace fragmented dealer networks. These multi-year volume commitments concentrate factory capacity allocation and squeeze independent retail channels in Texas and Florida where institutional penetration lags. The shift concentrates pricing power with buyers holding portfolio-scale deployment schedules.
North America Prefabricated Housing Market Segmentation
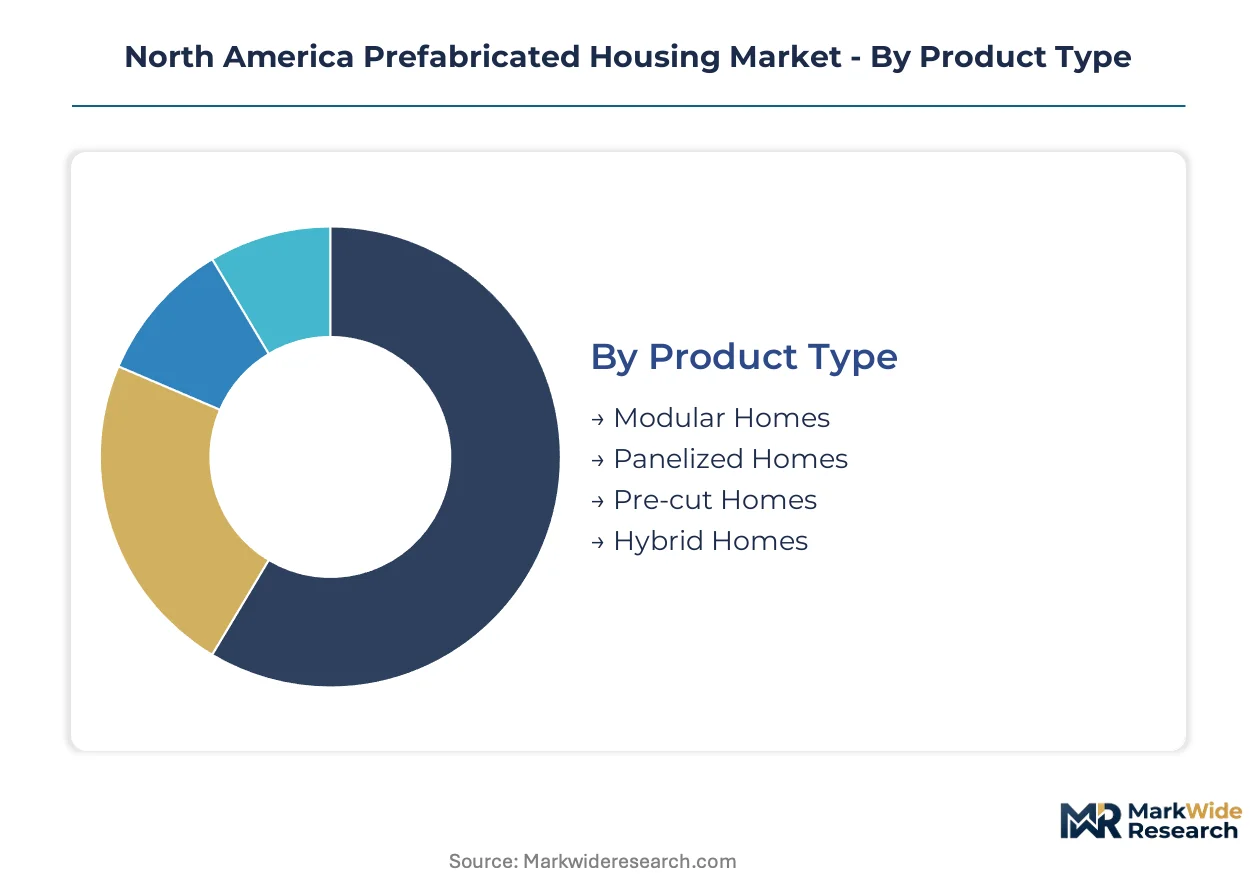
Prefabricated housing segmentation reveals how factory production methods, material specifications, and procurement channels reshape competitive positioning across distinct customer workflows. Understanding these boundaries clarifies where standardization economies clash with customization premiums.
Product Type:
Structural completeness at the factory gate distinguishes volume tiers and code compliance obligations across the North American market.
- Modular Homes:Fully enclosed three-dimensional modules arrive with interior finishes, MEP rough-ins, and fenestration complete. California and Ontario developers specify these for mid-rise workforce housing where local code compliance eliminates manufactured housing eligibility. Premium positioning reflects state-level modular certification overhead versus federal HUD standards.
- Panelized Homes:Wall, floor, and roof assemblies ship flat-packed for crane-assisted field erection. Toronto and Vancouver infill projects favor panel delivery where narrow lot access excludes module transport. Customization flexibility attracts architect-driven single-family clients seeking design control unavailable in pure modular systems.
- Pre-cut Homes:Dimensionally precise framing packages arrive with CNC-cut lumber and pre-assembled trusses. Remote Canadian markets and rural Texas counties use these where skilled framing labor scarcity extends site-built timelines.
- Hybrid Homes:Mixed-modality systems combine volumetric bathroom/kitchen pods with panelized shell construction. Student housing developers in Denver and Seattle deploy hybrid configurations to balance repetition economies with unit-type variation.
Mature deployment sits with Panelized Homes. Newer deployment is concentrated in Hybrid Homes.
End User:
Procurement scale and hold period duration separate pricing power and specification authority across demand channels.
- Residential Developers:Multi-unit project sponsors in Texas oilfield corridors and southwestern states negotiate master service agreements locking factory capacity. Volume commitments extract 8-12% price discounts and priority production scheduling unavailable to fragmented buyers.
- Homeowners:Individual purchasers through retail dealer networks or direct-to-consumer platforms. California coastal metros show strongest uptake where conventional construction costs and timelines deter site-built alternatives.
- Investors:Portfolio-scale buyers including REITs and institutional housing funds. University housing authorities in the Pacific Northwest consolidate procurement through multi-year agreements displacing traditional dealer intermediaries.
- Contractors:General contractors serving as specification agents for land-owning clients. Panelized systems dominate this channel where field modification tolerance aligns with contractor risk preferences.
Volume concentrates with Residential Developers. Margin capture is shifting toward Investors.
Technology:
Structural material selection governs span capability, fire rating, and climate-zone eligibility across code jurisdictions.
- Wood Frame:Dimensional lumber and engineered wood products dominate single-family and low-rise multi-family production. Cross-laminated timber integration is climbing the fastest in Seattle and Denver mid-rise applications where seismic and fire ratings expand modular eligibility.
- Steel Frame:Cold-formed steel assemblies penetrate multi-story affordable housing and student residences where wood span limitations and fire rating requirements exclude pure wood solutions. Texas and Florida show concentrated adoption for workforce housing durability.
- Concrete Frame:Precast concrete modules serve hurricane-rated coastal zones and sound-attenuation-critical urban infill. Premium positioning reflects transport weight penalties and foundation engineering complexity.
- Eco-friendly Materials:Bio-based insulation, reclaimed structural elements, and low-carbon concrete alternatives. California and Ontario incentive programs drive specification where Energy Star and DOE Zero Energy Ready Home certification unlocks rebate stacking.
Cost efficiency anchors Wood Frame deployment. Regulatory pressure is accelerating Eco-friendly Materials specification.
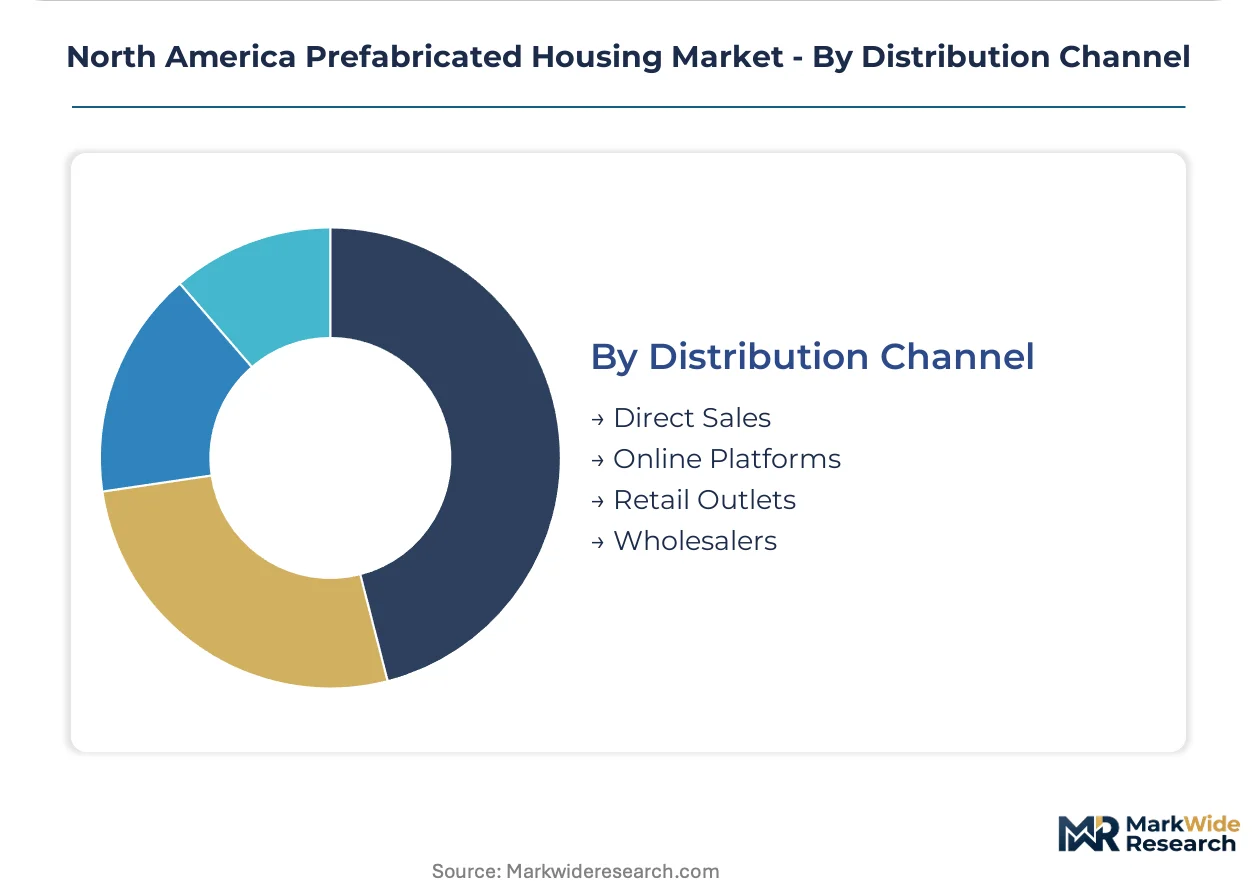
Distribution Channel:
Channel structure determines margin allocation between factory, intermediary, and site-assembly stakeholders.
- Direct Sales:Factory-to-developer relationships bypassing dealer networks. Institutional buyers in Texas and Florida consolidate procurement through this channel, concentrating pricing power with volume-holding purchasers.
- Online Platforms:Digital configuration tools with remote design consultation and transparent pricing. Homeowner segments in California coastal metros show strongest platform adoption where information asymmetry historically favored dealer intermediaries.
- Retail Outlets:Physical display centers with model home walkthroughs and financing packaging. Skyline Champion Corporation's captive retail network exemplifies margin capture from independent dealers in manufactured housing tiers.
- Wholesalers:Regional distributors aggregating small-contractor demand. Panelized systems flow through this channel where contractor-specified modifications require local technical support.
Margin compression is concentrating in Retail Outlets. Channel expansion is climbing the fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern yellow pine forests and Pacific Northwest timberlands anchor factory feedstock access across the North American prefabricated housing corridor. Controlled-environment manufacturing clusters concentrate near these resource bases to minimize dimensional lumber transport costs. State-level modular incentives and federal HUD code administration create divergent regulatory environments that reshape sub-regional competitive positioning.
United States
Texas oilfield corridor expansion and California coastal workforce housing mandates generate concentrated factory demand. HUD administers federal manufactured housing standards while California's SB 9 density bonuses and streamlined modular permitting accelerate developer adoption. Factory production concentrates in the Dallas-Fort Worth metroplex where Clayton Homes and Cavco Industries operate multi-facility manufacturing networks serving southwestern states.
Canada
Ontario's Golden Horseshoe labor shortages and British Columbia's timber cost volatility push residential developers toward panelized and modular alternatives. The National Building Code of Canada harmonizes with provincial modular programs in Ontario and British Columbia that exceed federal energy efficiency baselines. Toronto's narrow-lot infill projects favor crane-accessible panel delivery over module constraints, opening customization-flexible market segments for regional fabricators.
Mexico
Maquiladora corridor workforce expansion and northern border state logistics growth generate demand for rapid-deployment manufactured units. Mexico's federal housing agency INFONAVIT channels financing toward certified factory-built products meeting seismic and thermal standards. Manufacturing activity concentrates in Nuevo León and Baja California where cross-border supply chains integrate with Texas and California factory networks.
California
Coastal metro construction cost premiums and severe skilled labor constraints compress site-built timelines toward factory alternatives. The California Department of Housing and Community Development administers state modular construction incentives including tax credits and expedited plan review. Factory production clusters in the Central Valley where land costs and highway access optimize module transport radius economics for Los Angeles and Bay Area delivery.
Texas
Permian Basin energy sector workforce housing and logistics corridor expansion drive manufactured unit procurement at scale. The Texas Department of Housing and Community Affairs coordinates with federal HUD standards while maintaining state-specific wind-load and thermal requirements for modular eligibility. Production concentrates in the I-35 corridor from Dallas to San Antonio where factory networks serve oilfield, agricultural, and border housing demand.
North America Prefabricated Housing Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale factory footprints to capture workforce housing procurement volume. The vendor base organizes around three structural tiers: national-scale integrated producers controlling captive manufacturing and distribution networks, regional specialists configuring products for climate-specific code requirements, and technology-forward entrants deploying digital fabrication workflows. Strategic archetypes include vertically integrated volume leaders, code-specialization regionalists, and BIM-enabled precision fabricators. Competitive intensity concentrates in manufacturing scale races and retail channel consolidation moves.
Among national-scale integrated producers, Clayton Homes, Skyline Champion Corporation, and Cavco Industries exemplify divergent strategic positioning. Clayton Homes anchors the manufactured housing tier through captive manufacturing scale across dozens of production facilities. Skyline Champion Corporation occupies a position emphasizing retail distribution integration. Cavco Industries represents regional product configuration specialization tailored to distinct climate zones and code jurisdictions.
| Leading Market Players |
|---|
| Clayton Homes |
| Skyline Champion Corporation |
| Cavco Industries |
| Champion Home Builders |
| Ritz-Craft Corporation |
| Guerdon Modular Buildings |
| FullStack Modular |
| Legacy Housing |
| Sekisui House |
| Others |
Value Network & Pricing Analysis
Institutional buyers including university housing authorities and municipal housing agencies concentrate procurement through master service agreements, locking factory capacity and compressing margin capture for fragmented retail channels. This buyer-archetype consolidation rewards volume-commitment pricing models while squeezing independent dealers serving individual homeowners.
Pricing Analysis
Warranty and installation-service bundling separates modular home pricing tiers, with turnkey foundation-to-finish packages commanding premiums over transport-only arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects DOE Zero Energy Ready Home certification status, volume scale, and geographic delivery radius. Pricing pressure stems from OSB and dimensional lumber commodity volatility destabilizing factory quoting mechanisms. Residential developers exhibit lowest price sensitivity due to locked capacity agreements, while individual homeowners through retail channels face highest cost elasticity.
Supply Chain Analysis
Domestic-content mandates including California's SB 9 local-hiring provisions and Ontario's Buy Local procurement rules reshape sourcing toward North American timber and steel suppliers. Factory production draws from southern yellow pine forests in the United States and Pacific Northwest timberlands, with steel frame inputs anchored in Great Lakes manufacturing corridors. Single-source vulnerability concentrates in engineered wood product supply where CLT production capacity lags demand growth. Distribution runs through captive retail networks, direct factory-to-developer relationships, and emerging digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory capacity constraints across Clayton Homes and Skyline Champion Corporation production networks prop pricing power, creating supply-constrained conditions favoring incumbent margin defense.
For Market Incumbents: Deepen backward integration into engineered wood product supply to buffer CLT cost volatility and capture margin pools currently held by third-party suppliers. Expand certified modular inspector training programs internally to circumvent state-licensed third-party bottlenecks extending project timelines. Prioritize DOE Zero Energy Ready Home certification investment to unlock utility rebate stacking and municipal density bonus eligibility. For New Entrants and Emerging Players: Enter via panelized system specialization for Toronto and Vancouver narrow-lot infill projects where module transport constraints exclude incumbent modular competitors. Target crane-accessible urban sites favoring customization-flexible delivery over pure modular rigidity. Deploy BIM-to-field workflow capabilities as differentiated go-to-market positioning for multi-family developers in Seattle and Denver. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional panelized fabricators with established Ontario and British Columbia code certifications during lumber cost volatility windows. Long-term viability centers on factory networks with multi-jurisdictional compliance systems spanning federal HUD and state modular programs. Watch cross-laminated timber production capacity expansion as inflection signal for mid-rise modular eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Clayton Homes multi-facility manufacturing networks capture southwestern workforce housing procurement volume. |
| Backward Integration | Captive engineered wood product supply buffers margin erosion from OSB commodity price swings. |
| Certification Investment | DOE Zero Energy Ready Home standards unlock California density bonuses and utility rebate stacking. |
| Channel Consolidation | Skyline Champion retail network displacement of independent dealers captures margin pools in manufactured housing tiers. |
| Technology Licensing | BIM-to-field workflow partnerships transfer field-fit liability from general contractors to factory engineers. |
Research Methodology
Document review covered HUD code filings, state modular program registrations, EPA Energy Star certification databases, and DOE Zero Energy Ready Home compliance records, complemented by interviews with residential development executives, factory operations managers, municipal housing authority procurement directors, and third-party modular inspectors. Secondary validation drew from customs and trade data, SEC 10-K disclosures of publicly traded manufacturers, and National Building Code of Canada harmonization documents. Bottom-up unit shipment tallies triangulated against top-down construction spending allocations.
Segmented outputs across product type, end user, technology, and distribution channel dimensions were generated over the projection horizon. CAGRs were derived from regression analysis of historical shipment velocity against housing start correlations and workforce housing mandate implementation timelines. Model inputs incorporated cross-laminated timber adoption curves, state-level modular incentive program enrollment, and institutional buyer procurement consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged lumber commodity volatility or accelerated HUD-state modular code harmonization. Projections reflect assumptions regarding labor availability stabilization and transportation radius economics holding constant. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
US Residential Remodeling Market
Residential Construction
Swimming Pool Construction Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
UK Residential Construction Market
Residential Construction
US Residential Construction Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Siding Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Prefabricated Homes Market