
 Global Metal Cladding Market | 2026-2036
Global Metal Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Cladding Market Foresight
Aluminum is repositioning product economics across the Global Metal Cladding Market as architects substitute heavier steel systems for lightweight, corrosion-resistant facade assemblies in high-rise construction. ArcelorMittal Construction leverages its integrated steelmaking and coating capabilities to supply pre-finished cladding substrates at scale across European infrastructure projects. Tata Steel Limited anchors its competitive stance through deep vertical integration into color-coated steel production for industrial and commercial envelopes. Alcoa Corporation specializes in rolled aluminum products engineered specifically for architectural panel systems, competing on alloy formulation and surface finish consistency.
Metal cladding comprises factory-formed sheet or panel systems—typically aluminum, steel, copper, zinc, or titanium alloys ranging from 0.4 mm to 2.0 mm in thickness—mechanically attached to building exteriors to provide weather protection, thermal insulation integration, and aesthetic finish. Manufacturers produce these systems through continuous roll-forming, brake-pressing, or composite lamination processes, with specification governed by ASTM E330 structural performance standards and EN 508 weathering classifications. Aluminum and stainless steel product types command the largest installed base due to their strength-to-weight ratios and low maintenance profiles, while titanium and zinc segments attract premium specification in cultural centers and landmark commercial facades where patina development and extended service life justify higher material costs. Application demand from transportation hubs and sports venues represents the fastest-growing structural pocket, driven by large-span envelope requirements and accelerated construction timelines favoring prefabricated panel systems.
The EU Green Deal and REACH chemical compliance frameworks are tightening embodied carbon disclosure requirements for construction materials sold across member states, directly influencing cladding specification through Environmental Product Declaration mandates. The EPA's industrial emissions standards and China's dual carbon goals from MEE are similarly pressuring steel and aluminum smelters to decarbonize feedstock supply, reshaping cost structures for substrate producers. China's GB standards for building energy efficiency and the EU AI Act's emerging requirements for automated facade inspection systems will further complicate compliance architecture. Stakeholders must monitor regulatory divergence between jurisdictions to avoid specification mismatches that strand inventory or disqualify bids.
Market Dynamics
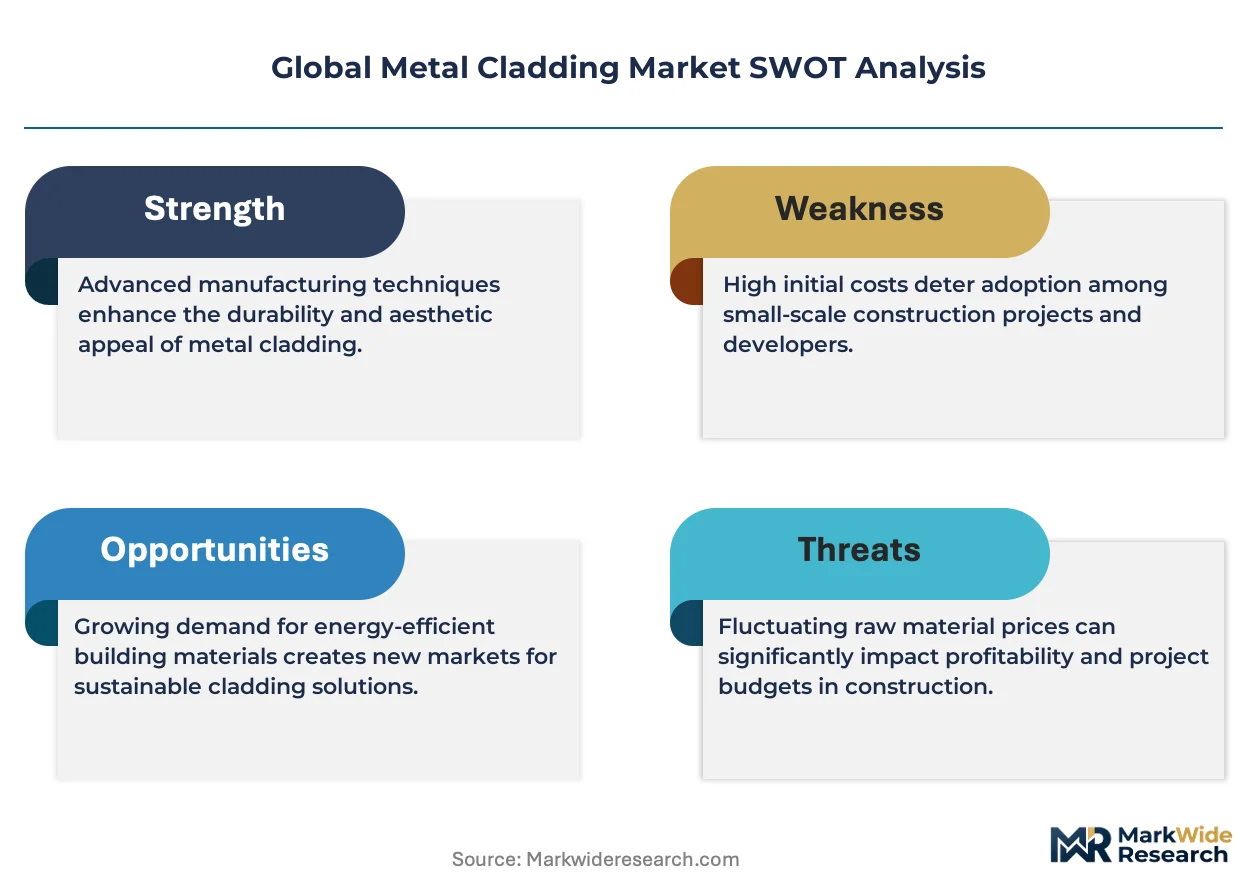
Embodied carbon disclosure mandates are compressing specification windows across the Global Metal Cladding Market, forcing substrate producers to decarbonize supply chains or lose qualification on major commercial and infrastructure tenders.
Growth Catalysts
- EU Green Deal thresholds:Mandatory Environmental Product Declarations for construction materials sold across member states redirect procurement toward lower-carbon steel and recycled aluminum substrates.
- Urban density intensification:High-rise construction in Germany, China, and the United States concentrates demand for lightweight aluminum composite facade systems that reduce structural load.
- Prefabrication acceleration:Continuous roll-forming and composite lamination processes compress installation timelines for transportation hubs and sports venues requiring large-span envelopes.
Market Restraints
- Aluminum smelting energy intensity:China's dual carbon goals from MEE and EPA industrial emissions standards simultaneously pressure feedstock costs and supply availability.
- REACH chemical compliance:Coating formulation restrictions limit surface finish options for European projects, constraining aesthetic differentiation.
- Steel substrate concentration:Integrated mill dominance in specific geographies creates vulnerability to regional carbon pricing volatility and trade barrier exposure.
Strategic Opportunities
- India building energy code expansion:BIS standards adoption and urban infrastructure investment open specification channels for color-coated steel in commercial envelopes.
- Automated facade inspection convergence:EU AI Act requirements for building envelope monitoring systems create bundled hardware-software service models.
- Recycled aluminum alloy development:Post-consumer scrap integration into architectural panel systems satisfies circular procurement mandates without performance degradation.
Industry Challenges
- Multi-jurisdiction certification complexity:ASTM E330 structural performance standards and EN 508 weathering classifications require parallel testing protocols that extend product qualification timelines.
- Coating chemistry reformulation:Elimination of legacy solvent-based systems demands R&D investment and production line retooling without immediate price recovery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Cladding Market |
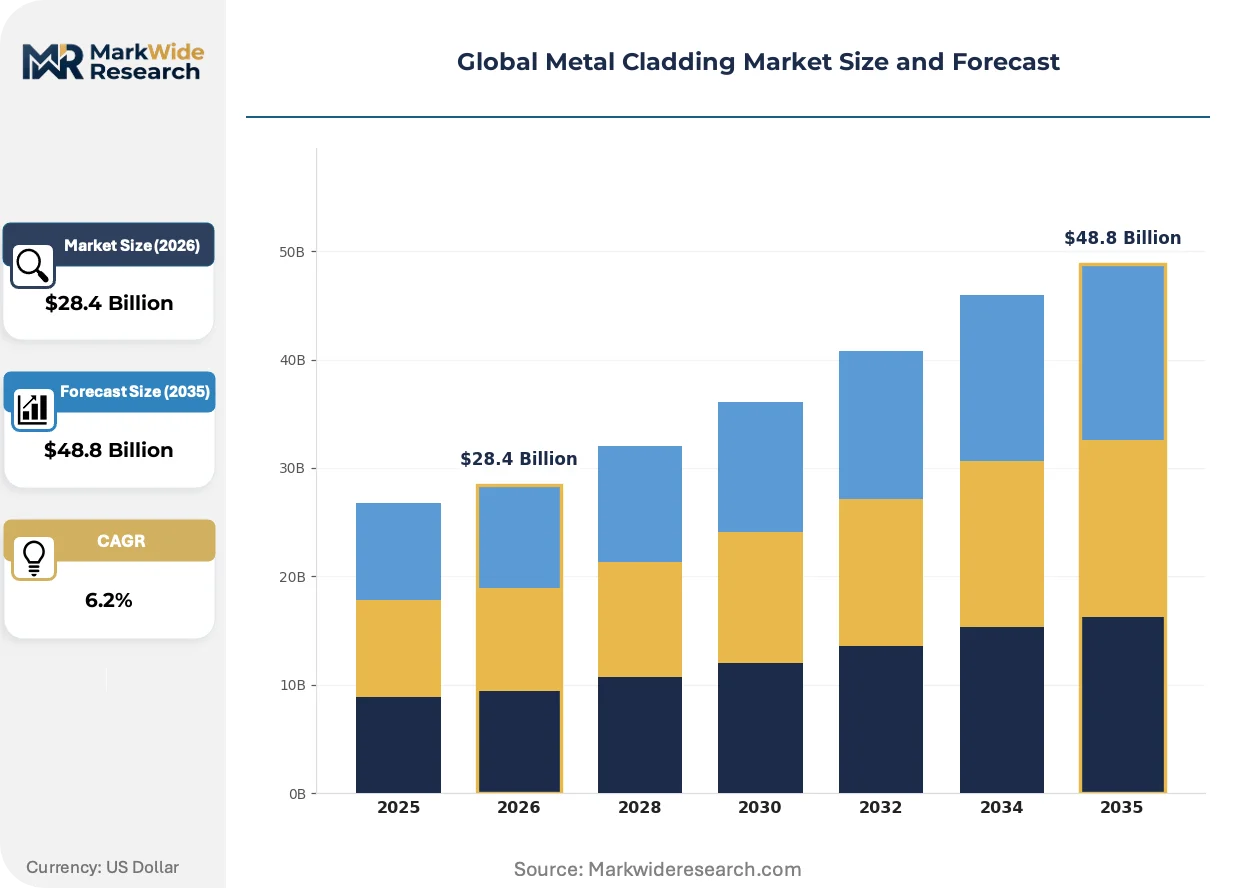
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Stainless Steel, Copper, Zinc, Titanium, Galvanized Steel Application: Commercial Buildings, Industrial Facilities, Educational Institutions, Transportation Hubs, Cultural Centers, Sports Venues Installation Type: New Construction, Renovation Projects, Prefabricated Panels, On-site Fabrication End User: Construction Contractors, Architectural Firms, Building Owners, Facility Managers |
| Companies Covered | Tata Steel Limited, Kobe Steel Ltd., Compagnie de Saint-Gobain S.A., ArcelorMittal Construction, Alcoa Corporation, Nippon Steel & Sumitomo Metal Corporation, Hindalco Industries Limited, Alucoil, JFE Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Cladding Market Shifts & Advancements
Specification workflows are digitizing across architectural and engineering practices, compressing the window between design intent and substrate procurement while embedding compliance verification earlier in project timelines.
Photovoltaic-integrated metal cladding is consolidating building envelope functions into unified systems that generate renewable energy while providing weather protection. Commercial developers in Germany and the Netherlands specify these assemblies to meet net-zero operational targets. The technology is consolidating separate trades—electrical, roofing, and facade—into single-source procurement packages that reduce interface risk.
REACH chemical compliance frameworks are tightening disclosure requirements for coating constituents used in architectural applications. Manufacturers must reformulate pre-finished steel and aluminum substrates to eliminate restricted substances or face market exclusion across EU member states. German industrial building projects now require full material passports that trace substrate origin through smelting, rolling, and coating stages.
Design-assist contracting is replacing traditional bid-specify sequences for complex facade projects. Architects in the United States and United Kingdom engage cladding specialists during schematic design to validate constructability and cost parameters before documentation finalization. Transportation hub developments in China and airport expansions across the Middle East demonstrate this pattern most visibly, with single-source accountability reducing change-order exposure on accelerated construction schedules.
Global Metal Cladding Market Segmentation
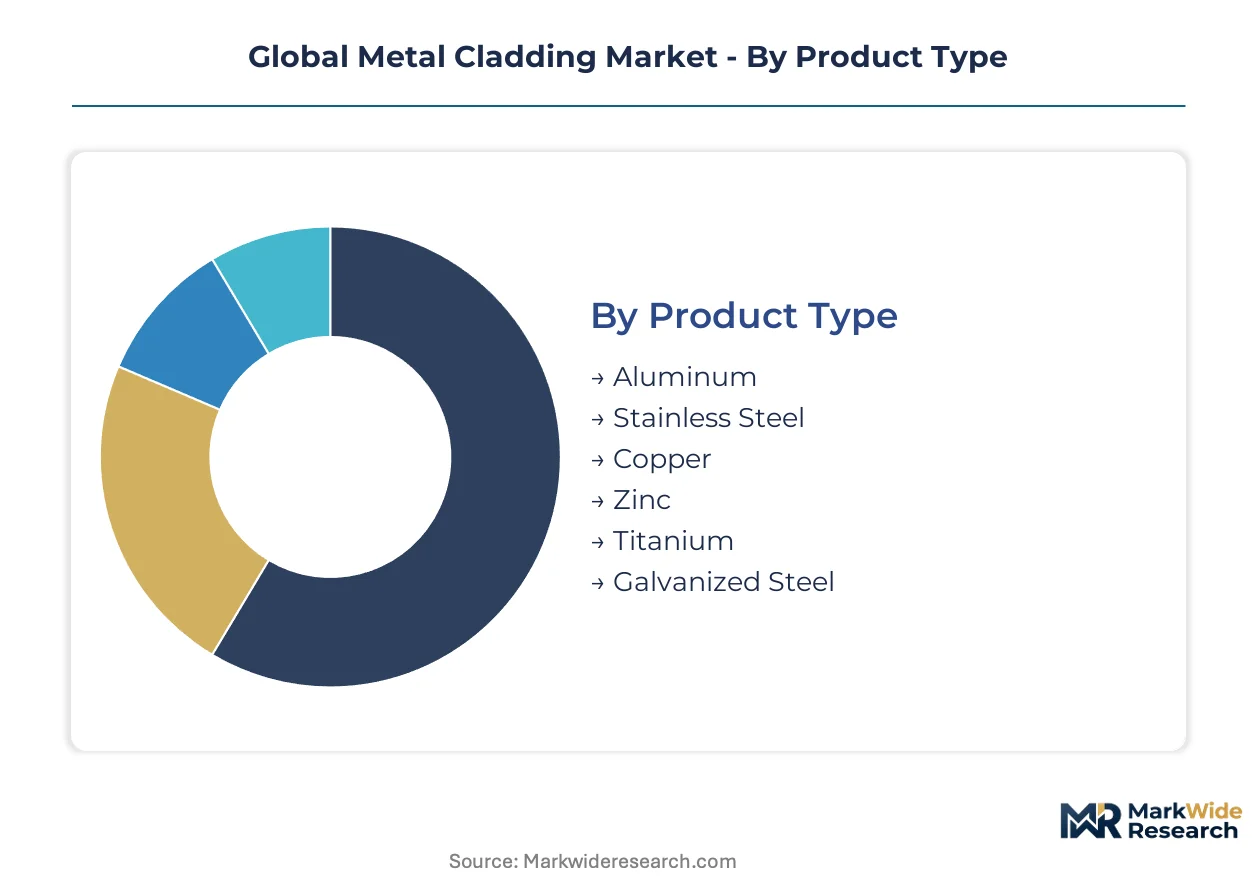
Metal cladding procurement splits across substrate chemistry, building typology, installation methodology, and buyer sophistication. Specification patterns diverge sharply between new high-rise construction and facade retrofit cycles, with each segment demanding distinct performance certifications and supply chain configurations.
Product Type:
Upgrade cycles favor lighter alloys that reduce structural load while extending envelope service life, displacing legacy steel specifications in vertical construction.
- Aluminum:Rolled alloy sheets and composite laminates deliver strength-to-weight ratios critical for high-rise curtain walls. German and Chinese developers specify these systems to meet stringent energy code thermal bridging requirements.
- Stainless Steel:Austenitic grades resist chloride corrosion in coastal and industrial atmospheres without surface coating maintenance. Transportation hubs in the Netherlands and airport terminals across the United States deploy these substrates for 50-year design life targets.
- Copper:Natural patina formation provides distinctive aesthetic aging for cultural institutions.
- Zinc:Low melting point enables complex seam geometries for heritage building restoration.
- Titanium:Exceptional durability commands premium specification in landmark facades.
- Galvanized Steel:Cost-positioned substrate dominates industrial warehouse envelopes.
Aluminum sits at the top of the volume ranking, with titanium climbing the fastest.
Application:
Building typology determines fire rating requirements, panel span capabilities, and aesthetic finish specifications.
- Commercial Buildings:Office towers and mixed-use developments specify aluminum composite systems with integrated thermal breaks. Projects in Frankfurt and Shanghai prioritize LEED certification compatibility through high-recycled-content substrates.
- Transportation Hubs:Airports and rail terminals demand large-format panels with accelerated installation protocols. Prefabricated cassette systems reduce site labor in Dubai and Singapore megaprojects.
- Industrial Facilities:Corrosion-resistant coatings protect against chemical exposure in manufacturing plants.
- Educational Institutions:Vandal-resistant surfaces and acoustic dampening drive specification.
- Cultural Centers:Custom patina and artisan finishes justify extended procurement timelines.
- Sports Venues:Tensile roof integration and crowd-facing durability requirements shape panel engineering.
Commercial Buildings capture the dominant revenue share, while Transportation Hubs gain share fastest.
Installation Type:
Project delivery methodology constrains substrate sourcing windows and fabrication quality control protocols.
- Prefabricated Panels:Factory-controlled conditions ensure consistent coating adhesion and dimensional tolerance. Dutch and Japanese contractors specify unitized systems to compress envelope installation schedules by 40 percent.
- New Construction:Design-build contracts enable early cladding specialist involvement for constructability optimization.
- Renovation Projects:Existing structural capacity limits drive lightweight aluminum substitution.
- On-site Fabrication:Complex geometries and heritage matching require brake-pressing at project location.
Prefabricated Panels lead installation methodology adoption, with Renovation Projects expanding most quickly.
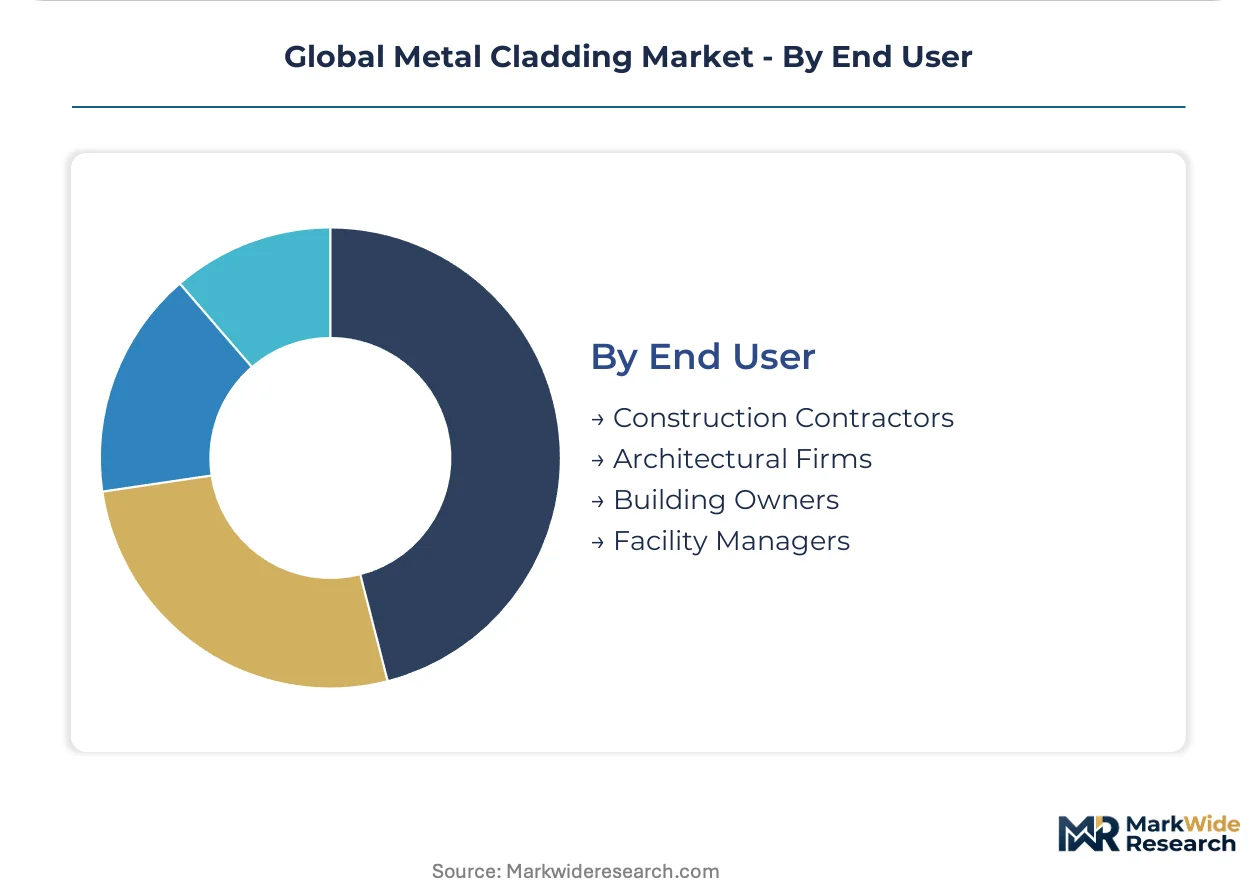
End User:
Procurement authority concentration varies by contract structure and asset ownership model.
- Construction Contractors:Design-build and EPC firms control specification through package procurement. German contractors bundle cladding with MEP systems to optimize interface coordination.
- Architectural Firms:Signature designers in London and New York mandate specific alloy grades and surface finishes.
- Building Owners:Institutional investors impose lifecycle cost criteria and embodied carbon thresholds.
- Facility Managers:Maintenance cost accountability drives warranty and service agreement negotiations.
Construction Contractors dominate specification authority, with Building Owners gaining influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor concentrates European metal cladding fabrication capacity, with German mills supplying pre-finished steel substrates across the continent. Chinese producers in the Yangtze River Delta dominate aluminum composite panel output for Asia-Pacific high-rise construction. North American demand centers on the Great Lakes manufacturing belt, where integrated steelmakers serve commercial envelope projects from Toronto to Chicago.
Germany
Frankfurt and Munich high-rise developments specify aluminum composite systems with integrated thermal breaks to meet stringent envelope energy codes. The EU Green Deal mandates Environmental Product Declarations for construction materials, redirecting procurement toward lower-carbon steel and recycled aluminum substrates. The Ruhr Valley industrial cluster hosts ArcelorMittal Construction facilities producing pre-finished cladding substrates at scale for European infrastructure tenders.
China
Shanghai and Shenzhen commercial towers drive specification of lightweight facade assemblies that reduce structural load in dense urban cores. The Ministry of Ecology and Environment's dual carbon goals pressure aluminum smelters to decarbonize feedstock supply, reshaping cost structures for substrate producers. The Yangtze River Delta manufacturing belt concentrates continuous roll-forming capacity serving transportation hub developments across the Asia-Pacific.
United States
New York and Chicago developers specify unitized panel systems to compress installation schedules on accelerated high-rise timelines. The EPA's industrial emissions standards constrain coating formulation options while tightening embodied carbon disclosure expectations for federal projects. The Great Lakes steel corridor supplies color-coated substrates for commercial envelope applications from Detroit to Milwaukee.
India
Mumbai and Bengaluru commercial construction expands specification channels for color-coated steel as building energy codes tighten across metropolitan jurisdictions. The Bureau of Indian Standards adoption of envelope performance criteria creates qualification pathways for pre-finished metal systems in institutional projects. The Gujarat industrial belt attracts cladding substrate fabrication investment serving infrastructure expansion in Delhi-Mumbai corridors.
United Arab Emirates
Dubai and Abu Dhabi airport expansions demand large-format prefabricated panels with accelerated installation protocols for megaproject delivery. The country's building codes increasingly reference EU weathering classification standards for facade material qualification. The Jebel Ali industrial zone concentrates composite lamination capacity serving Gulf Cooperation Council transportation and sports venue developments.
Global Metal Cladding Market Competitive Landscape
Global majors compete with regional champions across substrate chemistry and coating technology dimensions, producing a tiered structure where integrated steelmakers and aluminum specialists occupy distinct competitive positions. Market concentration varies by alloy type, with aluminum composite panels showing broader fragmentation than pre-finished steel. Three archetypes dominate: integrated primary metal producers with captive coating capacity, independent fabricators sourcing commodity substrates, and specialty composite laminators serving premium architectural segments. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as regulatory compliance tightens across jurisdictions.
Within the integrated producer tier, ArcelorMittal Construction and Tata Steel Limited exemplify the steel-backed archetype with in-house production of color-coated substrates for industrial and commercial envelopes. Alcoa Corporation occupies a position among aluminum specialists, with rolled product capabilities engineered for architectural panel systems. These three companies represent contrasting geographic footprints—European, Indian, and North American respectively—while competing on alloy formulation and surface finish consistency rather than scale alone.
| Leading Market Players |
|---|
| Tata Steel Limited |
| Kobe Steel Ltd. |
| Compagnie de Saint-Gobain S.A. |
| ArcelorMittal Construction |
| Alcoa Corporation |
| Nippon Steel & Sumitomo Metal Corporation |
| Hindalco Industries Limited |
| Alucoil |
| JFE Steel Corporation |
| Others |
Supply & Pricing Matrix
Continuous roll-forming specialists in the Yangtze River Delta command wage premiums that compress pricing spreads between standard and premium cladding tiers, forcing German and Indian producers to automate coating lines or cede mid-market share.
Pricing Analysis
Aluminum ingot and zinc coating costs pass through to buyers via quarterly contract adjustments, with Chinese mills absorbing volatility through state-backed energy subsidies unavailable to European competitors. Three-tier pricing structure across premium, standard, and economy levels separates titanium-clad cultural landmarks from aluminum composite high-rises and galvanized steel warehouses. Price erosion runs through the economy tier as Chinese overcapacity floods spot markets. Building owners with lifecycle cost mandates show least price sensitivity, while speculative commercial developers in India negotiate hardest on unit rates.
Supply Chain Analysis
Skilled brake-press operators and coating technicians concentrate in Germany's Ruhr Valley, China's Jiangsu province, and India's Gujarat belt, creating localized labor bottlenecks that constrain surge capacity. Primary aluminum draws from Chinese smelters, Australian bauxite, and Russian alumina, while color-coated steel feeds from ArcelorMittal's European integrated mills and Tata's Jamshedpur complex. Single-source vulnerability concentrates in Chinese aluminum composite panel output, where geopolitical friction threatens project timelines. Distribution runs through contractor-direct procurement for megaprojects and regional distributor networks for retrofit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Metal Cladding Market compounds regulatory tailwinds into structural demand shifts, with the EU Green Deal's EPD mandates disqualifying high-carbon substrates from public tenders worth billions in contract value.
For Market Incumbents: Hedge against coating chemistry obsolescence by securing REACH-compliant formulation patents before 2026 reformulation deadlines strand legacy inventory. ArcelorMittal and Tata Steel should deepen backward integration into scrap-recycled feedstock to defend margin position as carbon border adjustments bite. Captive coating capacity in low-energy-cost geographies becomes the critical lever as electricity differentials widen between European and Asian smelting. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for automated facade inspection hardware-software bundles that incumbent cladding makers cannot assemble without Silicon Valley partnerships. Target India's color-coated steel specification channels before BIS standards fully mature and foreign certification becomes mandatory. A design-assist contracting model, proven in Dubai airport expansions, offers the fastest go-to-market path for unknown brands seeking reference projects. For Investors and Strategic Acquirers: Building materials conglomerates are the most active acquirer in this space, seeking cladding capabilities to complete envelope-system portfolios. Five-to-ten-year viability hinges on circular economy positioning, with post-consumer scrap integration capabilities commanding acquisition premiums. Watch for MEE enforcement actions against Chinese aluminum smelters as the inflection signal for supply-driven price spikes in Asia-Pacific markets.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Aluminum Alloy Development | Post-consumer scrap integration satisfies EU Green Deal circular procurement mandates without performance degradation. |
| Automated Facade Inspection Convergence | EU AI Act requirements create bundled hardware-software service models for building envelope monitoring systems. |
| Coating Chemistry Reformulation | ECHA REACH restrictions demand R&D investment to eliminate legacy solvent-based systems from European specifications. |
| Design-Assist Contracting Expansion | Early cladding specialist involvement reduces change-order exposure on accelerated transportation hub schedules in China and the Middle East. |
| Prefabricated Panel Capacity Buildout | Factory-controlled conditions ensure coating adhesion consistency while compressing envelope installation timelines by 40 percent in Dutch and Japanese projects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facade engineers, coating chemists, procurement directors at German contractors, sustainability officers at Dutch developers, and technical directors at Indian steel mills with secondary validation against SEC filings, EU EPD registration databases, Chinese customs trade data, and ASTM certification records. Bottom-up project pipeline enumeration and top-down materials consumption estimates triangulated to cross-check volume assumptions.
Historical reference periods anchored the projection framework, with growth rates derived from elasticity modeling against construction output indices and energy code adoption curves across the analysis window. Segmentation dimensions included substrate chemistry, building typology, installation methodology, and buyer sophistication archetype. Forecast inputs incorporated smelter electricity cost differentials, REACH chemical restriction timelines, and BIS standards adoption trajectories.
Revisions become necessary when Chinese MEE enforcement intensity shifts, EU carbon border adjustment mechanisms expand coverage, or aluminum scrap availability constraints materialize. Practitioners should monitor EPD registration volumes, coating formulation patent filings, and German high-rise permitting data for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Materials Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Concrete and Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Italy Cement Market
Building Materials
Steel Slag Market
Building Materials
Africa Green Cement Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Long Steel Market
Building Materials
India Concealed Cistern Market
Building Materials
Brick Adhesive Market
Building Materials
China Architectural Coatings Market
Building Materials
Global Fiber Cement Siding Market