
 Timber Frames Market | 2026-2036
Timber Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Frames Market Outlook
Multi-family residential developers is rotating toward engineered timber frames as mid-rise construction codes modernize across North America and Europe. Stora Enso Oyj anchors its position through captive Nordic fiber supply and large-scale CLT manufacturing capacity. Binderholz GmbH differentiates via integrated glulam and cross-laminated timber production spanning Central European forests. New Energy Works specializes in custom timber frame packages for architect-driven residential and hospitality projects in the northeastern United States.
Timber frames are structural building assemblies fabricated from solid sawn or engineered wood members, joined through traditional mortise-and-tenon, steel connector, or integrated fastener systems, with engineered variants such as cross-laminated timber achieving fire ratings up to 90 minutes through char-layer design. These assemblies serve as primary load-bearing skeletons for buildings ranging from single-family residences to multi-story commercial structures, offering favorable strength-to-weight ratios and carbon sequestration properties compared to steel or concrete alternatives. Cross-laminated timber commands the fastest expansion among product types as panelized construction reduces on-site labor hours and accelerates project schedules. Residential buildings remains the dominant application category, though commercial structures is gaining share as office and retail developers pursue biophilic design credentials and embodied carbon reduction targets.
Building codes adopted by the International Code Council in the United States, the European Technical Assessment guidelines under the Construction Products Regulation, and Japan's Building Standards Law collectively determine height allowances, fire performance classifications, and seismic design parameters for timber frame structures. Compliance with these frameworks directly shapes product certification requirements, insurance availability, and architect specification behavior across jurisdictions. Stakeholders must monitor code amendment cycles and standard harmonization efforts to anticipate where engineered timber will secure structural parity with conventional materials.
Market Dynamics
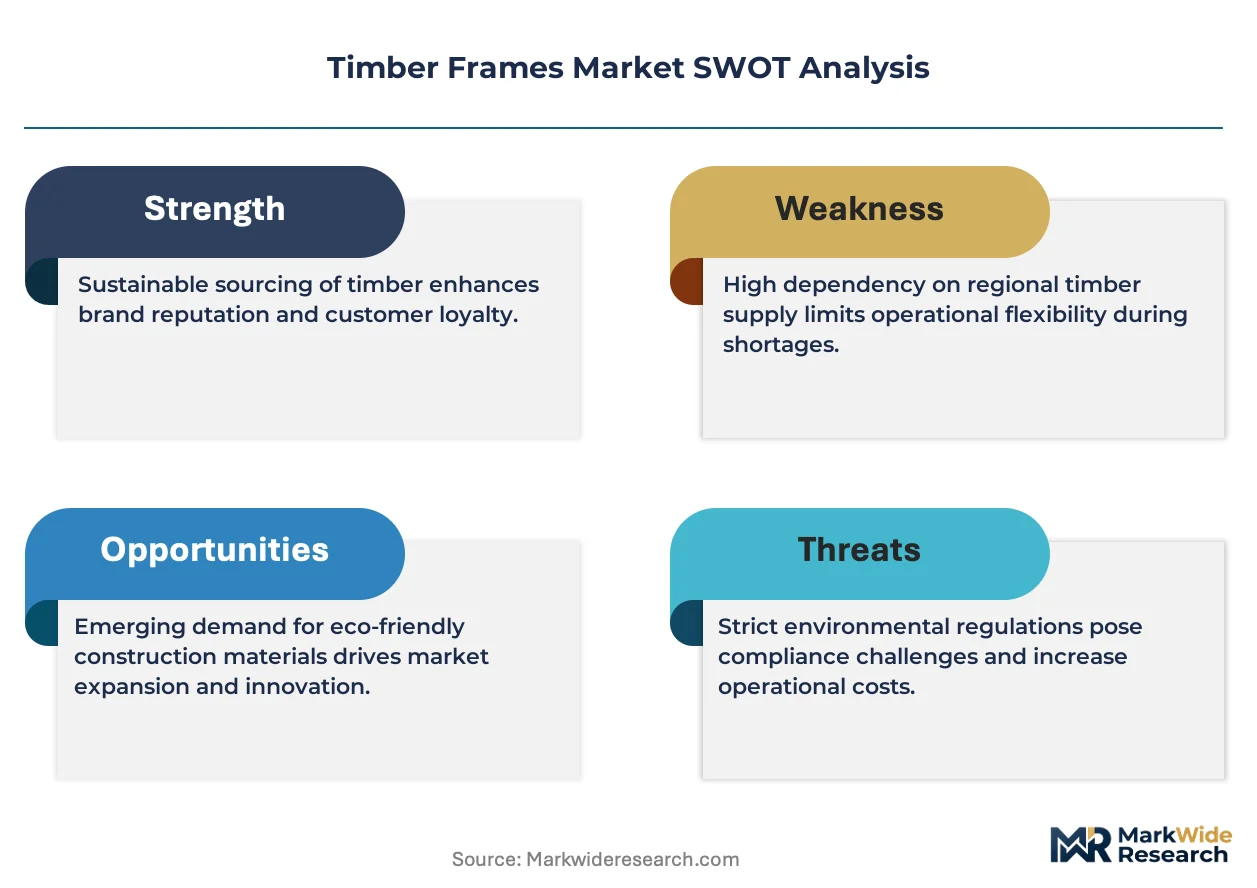
Building code harmonization across Germany, Canada, and Japan is dismantling height restrictions that historically confined timber frames to low-rise construction, unlocking mid-rise commercial and residential applications previously reserved for steel and concrete.
Growth Catalysts
- International Code Council amendments:The 2021 and 2024 IBC updates in the United States explicitly permit mass-timber structures up to 18 stories, triggering architect specification shifts in urban infill markets.
- Cross-laminated timber panelization:Factory-fabricated CLT floor and wall assemblies compress construction schedules by 30-50% versus cast-in-place concrete, attracting developer interest in high-labor-cost metros.
- Carbon accounting mandates:The EU Green Deal's embodied carbon disclosure requirements for public procurement tilt specification decisions toward timber's sequestration advantage over conventional materials.
Market Restraints
- Spruce-fir supply concentration:Nordic and Central European forests supply 70% of structural-grade softwood feedstock, exposing producers to weather-driven harvest volatility and trade flow disruptions.
- Adhesive cost inflation:Phenol-formaldehyde and polyurethane resins essential for CLT and glulam lamination track petrochemical feedstock prices, compressing margins when oil markets spike.
- Insurance market friction:Underwriters in jurisdictions lacking standardized fire-test protocols for engineered timber impose premium surcharges or coverage exclusions that deter speculative development.
Strategic Opportunities
- Japan's wooden architecture promotion act:METI subsidies for non-residential timber construction create immediate demand pull for fire-rated engineered systems in office and retail verticals.
- Hybrid structural systems:Timber-steel composite frames combining glulam beams with steel moment connections penetrate seismic zones where pure timber solutions face code resistance.
- Direct-to-developer prefabrication:Bypassing traditional lumber distribution through design-build partnerships captures margin and reduces lead-time uncertainty for multi-family developers.
Industry Challenges
- Fire engineering talent scarcity:Char-layer modeling and advanced compartmentation design require specialized structural engineers, with accredited practitioners concentrated in Scandinavia and the Pacific Northwest.
- CE marking bottlenecks:European Technical Assessment approvals for novel connection systems or adhesive formulations impose 12-24 month certification timelines that stall product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Frames Market |
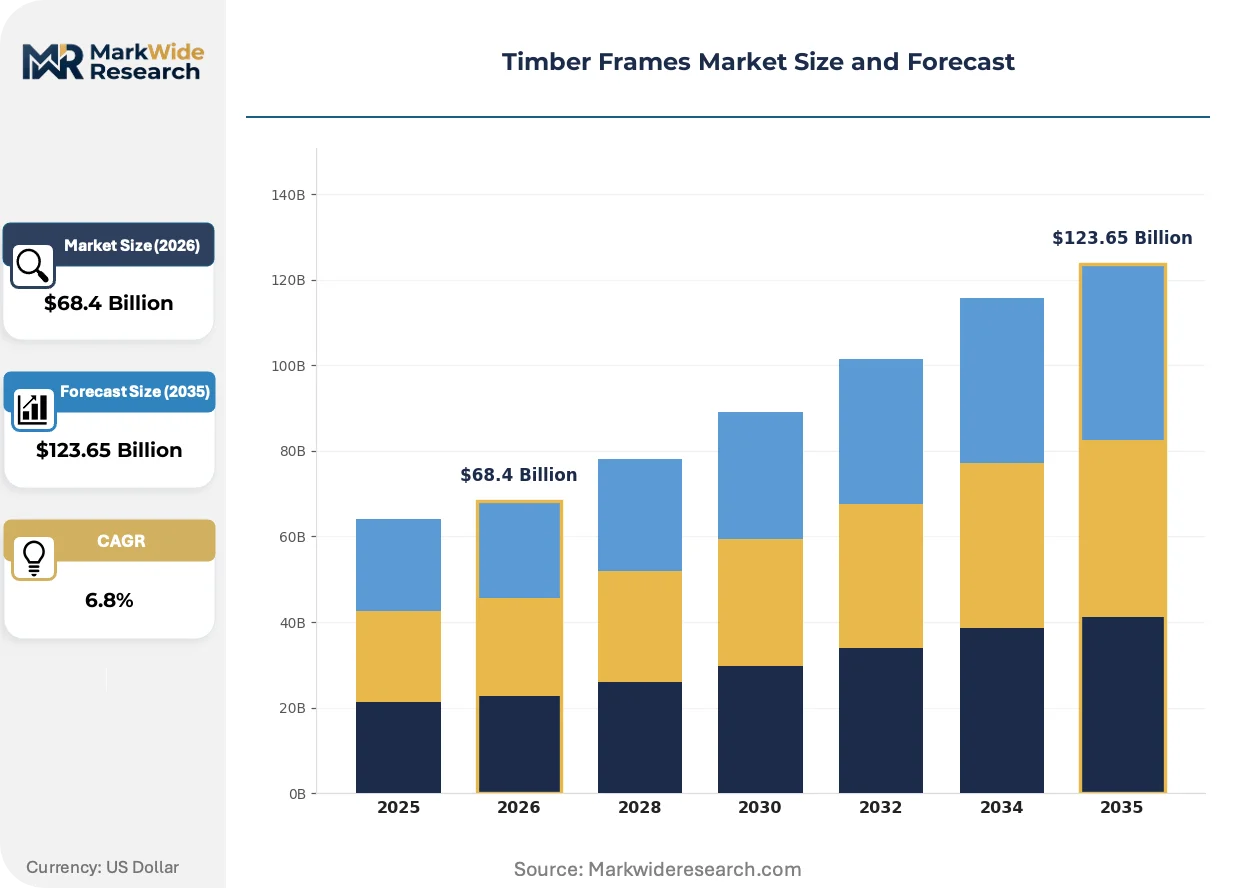
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue-Laminated, Cross-Laminated, Finger-Jointed, Solid Sawn Application: Residential Buildings, Commercial Structures, Industrial Facilities, Agricultural Buildings End User: Contractors, Architects, Developers, Homeowners Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | New Energy Works, Stora Enso Oyj, Woodhouse The Timber Frame Company, Canfor Corporation, Boise Cascade Company, DC Structures, Mid-Atlantic Timberframes, Binderholz GmbH, Custom Timber Frames, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Frames Market Strategic Shifts
Digital fabrication and biomaterial chemistry are converging to expand timber's performance envelope beyond traditional structural limits, while procurement rationalization compresses supply chain tiers.
Mass-customization software is miniaturizing the economics of bespoke timber frame production. Parametric design tools linked directly to CNC routing equipment enable single-batch fabrication of complex joinery at unit costs approaching standardized production. Boutique hospitality developers in British Columbia and Bavaria exploit this capability to deliver architecturally distinctive structures without the historical penalty of hand-craftsmanship. The technology is miniaturizing the minimum efficient scale for custom timber, fragmenting what was once a consolidated prefabrication market into distributed micro-factories.
Japan's Building Standards Law revisions explicitly recognize fire-resistant timber construction methods for buildings up to 11 stories, eliminating the previous 3-story cap that relegated mass-timber to peripheral applications. METI's accompanying technical guidance documents standardize char-rate calculations and connection protection protocols, reducing regulatory uncertainty that previously deterred institutional investment. Commercial developers in Tokyo and Osaka are responding with pilot office projects that test hybrid timber-core structures against seismic performance benchmarks.
Design-assist contracting is displacing traditional design-bid-build procurement for timber frame projects. Developers in Germany and Canada increasingly engage timber specialists during schematic design to optimize structural grids for panel dimensions and crane logistics, compressing change-order exposure and accelerating permitting. This model concentrates specification authority with integrated design-build entities rather than dispersed architect-contractor relationships, favoring producers with in-house engineering capabilities over commodity suppliers.
Timber Frames Market Segmentation
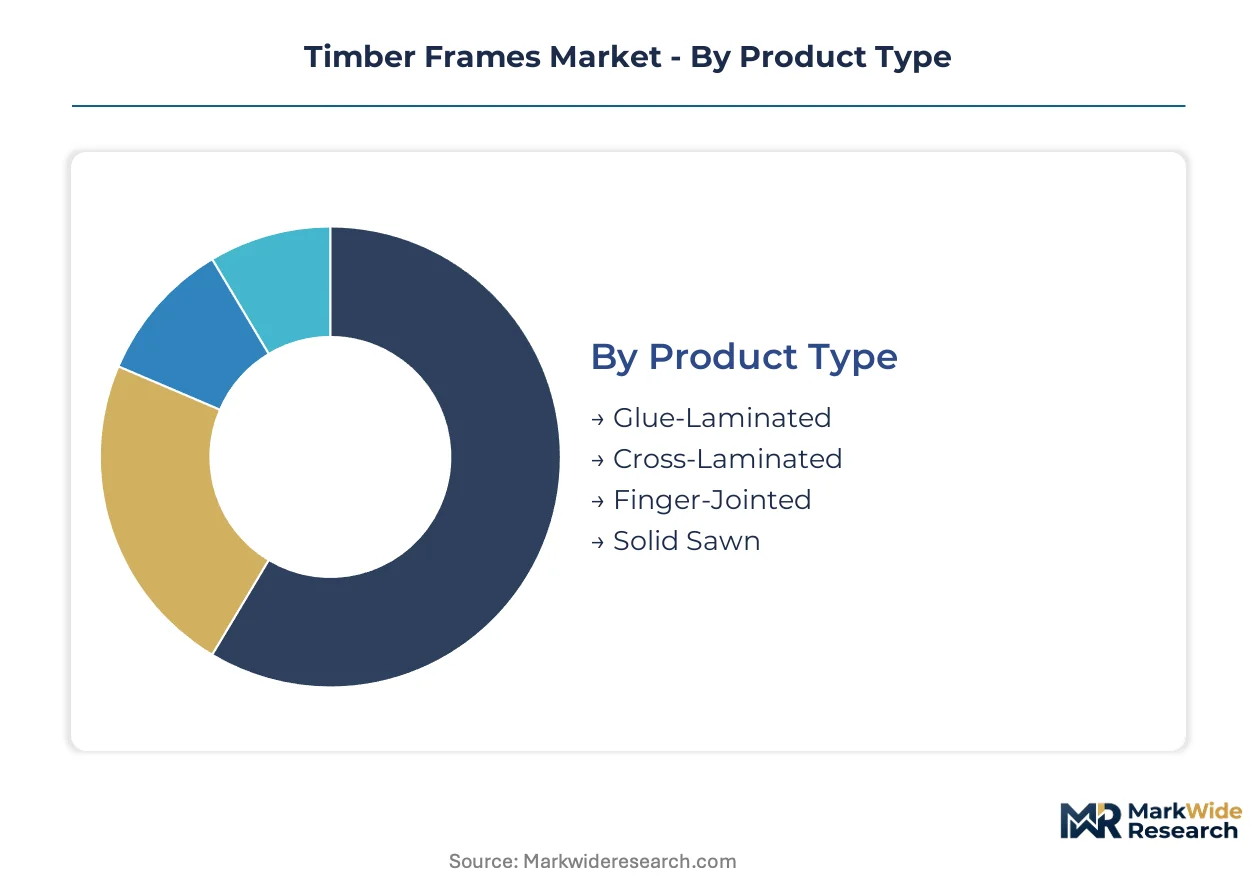
Segmentation in timber frames reveals how engineered wood products traverse distinct procurement pathways. Product specifications determine certification requirements, while application verticals dictate fire-rating and seismic performance thresholds that channel specifications toward specialized producers.
Product Type:
Channel mix varies sharply by product complexity, with factory-fabricated panels flowing through design-build partnerships while commodity beams move via traditional lumber distribution.
- Cross-Laminated:Factory-bonded orthogonal laminations create structural panels rated for 90-minute fire resistance through char-layer engineering. Demand concentrates in German and Canadian mid-rise residential towers where code harmonization permits 12-18 story mass-timber construction.
- Glue-Laminated:Parallel-laminated dimensional lumber achieves long-span beam and column performance with customizable camber profiles. Scandinavian commercial developers specify glulam for airport terminals and exhibition halls requiring exposed structural aesthetics combined with carbon accounting compliance.
- Finger-Jointed:End-jointed studs and trimmers reduce material waste while maintaining structural continuity for platform-framed construction.
- Solid Sawn:Traditional dimensional lumber serves single-family residential markets with minimal processing overhead and established grading protocols.
Cross-laminated timber dominates installed base in commercial verticals. Glue-laminated beams represent where expansion concentrates for long-span architectural applications.
Application:
Cost tier stratification separates premium architect-driven commercial projects from volume residential procurement, with industrial and agricultural segments occupying mid-tier specification bands.
- Residential Buildings:Single-family and multi-family structures account for the majority of timber frame volume, with platform framing and panelized systems competing on labor efficiency. Scandinavian and Pacific Northwest infill developers specify CLT for mid-rise apartment construction where code amendments permit.
- Commercial Structures:Office, retail, and hospitality projects pursue biophilic design credentials and embodied carbon reduction through exposed timber structures. Japanese METI subsidies accelerate non-residential timber adoption in Tokyo and Osaka office verticals.
- Industrial Facilities:Warehousing and light manufacturing employ timber frames for cost-sensitive envelope structures with moderate span requirements.
- Agricultural Buildings:Barns, equipment storage, and livestock facilities utilize pressure-treated solid sawn and glulam posts for durability in high-moisture environments.
Residential buildings anchor current volume. Commercial structures represent the steepest expansion trajectory as carbon disclosure mandates tighten across European public procurement.
End User:
Customer type determines technical engagement depth, with architects driving specification innovation while contractors and developers prioritize supply security and schedule compression.
- Developers:Multi-family and commercial project sponsors initiate design-assist procurement early in schematic phases to optimize structural grids for panel dimensions. German and Canadian developers increasingly bypass traditional distribution through direct mill partnerships.
- Architects:Design professionals specify engineered timber for biophilic and carbon-responsive projects, requiring producers with in-house fire engineering and connection design capabilities.
- Contractors:Construction managers source timber frames through established lumber distribution for platform-framed residential and light commercial projects.
- Homeowners:Individual purchasers access custom timber frame packages through specialty dealers for single-family residential and recreational structures.
Developers control specification authority in commercial verticals. Architects drive adoption in institutional and hospitality segments where design credentials command premium positioning.
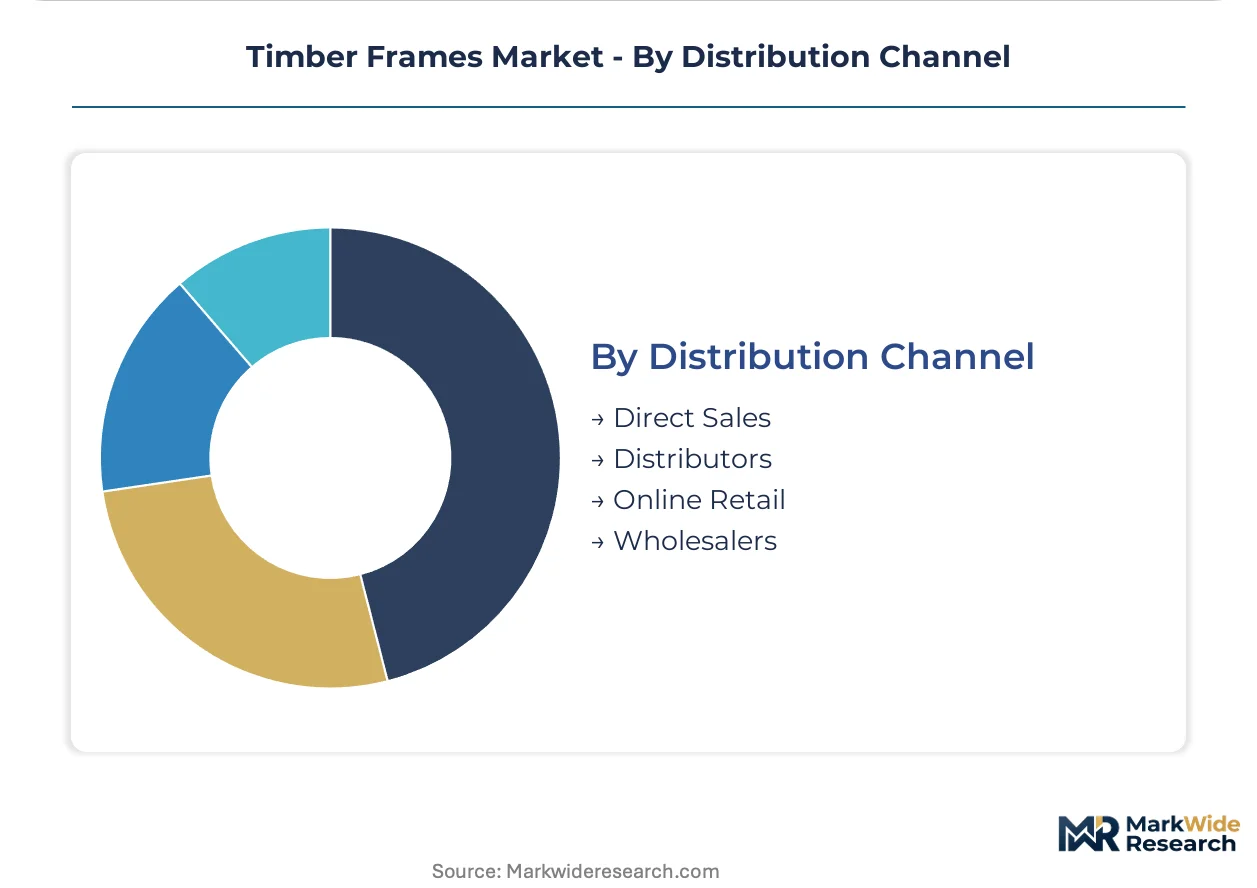
Distribution Channel:
Supply concentration in Nordic and Central European forests shapes channel economics, with direct sales capturing margin from large developers while distributors serve fragmented contractor demand.
- Direct Sales:Producers engage multi-story residential and commercial developers through design-build partnerships, capturing margin and reducing lead-time uncertainty. Stora Enso and Binderholz operate captive direct channels for CLT and glulam in European markets.
- Distributors:Regional lumber dealers stock commodity solid sawn and glulam beams for contractor spot purchasing and project-based procurement.
- Wholesalers:Volume aggregators supply platform-framing packages to production homebuilders across North American markets.
- Online Retail:Digital channels serve homeowner and small contractor demand for specialty fasteners, connection hardware, and custom-cut components.
Direct sales dominate engineered timber panel flow. Distributors retain solid sawn and commodity glulam volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish and Swedish producers export cross-laminated timber panels to German and British developers building mid-rise residential towers. Canadian manufacturers ship engineered timber frames to United States multi-family construction markets along the Pacific Coast and Northeast corridor.
United States
Multi-family developers in Seattle, Portland, and New York specify mass-timber for mid-rise apartment construction. The International Code Council's 2021 and 2024 IBC amendments permit timber structures up to 18 stories. Design-assist procurement concentrates in the Pacific Northwest where local fabricators partner directly with developers.
Germany
Commercial developers pursue carbon-neutral office construction using exposed glulam and CLT systems. The federal government's climate action program subsidizes timber construction in public procurement. Industrial clusters in Bavaria and Baden-Württemberg host integrated glulam manufacturing and engineering design firms.
Canada
British Columbia and Quebec producers supply cross-laminated timber to domestic mid-rise residential markets and United States export demand. The National Building Code of Canada harmonizes with international mass-timber standards through the Canadian Commission on Building and Fire Codes. Vancouver architects specify hybrid timber-core structures for seismic zones.
Japan
Tokyo and Osaka commercial developers pilot fire-rated engineered timber for office and retail verticals. METI's Wooden Architecture Promotion Act subsidizes non-residential timber construction. The Building Standards Law revision permits 11-story timber structures, eliminating the previous 3-story cap.
United Kingdom
London developers specify cross-laminated timber for urban infill residential projects targeting embodied carbon reduction. The Building Safety Regulator enforces fire performance standards for engineered timber under the Building Safety Act. Scottish producers in the Highlands supply structural-grade softwood feedstock to English panel manufacturers.
Timber Frames Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic reach. The market structures around three tiers: Nordic integrated forest-products groups with captive fiber supply, Central European engineered-wood specialists with regional manufacturing footprints, and North American custom fabricators serving architect-driven residential projects. Strategic moves concentrate on backward integration into forestland ownership and design-build partnership models that bypass traditional distribution.
Among Nordic integrated producers, Stora Enso Oyj anchors the listed-leader tier with captive fiber supply across Finnish and Swedish forests. Binderholz GmbH exemplifies the Central European specialist model with integrated glulam and cross-laminated timber production. New Energy Works occupies a position within the North American custom-fabrication segment, serving architect-driven residential and hospitality projects through direct mill partnerships rather than commodity distribution channels.
| Leading Market Players |
|---|
| New Energy Works |
| Stora Enso Oyj |
| Woodhouse The Timber Frame Company |
| Canfor Corporation |
| Boise Cascade Company |
| DC Structures |
| Mid-Atlantic Timberframes |
| Binderholz GmbH |
| Custom Timber Frames |
| Others |
Value Chain & Pricing Dynamics
Mill-scale economies at Nordic CLT facilities create asymmetric pricing power that compresses margins for smaller Central European competitors while elevating floor prices for engineered timber in German and British mid-rise construction. Capacity utilization above eighty percent at Finnish and Swedish integrated mills translates into contract pricing leverage against developers in high-labor-cost metros, whereas fragmented solid-sawn producers in North American markets absorb volatility through spot-market exposure.
Pricing Analysis
Next-generation fire-rated CLT systems command thirty to forty percent premiums over conventional glulam beam configurations, while prior-generation platform-framing packages trade at commodity levels with minimal differentiation. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers capture architect-specified commercial projects requiring CE-marked fire engineering, standard tiers serve multi-family developers pursuing carbon accounting compliance, and economy tiers address agricultural and light industrial envelope structures. Pricing pressure stems from phenol-formaldehyde resin cost inflation tracking petrochemical feedstock volatility, compressing margins for CLT laminators without captive adhesive supply. Multi-family developers exhibit highest price sensitivity through design-assist procurement that benchmarks panel costs against cast-in-place concrete alternatives, while hospitality architects demonstrate lowest sensitivity when biophilic credentials command premium positioning.
Supply Chain Analysis
Strategic stockpiling of structural-grade spruce-fir feedstock dominates procurement behavior among integrated Nordic producers, whereas North American fabricators operate on just-in-time lumber delivery from regional distribution yards. Geographic supply concentrates in Finland, Sweden, and Austria, where captive forestland ownership secures fiber access for Stora Enso and Binderholz against weather-driven harvest volatility. Raw material dependencies center on phenol-formaldehyde resins, polyurethane adhesives, and structural metal connectors sourced from petrochemical and steel manufacturing clusters. Single-source vulnerability in Nordic fiber supply exposes the entire engineered timber value chain to beetle infestation and storm-damage disruptions that have historically constrained harvest quotas. Distribution runs through direct mill partnerships for CLT and glulam panels, while commodity solid sawn moves via regional lumber dealers serving contractor spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the timber frames market creates multiple entry niches as design-assist procurement displaces traditional specification channels and code harmonization unlocks mid-rise applications previously reserved for steel and concrete. The dissolution of consolidated architect-contractor relationships favors specialized producers with in-house engineering capabilities over commodity suppliers.
For Market Incumbents: Compound market position through backward integration into forestland ownership in Finland and Sweden, securing captive fiber supply against climate-driven harvest volatility while expanding CLT capacity to serve German mid-rise residential demand. Prioritize CE marking investment for novel connection systems to accelerate European Technical Assessment timelines that currently stall product commercialization. Defensive consolidation of regional engineering talent pools in Scandinavia and the Pacific Northwest addresses fire engineering scarcity that constrains project execution.
For New Entrants and Emerging Players: CE marking fast-track through European Technical Assessment mutual recognition agreements creates immediate access to German and British public procurement markets where carbon disclosure mandates tilt specification toward timber. Target Japanese commercial verticals under METI's Wooden Architecture Promotion Act subsidies, where fire-rated engineered timber penetration remains below residential levels despite code amendments permitting eleven-story construction. Pursue hybrid timber-steel composite positioning for seismic zones where pure timber solutions face residual code resistance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with captive fiber supply and in-house fire engineering capabilities over commodity fabricators exposed to resin cost volatility. Five-to-ten year viability rests on code harmonization momentum across North America and Europe, with acquisition value concentrating in Central European glulam specialists possessing regional manufacturing footprints and established distributor relationships. Monitor International Code Council amendment cycles as inflection indicator for United States market expansion beyond current eighteen-story permissibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestland | Captive Nordic fiber supply insulates margins against weather-driven harvest volatility and trade flow disruptions. |
| CE Marking Investment | Accelerated European Technical Assessment timelines reduce twelve-to-twenty-four month certification bottlenecks for novel connection systems. |
| Design-Build Partnership Expansion | Direct developer engagement captures margin and reduces lead-time uncertainty in multi-family procurement. |
| Fire Engineering Talent Acquisition | Scandinavian and Pacific Northwest practitioner concentration addresses char-layer modeling scarcity constraining commercial project execution. |
| Hybrid Timber-Steel Development | Composite frame penetration unlocks seismic zone applications where pure timber faces residual code resistance in Japan and Vancouver. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, national building code filings, and forest products industry association reports across the analysis window. Primary interviews engaged timber frame fabricators, multi-family development executives, fire engineering consultants, and architect specification leads in Germany, Canada, Japan, and the United States. Secondary validation drew from International Code Council amendment documentation, European Technical Assessment registries, METI subsidy program disclosures, and Canadian Commission on Building and Fire Codes harmonization records. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and utilization estimates.
Segmentation dimensions modeled include product type hierarchy, application vertical stratification, end-user procurement behavior, and distribution channel concentration across the projection horizon. Cross-laminated timber, glue-laminated beams, finger-jointed studs, and solid sawn lumber constituted product categories. Residential, commercial, industrial, and agricultural applications captured demand verticals. Developer, architect, contractor, and homeowner end-user types determined specification authority patterns. Direct sales, distributor, wholesaler, and online retail channels mapped supply chain economics. CAGRs derived from regression analysis of historical production volumes against code amendment timing and carbon policy implementation trajectories, with timber-specific inputs including forest harvest quotas, adhesive cost indices, and fire engineering labor availability.
Underlying assumptions cover sustained code harmonization momentum, stable phenol-formaldehyde resin supply, and continued carbon accounting policy expansion, with deviation risk concentrated in insurance market friction for engineered timber coverage and single-source fiber supply disruptions. Forecasts reflect these conditions with acknowledgment that regulatory reversal, petrochemical price spikes, or beetle infestation events could materially alter trajectory. Revision becomes warranted when building code permissibility thresholds cross twenty stories in major jurisdictions or when insurance premium surcharges for mass-timber construction compress below steel and concrete parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Concrete Admixtures Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Blind Bolts Market
Building Materials
Polymer Concrete Market
Building Materials
Steel Products Market
Building Materials
Granite Market
Building Materials
Global Building Panels Market
Building Materials
Thin Brick Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Spain Cement Market
Building Materials
Global FRP Rebar Market
Building Materials
Cement Tiles Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Cellular Concrete Market