
 Poland Cement Market | 2026-2036
Poland Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Cement Market Insights
The premium-to-commodity tier split is consolidating. Heidelberg Materials Poland leverages integrated quarry-to-delivery chains to command premium positioning. Lafarge Cement S.A. competes through specialized blended formulations for infrastructure-grade applications. Cement Ożarów anchors its position in white cement niches where architectural specification drives margin retention.
Cement is a hydraulic binder produced by calcining limestone with clay at approximately 1,450°C, then grinding the resulting clinker with gypsum to control setting time; its compressive strength grades per EN 197-1 define structural suitability. Ordinary Portland Cement dominates volume flows but faces margin compression as the EU ETS raises carbon costs on clinker-intensive production. Blended Cement captures structural growth as fly ash and slag substitution ratios climb under decarbonization mandates. White Cement occupies a narrow but defensible premium tier where facade and decorative specifications resist commoditization.
Poland's cement sector operates under the EU Emissions Trading System, the Industrial Emissions Directive, and national transpositions through the Chief Inspectorate of Environmental Protection, with carbon allowance scarcity directly reshaping kiln investment calculus. BIS certification alignment and CE marking requirements govern cross-border product acceptance within the single market. Stakeholders must weigh clinker substitution pathways against ETS liability accumulation as the regulatory cost base hardens.
Market Dynamics
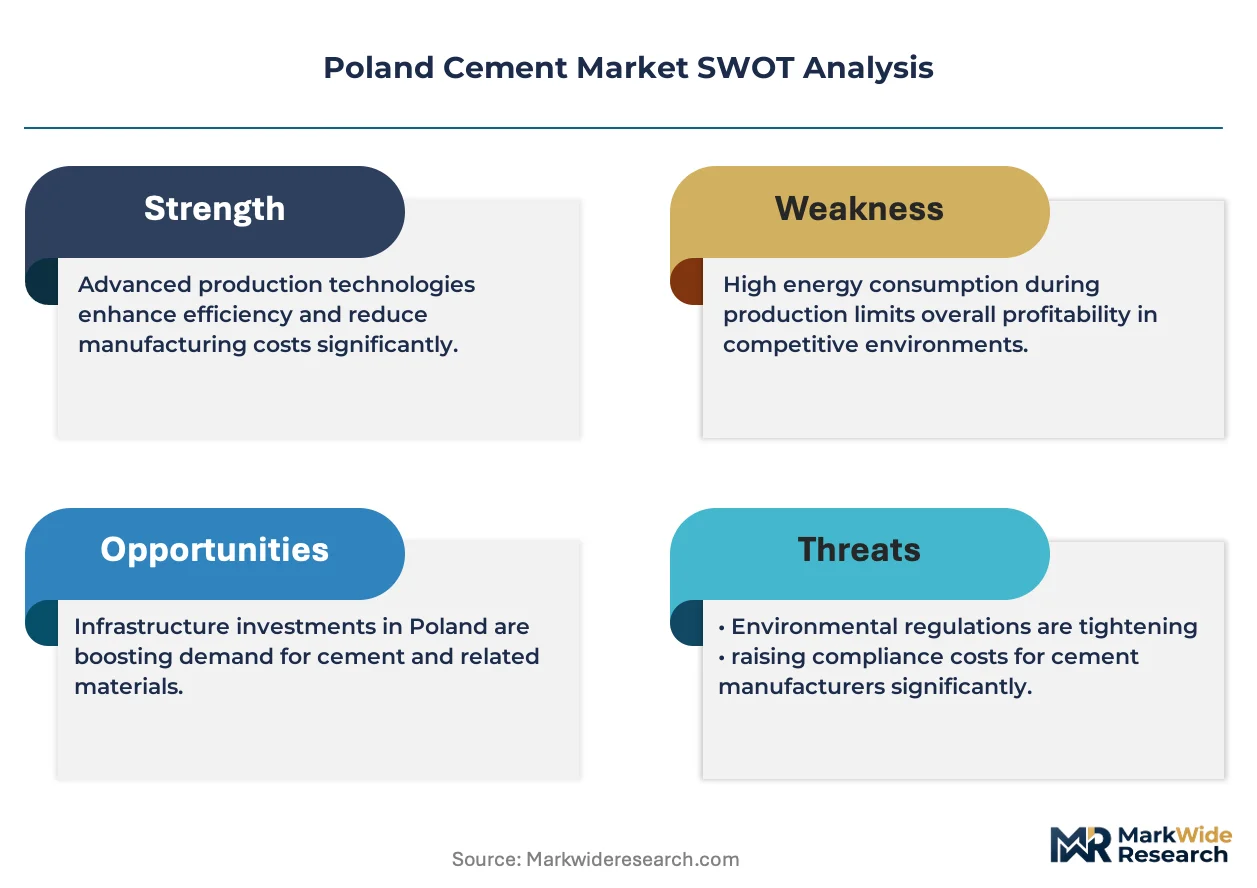
The EU Emissions Trading System is compressing clinker production margins while accelerating capital redeployment toward alternative binder technologies and kiln efficiency retrofits across Polish cement operations.
Growth Catalysts
- Housing infrastructure programs:National residential construction targets are absorbing rising cement volumes, particularly in Warsaw and Silesian metropolitan corridors where pipeline depth concentrates demand.
- EU ETS carbon cost differentials:Blended cement formulations gain competitive advantage as fly ash and slag substitution ratios climb under tightening allowance scarcity.
- White cement architectural specification:Facade and decorative applications resist commoditization, anchoring premium tier margin retention in specialized production facilities.
Market Restraints
- Clinker input cost volatility:Limestone and energy price swings compress operating margins for Ordinary Portland Cement producers dependent on high-temperature calcination.
- Supply concentration in Silesia:Kiln capacity clustering around specific mining regions creates geographic vulnerability to localized logistics disruptions or environmental enforcement actions.
- Regulatory friction from EU ETS:Carbon allowance auction mechanics and declining free allocation trajectories raise capital intensity for emission-intensive production assets.
Strategic Opportunities
- Underpenetrated rural construction:Smaller municipalities outside Warsaw and Kraków agglomerations present volume expansion potential as regional road and utility programs accelerate.
- CE marking cross-border access:BIS certification alignment enables Polish producers to capture infrastructure-grade demand across adjacent EU member state markets.
- Alternative fuel kiln integration:RDF and biomass co-processing technologies converge with decarbonization mandates to reduce fossil fuel dependency and ETS liability exposure.
Industry Challenges
- Process engineering talent scarcity:Specialized kiln operation and emissions control expertise shortages complicate workforce scaling for alternative fuel transitions.
- Legacy asset retrofit complexity:Decades-old production lines require substantial capital reconfiguration to meet Industrial Emissions Directive standards without operational interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Cement Market |
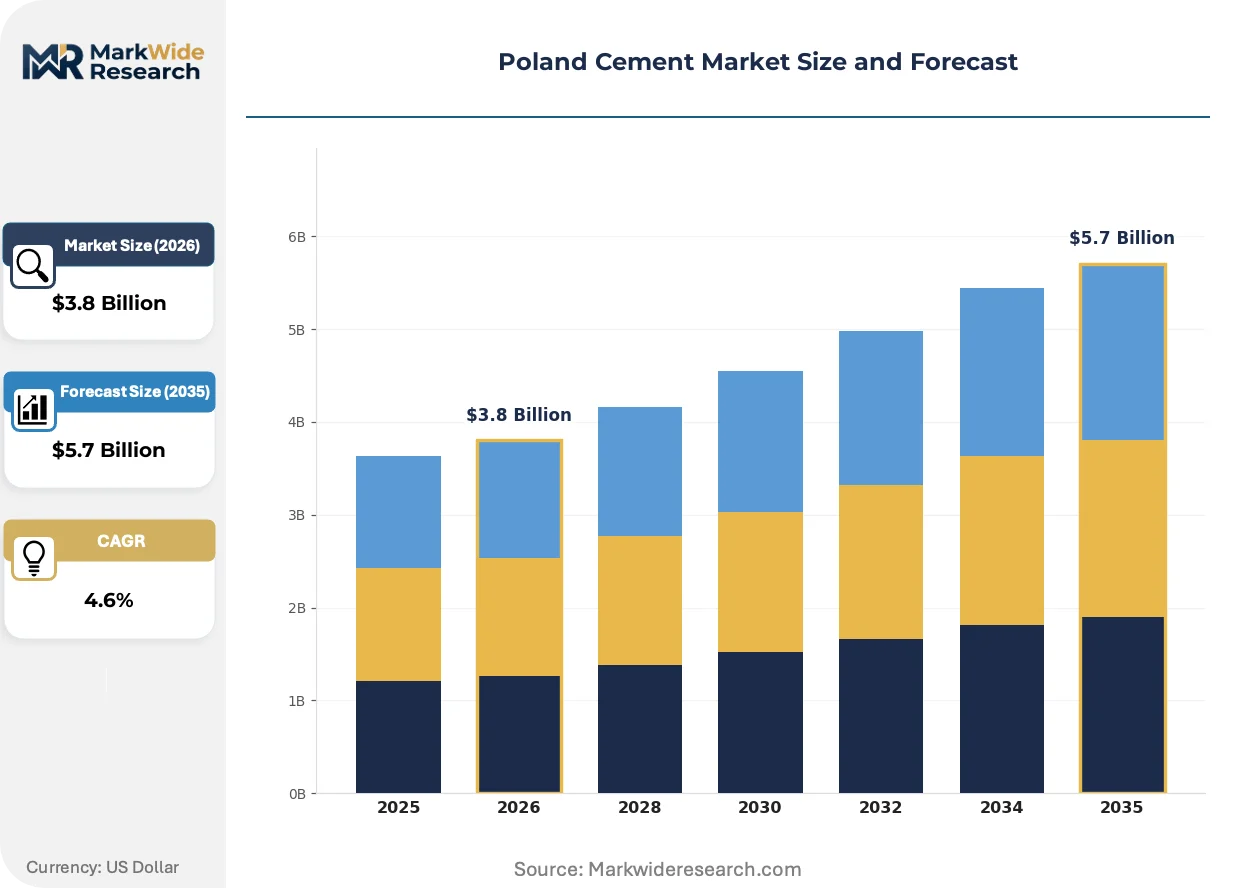
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, White Cement, Roller Compacted Cement Application: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Applications End User: Contractors, Builders, Civil Engineers, Government Projects Distribution Channel: Direct Sales, Retail Outlets, Wholesale Distributors, Online Sales |
| Companies Covered | Heidelberg Materials Poland, Lafarge Cement S.A., Holcim Ltd, Buzzi Cement, Cement Ożarów, Cement Plant Chełm, Cement Plant Kujawy, Cement Plant Ryazdź, Cement Plant Małogoszcz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Cement Market Trends and Innovations
Kiln control systems and alternative binder chemistry are reshaping competitive differentiation as carbon accounting penetrates procurement specifications and construction tender documentation.
Predictive maintenance platforms integrating sensor arrays and machine learning algorithms are automating kiln thermal profile optimization across major Polish cement plants. Infrastructure-grade concrete producers are adopting these systems fastest, driven by batch consistency requirements and energy cost pressures. This automation is compressing the advantage gap between integrated majors and mid-scale operators previously dependent on manual process control expertise.
The EU Emissions Trading System's Market Stability Reserve mechanism is tightening allowance supply faster than anticipated, forcing clinker producers to accelerate alternative fuel investments or accept margin erosion. Industrial emitters face auction price trajectories that reshape long-term kiln retirement calculus. Polish operations with pre-2000 assets are responding most aggressively, prioritizing RDF co-processing retrofits over greenfield replacement.
Public procurement frameworks are embedding embodied carbon thresholds into concrete supply contracts, displacing pure price-based tender evaluation. General contractors bidding on national road and rail programs now face specification requirements that favor low-clinker blends. This shift concentrates demand pull in Warsaw and Łódź corridors where infrastructure pipeline density justifies dedicated low-carbon supply chain investments.
Poland Cement Market Segmentation
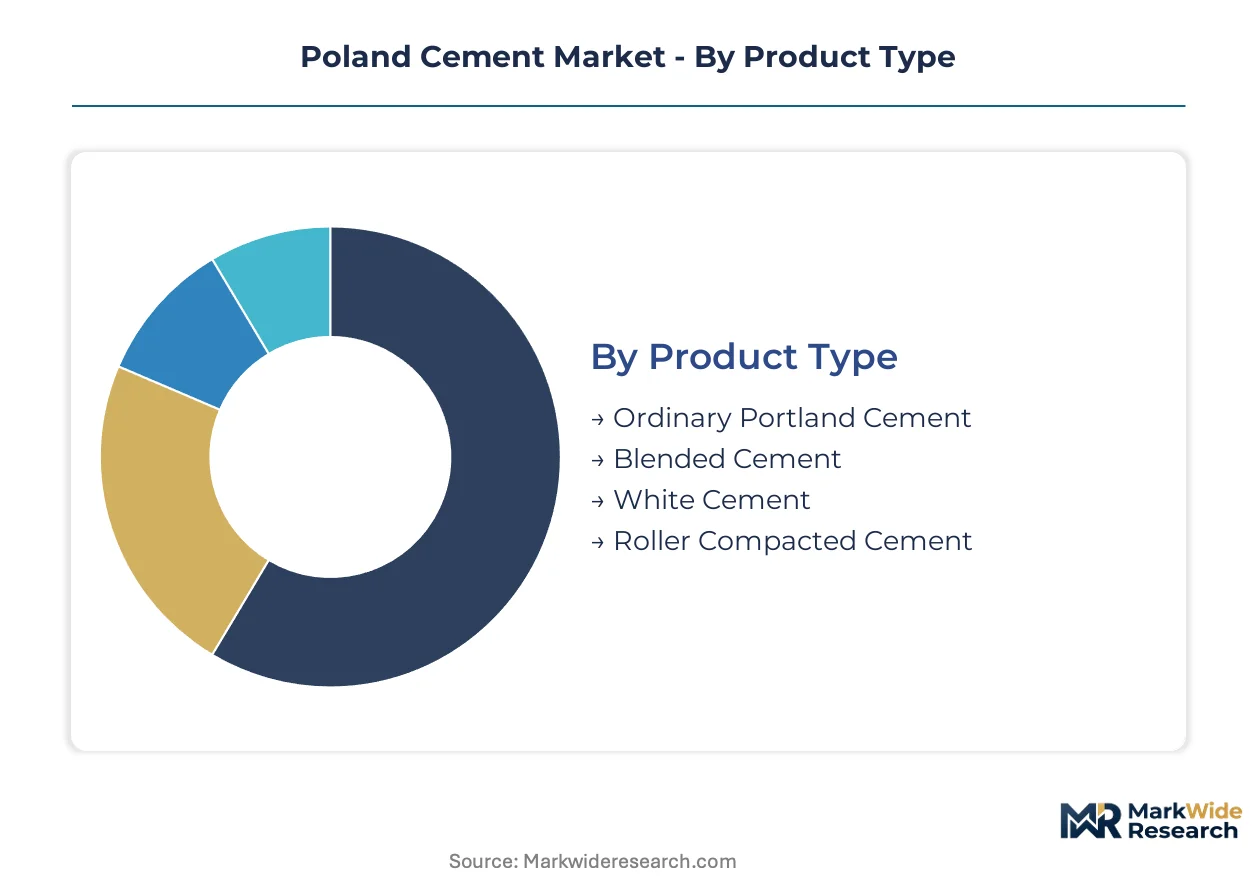
Poland's cement market segments along four intersecting dimensions that determine procurement patterns, margin structures, and regulatory exposure. Product type differentiation governs carbon intensity and ETS liability. Application mix concentrates demand geographically around Warsaw and Silesian infrastructure corridors.
Product Type:
Cost tier differentiation separates commodity-grade bulk cement from specialized formulations commanding specification premiums.
- Ordinary Portland Cement:High-clinker formulation produced by calcining limestone with clay at 1,450°C delivers standardized compressive strength grades per EN 197-1. Volume concentrates in Warsaw and Silesian metropolitan corridors where residential and infrastructure programs absorb bulk deliveries; ETS carbon cost pressure compresses margins as free allowance allocations decline.
- Blended Cement:Fly ash and slag substitution reduces clinker content below 65%, directly lowering EU ETS exposure. Demand accelerates fastest where public procurement embeds embodied carbon thresholds into concrete supply contracts, particularly national road and rail programs in Łódź corridor.
- White Cement:Low-iron clinker and specialized kiln control yield decorative-grade brightness for facade applications.
- Roller Compacted Cement:Zero-slump formulation suits dam and heavy foundation work with rapid placement requirements.
Volume sits with Ordinary Portland Cement; growth tilts toward Blended Cement.
Application:
Project scale and funding source determine specification stringency and supplier qualification requirements.
- Residential Construction:National housing programs drive volume absorption across multi-family and single-family developments. Warsaw agglomeration concentrates demand where pipeline depth justifies dedicated batching plant investments; margin pressure intensifies from standardized strength requirements and price-sensitive procurement.
- Infrastructure Development:Road, rail, and utility projects embed CE marking and low-carbon blend specifications into tender documentation. Silesian corridor anchors demand where EU cohesion fund pipelines intersect with national transport investment programs; carbon accounting requirements favor slag-rich formulations.
- Commercial Construction:Office and retail developments in Kraków and Wrocław agglomerations.
- Industrial Applications:Manufacturing facility foundations and process flooring specifications.
Residential Construction captures current volume leadership; Infrastructure Development climbs fastest on public procurement reform.
End User:
Technical capability and contract scale segment buyers by quality assurance requirements and logistics complexity.
- Contractors:General construction firms managing multi-trade projects across residential and commercial segments. Warsaw-based operators dominate volume through integrated quarry-to-site supply agreements; ETS cost pass-through negotiations determine margin retention.
- Government Projects:Central and municipal procurement authorities specifying embodied carbon limits and BIS certification alignment. National road agency contracts concentrate demand in Silesian and Łódź corridors; low-clinker blend mandates reshape supplier qualification.
- Builders:Smaller-scale residential developers outside major agglomerations.
- Civil Engineers:Infrastructure design consultants influencing specification-setting.
Contractors hold volume dominance; Government Projects expand most quickly on procurement framework reform.
Distribution Channel:
Customer scale and urgency requirements determine channel selection and service level differentiation.
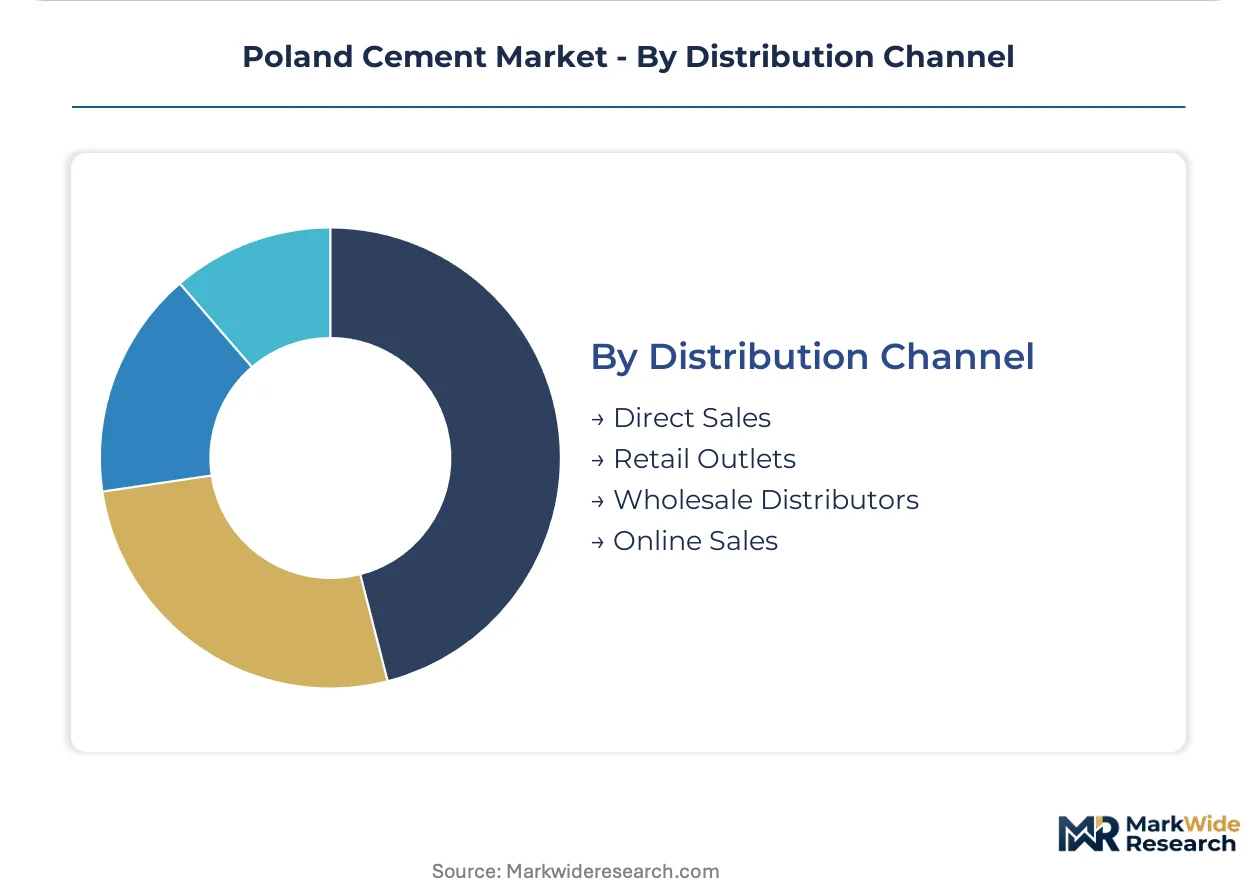
- Direct Sales:Kiln-to-site delivery for volume contractors and government projects. Integrated majors leverage captive transport fleets and dedicated silo installations around Warsaw and Silesian demand clusters; just-in-time logistics contracts lock in multi-year offtake commitments.
- Wholesale Distributors:Regional stockholding networks serving mid-scale builders and smaller contractors. Kraków and Wrocław distribution hubs consolidate fragmented rural demand; inventory carrying costs concentrate working capital requirements.
- Retail Outlets:Bagged cement sales for renovation and small-project segments.
- Online Sales:Emerging channel for specification documentation and order placement.
Direct Sales anchors volume; Wholesale Distributors gain share fastest on rural construction program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw anchors cement demand through its residential construction pipeline and infrastructure corridor density. Silesian metropolitan clusters concentrate kiln capacity alongside mining regions. The EU Emissions Trading System compresses margins unevenly across these production zones.
Masovian Voivodeship
National housing programs absorb bulk cement volumes across Warsaw agglomeration and surrounding municipalities. The Chief Inspectorate of Environmental Protection enforces Industrial Emissions Directive standards on local batching operations. Radom and Płock sub-regions concentrate secondary demand as regional road programs accelerate.
Silesian Voivodeship
Clinker production clusters around limestone deposits and established mining infrastructure in the Upper Silesian industrial zone. EU ETS allowance scarcity forces kiln operators toward alternative fuel retrofits. Katowice metropolitan corridor anchors infrastructure-grade demand through EU cohesion fund pipelines.
Lesser Poland Voivodeship
Kraków agglomeration drives commercial construction specifications with CE marking requirements for cross-border project eligibility. Municipal procurement frameworks embed embodied carbon thresholds into concrete supply contracts. Tarnów and Nowy Sącz sub-regions present underpenetrated volume potential as rural utility programs expand.
Łódź Voivodeship
Rail and national road investment programs concentrate government project demand along the Warsaw-Łódź corridor. Public procurement reform favors low-clinker blend suppliers with BIS certification alignment. Piotrków Trybunalski and Sieradz sub-regions attract wholesale distributor investment as logistics networks extend.
Lower Silesian Voivodeship
Wrocław metropolitan construction absorbs blended cement formulations for large-scale residential developments. Industrial Emissions Directive compliance costs accelerate legacy asset retirement decisions in surrounding production zones. Wałbrzych and Legnica sub-regions retain dormant capacity suitable for alternative fuel reactivation.
Poland Cement Market Competitive Landscape
Capital-heavy integrated producers compete with specialized niche operators across distinct capability tiers. Market structure consolidates around quarry-to-delivery chains controlling limestone access and captive transport fleets. Three archetypes dominate: vertically integrated majors with full supply chain control, regional specialists commanding white cement or infrastructure-grade niches, and state-affiliated plants serving localized catchments. Competitive moves center on kiln efficiency retrofits and alternative fuel co-processing investments that reduce EU ETS exposure.
Within the integrated major tier, Heidelberg Materials Poland and Lafarge Cement S.A. exemplify archetypes differentiated by supply chain breadth versus formulation specialization. Cement Ożarów occupies a position in the premium niche segment where architectural specification resists price-based competition. Among regional state-affiliated operators, Cement Plant Chełm and Cement Plant Kujawy represent production assets anchored to specific limestone deposits and municipal demand catchments. These named entities illustrate how competitive positioning stratifies across capital intensity, geographic control, and specification capability rather than scale alone.
| Leading Market Players |
|---|
| Heidelberg Materials Poland |
| Lafarge Cement S.A. |
| Holcim Ltd |
| Buzzi Cement |
| Cement Ożarów |
| Cement Plant Chełm |
| Cement Plant Kujawy |
| Cement Plant Ryazdź |
| Cement Plant Małogoszcz |
| Others |
Pricing and Supply Chain Analysis
Alternative fuel kiln retrofits across Polish cement operations simultaneously compress production economics and reshape limestone sourcing patterns around RDF and biomass availability corridors. EU ETS carbon cost pass-through mechanics now govern contract negotiations between integrated majors and volume contractors, embedding emissions liability into every tonne price.
Pricing Analysis
Throughput-linked pricing for infrastructure-grade concrete contracts anchors value capture for integrated producers with captive batching plant networks. Three-tier pricing structure across premium white cement, standard blended formulations, and economy-grade bulk OPC separates architectural specification from commodity construction. Pricing pressure stems from declining EU ETS free allowance allocations compressing clinker-intensive margins. Government project procurement offices exhibit lowest price sensitivity due to embodied carbon mandates, while rural residential builders face acute cost compression.
Supply Chain Analysis
Domestic limestone extraction licensing under Poland's Chief Inspectorate of Environmental Protection constrains foreign sourcing and reinforces Silesian-Masovian quarry concentration. Clinker production draws from Upper Silesian limestone deposits, Ukrainian fly ash for blended formulations, and German kiln equipment spares. Single-source vulnerability concentrates in Silesian kiln clustering where environmental enforcement actions could disrupt national supply. Distribution runs through integrated direct-delivery fleets for volume contractors and regional wholesale stockholders for fragmented rural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Poland cement market functions as a vertical-integration race where quarry-to-delivery chain control determines margin retention against carbon cost pass-through pressures. Players are pursuing backward integration into limestone deposits and captive transport fleets as the decisive upstream lever.
For Market Incumbents: Hedge clinker margin erosion by accelerating alternative fuel retrofits in pre-2000 Silesian assets and locking multi-year offtake contracts with Warsaw infrastructure contractors before EU ETS auction prices tighten further. Prioritize RDF co-processing investments over greenfield kiln replacement to preserve capital flexibility against regulatory uncertainty. For New Entrants and Emerging Players: Begin with white cement niche production in under-supplied Łódź corridor regions where architectural specification premiums resist commoditization. Target municipal road programs in Tarnów and Nowy Sącz sub-regions for blended cement volume entry. Pursue BIS certification alignment as the qualifying threshold for government project procurement participation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated European majors seeking Polish limestone access and ETS compliance diversification. Five-to-ten year viability favors assets with alternative fuel retrofit completion and locked government project pipelines. Monitor EU Market Stability Reserve allowance release schedules as the critical inflection signal for clinker production asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Kiln Retrofit | RDF and biomass co-processing reduces EU ETS liability exposure for Silesian clinker producers. |
| Backward Integration into Limestone | Quarry control secures feedstock access against Chief Inspectorate licensing constraints. |
| Low-Clinker Blend Capacity Expansion | Slag-rich formulation investments capture Warsaw-Łódź infrastructure procurement reform. |
| BIS Certification Alignment | CE marking equivalence enables cross-border concrete supply to adjacent EU member states. |
| Captive Transport Fleet Investment | Just-in-time silo delivery locks multi-year contractor commitments in Masovian demand clusters. |
Research Methodology
Independent corroboration across plant managers at integrated cement operations, procurement leads at Warsaw-based general contractors, distribution channel partners in Kraków hub regions, and regulatory affairs specialists at the Chief Inspectorate of Environmental Protection underwrites the qualitative findings. Secondary validation drew from EU ETS auction price databases, Polish Central Statistical Office construction output indices, Industrial Emissions Directive compliance filings, and Heidelberg Materials Poland SEC disclosures. Bottom-up volume modeling triangulated against top-down cement consumption intensity benchmarks per construction sector.
Rate-of-change decomposition across product type, application segment, end-user archetype, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression against construction investment cycles, EU ETS price trajectory scenarios, and clinker substitution elasticity parameters. Forecast inputs incorporated housing program pipeline depth by voivodeship and public procurement framework reform implementation timelines.
Underlying measurement precision varies by segment; Ordinary Portland Cement volume estimates carry tighter precision than white cement niche projections due to batching plant reporting granularity. Forecasts reflect documented assumptions regarding EU ETS allowance allocation trajectories and national infrastructure budget execution rates. Carbon border adjustment implementation or accelerated kiln retirement could materially revise outlooks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Granite Flooring Market