
 Global Commercial Paving Slabs Market | 2026-2036
Global Commercial Paving Slabs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Paving Slabs Market Analysis
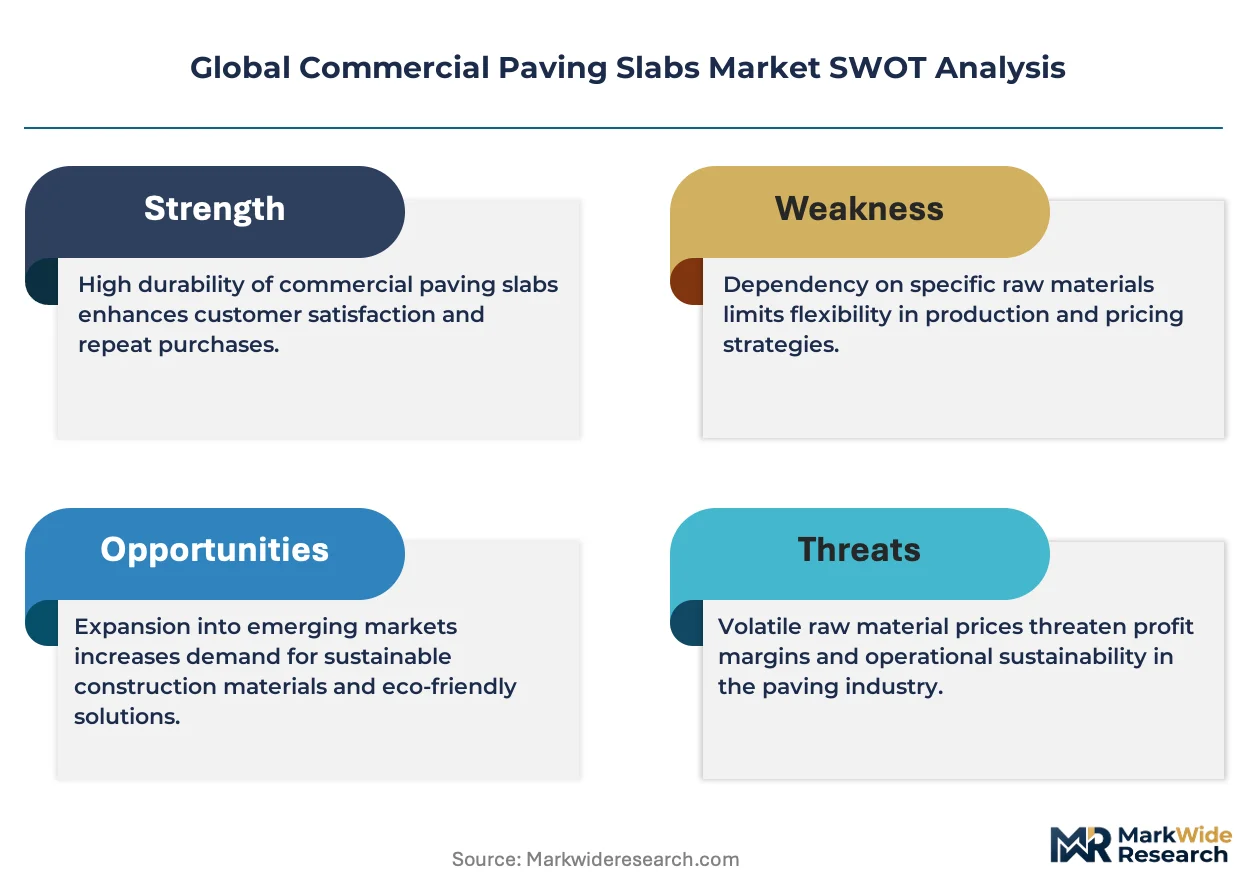
Skilled masonry labor availability is bifurcating the competitive landscape between premium and volume producers. Hanover Architectural Products leverages in-house fabrication capabilities to sustain its position in architect-specified commercial projects. Marshalls plc anchors its UK and European presence through vertically integrated quarry-to-site operations. CRH plc competes across multiple price tiers through its broad geographic manufacturing footprint.
Commercial paving slabs are load-bearing surface units manufactured from concrete, stone, clay, or asphalt composites, typically ranging from 50mm to 150mm in thickness and engineered for pedestrian and vehicular traffic in public and private exterior spaces. Concrete formulations dominate volume due to their cost efficiency and moldability for textured finishes, while stone variants command premium positioning in heritage and high-visibility plaza applications. The contractor end-user segment represents the largest procurement channel, though municipality direct purchasing is expanding fastest as cities internalize lifecycle cost analysis for infrastructure assets.
EPA stormwater management guidelines in the United States, REACH chemical compliance frameworks in Europe, and China's GB standards for construction materials collectively shape product formulation, permeability requirements, and market access conditions across major producing regions. Ecodesign regulations in the European Union are progressively embedding carbon disclosure obligations into public procurement criteria for hard landscaping materials. Stakeholders must monitor evolving embodied carbon thresholds and permeability mandates as these regulatory vectors increasingly determine specification eligibility and contract win rates.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are restructuring specification eligibility for public infrastructure contracts, forcing reformulation investments across the supply base.
Growth Catalysts
- Urban Renewal Programs:China's tier-one cities are prioritizing durable surface infrastructure in pedestrian plaza renovations, creating concentrated demand for permeable concrete systems.
- REACH Chemical Compliance:The European framework is accelerating low-carbon binder substitutions in wet-cast manufacturing processes.
- Stormwater Infrastructure Modernization:EPA guidelines in the United States are mandating permeable surface coverage ratios in new commercial developments.
Market Restraints
- Cement Input Volatility:Energy-intensive clinker production faces carbon border adjustment pressures, compressing margin structures for volume producers.
- Quarry Resource Concentration:Premium stone slab supply clusters in specific regional extraction zones, creating logistics cost premiums for distant projects.
- Clay Firing Limitations:Traditional kiln processes face hard technical caps on permeability performance versus concrete alternatives.
Strategic Opportunities
- Carbon-Negative Formulations:Biochar-integrated concrete and geopolymer binders qualify for EU public procurement preference thresholds.
- Direct Municipality Contracting:Lifecycle cost analysis adoption is opening bypass channels around traditional distributor networks.
- India Smart Cities Mission:Urban heat island mitigation specifications are creating specification pull for high-albedo surface materials.
Industry Challenges
- Skilled Masonry Scarcity:Specialized installation labor for heritage-specification stone paving limits project throughput in premium segments.
- GB Standard Certification Timelines:China's construction material approval processes create extended market access delays for imported formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Paving Slabs Market |
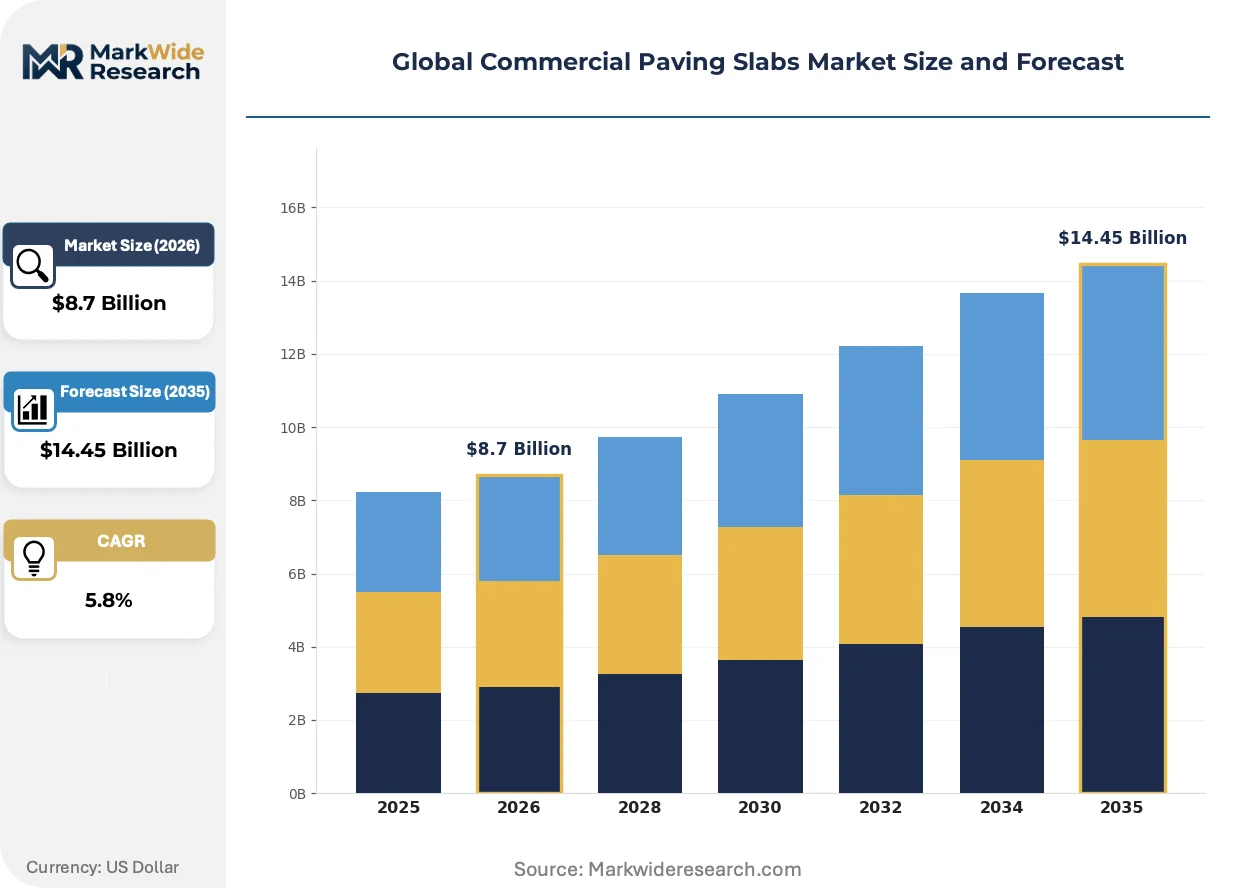
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Concrete, Stone, Clay, Asphalt Application: Parks, Roadways, Driveways, Public Squares End User: Contractors, Municipalities, Homeowners, Landscapers Thickness: Thin, Standard, Thick, Extra Thick |
| Companies Covered | Hanover Architectural Products, Unilock Ltd., Artistic Paver Manufacturing Inc., Belgard, Cambridge Pavingstones, Tile Tech Pavers, Marshalls plc, CRH plc, Tobermore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Paving Slabs Market Emerging Trajectories
Formulation chemistry and procurement digitization are converging to compress specification cycles and reshape competitive access in commercial hardscaping.
Geopolymer and alkali-activated binder technologies are displacing Portland cement in municipal specification pools. German cities are piloting these formulations in pedestrian zones ahead of wider EU Green Deal compliance deadlines. The shift is compressing traditional ready-mix supply relationships as in-house batching capabilities spread among large contractors.
REACH chemical restriction expansions are forcing reformulation of surface sealants and release agents used in wet-cast manufacturing. The industrial consequence is accelerated R&D spending on bio-based alternatives among European producers. Wet-cast concrete slab manufacturers serving heritage restoration projects face the steepest compliance cost curves.
Lifecycle cost modeling software is embedding directly into municipal procurement platforms, altering how surface material bids are evaluated. Contractors in the United Kingdom are restructuring service offerings around 20-year maintenance-inclusive contracts. The shift is most visible in UK county council frameworks, where whole-life value scoring now dominates initial price weighting.
Global Commercial Paving Slabs Market Segmentation
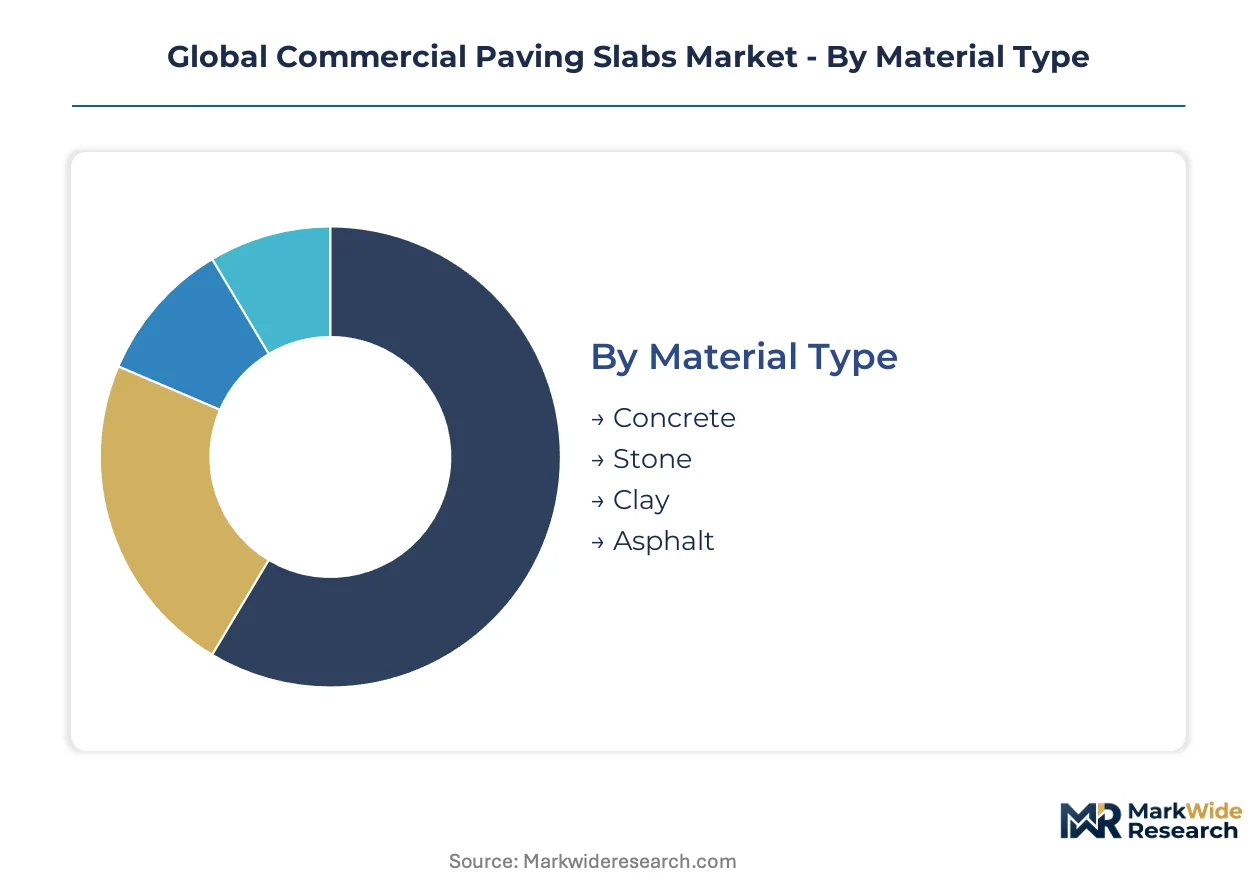
Material composition and application context determine specification eligibility, procurement channel, and margin structure across commercial paving markets. Channel mix varies sharply by segment, with municipalities bypassing distributors for direct contracting on infrastructure-grade materials while contractors dominate volume procurement for private developments.
Material Type:
Channel flow diverges by material cost tier and specification complexity, with concrete and stone following distinct procurement pathways.
- Concrete:Wet-cast and pressed formulations deliver cost efficiency and moldability for textured surface finishes. Demand concentrates in China's tier-one cities where urban renewal programs specify permeable concrete systems for pedestrian plaza renovations, driven by dual carbon goals and stormwater infrastructure mandates.
- Stone:Natural granite and limestone variants command premium positioning in heritage restoration and high-visibility public square applications. German municipalities anchor European demand for stone paving in historic district renovations, constrained by quarry resource concentration in specific regional extraction zones that elevate logistics costs for distant projects.
- Clay:Traditional kiln-fired units serve aesthetic specifications in residential-adjacent commercial landscapes. REACH chemical compliance frameworks in Europe are accelerating reformulation of surface sealants used in manufacturing processes.
- Asphalt:Composite formulations target heavy-vehicular load applications in commercial driveways and service roadways. EPA stormwater guidelines in the United States are mandating permeable surface coverage ratios in new commercial developments.
Concrete dominates installed base. Stone is where expansion concentrates for premium specification pools.
Application:
Project scale and regulatory exposure shape customer type and procurement modality across use cases.
- Parks:Green infrastructure specifications prioritize permeability and thermal performance for pedestrian comfort. India's Smart Cities Mission is creating specification pull for high-albedo surface materials in urban heat island mitigation programs across municipal park renovations.
- Roadways:Heavy-vehicular load requirements demand thick-section concrete or stone with engineered base systems. Lifecycle cost modeling software is embedding directly into UK county council procurement platforms, shifting bid evaluation toward 20-year maintenance-inclusive contracts.
- Driveways:Commercial service access routes balance durability against installation speed and initial cost. Contractor procurement channels dominate this segment through distributor relationships.
- Public Squares:High-visibility pedestrian plazas combine aesthetic specification with heritage compliance requirements. EU Green Deal embodied carbon disclosure mandates are restructuring eligibility for public infrastructure contracts, forcing reformulation investments across stone and concrete supply bases.
Roadways anchor volume procurement. Public squares are climbing the fastest on specification value per square meter.
End User:
Procurement sophistication and lifecycle cost analysis adoption determine margin capture and channel control.
- Contractors:General and specialty hardscaping firms represent the largest procurement channel by volume, sourcing through established distributor networks for project-based demand.
- Municipalities:Direct purchasing is expanding most quickly as cities internalize lifecycle cost analysis for infrastructure assets, opening bypass channels around traditional distributor networks in Germany, the United Kingdom, and United States.
- Homeowners:Residential-adjacent commercial property owners drive demand for aesthetic stone and clay variants through retail and contractor channels.
- Landscapers:Design-build firms specify premium materials for high-visibility private commercial developments, constrained by skilled masonry scarcity for heritage-specification stone installation.
Contractors retain volume leadership. Municipalities are gaining share fastest on direct contracting conversion.
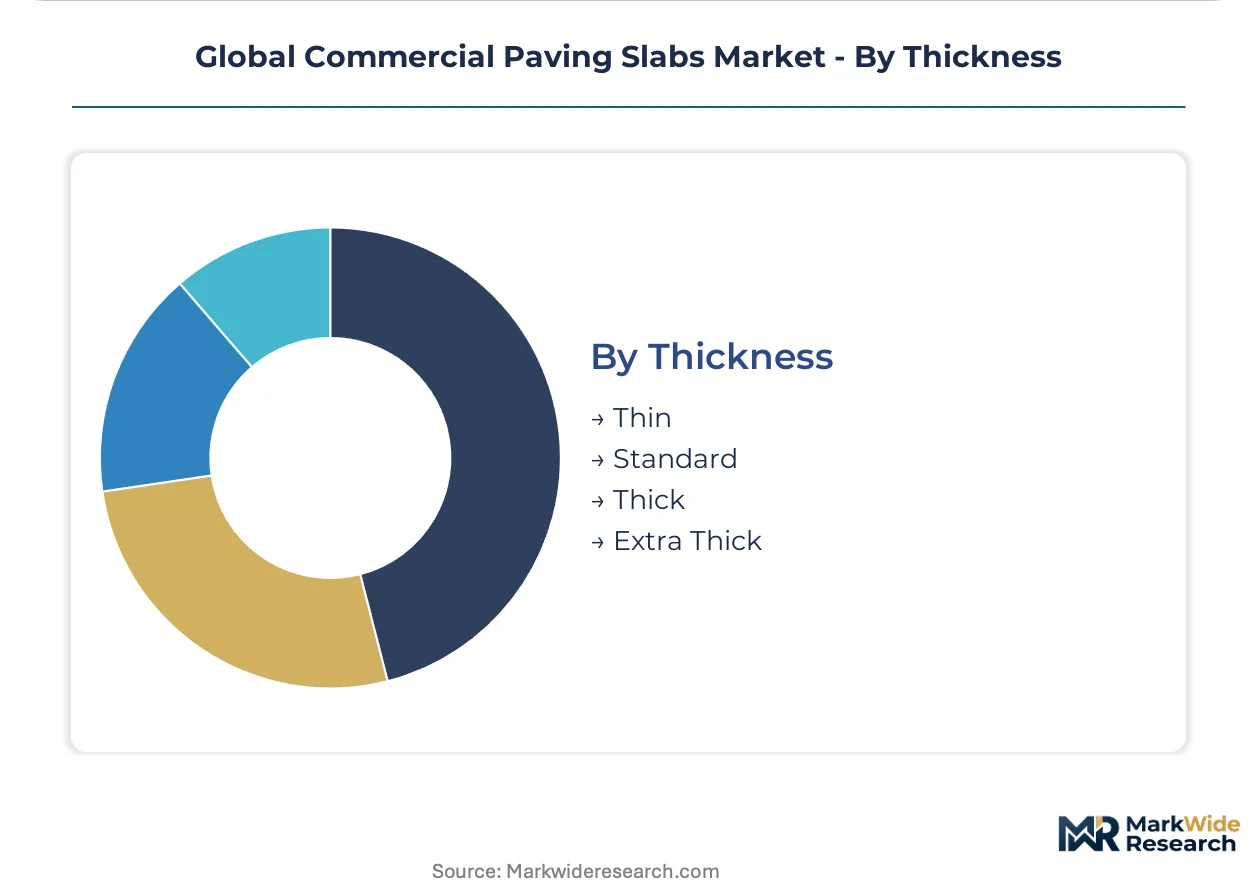
Thickness:
Structural load requirements and installation labor intensity stratify pricing and competitive positioning.
- Thin:50mm sections serve pedestrian-only applications in parks and public squares where subgrade conditions permit reduced structural depth.
- Standard:75-100mm units balance material cost against vehicular load tolerance for light commercial driveways and access routes.
- Thick:100-125mm sections target heavy-vehicular roadways and industrial service areas requiring enhanced load distribution.
- Extra Thick:125-150mm units address extreme loading conditions and permeable base systems in stormwater management infrastructure.
Standard thickness anchors volume production. Extra thick is expanding most quickly on permeable infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German municipalities prioritize heritage-compliant stone for historic district renovations, while Chinese urban planners specify permeable concrete for stormwater management in dense metropolitan cores. The United States and India represent contrasting growth vectors driven by regulatory and climatic pressures respectively.
United States
Commercial developers face escalating permeable surface mandates from EPA stormwater guidelines in new construction projects. The Infrastructure Investment and Jobs Act channels federal funding toward resilient surface infrastructure in flood-prone municipalities. Texas and Florida metropolitan areas are deploying extra-thick permeable systems for parking and service roadways in commercial zones.
Germany
Municipal pedestrian plaza renovations in Berlin, Hamburg, and Munich specify low-carbon concrete and natural stone under EU Green Deal procurement criteria. REACH chemical compliance frameworks are accelerating reformulation of wet-cast manufacturing processes across domestic producers. The Ruhr industrial corridor hosts concentrated fabrication capacity serving heritage restoration projects across Western Europe.
China
Shanghai, Beijing, and Shenzhen urban renewal programs prioritize durable permeable concrete for pedestrian infrastructure under dual carbon goals and GB construction material standards. Tier-one city procurement platforms are embedding lifecycle cost analysis into surface material bid evaluation. The Yangtze River Delta manufacturing cluster supplies wet-cast and pressed formulations for domestic and export markets.
India
The Smart Cities Mission is generating specification pull for high-albedo paving materials in urban heat island mitigation programs across municipal park and plaza renovations. BIS certification requirements for construction materials are structuring import access for foreign formulations. Maharashtra and Karnataka state capitals are piloting reflective surface specifications in commercial district redevelopment.
United Kingdom
County council procurement frameworks have shifted bid evaluation toward 20-year maintenance-inclusive contracts using embedded lifecycle cost software. Marshalls plc and domestic competitors serve this demand through vertically integrated quarry-to-site operations. The Midlands and North England retain concentrated natural stone extraction serving heritage plaza specifications.
Global Commercial Paving Slabs Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in commercial paving slabs. The upper tier commands specification influence in architect-directed projects and municipal frameworks through captive raw material access and in-house fabrication capabilities. Mid-scale specialists compete on installation speed and regional distributor relationships for contractor-channel volume. The dominant competitive moves are backward integration into quarry resources and formulation R&D partnerships for low-carbon binder technologies.
Within the integrated leader tier, Marshalls plc and CRH plc occupy positions spanning multiple price segments and geographies through diversified manufacturing footprints. Hanover Architectural Products exemplifies the architect-specified specialist archetype with concentrated presence in premium commercial developments. These three entities anchor competitive dynamics across the United States, United Kingdom, and broader European specification pools.
| Leading Market Players |
|---|
| Hanover Architectural Products |
| Unilock Ltd. |
| Artistic Paver Manufacturing Inc. |
| Belgard |
| Cambridge Pavingstones |
| Tile Tech Pavers |
| Marshalls plc |
| CRH plc |
| Tobermore |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at wet-cast concrete facilities in China's Yangtze River Delta and Germany's Ruhr corridor anchors both supply concentration and price floors across the commercial paving slabs market. Scale economies in permeable concrete batching compress unit costs for volume producers while quarry resource scarcity in premium stone segments elevates logistics-adjusted price baselines for heritage-specification projects.
Pricing Analysis
Project-based contracting dominates municipal procurement while spot purchasing persists among contractor channels for private developments. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified stone from wet-cast concrete and pressed clay variants. Cost compression in standard-grade concrete is intensifying because cement input volatility under carbon border adjustment pressures squeezes margin structures. Contractor segments exhibit highest price sensitivity due to distributor markup exposure, while municipalities demonstrate lowest sensitivity as lifecycle cost analysis embeds 20-year maintenance obligations into bid evaluation.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores energy input risks for clinker-dependent concrete production across Middle Eastern supply corridors. Manufacturing gravity centers on China, Germany, and the United Kingdom for wet-cast and pressed formulations, with Italy and Spain anchoring premium stone fabrication. Raw material dependencies rest on Portland cement, natural aggregates, and biochar additives for carbon-negative formulations. Single-source vulnerability concentrates in quarry-controlled granite and limestone extraction zones. Distribution runs through vertically integrated quarry-to-site operations for municipal frameworks and layered distributor networks for contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal embodied carbon disclosure mandates are accelerating a technological inflection that restructures specification eligibility and procurement access across commercial hardscaping markets.
For Market Incumbents: Compound captive quarry access and in-house batching capabilities to defend against geopolymer binder displacement in municipal specification pools. Accelerate REACH-compliant sealant reformulation ahead of chemical restriction expansions. Prioritize backward integration into regional aggregate reserves to secure logistics cost advantages for distant infrastructure projects. For New Entrants and Emerging Players: GB Standard certification fast-track programs in China's tier-one cities offer the most penetrable entry vector for low-carbon concrete formulations. Target India's Smart Cities Mission high-albedo specifications where BIS certification barriers remain lower than in saturated European markets. Lead with direct municipality contracting models that bypass established distributor relationships through embedded lifecycle cost software partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with captive raw material access and in-house R&D capabilities for alkali-activated binders. Long-term viability hinges on specification influence in architect-directed projects and municipal framework dominance. Watch for geopolymer formulation adoption rates in German pilot zones as the inflection indicator for broader EU procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Resources | Captive granite and limestone supply secures logistics cost control for heritage plaza specifications across Germany and the United Kingdom. |
| Low-Carbon Binder R&D Partnerships | Geopolymer and biochar-integrated formulations qualify for EU public procurement preference thresholds under Green Deal mandates. |
| Direct Municipality Contracting Channels | Bypassing distributor networks captures margin expansion as lifecycle cost analysis embeds into UK county council and Chinese tier-one city procurement platforms. |
| REACH-Compliant Sealant Reformulation | Bio-based surface treatments maintain market access as ECHA chemical restrictions accelerate across wet-cast manufacturing processes. |
| High-Albedo Product Line Expansion | Reflective surface specifications address India's Smart Cities Mission urban heat island mitigation programs in Maharashtra and Karnataka state capitals. |
Methodological Framework
Cross-validation between municipal procurement officer interviews and customs trade data anchors the qualitative findings in this analysis. Primary fieldwork engaged plant managers at wet-cast facilities, procurement leads at hardscaping contractors, distribution channel partners, and technical R&D directors in binder formulation. Secondary validation drew from EPA stormwater guideline filings, EU Ecodesign regulation disclosures, China's GB standard certification databases, and SEC 10-K extracts from publicly traded building materials conglomerates. Bottom-up project pipeline enumeration and top-down construction spending allocation triangulate volume estimates.
Sensitivity analysis around cement price volatility and carbon border adjustment implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition tier, application load requirement, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from regression against construction output indices and infrastructure spending commitments. Industry-specific forecast inputs incorporate permeable surface mandate adoption curves and skilled masonry labor availability constraints.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and China's dual carbon goal continuity; material deviation in regulatory stringency or construction investment flows would warrant model refresh. Practitioners should keep alternative scenarios live as REACH chemical restriction expansions and GB Standard certification timeline variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Exterior Sheathing Market
Building Materials
Refractory Cement Market
Building Materials
Composite Decking and Railing Market
Building Materials
Foam Concrete Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
East Africa White Cement Market
Building Materials
Granite Market
Building Materials
Aluminum Door and Window Market
Building Materials
Natural Stone Market
Building Materials
Construction Coatings Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Rubbing Bricks Market
Building Materials
Exterior Doors Market
Building Materials
North America Engineered Stone Market