
 Trommel Screen Market | 2026-2036
Trommel Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Trommel Screen Market Analytics
The EU Green Deal's circular economy action plan is realigning procurement criteria for waste processing equipment across European municipalities. Multotec (Pty) Ltd. leverages its dense media separation expertise to anchor aftermarket screen panel demand in African mining corridors. Vermeer Corporation dominates the mobile trommel segment through its controlled dealer network in North American construction markets. McCloskey International extends its footprint by competing aggressively on engine emission compliance in Canadian aggregates operations.
A trommel screen is a cylindrical rotating drum with perforated or mesh screening surfaces that mechanically separates materials by particle size through gravitational and rotational forces. Drum diameters typically range from 1.5 to 3.5 meters with rotational speeds of 10-25 RPM, optimized for throughput rates exceeding 200 tons per hour in mining applications. Heavy-duty steel trommels sustain the highest replacement part revenue pools due to abrasive wear in mining and construction, while mobile units represent the fastest-expanding configuration as contractors prioritize fleet flexibility over fixed plant investment. Wire mesh and rubber material segments diverge sharply in margin structure, with composite-lined drums commanding premium positioning in corrosive recycling environments.
EPA landfill regulations and state-level organics diversion mandates in California, Washington, and Vermont are tightening permissible contamination rates for municipal solid waste streams. The EU F-Gas Regulation and REACH compliance requirements for industrial machinery are reshaping material specifications and hydraulic fluid formulations in equipment sold across European member states. Stakeholders must monitor how emerging extended producer responsibility frameworks in packaging and construction debris reshape capital deployment timing for replacement screening infrastructure.
Market Dynamics
Municipal landfill diversion mandates and organics processing infrastructure buildouts constitute the dominant structural force reshaping trommel screen procurement cycles across waste management agencies. Equipment replacement timelines compress as jurisdictions race to meet binding contamination reduction targets.
Growth Catalysts
- EU Waste Framework Directive:Mechanical-biological treatment plant retrofits in Germany drive high-throughput trommel system demand as operators replace aging screening infrastructure.
- Construction aggregates recovery:Urban demolition waste streams in the United States require mobile trommel deployment for on-site material sorting and landfill avoidance.
- Compost quality standards:State-level organics mandates in California, Washington, and Vermont tighten permissible contamination rates, forcing screening technology upgrades.
Market Restraints
- Steel price volatility:Abrasion-resistant plate and wire mesh input costs fluctuate with raw material indices, compressing margins for heavy-duty drum manufacturers.
- Specialized fabrication concentration:Precision welding and drum balancing capabilities cluster in Upper Midwest industrial corridors, creating supply bottleneck risks.
- Hydraulic system substitution:Electric drive trommels displace diesel-hydraulic units in indoor recycling facilities, stranding existing dealer service infrastructure.
Strategic Opportunities
- Indian municipal solid waste rules:Swachh Bharat Mission 2.0 funding unlocks mechanized screening procurement for tier-2 city waste processing plants.
- Biomass fuel preparation:Wood chip and agricultural residue sizing for co-firing applications creates new trommel specification requirements in Nordic district heating markets.
- Sensor-trommel convergence:Near-infrared and X-ray transmission integration enables real-time contaminant rejection during municipal waste sorting operations.
Industry Challenges
- Welder certification scarcity:ASME Section IX-qualified pressure vessel fabricators command premium wages, extending drum manufacturing lead times.
- Legacy control system integration:PLC retrofit compatibility with existing SCADA architectures complicates upgrade paths for fixed plant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trommel Screen Market |
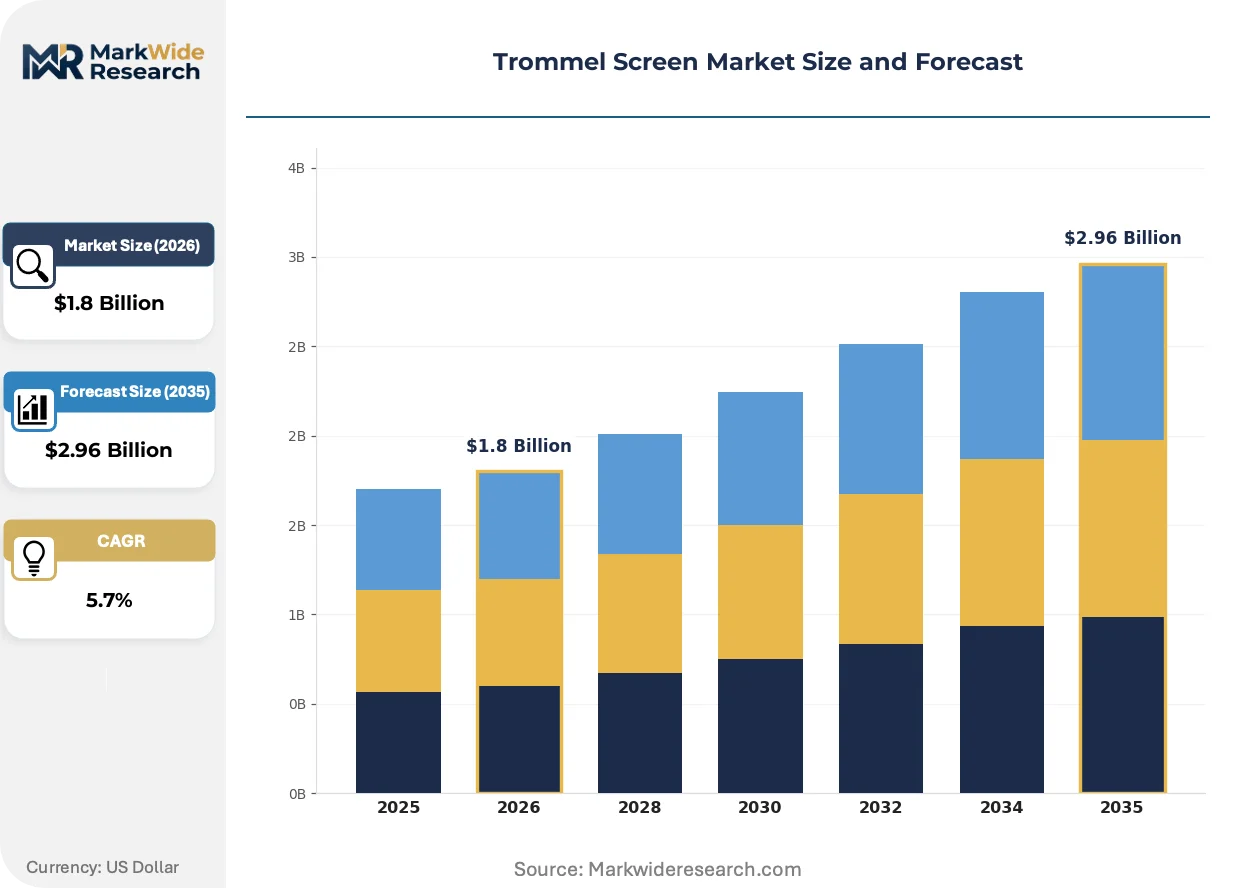
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Heavy-Duty, Medium-Duty, Light-Duty, Mobile Application: Construction, Mining, Recycling, Agriculture Material: Steel, Rubber, Wire Mesh, Composite End User: Industrial, Commercial, Municipal, Private |
| Companies Covered | Multotec (Pty) Ltd., Screen Machine Industries, Vermeer Corporation, Eggersmann GmbH, Sandvik AB, Terex Corporation, McCloskey International, Zhengzhou Sinolion Machinery, Metso Outotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trommel Screen Market Evolving Landscape
Equipment architecture is fragmenting between fixed high-capacity installations and mobile contractor-deployable units, with digital integration and alternative drive systems reshaping competitive specifications across both categories.
Composite rubber and polyurethane screen panel technology is modularizing drum maintenance protocols in corrosive recycling environments. Material recovery facility operators in the Netherlands and Belgium adopt segmented lining systems to reduce scheduled downtime. The technology is modularizing aftermarket service revenue structures away from full drum replacement toward component-level refresh cycles.
REACH compliance requirements for industrial machinery are mandating reformulated hydraulic fluids and sealed bearing specifications across equipment sold into European member states. Manufacturers must certify material composition disclosures for screen panels and structural steel to maintain CE marking validity. German mechanical-biological treatment plants face the steepest compliance retrofit timelines under concurrent F-Gas Regulation phase-down schedules.
Rental and lease-to-own structures are displacing outright purchase in North American construction and demolition waste segments. Fleet flexibility priorities among regional contractors favor short-term equipment access over fixed plant capital commitment. Equipment utilization tracking via telematics is most visible in Texas and Florida aggregate operations where seasonal demand volatility rewards asset-light positioning.
Trommel Screen Market Segmentation
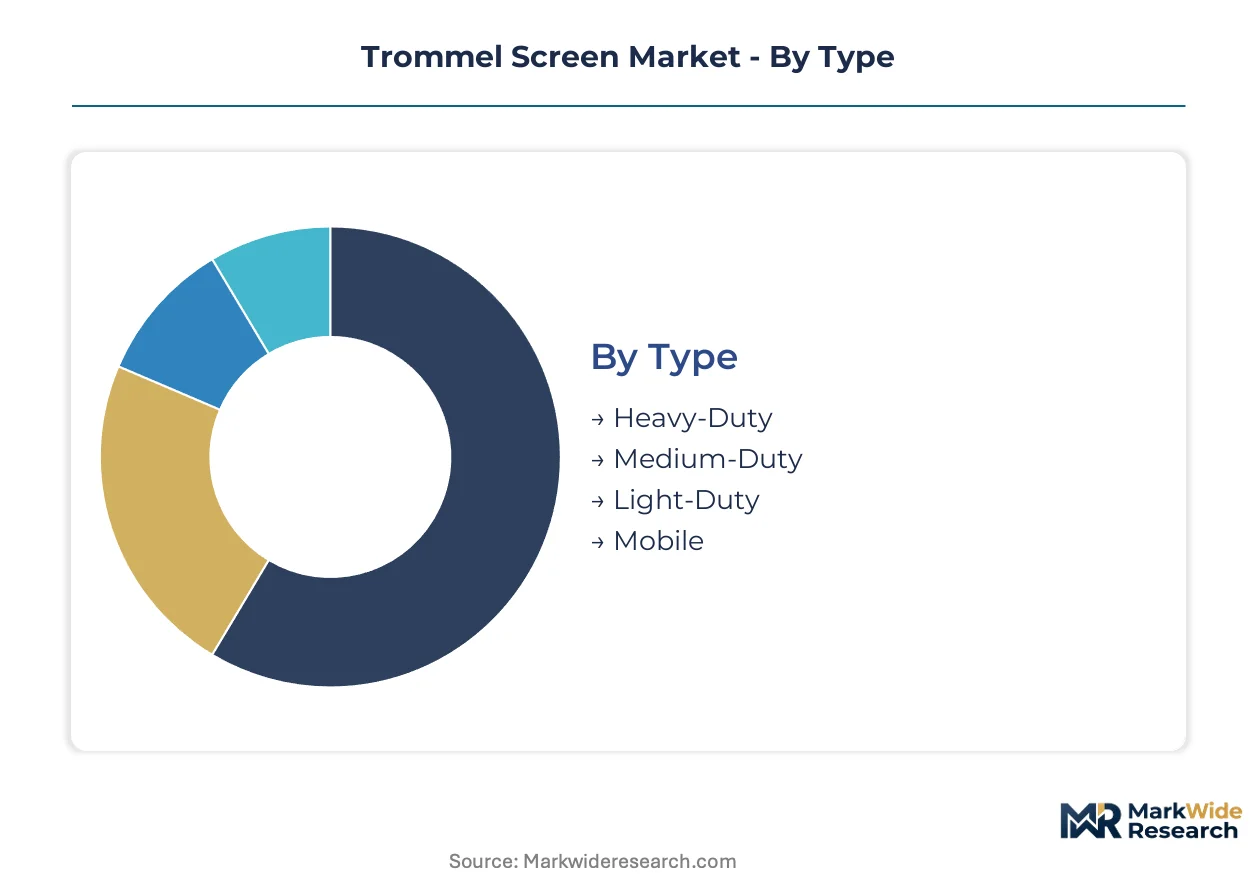
Trommel screen procurement splits sharply across duty ratings, mobility requirements, and end-use contamination profiles. Capital deployment patterns diverge between fixed infrastructure investments and contractor fleet flexibility priorities.
Type:
Capital intensity escalates with drum diameter and structural reinforcement requirements, concentrating investment in heavy-duty and mobile configurations.
- Heavy-Duty:Reinforced steel drum construction withstands abrasive mining feedstocks and demolition debris at throughput rates exceeding 200 tons per hour. German mechanical-biological treatment plants drive replacement demand as operators retire aging fixed installations.
- Mobile:Trailer-mounted or track-based units prioritize rapid site relocation over maximum throughput. Texas and Florida aggregate contractors favor rental-access models to navigate seasonal demand volatility without fixed plant commitment.
- Medium-Duty:Balances structural durability against capital outlay for mid-scale recycling operations.
- Light-Duty:Serves composting facilities and small-scale agricultural sorting with minimal abrasive wear exposure.
Most installed capacity flows through Heavy-Duty. Expansion is steepest in Mobile.
Application:
Regulatory pressure intensity varies by waste stream type, reshaping equipment specification priorities across end-use verticals.
- Recycling:Material recovery facilities in the Netherlands and Belgium adopt segmented rubber lining systems to reduce scheduled downtime from corrosive municipal waste exposure. California's organics diversion mandates force screening technology upgrades to meet tightened contamination thresholds.
- Construction:Urban demolition waste streams require on-site trommel deployment for aggregate recovery and landfill avoidance. Washington state contractors face compressed project timelines that favor mobile unit rental over fixed plant investment.
- Mining:Abrasive ore processing sustains the highest replacement part revenue pools for wire mesh and steel drum components.
- Agriculture:Wood chip and agricultural residue sizing for biomass co-firing creates specification requirements in Nordic district heating supply chains.
Volume concentrates in Mining. Regulatory momentum is strongest in Recycling.
Material:
Margin structure diverges sharply between commodity steel inputs and engineered composite formulations targeting corrosive environments.
- Steel:Abrasion-resistant plate construction dominates heavy-duty mining applications where replacement cycles generate predictable aftermarket revenue. Raw material price volatility compresses fabricator margins during commodity spike periods.
- Composite:Polyurethane and rubber formulations command premium positioning in European recycling facilities subject to REACH compliance requirements for material composition disclosure.
- Rubber:Modular panel systems enable component-level refresh rather than full drum replacement.
- Wire Mesh:Standard screening surface for light-duty agricultural and commercial applications with minimal wear exposure.
Steel retains the largest installed base. Composite formulations are gaining share fastest in corrosive processing environments.
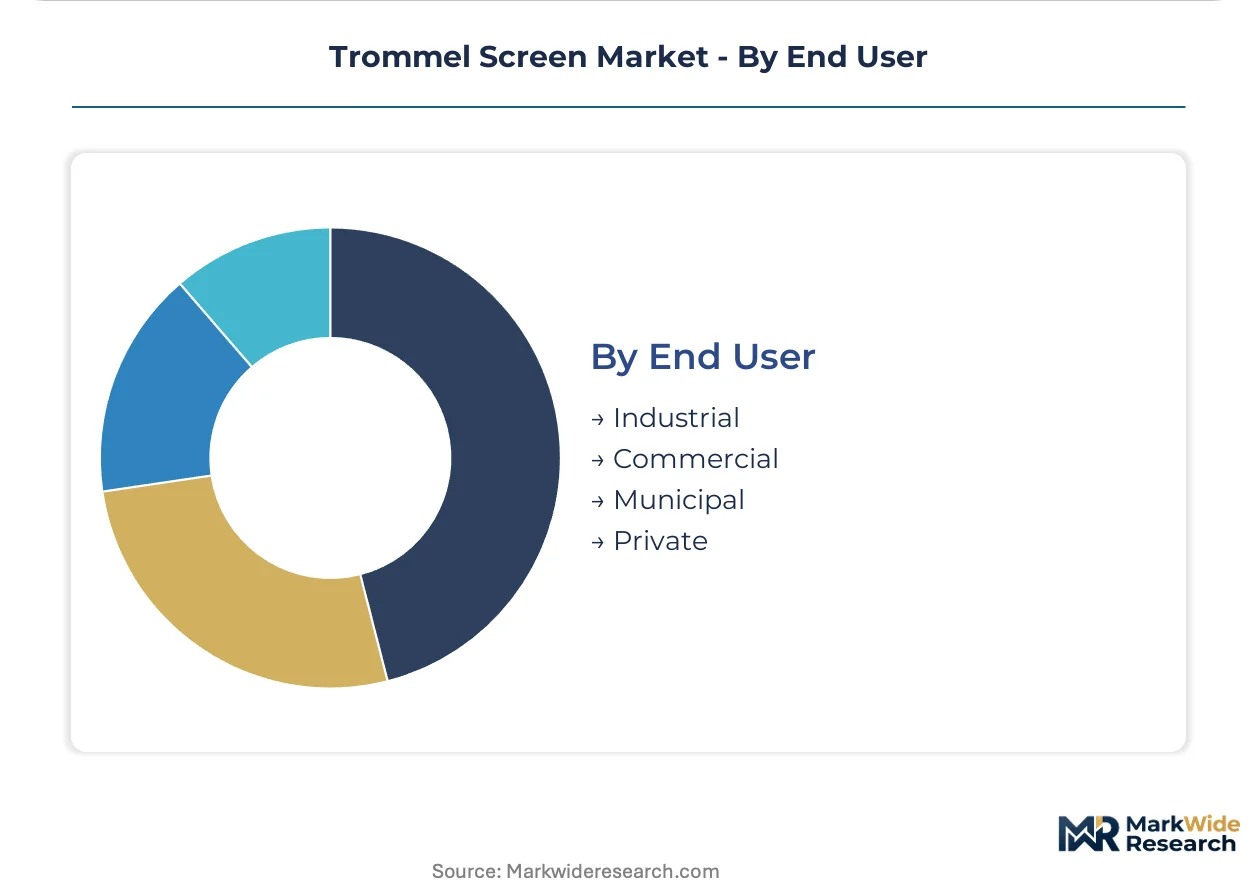
End User:
Procurement authority and capital access differentiate customer segments, with municipal agencies subject to binding diversion timelines.
- Municipal:Waste management agencies across Germany and California deploy high-throughput fixed systems to meet landfill diversion targets under EU Waste Framework Directive and state-level organics mandates. Funding cycles align with political procurement windows.
- Industrial:Mining and aggregates operators prioritize equipment availability and aftermarket service density over initial capital outlay.
- Commercial:Private waste haulers and material processors balance throughput requirements against fleet standardization needs.
- Private:Individual contractors and small-scale composting operations represent price-sensitive demand with minimal specification complexity.
Municipal agencies control the largest committed capital pipeline. Industrial users drive aftermarket service revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered mechanical-biological treatment infrastructure for municipal waste processing. Trommel screen procurement now concentrates in jurisdictions with binding landfill diversion timelines and active construction demolition recovery programs.
Germany
Mechanical-biological treatment plant retrofits drive replacement demand for high-throughput trommel systems. The EU Waste Framework Directive and concurrent F-Gas Regulation phase-down schedules compress compliance retrofit timelines. Bavaria and North Rhine-Westphalia host the densest clusters of waste processing infrastructure requiring screening technology upgrades.
United States
State-level organics mandates in California, Washington, and Vermont tighten contamination thresholds for municipal solid waste streams. EPA landfill regulations enforce permissible contamination rates that force screening technology deployment. Texas and Florida aggregate contractors favor mobile unit rental models to navigate seasonal demand volatility without fixed plant capital commitment.
Netherlands
Material recovery facility operators adopt segmented rubber lining systems to reduce scheduled downtime from corrosive municipal waste exposure. REACH compliance requirements mandate reformulated hydraulic fluids and sealed bearing specifications for equipment sold into European member states. The Randstad region concentrates recycling infrastructure investment under circular economy procurement criteria.
India
Swachh Bharat Mission 2.0 funding unlocks mechanized screening procurement for tier-2 city waste processing plants. The Central Pollution Control Board enforces municipal solid waste rules that mandate landfill diversion targets. Maharashtra and Gujarat industrial corridors see concentrated deployment of screening infrastructure for urban waste management buildouts.
Canada
Aggregates operations prioritize engine emission compliance in equipment specifications for mining and construction applications. Canadian Environmental Protection Act regulations shape hydraulic fluid formulations and material composition disclosures. Ontario and British Columbia host the primary clusters of mining and demolition waste processing infrastructure requiring trommel deployment.
Trommel Screen Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the trommel screen market structure. Heavy-duty drum fabricators with in-house welding and balancing capabilities anchor the premium tier, while mobile equipment specialists leverage dealer networks for fleet flexibility. The market fragments across three strategic archetypes: mining-focused heavy-duty manufacturers, construction-oriented mobile unit providers, and recycling-specialized composite lining system suppliers. Competitive moves concentrate on aftermarket service density expansion and electric drive system development to displace diesel-hydraulic units in indoor facilities.
Among North American mobile equipment specialists, Vermeer Corporation and McCloskey International exemplify the contractor-access model prioritizing fleet flexibility over fixed plant investment. Terex Corporation occupies a position spanning heavy-duty mining and mobile construction segments. German fabricators including Eggersmann GmbH anchor the European mechanical-biological treatment retrofit market. Multotec (Pty) Ltd. represents the aftermarket service archetype leveraging dense media separation expertise in African mining corridors. Chinese manufacturers including Zhengzhou Sinolion Machinery sit within the scale-driven export tier supplying emerging market infrastructure buildouts.
| Leading Market Players |
|---|
| Multotec (Pty) Ltd. |
| Screen Machine Industries |
| Vermeer Corporation |
| Eggersmann GmbH |
| Sandvik AB |
| Terex Corporation |
| McCloskey International |
| Zhengzhou Sinolion Machinery |
| Metso Outotec |
| Others |
Value Network & Pricing Analysis
California's organics diversion mandates and similar state-level contamination thresholds across Washington and Vermont force specification upgrades that compress supplier margins. Equipment fabricators must absorb certification costs for REACH-compliant hydraulic fluids and sealed bearing assemblies while competing against rental-model disruptors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers bundling telematics integration and extended service contracts. Price differentiation hinges on drum diameter specifications and aftermarket service density, with heavy-duty mining configurations commanding substantial premiums over mobile contractor units. Cost compression in standard-tier mobile equipment is intensifying because fleet rental operators prioritize utilization metrics over ownership. Municipal agencies exhibit the lowest price sensitivity due to grant-funded procurement windows, while individual contractors and small-scale composting operations represent the most price-constrained demand segment.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and South Africa anchor aftermarket parts fulfillment for screen panels and hydraulic components. Manufacturing draws from abrasion-resistant steel plate suppliers in China and India, composite rubber formulators in the Netherlands and Belgium, and precision welding capabilities concentrated in Upper Midwest industrial corridors. Single-source vulnerability in ASME Section IX-qualified pressure vessel fabricators extends drum manufacturing lead times. Distribution runs through authorized dealer networks for mobile units and direct OEM relationships for fixed plant installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH compliance costs and emerging market infrastructure subsidies, with tier-2 Indian cities offering procurement windows absent stringent material disclosure requirements.
For Market Incumbents: Cement aftermarket service density in African mining corridors and German mechanical-biological treatment retrofit markets before electric drive trommels displace diesel-hydraulic units and strand existing dealer infrastructure. Prioritize backward integration into composite rubber panel production to capture premium positioning in corrosive recycling environments. For New Entrants and Emerging Players: Dealer networks in Texas and Florida aggregate contractors represent the most penetrable channel, given seasonal demand volatility and rental-model acceptance. Target biomass fuel preparation specifications in Nordic district heating supply chains, where wood chip sizing requirements outpace incumbent coverage. Pursue sensor-trommel convergence partnerships with near-infrared and X-ray transmission technology providers to differentiate municipal waste sorting offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with aftermarket service specialists possessing dense media separation expertise and established screen panel replacement revenue streams. Long-term viability favors fabricators with in-house welding and drum balancing capabilities serving mining and construction verticals. Monitor F-Gas Regulation phase-down schedules and extended producer responsibility framework implementations as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive System Development | Displaces diesel-hydraulic units in indoor recycling facilities subject to EPA emission standards. |
| Composite Panel Manufacturing Scale-Up | Captures premium positioning in REACH-compliant European material recovery facilities. |
| Telematics Platform Integration | Enables utilization tracking for Texas and Florida rental fleet operators navigating seasonal volatility. |
| Dealer Network Expansion | Secures contractor access models displacing outright purchase in North American construction segments. |
| Sensor Technology Partnership | Integrates near-infrared sorting for real-time contaminant rejection under California organics mandates. |
Research Methodology
Coverage spans Germany, the United States, India, and the Netherlands, with primary inputs from each market's waste management agencies and equipment operators. The approach combines interviews with maintenance directors at material recovery facilities, plant engineers at mechanical-biological treatment installations, OEM procurement teams at mining operations, and aftermarket service heads at distributor networks. Secondary validation draws from EPA landfill regulation filings, EU Waste Framework Directive implementation reports, Central Pollution Control Board enforcement data, and customs records for abrasion-resistant steel imports. Bottom-up unit deployment estimates triangulate against top-down capital expenditure projections from municipal procurement databases.
Granularity-level modeling disaggregates volume and value across drum diameter specifications, mobility configurations, material formulations, and end-user procurement authority. Segmentation dimensions include duty rating, application vertical, panel material composition, and customer type. CAGRs derive from equipment replacement cycle compression analysis and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate welder certification scarcity metrics and hydraulic system substitution rates in indoor recycling facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility and electric drive adoption curves. Outputs reflect documented assumptions around landfill diversion target enforcement and grant funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Slag Handling Equipment Market