
 Ventilation Fan Market | 2026-2036
Ventilation Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilation Fan Market Intelligence
The European Union's Ecodesign Directive for ventilation units (Lot 6) is pivoting the competitive landscape toward manufacturers capable of high-efficiency motor integration. Systemair AB leverages its European base to lead in compliant system design. Delta Electronics, Inc. specializes in advanced electronically commutated fans for original equipment manufacturers. Panasonic Corporation competes with a broad portfolio spanning residential to commercial applications, emphasizing smart controls.
A ventilation fan is a mechanical device used to move air and gases for cooling, circulation, or exhausting contaminants from a space. These devices are characterized by parameters like airflow rate, measured in cubic feet per minute (CFM), static pressure, and motor efficiency. Electronically commutated fans represent the fastest-growing technology segment due to superior energy efficiency over traditional AC fans. Within applications, demand from data centers and food processing facilities commands higher margins than standard commercial space ventilation.
Product standards are shaped by a matrix of national and regional bodies, including the EPA in the United States and compliance with GB standards in China. These regulations mandate minimum energy performance and acceptable noise levels for fans sold into commercial and residential markets. Success for manufacturers now depends on navigating fragmented energy efficiency requirements and integrating smart control capabilities to meet evolving building codes.
Market Dynamics
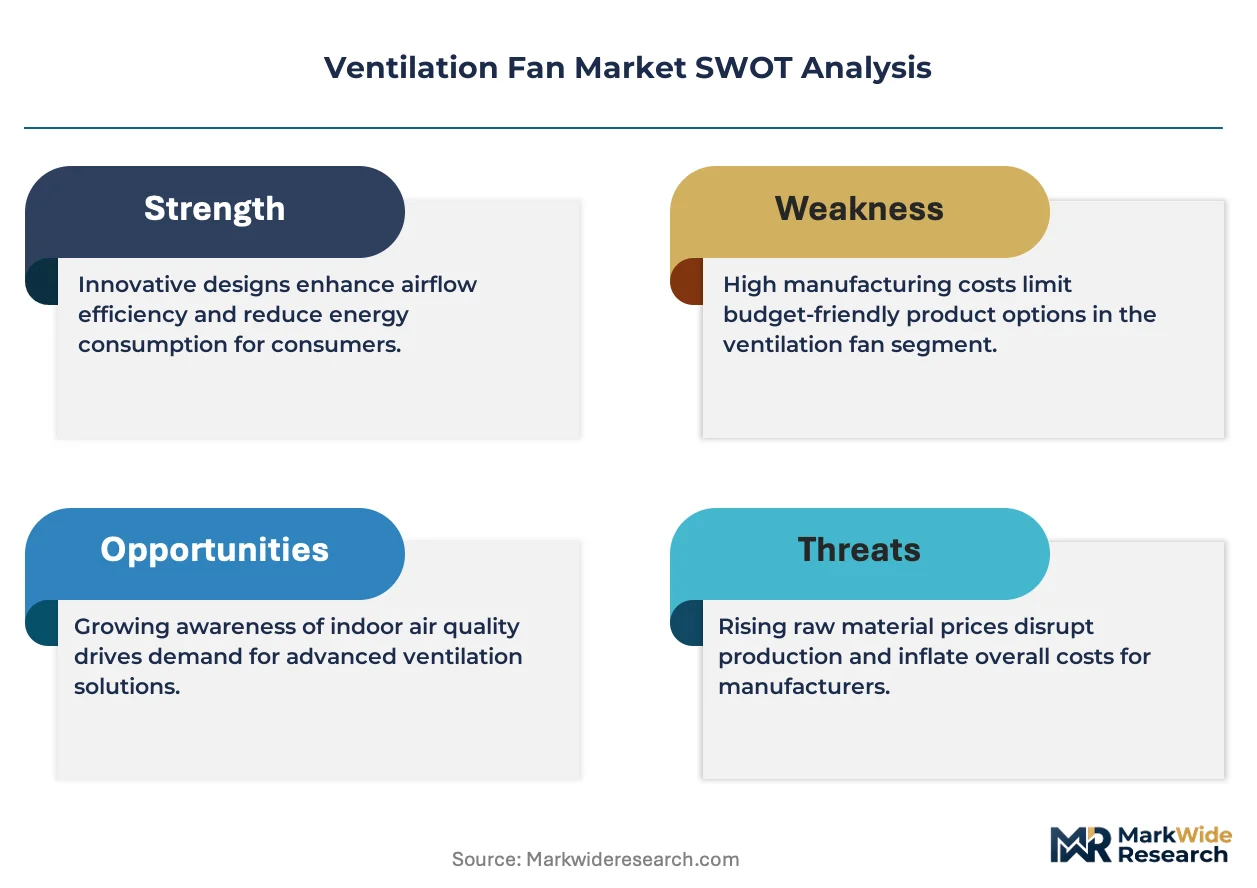
The ventilation fan market is defined by a fundamental tension between demand for higher airflow performance in specialized applications and intensifying regulatory pressure for energy efficiency. This dynamic forces innovation in motor technology and system design to meet divergent end-user requirements.
Growth Catalysts
- Data Center Expansion:The proliferation of hyperscale data centers creates sustained demand for high-static-pressure, high-efficiency fans to manage thermal loads, a critical factor for operational uptime and energy cost containment.
- Regulatory Mandates:The EU's Ecodesign Directive for ventilation units compels manufacturers to integrate higher-efficiency motors and controls, directly stimulating sales of compliant, premium-priced products across the European continent.
- Indoor Air Quality Focus:A heightened focus on indoor air quality (IAQ) in commercial and residential buildings, particularly in densely populated urban areas in Asia, is driving retrofits and new installations of advanced ventilation systems.
Market Restraints
- High Initial Cost:The upfront investment for electronically commutated (EC) fans and smart ventilation systems remains a significant barrier for adoption in cost-sensitive segments, particularly for small-to-medium commercial building retrofits.
- Raw Material Dependency:Production of high-efficiency permanent magnet motors depends on a supply chain for rare earth elements, which is geographically concentrated and subject to price volatility and geopolitical risks.
- Legacy Infrastructure Constraints:Retrofitting modern, often larger, ventilation units into older buildings with pre-existing, size-constrained ductwork presents significant technical and financial challenges for installers and building owners.
Strategic Opportunities
- Controlled Environment Agriculture:The expansion of vertical farming and indoor agriculture creates a new application for specialized fans that provide precise airflow control, humidity management, and CO2 distribution for optimal crop yields.
- IoT and AI Integration:Integrating IoT sensors and AI-driven analytics enables predictive maintenance and demand-controlled ventilation, offering new revenue streams through software-as-a-service (SaaS) models and performance-based contracts.
- Emerging Economies:Rising disposable incomes and building standards in countries like India and Brazil create untapped markets for residential ventilation solutions, including kitchen exhaust fans and whole-house mechanical ventilation.
Industry Challenges
- Fragmented Compliance Standards:Manufacturers face complexity and increased certification costs navigating a patchwork of regional energy efficiency regulations, such as EPA rules in the United States and GB standards in China.
- Interoperability with Building Systems:Ensuring seamless communication and integration between new smart ventilation fans and a diverse landscape of legacy building management systems (BMS) remains a persistent technical hurdle for system integrators.
- Technician Skill Gaps:A shortage of HVAC technicians trained in the installation, commissioning, and maintenance of advanced EC motor-based systems and their associated digital controls can slow deployment and impact system performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilation Fan Market |
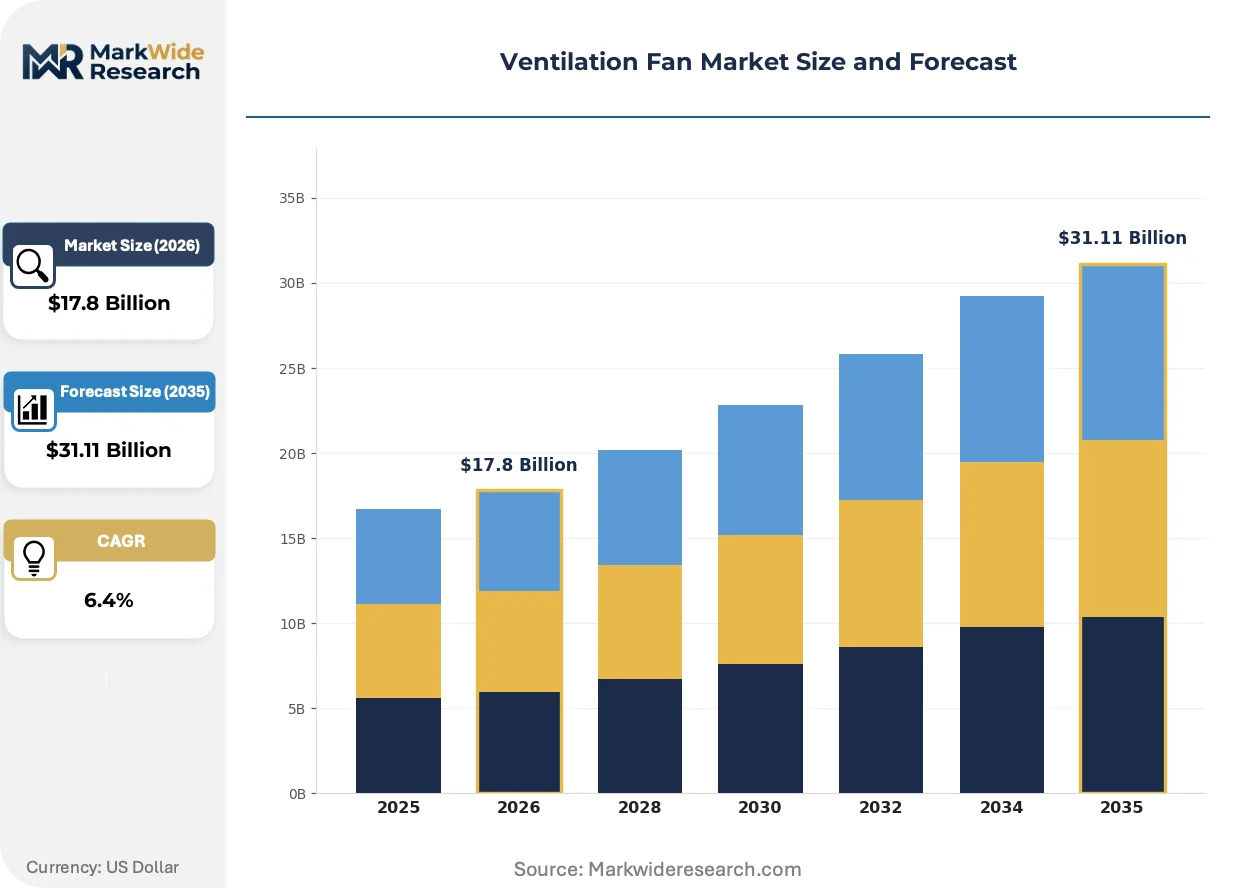
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Exhaust Fans, Inline Fans, Mixed Flow Fans Technology: DC Fans, AC Fans, Electronically Commutated Fans, Brushless Motors, Permanent Magnet Motors Application: HVAC Systems, Agricultural Ventilation, Commercial Spaces, Food Processing, Data Centers End User Industry: Manufacturing Plants, Food & Beverage Facilities, Technology Firms, Educational Institutions |
| Companies Covered | Daikin Industries, Ltd, Panasonic Corporation, Delta Electronics, Inc., Lennox International Inc., Systemair AB, Greenheck Fan Corporation, Crompton Greaves Consumer Electricals Limited, Mitsubishi Electric Corporation, Broan-NuTone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilation Fan Market Strategic Shifts & Innovations
Product evolution is moving towards intelligent, self-regulating systems that optimize performance based on real-time environmental data. This shift from static components to dynamic systems is driven by parallel advances in motor technology, sensor integration, and stringent energy codes.
Smart fan technology incorporates embedded sensors and microcontrollers to monitor conditions like temperature, humidity, and air quality. Commercial buildings and data centers are the primary adopters, seeking to reduce energy consumption and improve environmental control. This on-board intelligence is automating the process of airflow regulation, dynamically adjusting fan speed to meet precise demand without requiring external control system intervention.
China’s national 'dual carbon goals' are accelerating updates to GB standards governing motor energy efficiency. The policy has direct industrial consequences, mandating a phase-out of less efficient fan types in favor of higher-performance alternatives. This regulatory pressure most acutely affects the industrial and commercial ventilation segments, forcing a rapid market-wide transition toward more advanced motor technologies to achieve compliance.
A notable shift in buying behavior involves the move from purchasing standalone fans to specifying complete, performance-guaranteed ventilation solutions. This trend disrupts the business model of traditional component distributors, creating an advantage for system integrators and OEMs that can deliver and validate integrated packages. This procurement pattern is most pronounced in North American and European markets for critical infrastructure projects like hospitals and laboratories.
Ventilation Fan Market Segmentation
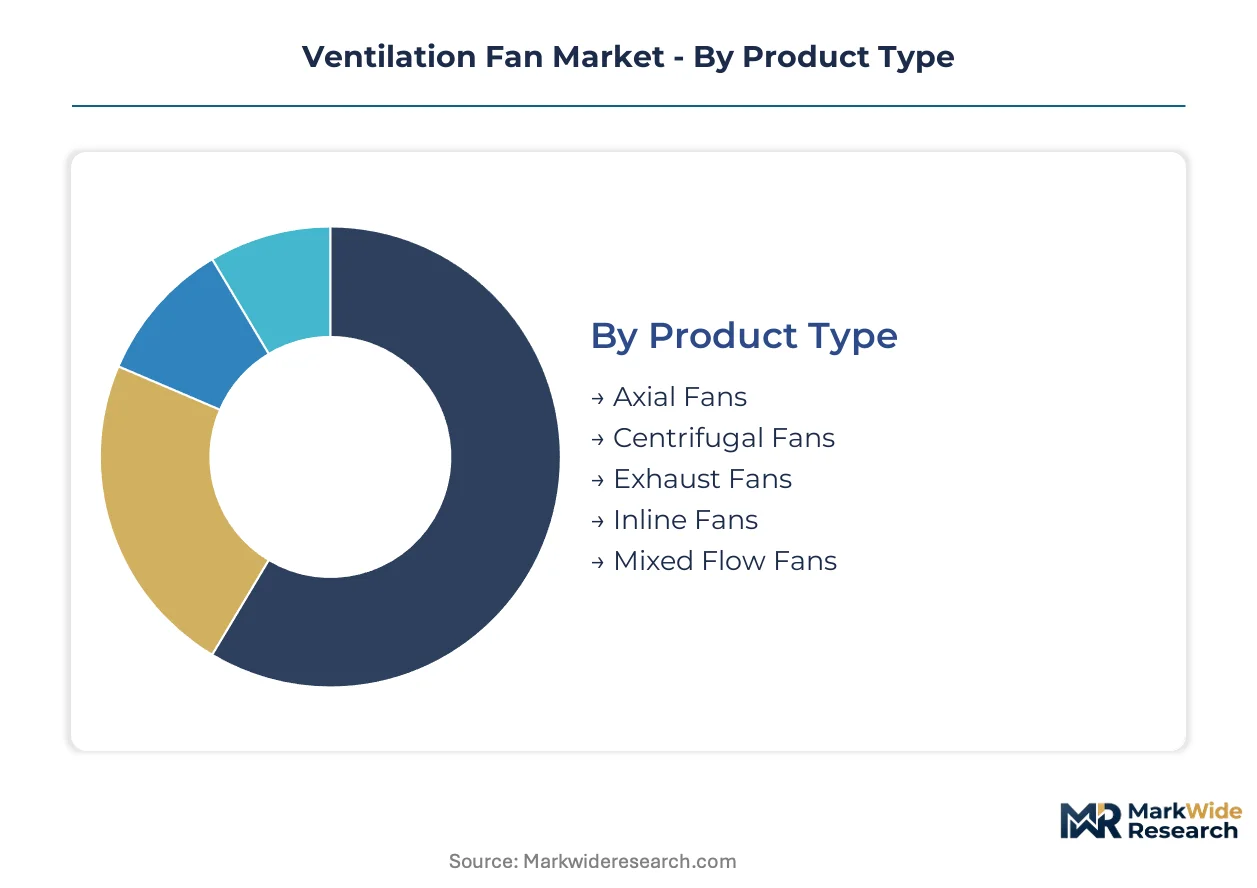
Understanding the ventilation fan market through segmentation reveals distinct demand drivers and technological preferences across various applications. This detailed breakdown helps manufacturers tailor product development and sales strategies to specific end-user requirements and regulatory environments.
Product Type:
Ventilation fan product types differentiate based on airflow direction, pressure generation, and installation needs, addressing diverse environmental control challenges.
- Centrifugal Fans:These fans move air perpendicularly to the fan axis, generating high static pressure suitable for ducted systems and industrial applications. Demand from data centers for effective thermal management drives significant volume.
- Axial Fans:Axial fans move air parallel to the fan axis, providing high airflow at lower static pressures, commonly used in general ventilation and HVAC systems. Residential and commercial building projects frequently specify these units for air circulation.
- Exhaust Fans:These devices remove stale or contaminated air from a space, crucial for maintaining indoor air quality in kitchens and bathrooms.
- Inline Fans:Designed for duct installation, inline fans offer versatile airflow solutions for both supply and exhaust applications within confined spaces.
- Mixed Flow Fans:Combining characteristics of both axial and centrifugal designs, mixed flow fans provide a balance of high airflow and moderate static pressure.
Centrifugal Fans lead on scale; Mixed Flow Fans lead on momentum.
Technology:
Technology segmentation highlights varying levels of energy efficiency and initial investment across fan motor designs.
- Electronically Commutated Fans:EC fans integrate DC motors with onboard electronics, offering superior energy efficiency and precise speed control compared to traditional AC motors. The EU's Ecodesign Directive compels manufacturers to adopt these advanced motor technologies.
- Permanent Magnet Motors:These motors utilize permanent magnets to enhance efficiency and power density, forming a core component of high-performance EC fans and industrial drives. Production relies on a supply chain for rare earth elements.
- AC Fans:Alternating current fans represent traditional, cost-effective technology, widely used in various general-purpose ventilation applications.
- DC Fans:Direct current fans operate at lower voltages, finding applications in electronics cooling and small-scale ventilation systems.
- Brushless Motors:A type of DC motor, brushless motors offer improved efficiency and longer lifespan compared to brushed designs, often integrated into EC fan technology.
Electronically Commutated Fans exhibit the steepest expansion trajectory due to energy efficiency mandates.
Application:
Ventilation fan applications vary significantly in their required airflow, pressure, and control precision.
- Data Centers:These facilities require high-static-pressure, high-efficiency fans for precise thermal management to ensure operational uptime and energy cost containment. Hyperscale data centers represent a sustained demand segment.
- HVAC Systems:Heating, ventilation, and air conditioning systems utilize fans for air circulation, temperature regulation, and indoor air quality maintenance in residential and commercial buildings. Regulatory mandates for energy efficiency shape product design.
- Food Processing:This sector demands specialized ventilation to maintain hygienic conditions, control temperature, and extract fumes, adhering to stringent health and safety standards.
- Commercial Spaces:Fans in commercial buildings focus on occupant comfort, air circulation, and compliance with indoor air quality standards.
- Agricultural Ventilation:This application involves controlling environmental conditions in greenhouses and vertical farms for optimal crop growth and livestock welfare.
Data Centers command the highest margins due to critical uptime requirements and specialized cooling needs.
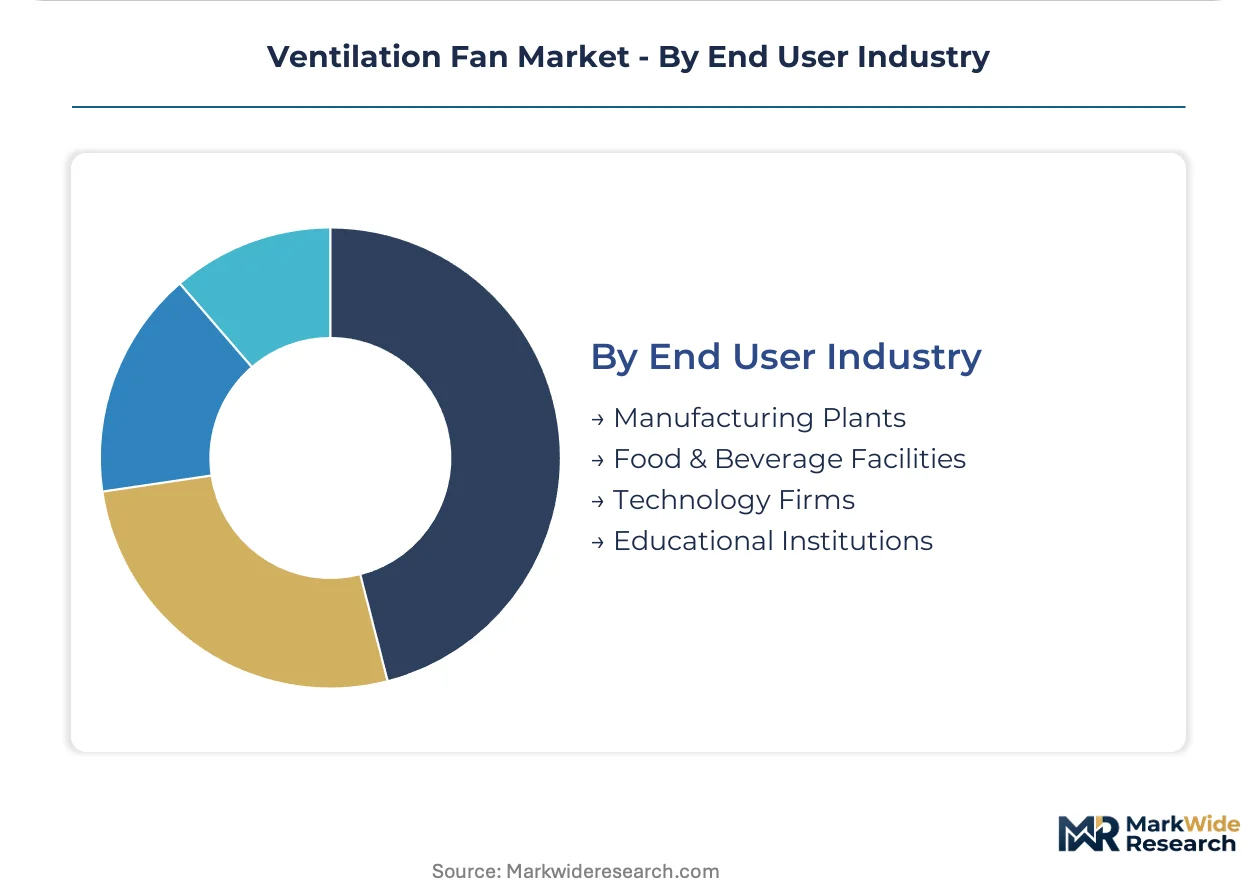
End User Industry:
End-user industries dictate fan specifications based on their unique operational environments and regulatory compliance needs.
- Manufacturing Plants:Industrial facilities require robust ventilation for process cooling, fume extraction, and maintaining safe working conditions, especially in advanced manufacturing sectors like Germany's. Demand for specialized industrial ventilation is high.
- Food & Beverage Facilities:These facilities need ventilation systems that meet strict hygiene standards for air quality, temperature control, and the removal of airborne contaminants to ensure product safety. Regulatory compliance is paramount.
- Technology Firms:This segment includes companies operating data centers, requiring advanced cooling solutions for servers and IT infrastructure.
- Educational Institutions:Schools and universities prioritize indoor air quality and energy-efficient ventilation to create healthy learning environments.
Manufacturing Plants exhibit the most diverse requirements for specialized ventilation solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ventilation fan market leverages diverse engineering and manufacturing talent pools across key regions. These concentrations drive innovation in motor technology and system design, responding to specific regional demands and regulatory pressures. This geographic distribution supports both specialized industrial applications and broad commercial deployments.
United States
The United States market demands high-efficiency fans for its expanding hyperscale data centers and commercial HVAC systems. EPA rules mandate minimum energy performance, influencing product design. Manufacturing hubs in the Midwest, particularly around Chicago, concentrate on producing advanced ventilation units.
Germany
Germany's advanced manufacturing sector drives significant demand for specialized industrial ventilation and high-efficiency HVAC systems. The EU's Ecodesign Directive compels manufacturers to innovate in motor technology. Industrial clusters in Bavaria focus on developing and deploying precision-engineered ventilation solutions.
China
China's rapid urbanization and industrial expansion create substantial demand for commercial and residential ventilation systems, alongside a focus on indoor air quality. The nation's GB standards accelerate the phase-out of less efficient fan types. Manufacturing hubs in the Yangtze River Delta are pivotal for producing advanced motor technologies.
India
India presents a growing market for residential ventilation solutions, driven by rising disposable incomes and expanding commercial construction. The Bureau of Indian Standards (BIS) sets benchmarks for product quality and safety. Major metropolitan areas like Mumbai are seeing significant installations of energy-efficient HVAC systems in new developments.
Japan
Japan's market emphasizes highly energy-efficient building systems and precision climate control for commercial and residential sectors. The Ministry of Economy, Trade and Industry (METI) sets stringent energy efficiency targets. Technology firms in the Tokyo metropolitan area lead integration of smart controls and IoT into advanced ventilation units.
Ventilation Fan Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the ventilation fan market. The market structure exhibits a tiered consolidation, with large established players holding significant shares while numerous smaller, specialized firms address niche applications. Strategic archetypes include global HVAC system providers, specialized industrial fan manufacturers, and technology-focused component suppliers. Portfolio diversification and strategic partnerships are dominant competitive moves.
Specialists in advanced motor technologies include Delta Electronics, Inc., an Inc.-registered firm, which exemplifies a focus on electronically commutated fans for original equipment manufacturers. Sweden-based Systemair AB, a leading European firm, occupies a position as a provider of compliant system designs, leveraging its regional base. Panasonic Corporation, a Japanese conglomerate, represents a broad portfolio spanning residential to commercial applications, emphasizing smart controls and integrated solutions.
| Leading Market Players |
|---|
| Daikin Industries, Ltd |
| Panasonic Corporation |
| Delta Electronics, Inc. |
| Lennox International Inc. |
| Systemair AB |
| Greenheck Fan Corporation |
| Crompton Greaves Consumer Electricals Limited |
| Mitsubishi Electric Corporation |
| Broan-NuTone |
| Others |
Cost & Logistics Intelligence
Rare earth elements, critical for permanent magnet motors, trace a path from concentrated mining and processing in specific geographies through component manufacturers to premium EC fan assemblies, influencing final product pricing across specialized applications. This upstream dependency creates a cost floor for high-efficiency fan technologies and impacts market-wide pricing strategies.
Pricing Analysis
Bundled solutions, offering integrated ventilation systems with smart controls, command project-based pricing, while standalone fan units typically follow a per-unit transactional model. Price differentiation stems from motor efficiency ratings, compliance with stringent certifications like the EU's Ecodesign Directive, and the level of customization for industrial applications. Pricing pressure intensifies for traditional AC fans due to widespread availability and competition. Data centers and critical infrastructure projects exhibit lower price sensitivity, prioritizing performance and reliability, whereas small-to-medium commercial building retrofits remain highly cost-sensitive.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of ventilation fans, particularly for commercial and residential markets. Supply concentration for advanced components relies heavily on manufacturing hubs in China for general components and specialized motor technologies from Germany and Japan. Key raw material dependencies include rare earth elements for permanent magnets and microcontrollers for smart fan integration. Geopolitical risks affecting rare earth element supply chains represent a structural risk for high-efficiency fan production. Downstream distribution typically runs through specialized HVAC distributors, original equipment manufacturers, and direct sales to large project integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage opportunities, leveraging lower component manufacturing costs in Asian economies while targeting premium European markets with stringent Ecodesign compliance requirements.
For Market Incumbents:Anchor existing market share by investing heavily in advanced motor technology research and development, particularly for electronically commutated designs. Acquire specialized firms offering AI-driven control systems to counter emerging threats from technology-focused new entrants. Reinforce channel control through strategic partnerships with established HVAC system integrators across Europe and North America. Invest in certifications for new products to meet evolving energy efficiency mandates in diverse national markets, leveraging economies of scale.
For New Entrants and Emerging Players:Launch via direct-to-project sales models, targeting niche, high-margin applications like Controlled Environment Agriculture, where precise airflow and humidity control are critical. The specialized requirements of vertical farms represent a penetrable segment for innovative fan designs. Focus go-to-market strategies on offering software-as-a-service (SaaS) solutions for demand-controlled ventilation, providing value beyond hardware. Develop modular, adaptable fan systems that can integrate seamlessly with diverse building management systems.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory complexity and advanced technology requirements favor larger, integrated players with deep R&D capabilities. Acquisition targets should include mid-sized firms specializing in advanced motor controls, sensor integration, or proprietary air purification technologies. The market favors firms with robust intellectual property in energy-efficient fan design and smart control algorithms over the next decade. A signal to watch is the sustained growth in recurring revenue streams from integrated ventilation system monitoring and optimization services.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: IoT-Enabled EC Fans | Introduces high-efficiency, smart fans capable of real-time environmental data integration. |
| Strategic Partnership: BMS Providers | Ensures seamless integration of ventilation systems with existing building management platforms. |
| Acquisition of Specialist Firm: AI/Sensor Technology | Enhances capabilities in predictive maintenance and demand-controlled ventilation algorithms. |
| Geographic Expansion: Emerging Economies | Captures new demand for residential and commercial ventilation in underserved markets. |
| Green Manufacturing Transition: Sustainable Materials | Reduces environmental footprint and aligns with global sustainability mandates and buyer preferences. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a robust data foundation. Primary research involved discussions with HVAC engineers, facility managers, procurement specialists, and product development leads across key regions. Secondary validation drew from industry association reports, national energy agency publications like EPA and METI, and company financial disclosures, triangulating data points for accuracy.
The forecast framework anchored the projection horizon to historical reference periods, building upon established market growth patterns. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived from an analysis of historical adoption rates and projected demand drivers across the modeling period. Key industry-specific forecast inputs included data center expansion plans and evolving building code updates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen geopolitical trade disputes or rapid technological disruption. The forecasts reflect assumptions regarding regulatory stability and sustained investment in energy-efficient infrastructure. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Industrial Chiller Market