
 Europe Custom Procedure Kits Market | 2026-2036
Europe Custom Procedure Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Custom Procedure Kits Market Intelligence
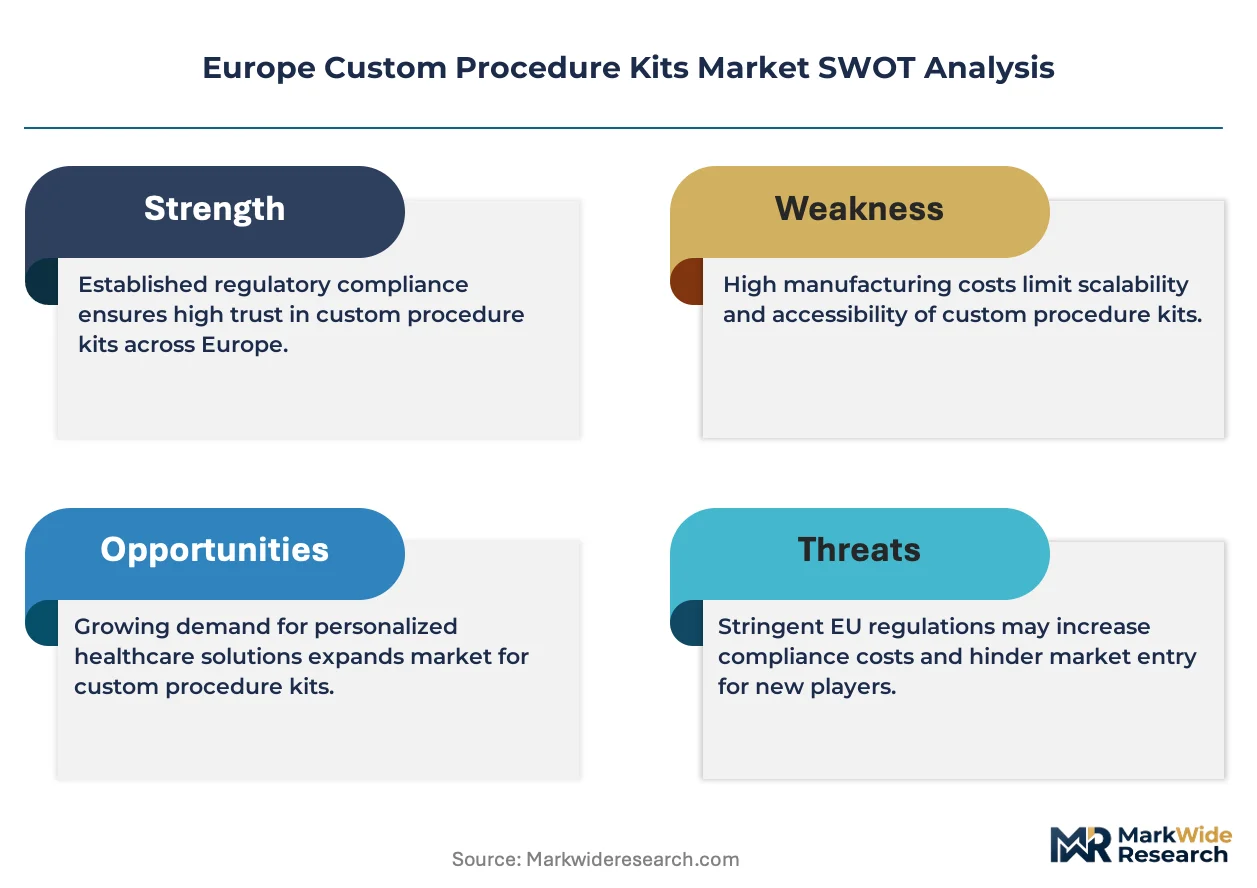
European surgical nursing labor is bifurcating between general ward staffing and specialized operating room technicians trained in sterile supply chain management. Cardinal Health leverages its pan-European distribution footprint to sustain kit assembly contracts with national hospital purchasing consortia. Mölnlycke Health Care anchors Nordic market share through proprietary surgical drape integration within custom kits. B. Braun SE competes by controlling in-house polymer extrusion for single-use kit components, reducing supplier dependency.
Europe custom procedure kits are pre-assembled, sterile collections of disposable instruments, drapes, and consumables configured to specific clinical protocols, typically gamma-sterilized and packaged in breathable polymer barrier systems for immediate use in controlled environments. Surgical kits dominate product type revenue due to procedural volume in orthopedic and cardiovascular interventions, while diagnostic kits represent the fastest-expanding segment as point-of-care testing migrates from centralized labs to ambulatory settings. Plastic material formulations lead kit construction for cost and disposability, though composite material adoption is accelerating where procedure-specific ergonomic handling requirements justify premium positioning.
CE marking under the EU Medical Device Regulation (MDR) mandates updated clinical evidence and post-market surveillance for kit manufacturers, while REACH compliance governs chemical substance disclosure in polymer components. The European Medicines Agency (EMA) coordinates with notified bodies on borderline product classifications where kits incorporate drug-device combinations. Stakeholders must monitor evolving harmonized standards under the EU Green Deal for sustainable packaging mandates that will reshape sterilization pouch specifications and waste recovery obligations across member state hospital networks.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing kit assembler margins through sterilization validation upgrades and post-market surveillance mandates, while hospital purchasing consortia consolidate procurement power across Germany, France, and the United Kingdom.
Growth Catalysts
- Bundled Payment Reforms:Germany's acute care hospital sector is accelerating standardized supply chain adoption to align procedure costs with reimbursement caps.
- Operating Room Efficiency Mandates:Hospital procurement teams across France and the United Kingdom are expanding pre-configured surgical set usage to reduce turnover times between procedures.
- Point-of-Care Testing Migration:Diagnostic kits are capturing ambulatory settings as testing decentralizes from centralized laboratories to outpatient clinics.
Market Restraints
- MDR Compliance Burden:Updated clinical evidence requirements and notified body bottlenecks are extending time-to-market for kit manufacturers.
- Polymer Feedstock Volatility:Plastic material formulations face input cost pressure from petrochemical supply fluctuations and REACH substance disclosure obligations.
- Gamma Sterilization Capacity Concentration:Contract sterilization services cluster in Western European industrial corridors, creating geographic supply risk for Eastern European kit assemblers.
Strategic Opportunities
- Central and Eastern Europe Expansion:Poland and Romania's hospital modernization programs present underpenetrated demand for standardized surgical kits.
- EU Green Deal Packaging Mandates:Sustainable sterilization pouch specifications and waste recovery obligations will favor early movers in recyclable barrier systems.
- Drug-Device Combination Kits:Borderline product classifications under EMA coordination create white space for kits incorporating localized pharmaceutical delivery.
Industry Challenges
- Sterile Supply Chain Technician Shortage:Specialized operating room staff trained in kit handling and inventory management remain scarce relative to general ward nursing labor pools.
- Legacy ERP Integration Friction:Hospital networks struggle to embed kit consumption tracking into existing procurement workflows for traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Custom Procedure Kits Market |
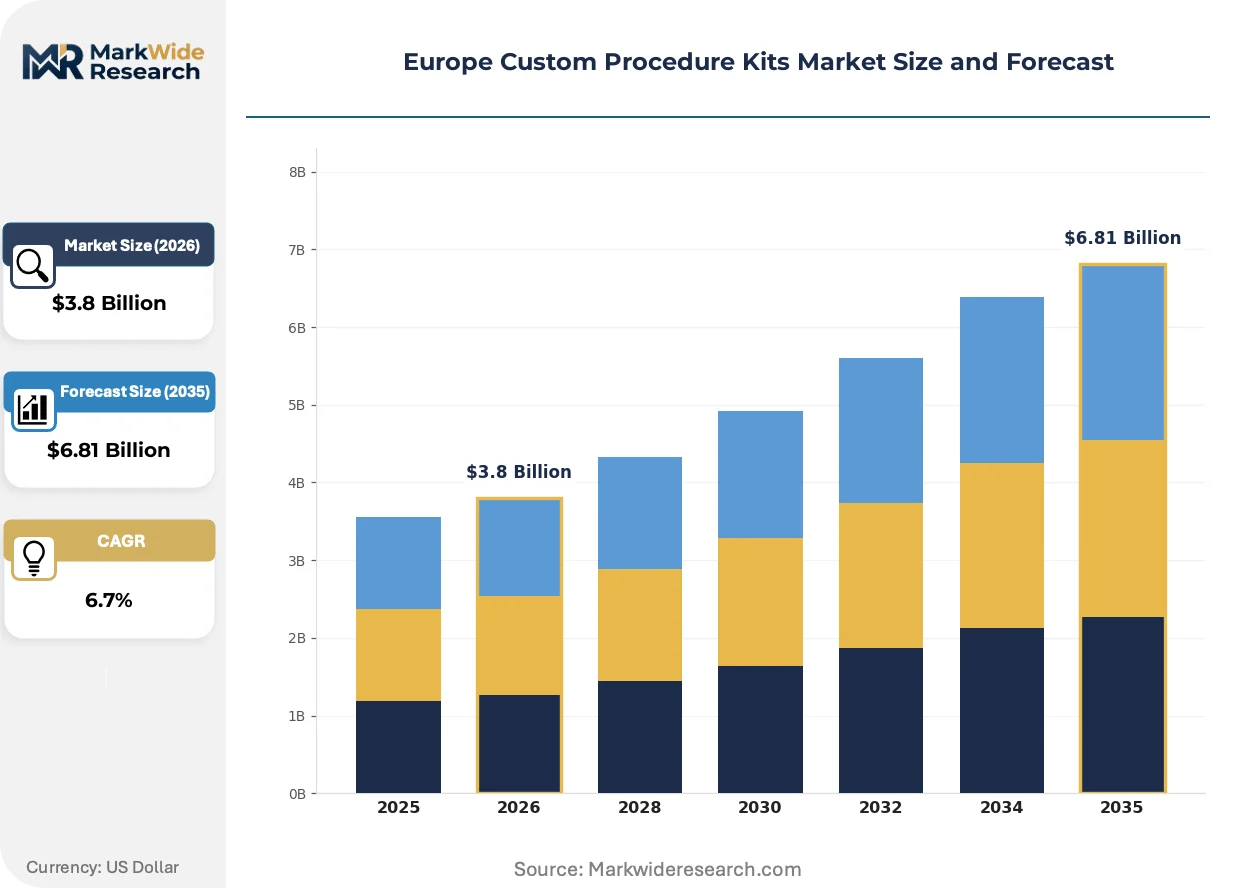
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Kits, Diagnostic Kits, Treatment Kits, Anesthesia Kits Material: Plastic, Metal, Fabric, Composite End User: Hospitals, Clinics, Home Care, Research Labs Application: Surgery, Diagnosis, Rehabilitation, Emergency Care |
| Companies Covered | Medline Industries, Inc., Cardinal Health, Mölnlycke Health Care, Teleflex Incorporated, Owens & Minor Inc., McKesson Corporation, Medtronic, B. Braun SE, Smiths Medical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Custom Procedure Kits Market Strategic Shifts & Innovations
Composite material adoption is accelerating across European kit manufacturing as procedure-specific ergonomic requirements displace commodity plastic formulations, while regulatory pressure on sterilization validation reshapes assembler technical capabilities.
Barrier material engineering is decomposing traditional polymer monolayer dominance in kit construction. Nordic hospital networks are piloting fiber-reinforced composite drapes where surgical handling precision demands premium positioning. This material transition is compressing cost-competitive assembler margins while rewarding in-house polymer compounding capabilities.
REACH chemical substance disclosure requirements are tightening polymer component sourcing transparency. ECHA enforcement of updated candidate list obligations is forcing kit assemblers to remap supplier tiers for full material composition documentation. German manufacturers face the steepest compliance acceleration due to national chemical industry density and downstream liability exposure.
Hospital purchasing consortia are consolidating vendor panels across national boundaries. France's regional health agencies and England's NHS Supply Chain are compressing approved supplier lists to capture volume discounts and standardize clinical protocols. This buyer concentration is visible most acutely in orthopedic and cardiovascular intervention kits where procedure volume justifies dedicated contract negotiation.
Europe Custom Procedure Kits Market Segmentation
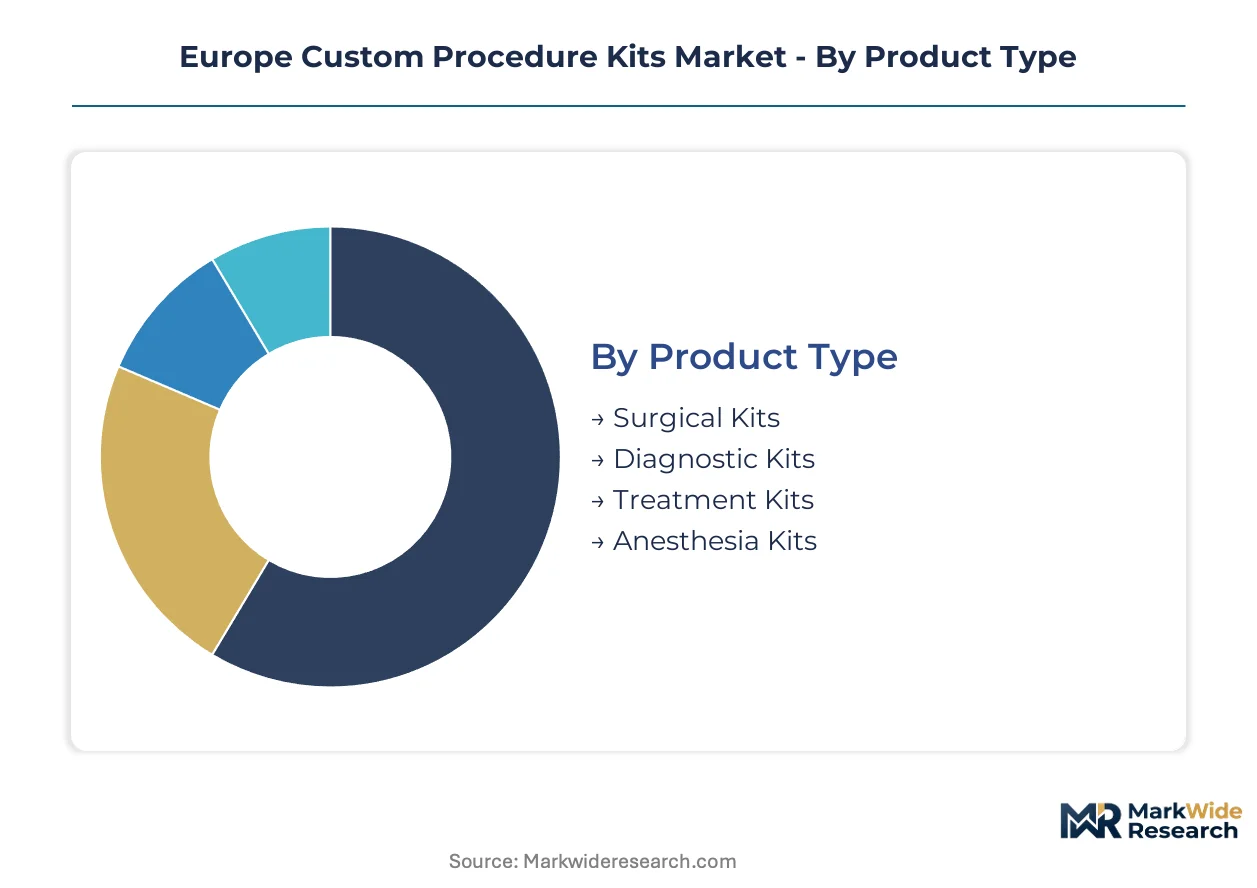
Segmentation in the Europe Custom Procedure Kits Market reveals how regulatory frameworks, sterilization requirements, and procurement consolidation reshape competitive positioning across distinct product configurations. Manufacturers must align kit specifications with divergent compliance burdens and end-user workflows.
Product Type:
CE marking under the EU MDR imposes differentiated clinical evidence requirements across kit categories, with surgical applications facing the most stringent sterilization validation protocols.
- Surgical Kits:Pre-configured sterile collections of drapes, instruments, and consumables for orthopedic and cardiovascular interventions. German acute care hospitals drive volume through bundled payment alignment, while France's regional health agencies standardize procurement specifications.
- Diagnostic Kits:Point-of-care testing configurations migrating from centralized laboratories to ambulatory settings. United Kingdom outpatient clinics and Nordic primary care networks are expanding adoption fastest as decentralized testing protocols take hold.
- Treatment Kits:Medication delivery and wound care configurations for standardized therapeutic protocols. Poland and Romania hospital modernization programs are opening procurement channels for procedure-specific treatment sets.
- Anesthesia Kits:Airway management and drug delivery assemblies for controlled sedation environments. REACH chemical disclosure requirements constrain polymer component sourcing for breathing circuit connectors.
Surgical Kits handle the majority of throughput; Diagnostic Kits is the fastest mover on share.
Material:
REACH substance disclosure obligations and EU Green Deal packaging mandates are forcing material selection trade-offs between cost efficiency, traceability compliance, and sustainability credentials.
- Plastic:Gamma-sterilizable polymer formulations dominate kit construction for disposability and cost positioning. Petrochemical feedstock volatility compresses assembler margins, particularly for German manufacturers facing downstream liability exposure.
- Composite:Fiber-reinforced barrier systems where ergonomic handling precision justifies premium positioning. Nordic hospital networks pilot composite drapes for surgical handling requirements that commodity plastics cannot satisfy.
- Fabric:Breathable textile barriers for specific sterilization pouch specifications. ECHA enforcement of updated candidate list obligations forces full material composition documentation across supplier tiers.
- Metal:Stainless steel instrument components and structural elements for reusable kit elements. MDR post-market surveillance mandates extend to metal alloy biocompatibility validation.
Plastic maintains volume leadership; Composite is climbing the fastest as ergonomic requirements displace commodity formulations.
End User:
Procurement consolidation across buyer categories is compressing vendor panels and standardizing kit specifications to capture volume discounts.
- Hospitals:National purchasing consortia in Germany, France, and the United Kingdom dominate kit consumption through dedicated contract negotiation for high-volume intervention types.
- Clinics:Ambulatory surgical centers and outpatient facilities in England's NHS Supply Chain footprint are expanding diagnostic kit adoption.
- Home Care:Patient-administered treatment kits for chronic disease management, constrained by traceability compliance in distributed settings.
- Research Labs:Custom configurations for clinical trial protocols, requiring flexible assembly runs outside standard sterilization validation batches.
Hospitals command the procurement volume; Clinics are gaining share fastest as care decentralizes.
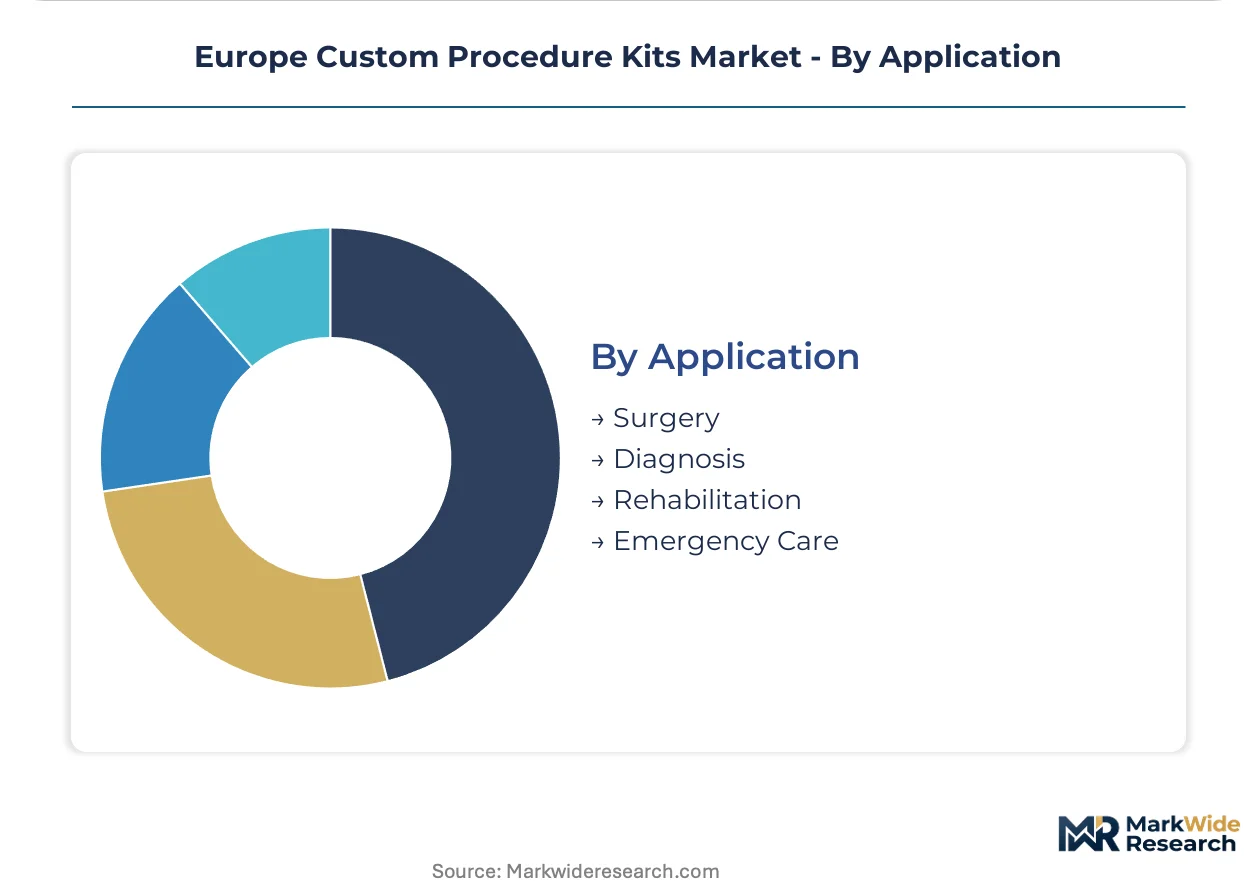
Application:
Procedure-specific kit configurations align with reimbursement structures and clinical protocol standardization across European health systems.
- Surgery:Orthopedic and cardiovascular intervention kits where operating room efficiency mandates drive pre-configured set adoption to reduce turnover times.
- Diagnosis:Point-of-care testing configurations capturing ambulatory settings as testing migrates from centralized labs.
- Rehabilitation:Post-surgical and physical therapy kits for standardized recovery protocols in Germany's bundled payment environment.
- Emergency Care:Trauma and resuscitation sets for rapid deployment, requiring gamma sterilization capacity concentration in Western European industrial corridors.
Surgery anchors revenue concentration; Diagnosis shows the steepest expansion trajectory as testing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's acute care hospital sector anchors European demand for custom procedure kits, with the country's national chemical regulator ECHA enforcing REACH substance disclosure obligations that reshape polymer component sourcing across the continent.
Germany
Bundled payment reforms in acute care hospitals drive standardized surgical kit adoption to align procedure costs with reimbursement caps. The EU Medical Device Regulation mandates updated clinical evidence and post-market surveillance for kit manufacturers. Industrial sterilization capacity concentrates in the Ruhr industrial corridor, where contract gamma sterilization services cluster to serve domestic assemblers.
France
Regional health agencies consolidate vendor panels to capture volume discounts on orthopedic and cardiovascular intervention kits. ANSM coordinates with notified bodies on borderline product classifications for drug-device combinations. The Paris-Saclay medical technology cluster hosts kit assembly operations serving national hospital purchasing consortia.
United Kingdom
NHS Supply Chain expands pre-configured surgical set usage to reduce operating room turnover times between procedures. MHRA enforces MDR compliance timelines for kit manufacturers seeking market access. Manufacturing activity concentrates in the Midlands medical device corridor, where sterile barrier system production serves domestic procurement networks.
Poland
Hospital modernization programs create underpenetrated demand for standardized surgical and treatment kits as acute care infrastructure upgrades. The national pharmaceutical regulator aligns with EMA coordination on drug-device combination classifications. Warsaw and Kraków emerge as distribution hubs for Eastern European kit logistics.
Sweden
Nordic primary care networks expand diagnostic kit adoption as point-of-care testing decentralizes from centralized laboratories. Medical Products Agency enforcement of MDR clinical evidence requirements extends time-to-market for new kit configurations. Stockholm anchors regional kit assembly operations serving Scandinavian hospital networks.
Europe Custom Procedure Kits Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European custom procedure kits landscape. Pan-European distribution networks and in-house polymer processing capabilities define the competitive frontier. Three archetypes dominate: integrated medical device conglomerates with captive sterilization capacity, specialized kit assemblers with regional hospital purchasing consortia relationships, and polymer compounders backward-integrated into component supply. Dominant competitive moves include strategic partnerships with national purchasing bodies and portfolio diversification into sustainable barrier materials.
Among diversified health care suppliers, Cardinal Health and McKesson Corporation occupy positions anchored by pan-European logistics infrastructure. Mölnlycke Health Care exemplifies the specialized assembler archetype through Nordic market concentration. B. Braun SE represents integrated manufacturing depth with in-house polymer extrusion capabilities that reduce supplier dependency for single-use kit components.
| Leading Market Players |
|---|
| Medline Industries, Inc. |
| Cardinal Health |
| Mölnlycke Health Care |
| Teleflex Incorporated |
| Owens & Minor Inc. |
| McKesson Corporation |
| Medtronic |
| B. Braun SE |
| Smiths Medical |
| Others |
Cost & Logistics Intelligence
CE marking under the EU Medical Device Regulation gates both supplier qualification and price differentiation simultaneously, as notified body certification costs stratify kit manufacturers into premium-validated and economy-positioned tiers while hospital purchasing consortia exploit this bifurcation in contract negotiations.
Pricing Analysis
Western European hospital networks pay 15-25% premiums over Eastern European procurement for identical kit specifications due to sterilization validation documentation burdens and logistics proximity. Three-tier pricing structure across premium, standard, and economy levels segments by MDR compliance depth, with premium tiers carrying full post-market surveillance data packages. Cost compression in economy tiers is intensifying because polymer feedstock volatility and REACH disclosure obligations squeeze assembler margins. Ambulatory clinics exhibit highest price sensitivity, while German acute care hospitals prioritize compliance reliability over unit cost.
Supply Chain Analysis
Gamma sterilization capacity clustering in Germany's Ruhr corridor and England's Midlands creates geographic chokepoints that tether Eastern European kit assemblers to Western contract services. Polymer resin compounding concentrates in Germany, Belgium, and the Netherlands, with specialty composite fiber sourcing resting on Nordic pulp and chemical processing infrastructure. Single-source vulnerability runs through concentrated ethylene oxide sterilization alternatives as environmental restrictions tighten. Distribution runs through pan-European healthcare logistics networks anchored by national GPO consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through MDR certification creates switching costs that lock hospital purchasing consortia into validated supplier relationships.
For Market Incumbents: Consolidate sterilization validation assets in Eastern Europe before hospital modernization programs mature, and deepen backward integration into polymer compounding to offset feedstock volatility. Emerging Polish and Romanian assemblers threaten margin compression in standard kit categories. Capacity addition in the Baltic states captures proximate access to Nordic composite fiber supply chains. For New Entrants and Emerging Players: Anchor in Poland's hospital modernization wave where procurement standardization lags Western European consolidation, and exploit diagnostic kit white space in United Kingdom outpatient clinics. Poland's underpenetrated acute care sector offers lowest competitive density for treatment kit categories. Go-to-market through regional health agency pilot programs bypasses national GPO vendor panel exclusion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite material kit manufacturing as ergonomic handling requirements displace commodity plastic formulations. Long-term viability favors assemblers with captive polymer processing and sterilization capacity. Target acquisition archetype: mid-cap specialists with MDR certification depth and underutilized gamma sterilization contracts. Watch ECHA enforcement intensity on REACH candidate list updates as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Notified body validation unlocks German hospital purchasing consortium contracts. |
| Composite Material Transition | Fiber-reinforced barrier systems capture Nordic premium positioning. |
| Eastern European Capacity Buildout | Poland and Romania hospital modernization opens underpenetrated procurement channels. |
| Sustainable Packaging Development | EU Green Deal mandates reshape sterilization pouch specifications. |
| Drug-Device Combination Kits | EMA borderline classifications create white space for localized pharmaceutical delivery. |
Research Approach
A standing panel of hospital procurement directors, sterile supply chain technicians, notified body auditors, and polymer sourcing managers provided ongoing calibration across primary interview rounds, with secondary validation drawing from EMA borderline product rulings, REACH candidate list updates, NHS Supply Chain contract disclosures, and German hospital purchasing consortium tender databases. Bottom-up kit volume modeling triangulated against top-down healthcare expenditure allocation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include kit type, material formulation, end-user facility tier, and application protocol. CAGRs derived from procedure volume elasticity to reimbursement reform timing and sterilization capacity expansion curves. Industry-specific inputs incorporated ECHA enforcement trajectories and bundled payment adoption rates.
Decision-makers should treat outputs as directional under base assumptions of MDR implementation continuity and polymer feedstock price stabilization; material deviation in notified body capacity or REACH substance restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal packaging mandates and gamma sterilization environmental regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Suture Wire Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Nasal Splints Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Port Access Needles Market