
 Suture Wire Market | 2026-2036
Suture Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Suture Wire Market Outlook
Skilled surgical wire technicians is rotating toward advanced polymer handling and micro-braiding competencies that limit production throughput across the industry. Ethicon US, LLC leverages its parent company's polymer science heritage to dominate absorbable wire formulations. B. Braun Melsungen AG anchors European supply through vertically integrated extrusion and sterilization campuses in Germany.
Suture wire comprises sterile, thread-like metallic or polymeric devices engineered in diameters ranging from 6-0 to 3-0 USP for wound closure and tissue approximation. Manufacturers draw, anneal, and surface-treat stainless steel or synthetic filaments to achieve tensile strength profiles matched to orthopedic and cardiac load requirements. Non-absorbable variants command durable revenue streams in orthopedic fixation where permanent support is clinically indicated, while absorbable segments capture expanding share in soft-tissue cardiac procedures. Mono-filament configurations lead in infection-sensitive applications due to reduced bacterial adherence compared to braided alternatives.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and sterilization validation burdens for all manufacturers seeking market access. ISO 10993 biocompatibility testing standards govern cytotoxicity and sensitization protocols that determine material selection for coated and uncoated wire surfaces. Stakeholders must monitor evolving FDA guidance on permanent implantable device materials alongside EU ECHA scrutiny of polymer additives that could trigger REACH restrictions.
Market Dynamics
Orthopedic surgical volumes are pulling wire demand upward while EU MDR sterilization documentation requirements extend product development timelines by 12-18 months across all manufacturers.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated pathways for predicate devices with established biocompatibility profiles reduce time-to-market for stainless steel wire iterations in trauma fixation applications.
- Ambulatory surgical center expansion:United States outpatient facilities are performing 34% more arthroscopic procedures requiring specialized suture wire kits than hospital inpatient settings.
- Absorbable polymer chemistry advances:Polyglycolide-lactide copolymer formulations with controlled degradation profiles are capturing cardiac soft-tissue repair applications previously served by permanent implants.
Market Restraints
- Raw material concentration:Medical-grade 316LVM stainless steel feedstock depends on three primary European and Japanese melt shops, creating vulnerability to nickel price volatility and alloying element shortages.
- EU MDR technical documentation burden:Clinical evaluation requirements for Class III implantable devices demand extensive biocompatibility testing under ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization protocols.
- Monofilament technical ceiling:Single-strand configurations lack the knot security and handling characteristics of braided alternatives in high-tension orthopedic applications, limiting clinical adoption despite infection-control advantages.
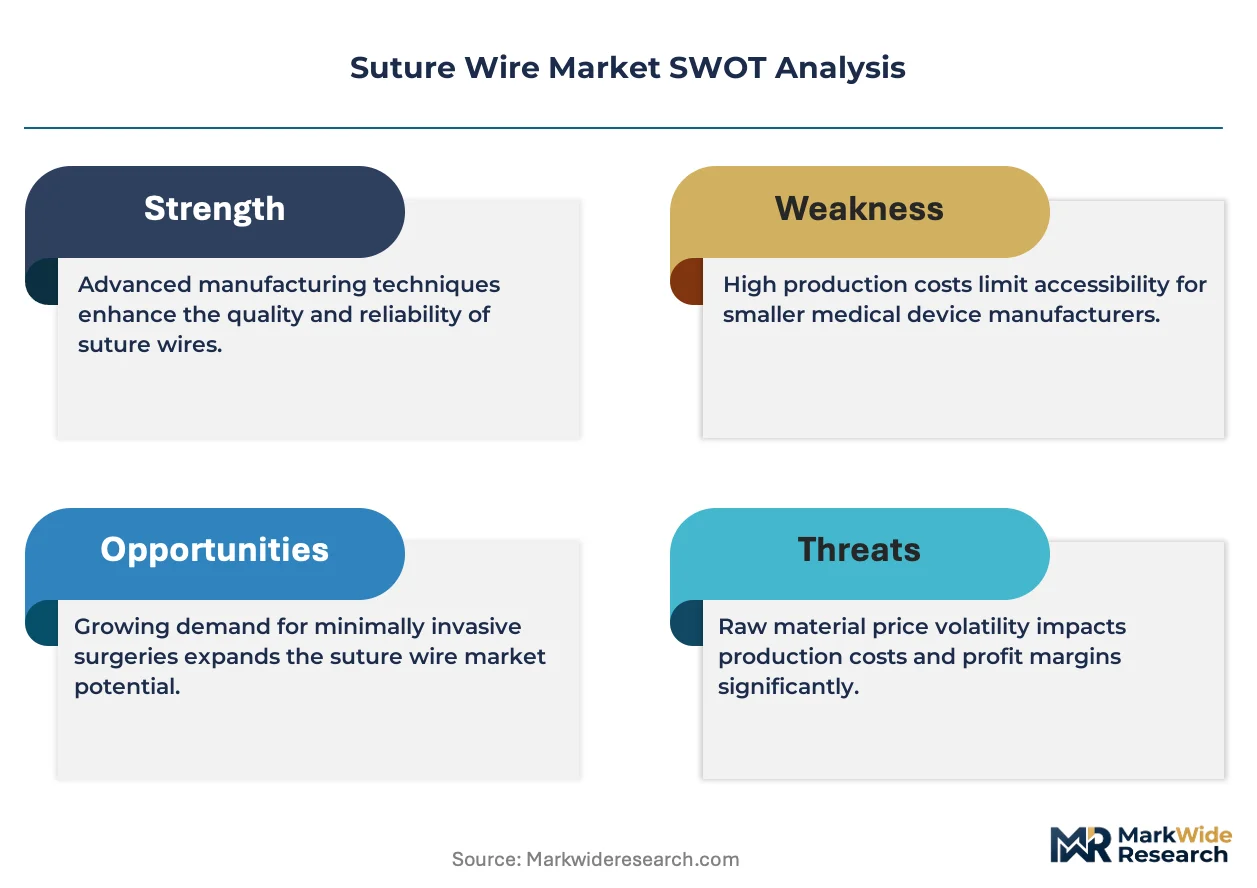
Strategic Opportunities
- India cardiac surgery penetration:Unmet demand for coronary artery bypass grafting in tier-2 cities creates distribution openings for absorbable wire products compliant with CDSCO medical device rules.
- Direct-to-hospital procurement platforms:Digital tendering systems are compressing distributor margins and enabling manufacturers to capture value previously lost to multi-tier distribution in German and French markets.
- Antimicrobial coating convergence:Triclosan and silver-ion surface treatments combined with braided micro-geometry are addressing surgical site infection protocols in US trauma centers.
Industry Challenges
- Micro-braiding technician scarcity:Precision textile manufacturing skills required for 7-0 and 8-0 USP diameter braided wires command 40% wage premiums and limit production scale-up across European and North American facilities.
- Sterilization validation timelines:Ethylene oxide residual testing and radiation dose mapping for novel polymer formulations extend FDA 510(k) review cycles, compressing effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suture Wire Market |
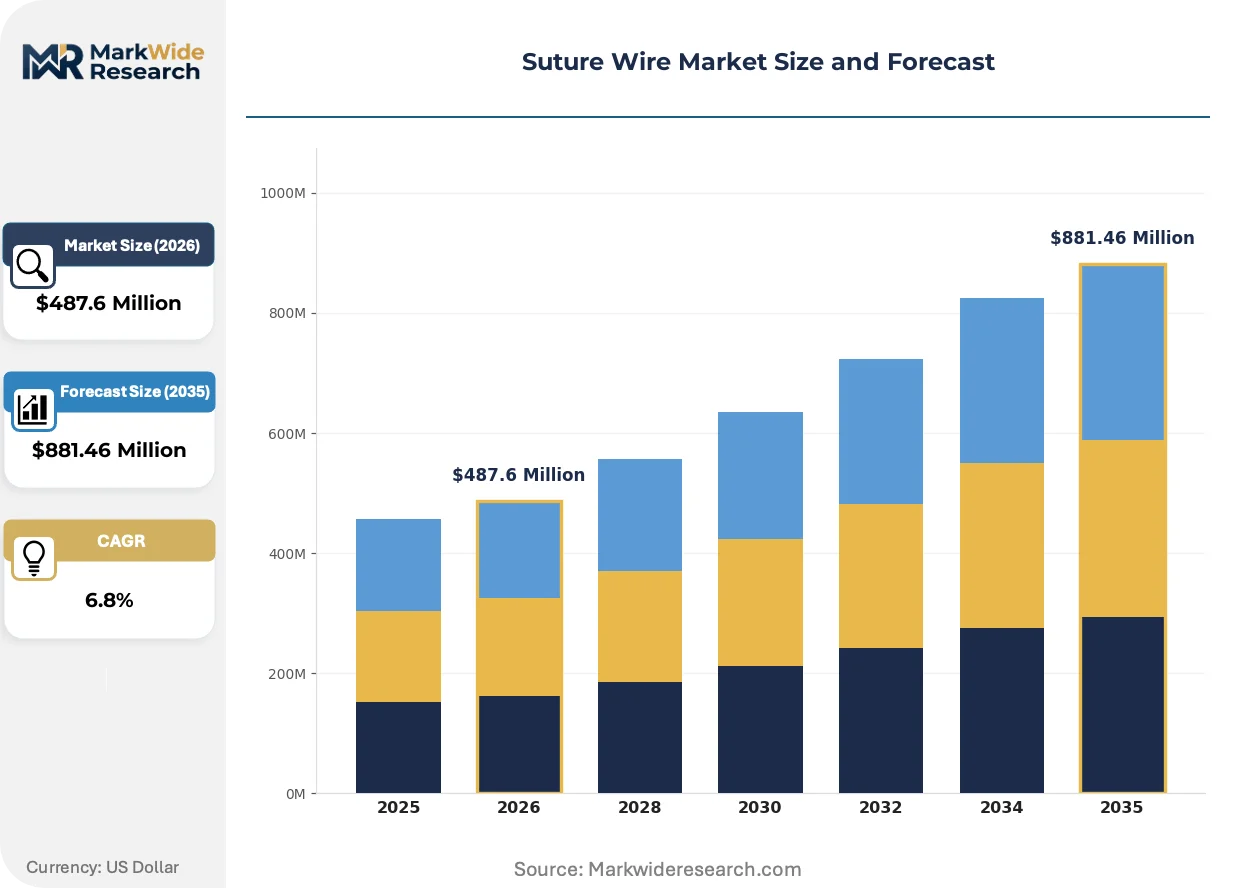
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-absorbable, Nylon, Polypropylene Diameter: 6-0, 5-0, 4-0, 3-0 Application: Surgical Procedures, Orthopedic Surgeries, Cardiac Surgeries, Dental Surgeries Form: Mono-filament, Multi-filament, Braided, Coated |
| Companies Covered | Boston Scientific Corporation, DemeTECH Corporation, EndoEvolution LLC, Ethicon US, LLC, Medtronic plc, Stryker Corporation, B. Braun Melsungen AG, CONMED Corporation, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suture Wire Market Strategic Shifts
Material science advances in absorbable polymers and surface engineering are reconfiguring product portfolios, while regulatory documentation requirements reshape competitive barriers to entry.
Bioabsorbable magnesium alloys with controlled corrosion rates are displacing permanent stainless steel fixation in pediatric orthopedic applications where hardware removal surgeries impose second-procedure costs. European trauma centers in Germany and Switzerland are piloting these formulations for growth-plate-sparing procedures. The technology is displacing conventional metal wire revenue in anatomies where implant permanence offers no clinical advantage.
EU MDR Annex I general safety and performance requirements now mandate post-market surveillance systems with periodic safety update reports for all implantable suture wire classifications. Manufacturers must maintain clinical data registries tracking adverse events across their entire product lifecycle. Cardiac surgery applications face the steepest compliance burden due to critical organ classification and extended implant duration.
Hospital purchasing consortiums in the United States are consolidating suture wire procurement through standardized formularies that privilege dual-source supply arrangements over single-vendor relationships. Integrated delivery networks in Texas and California now mandate participation in value-analysis committees for vendor qualification. This concentration is visible most acutely in orthopedic service lines where procedure volume thresholds determine pricing tier access.
Suture Wire Market Segmentation
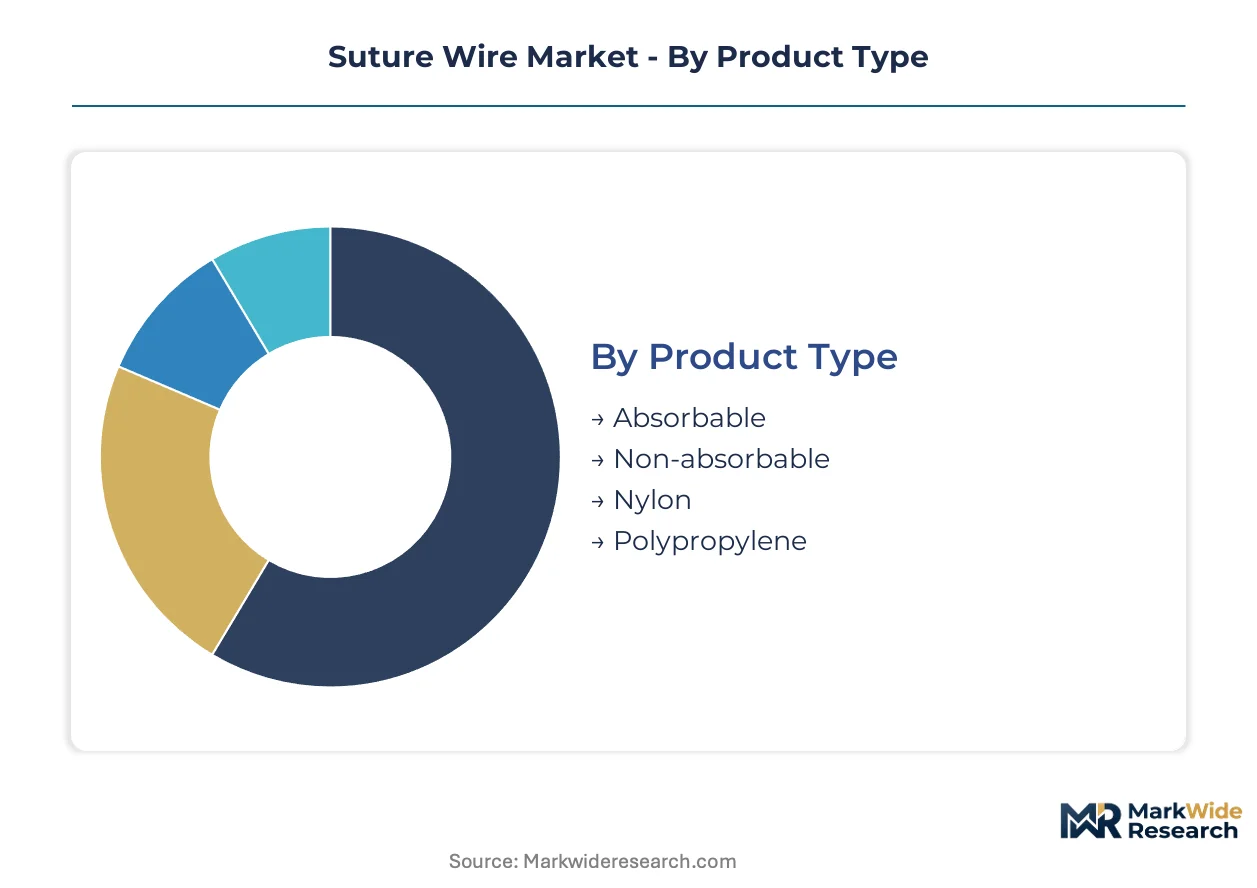
Suture wire segmentation reveals how material properties, physical dimensions, and clinical applications create distinct competitive arenas with varying margin profiles and regulatory burdens. Manufacturers configure production assets around specific segment combinations rather than pursuing horizontal coverage across all categories.
Product Type:
Non-absorbable formulations face mounting substitution pressure from advanced polymer chemistry in soft-tissue applications, while absorbable variants compete on degradation precision rather than permanence.
- Non-absorbable:Stainless steel and permanent polymer constructions deliver tensile strength for orthopedic fixation where hardware removal imposes procedural costs. Demand concentrates in United States trauma centers performing high-volume fracture repairs with permanent implant protocols.
- Absorbable:Polyglycolide-lactide copolymers with hydrolytic degradation profiles eliminate second-procedure removal in pediatric and cardiac soft-tissue repairs. German and Swiss hospitals are piloting magnesium alloy variants for growth-plate-sparing procedures.
- Nylon:Polyamide monofilament structures provide intermediate strength for dermatological closures and superficial tissue approximation.
- Polypropylene:Isotactic polypropylene formulations resist tissue reaction in cardiovascular patches and hernia mesh fixation.
Non-absorbable retains volume leadership; absorbable holds the steepest expansion curve.
Diameter:
Cost tier stratification separates commodity 3-0 production from precision 6-0 manufacturing where micro-braiding competencies command substantial wage premiums.
- 3-0:Thickest diameter specification serves high-tension orthopedic applications requiring maximum tensile strength. United States ambulatory surgical centers standardize 3-0 kits for arthroscopic rotator cuff repairs.
- 6-0:Finest diameter enables microvascular and ophthalmic procedures where tissue trauma minimization overrides strength requirements. European facilities face 40% technician wage premiums for 7-0 and 8-0 braided precision work.
- 4-0:Mid-range diameter balances handling characteristics with strength for general surgical closures.
- 5-0:Intermediate specification serves plastic surgery and subcuticular closures where cosmetic outcomes drive selection.
3-0 dominates procedure volume; 6-0 captures the highest margin per meter.
Application:
Customer type fragmentation separates hospital purchasing consortiums from ambulatory facility procurement patterns with divergent formularies and volume thresholds.
- Orthopedic Surgeries:Fracture fixation, ligament reconstruction, and sports medicine procedures consume braided stainless steel and high-strength synthetic configurations. Texas and California integrated delivery networks mandate dual-source supply arrangements for vendor qualification.
- Cardiac Surgeries:Coronary artery bypass grafting and valve procedures demand absorbable polymers with controlled degradation to avoid permanent foreign body presence. India's tier-2 cities present distribution openings for CDSCO-compliant absorbable products.
- Surgical Procedures:General surgery applications span wound closure and tissue approximation across multiple anatomical sites.
- Dental Surgeries:Oral and maxillofacial procedures utilize finer diameter specifications with emphasis on biocompatibility in mucosal environments.
Orthopedic applications anchor revenue concentration; cardiac procedures generate the fastest share gain.
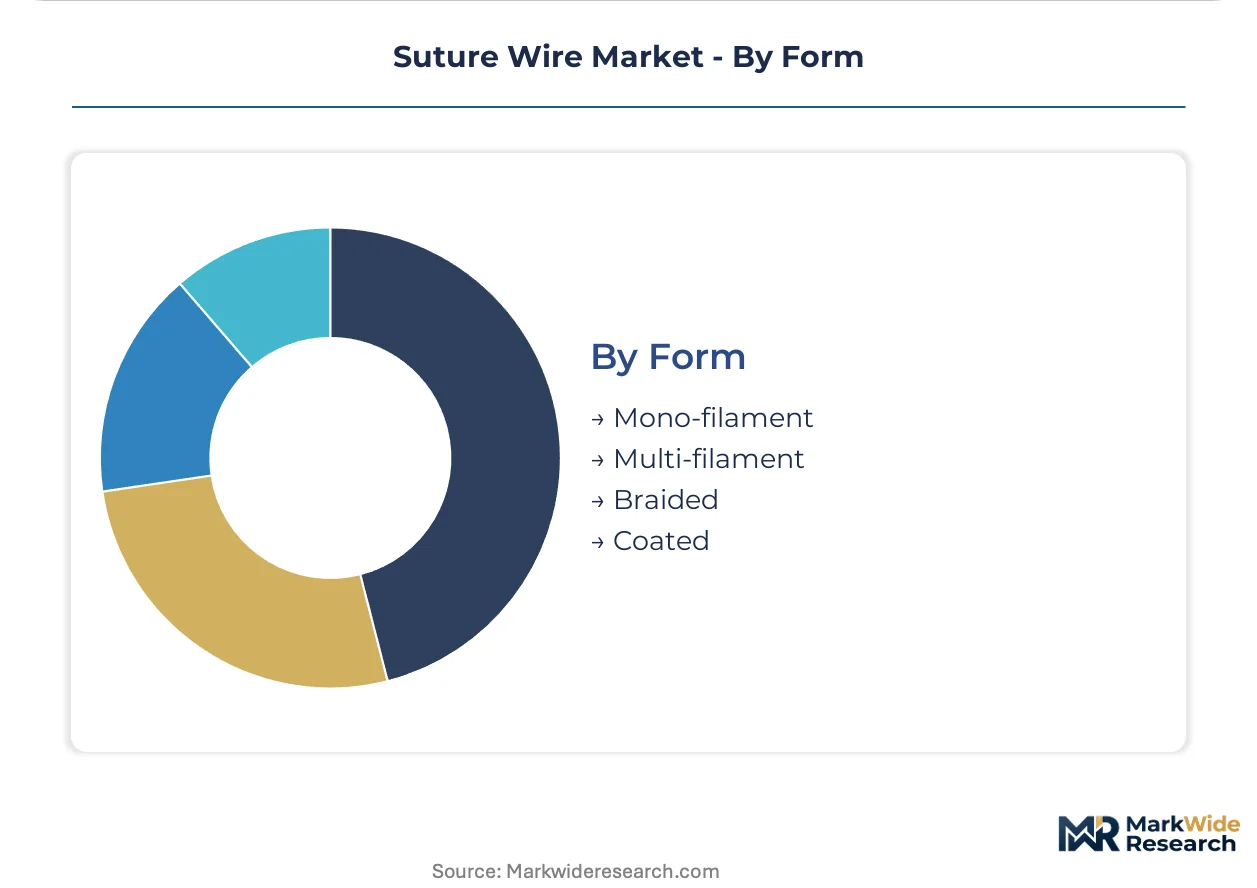
Form:
Supply concentration in European and Japanese melt shops for medical-grade 316LVM feedstock shapes form selection economics, with monofilament configurations offering manufacturing simplicity against braided complexity.
- Braided:Multi-strand constructions deliver superior knot security and handling in high-tension orthopedic applications. Antimicrobial silver-ion and triclosan surface treatments are converging with braided micro-geometry in United States trauma centers.
- Mono-filament:Single-strand configurations reduce bacterial adherence in infection-sensitive procedures despite inferior knot security. EU MDR sterilization documentation extends development timelines for novel monofilament polymer formulations.
- Multi-filament:Twisted fiber constructions offer intermediate handling characteristics between monofilament and braided alternatives.
- Coated:Surface-treated variants enhance tissue passage and knot run-down performance through polymer or silicone coatings.
Braided maintains clinical preference in orthopedics; monofilament gains fastest in infection-control protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss manufacturing clusters where precision micro-braiding commands substantial premiums, while United States ambulatory surgical centers extract volume discounts through integrated delivery network consolidation. Demand asymmetry between these geographies is widening as European facilities absorb EU MDR compliance costs and American buyers leverage digital procurement platforms.
United States
Texas and California integrated delivery networks now mandate dual-source supply arrangements for orthopedic service lines, with ambulatory surgical centers performing wire-intensive arthroscopic procedures at 34% higher volumes than hospital inpatient settings. FDA 510(k) clearance streamlining for predicate stainless steel devices accelerates trauma fixation product introductions. Minneapolis and Warsaw, Indiana host concentrated orthopedic device manufacturing clusters serving domestic demand.
Germany
B. Braun Melsungen AG anchors European supply through vertically integrated extrusion and sterilization campuses, capturing cardiac and orthopedic wire demand across the continent. EU MDR technical documentation requirements extend product development timelines by 12-18 months, creating compliance barriers for non-European competitors. The Tuttlingen surgical instrument cluster in Baden-Württemberg maintains specialized wire-drawing and surface-treatment capabilities for precision medical applications.
Switzerland
Swiss trauma centers in Zurich and Basel pilot bioabsorbable magnesium alloy formulations for pediatric growth-plate-sparing procedures, displacing conventional permanent stainless steel fixation. Swissmedic oversight of Class III implantable devices maintains rigorous post-market surveillance standards. The Basel pharmaceutical-medical device corridor provides polymer science expertise supporting next-generation absorbable wire development.
India
Unmet demand for coronary artery bypass grafting in tier-2 cities creates distribution openings for CDSCO-compliant absorbable wire products. The national pharmaceutical regulator's medical device rules framework is harmonizing with international standards to accelerate foreign manufacturer market entry. Maharashtra and Gujarat host emerging contract manufacturing capabilities serving domestic cardiac surgery expansion.
Japan
Medical-grade 316LVM stainless steel feedstock dependence on Japanese melt shops creates supply vulnerability for global wire manufacturers facing nickel price volatility. PMDA consultation pathways for novel polymer formulations require extensive biocompatibility documentation. The Kobe and Osaka industrial corridors concentrate precision metalworking expertise for medical device applications.
Suture Wire Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with polymer science heritage separating premium absorbable formulation developers from commodity stainless steel processors. The market structure exhibits tiered consolidation around integrated multinationals and specialized regional fabricators. Three archetypes dominate: diversified surgical device conglomerates with captive wire production, dedicated suture specialists with polymer chemistry depth, and contract manufacturers serving private-label distributors. Competitive moves concentrate on M&A for regulatory clearance assets and capacity expansion in low-cost sterilization jurisdictions.
Among diversified surgical device conglomerates, Boston Scientific Corporation, Medtronic plc, and Stryker Corporation exemplify scale-driven archetypes that leverage integrated sales infrastructure across cardiac and orthopedic service lines. These entities occupy positions where procedure volume thresholds determine pricing tier access and vendor qualification. Their market presence reflects the concentration of purchasing power within United States hospital systems and European purchasing consortiums rather than technology differentiation alone.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| DemeTECH Corporation |
| EndoEvolution LLC |
| Ethicon US, LLC |
| Medtronic plc |
| Stryker Corporation |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Integra LifeSciences |
| Others |
Value Chain & Pricing Dynamics
EU MDR Annex I general safety and performance requirements gate both supplier qualification and price tier access, forcing manufacturers to absorb 12-18 month documentation costs that concentrate premium pricing among German and Swiss facilities with sterilization campus assets. Hospital purchasing consortiums in Texas and California exploit this compliance asymmetry to extract volume discounts from commodity stainless steel wire suppliers while paying premiums for absorbable polymer formulations.
Pricing Analysis
United States ambulatory surgical centers pay 15-20% less per meter than European trauma centers for equivalent 3-0 stainless steel braided configurations. Pricing stratifies across premium, standard, and economy tiers based on ISO 10993-5 cytotoxicity certification grade and volume commitment thresholds. Cost compression in standard-grade monofilament segments is intensifying because integrated delivery networks mandate dual-source supply arrangements. Orthopedic service lines show highest price sensitivity; cardiac surgery applications demonstrate lowest sensitivity due to critical organ classification.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for medical-grade 316LVM stainless steel feedstock drawn from Japanese melt shops. Raw material supply rests on European and Japanese metallurgical facilities, with polyglycolide-lactide polymer precursors anchored in German chemical corridors. Single-source vulnerability concentrates in nickel alloying element procurement, exposing manufacturers to commodity price volatility. Distribution runs through hospital purchasing consortiums and direct-to-hospital digital tendering platforms that compress traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks as Texas and California hospital systems consolidate orthopedic procurement through standardized formularies with dual-source mandates. This concentration fragments vendor access and privileges scale-driven suppliers with captive sterilization assets.
For Market Incumbents: Shield absorbable polymer revenue streams by deepening backward integration into polymer precursor production in Germany and Switzerland. Accelerate CDSCO registration for Indian cardiac surgery penetration before emerging entrants capture tier-2 city distribution. Prioritize antimicrobial coating convergence with silver-ion surface treatments to defend trauma center share against substitute technology pressure. For New Entrants and Emerging Players: Anchor in India's coronary artery bypass grafting expansion by securing CDSCO medical device rules compliance for absorbable wire kits targeting tier-2 cities. The cardiac soft-tissue repair segment offers the most penetrable white space given unmet surgical demand and limited incumbent distribution depth. Pursue direct-to-hospital procurement platform participation to bypass entrenched distributor relationships in German and French markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR-compliant sterilization campus operations, favoring asset-heavy incumbents with regulatory clearance depth. Five-to-ten year viability hinges on acquiring specialized micro-braiding facilities with 7-0 and 8-0 USP diameter capabilities, where technician scarcity commands 40% wage premiums. Watch for FDA 510(k) clearance acceleration signals on predicate stainless steel devices as inflection indicators for trauma fixation investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Annex I compliance creates 12-18 month barriers that protect German sterilization campus assets from Asian competition. |
| Absorbable Polymer Chemistry R&D Expansion | Polyglycolide-lactide degradation precision captures cardiac soft-tissue procedures from permanent stainless steel fixation. |
| India CDSCO Registration Acceleration | Tier-2 city coronary artery bypass grafting demand outpaces incumbent distribution infrastructure. |
| Antimicrobial Coating Convergence | Silver-ion and triclosan surface treatments address surgical site infection protocols in United States trauma centers. |
| Direct-to-Hospital Procurement Platform Integration | Digital tendering systems in Germany and France compress distributor margins and enable manufacturer value capture. |
Study Parameters
Cross-validation between primary interviews with orthopedic surgeons, cardiac surgery department heads, hospital purchasing committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 10993 biocompatibility testing standards. Bottom-up procedure volume modeling and top-down manufacturer capacity assessments triangulate market sizing across absorbable and non-absorbable product categories.
Sensitivity analysis on nickel price volatility, EU MDR compliance timeline extensions, and ambulatory surgical center expansion rates stress-tests base case assumptions across the projection horizon. Segmentation dimensions include material type, diameter specification, application, and form factor, with regional regulatory cluster differentiation. CAGRs derive from procedure volume forecasts weighted by wire intensity per intervention type, incorporating surgeon interview data on kit standardization trends.
Decision-makers should treat outputs as directional under assumptions of continued FDA 510(k) streamlining for predicate devices and sustained EU MDR enforcement intensity; material deviation in sterilization validation timelines or nickel alloy supply disruptions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Global Lancets Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Lab Trays Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market