
 North America Hospital Supplies Market | 2026-2036
North America Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hospital Supplies Market Analytics
The gap between premium surgical instruments and commodity medical consumables is expanding across North America. Cardinal Health leverages its distribution network to dominate commodity flow into integrated delivery networks. Medline Industries sustains manufacturing scale across disposable product lines that serve ambulatory surgery centers. Becton Dickinson and Company differentiates through R&D intensity in safety-engineered devices that command premium placement in academic medical centers.
Hospital supplies encompass sterile and non-sterile products used in patient diagnosis, treatment, and facility operations, including latex and nitrile examination gloves rated at 3.0 mil minimum thickness for barrier integrity and single-use surgical drapes with fluid-resistant polyethylene laminate construction. Personal protective equipment and medical consumables anchor the largest volume pools, while electromechanical and robotics segments capture disproportionate margin concentration in procurement budgets. Diagnostic equipment represents a mature replacement cycle category where purchasing committees extend asset lifespans through refurbished channel alternatives.
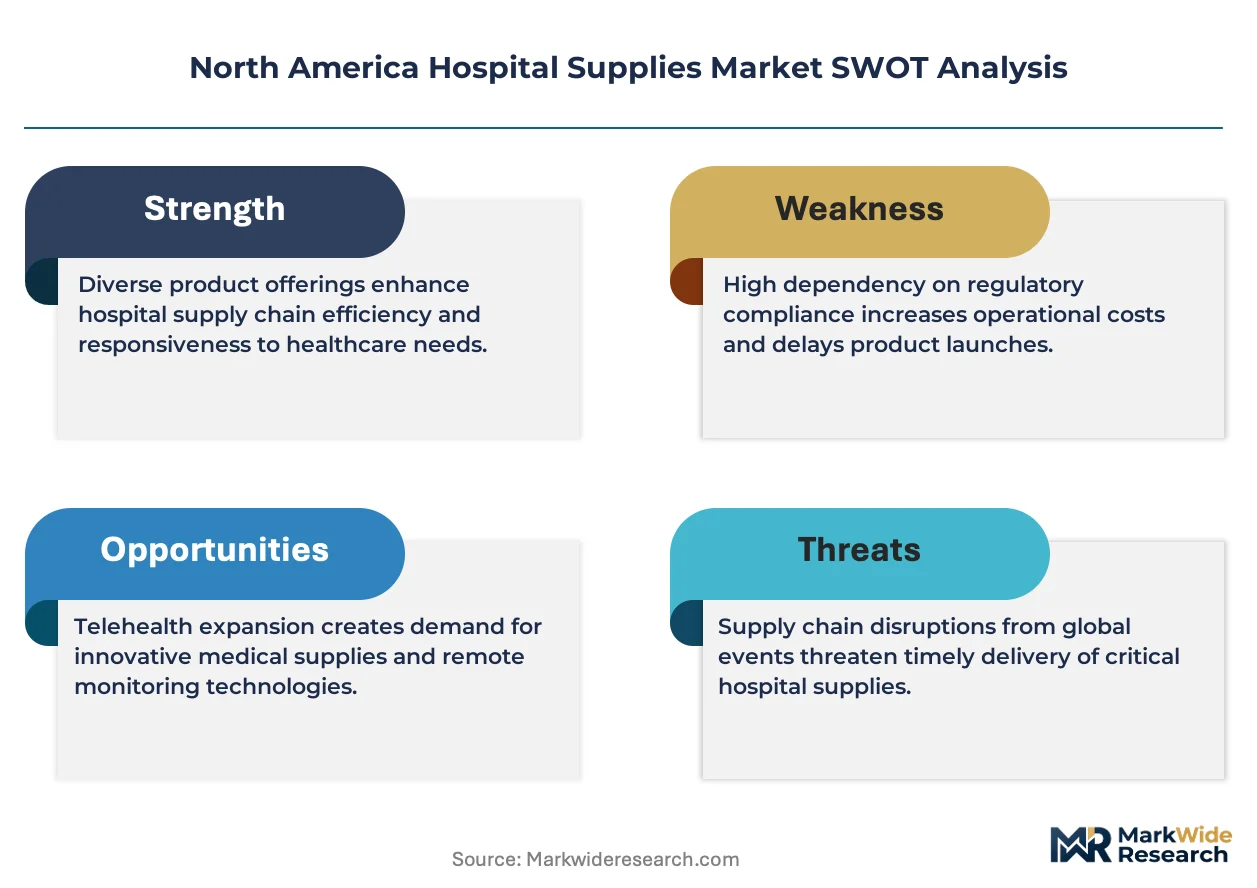
The FDA enforces Quality System Regulation 21 CFR Part 820 for device manufacturing controls, while Health Canada applies the Medical Devices Regulations under the Food and Drugs Act for market authorization across provinces. These frameworks elevate compliance costs for entrants and privilege incumbents with established quality management infrastructure. Stakeholders must monitor how CMS reimbursement adjustments for outpatient procedures reshape purchasing authority between hospital systems and freestanding ASCs.
Market Dynamics
ASC conversions across the southeastern United States are redirecting procurement authority from integrated delivery networks toward freestanding surgical centers, fragmenting purchasing volumes and forcing suppliers to rebuild channel economics around smaller, more frequent orders with stricter sterilization documentation.
Growth Catalysts
- CMS outpatient reimbursement expansion:The 2024 Medicare Physician Fee Schedule elevates payment parity for procedures performed in ambulatory settings, accelerating ASC construction and disposable kit demand across Texas and Florida.
- Nitrile glove substitution:Latex sensitivity protocols in Canadian and US academic medical centers are driving rapid conversion to synthetic alternatives with enhanced chemical resistance ratings.
- Mexico hospital privatization wave:Grupo Angeles and Hospital Star Médica are expanding bed capacity in Monterrey and Guadalajara, importing US-standard supply chains for surgical drapes and electromechanical devices.
Market Restraints
- FDA 21 CFR Part 820 compliance costs:Quality system infrastructure requirements for sterilization validation and design controls create capital barriers for mid-tier manufacturers seeking US market entry.
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with Gulf Coast refinery capacity, compressing margins on single-use surgical kits and fluid-resistant drapes.
- Health Canada Medical Devices Regulations:Class II device licensing timelines extending beyond 180 days delay product launches for safety-engineered needles and sharps containers in Ontario and Quebec.
Strategic Opportunities
- Underpenetrated Mexican ASC segment:Tijuana and Ciudad Juárez border clinics serving medical tourism demand lack integrated supply relationships, creating first-mover advantages for distributors with cross-border logistics.
- FDA Breakthrough Device Designation pathway:Robotics-assisted surgical platforms with integrated consumable ecosystems qualify for expedited review, compressing time-to-revenue for innovators.
- Reprocessed single-use device regulatory clarity:FDA third-party reprocessor guidance creates channel expansion for cost-conscious hospital systems in the US Mountain West seeking 40-60% cost reductions on eligible devices.
Industry Challenges
- Sterilization validation specialist scarcity:Ethylene oxide and radiation sterilization expertise concentrates among aging practitioners in Minnesota and Massachusetts, constraining capacity expansion for new device entrants.
- Legacy ERP integration with track-and-trace mandates:FDA Unique Device Identification compliance requires hospital systems to rebuild procurement databases, delaying supplier onboarding and invoice reconciliation.
- Cross-border customs documentation complexity:USMCA rules-of-origin disputes disrupt just-in-time inventory flows for nitrile gloves manufactured in Malaysian-owned Malaysian facilities but packaged in Mexican maquiladoras.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hospital Supplies Market |
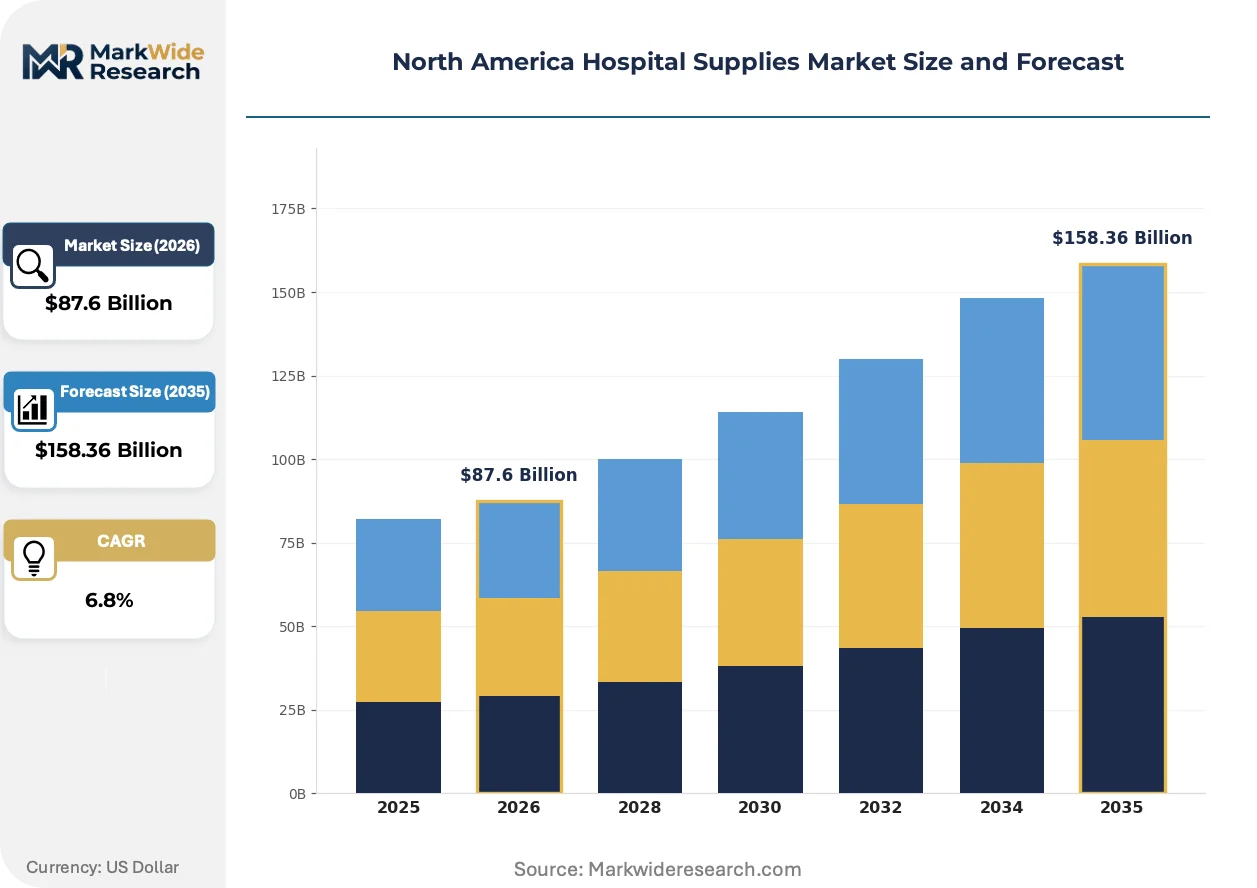
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Personal Protective Equipment, Medical Consumables End User: Hospitals, Ambulatory Surgery Centers, Home Care, Clinics Application: Inpatient Care, Outpatient Care, Emergency Care, Routine Check-ups Technology: Electromechanical, Disposable, Telemedicine, Robotics |
| Companies Covered | Cardinal Health, Medline Industries, McKesson Corporation, Becton Dickinson and Company, 3M Company, Johnson & Johnson, Medtronic, B. Braun SE, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hospital Supplies Market Evolving Landscape
Sterilization assurance technologies and procurement digitization are converging to reshape how hospital supplies flow from manufacturer to point-of-care, with regulatory pressure and buyer consolidation acting as twin accelerants of vendor selection criteria.
Smart packaging with embedded RFID temperature loggers is absorbing accountability for cold-chain integrity from distributors into manufacturers, enabling real-time spoilage alerts. Academic medical centers in Boston and Baltimore are piloting these systems for biologic-coated sutures and temperature-sensitive adhesives. The technology is absorbing liability exposure that previously sat with hospital pharmacy departments, compressing insurance premiums for early adopters.
Health Canada's 2024 guidance on sterilization process validation for reusable medical devices tightens documentation requirements for Canadian hospitals sourcing from US suppliers. Manufacturers must now submit complete ethylene oxide residual testing protocols for each production lot. Ontario's procurement consortium has responded by consolidating supplier lists to incumbents with established Canadian quality management infrastructure, excluding newer entrants lacking Health Canada audit history.
Hospital systems are consolidating purchasing authority into centralized value analysis committees that unbundle device selection from distributor relationships. Freestanding ASCs in Arizona and Nevada now negotiate direct with manufacturers for surgical kits, bypassing traditional distribution markups. This pattern concentrates most visibly in the Intermountain West, where Intermountain Healthcare and Banner Health have eliminated regional distributor tiers for commodity consumables.
North America Hospital Supplies Market Segmentation
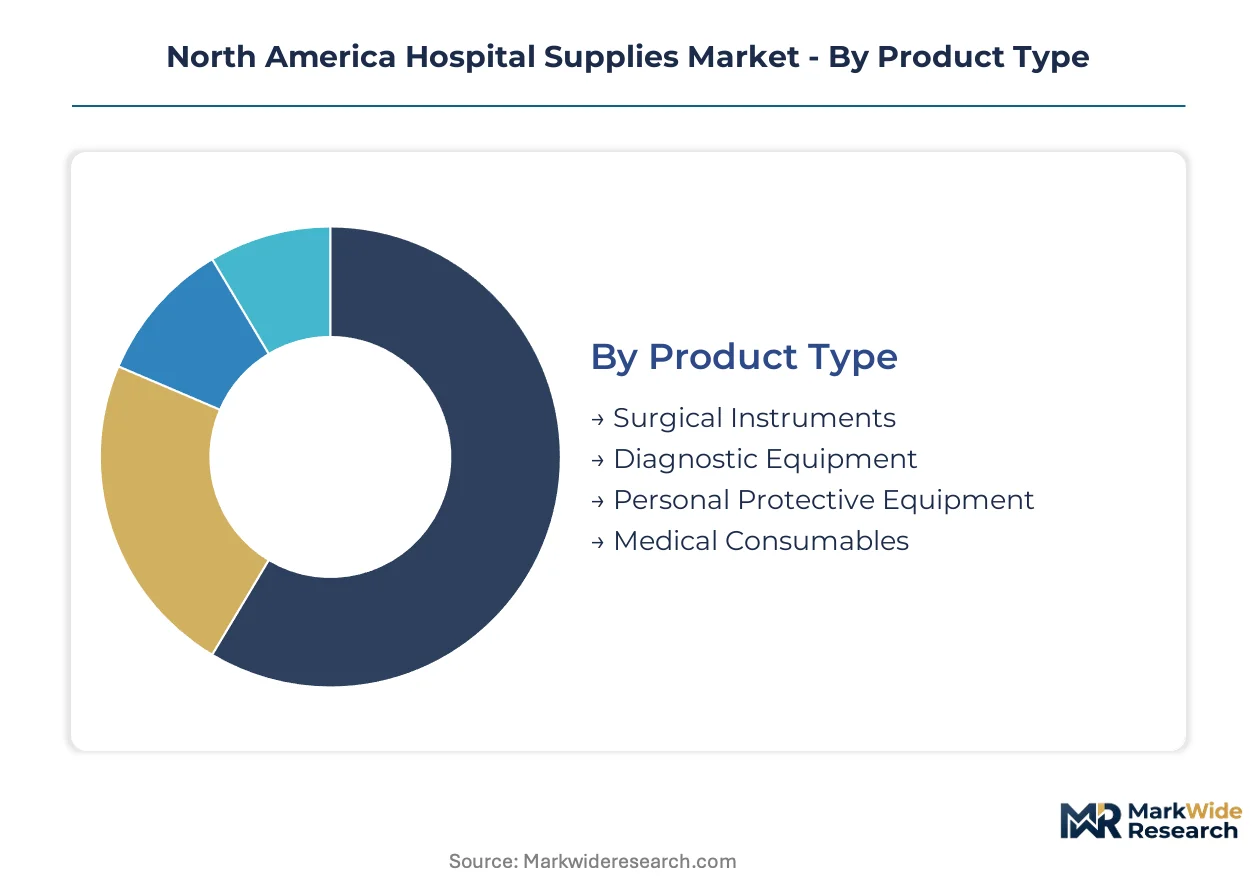
Hospital supplies procurement patterns diverge sharply across product categories and care settings. Understanding these splits reveals where margin pools concentrate and which channels command pricing power.
Product Type:
Surgical instruments and consumables draw from concentrated manufacturing bases in Massachusetts and Minnesota, while protective equipment supply chains stretch to Southeast Asian resin producers.
- Surgical Instruments:Precision-manufactured retractors, forceps, and clamps in stainless steel and titanium alloys serve orthopedic and cardiovascular suites. Academic medical centers in Boston and Houston prioritize instrument durability ratings and sterilization cycle tolerance over upfront cost.
- Medical Consumables:Single-use drapes, gowns, and suction tubing in polypropylene and SMS laminates anchor volume procurement. Ambulatory surgery centers across Florida and Texas are expanding kit customization programs that bundle procedure-specific consumable sets.
- Personal Protective Equipment:Nitrile examination gloves with 3.0 mil minimum thickness and ASTM D6319 barrier ratings dominate hospital formulary compliance. Latex sensitivity protocols in Canadian academic centers are accelerating synthetic substitution.
- Diagnostic Equipment:Replacement-cycle capital goods including patient monitors and imaging accessories face extended depreciation schedules. Hospital systems in the US Mountain West increasingly source refurbished modalities through third-party channels.
Medical consumables absorb the bulk of installed capacity; surgical instruments are expanding most quickly.
End User:
Procurement authority fragments as care migrates from inpatient towers to freestanding facilities, forcing suppliers to rebuild order economics around smaller batch sizes.
- Hospitals:Integrated delivery networks leverage centralized value analysis committees that unbundle device selection from distributor relationships. Southeastern health systems undergoing construction booms in Atlanta and Charlotte are renegotiating multi-year supply agreements.
- Ambulatory Surgery Centers:Freestanding facilities in Arizona and Nevada negotiate direct with manufacturers for procedure-specific kits, bypassing traditional distribution tiers. CMS outpatient reimbursement parity is accelerating ASC construction across Texas and Florida.
- Clinics:Physician office laboratories and urgent care chains source commodity consumables through group purchasing organizations. Federally qualified health centers in rural California face working capital constraints that favor consignment inventory arrangements.
- Home Care:Post-acute and hospice providers require portable diagnostic kits and wound care supplies with simplified instructions. Medicare Advantage penetration in metropolitan Chicago is expanding home infusion therapy demand.
Hospitals retain the deepest procurement infrastructure; ambulatory surgery centers are climbing the fastest.
Application:
Care setting intensity determines sterilization documentation burden and regulatory scrutiny level.
- Inpatient Care:Surgical suites and intensive care units demand sterile barrier systems with validated ethylene oxide residual levels. FDA Quality System Regulation compliance elevates supplier qualification costs for devices entering this channel.
- Outpatient Care:Scheduled procedures in endoscopy and ophthalmology favor disposable instrument kits with reduced reprocessing liability. Health Canada's sterilization validation guidance tightens documentation for reusable devices sourced from US suppliers.
- Emergency Care:Trauma bays require rapid-deployment supply configurations with color-coded inventory systems. Level I trauma centers in Baltimore and Philadelphia prioritize hemorrhage control product availability.
- Routine Check-ups:Primary care examination rooms consume high volumes of gloves, specula, and disposable drapes. Canadian provincial procurement consortia consolidate supplier lists to incumbents with established quality management infrastructure.
Inpatient care commands the strictest compliance overhead; outpatient care is gaining share fastest.
Technology:
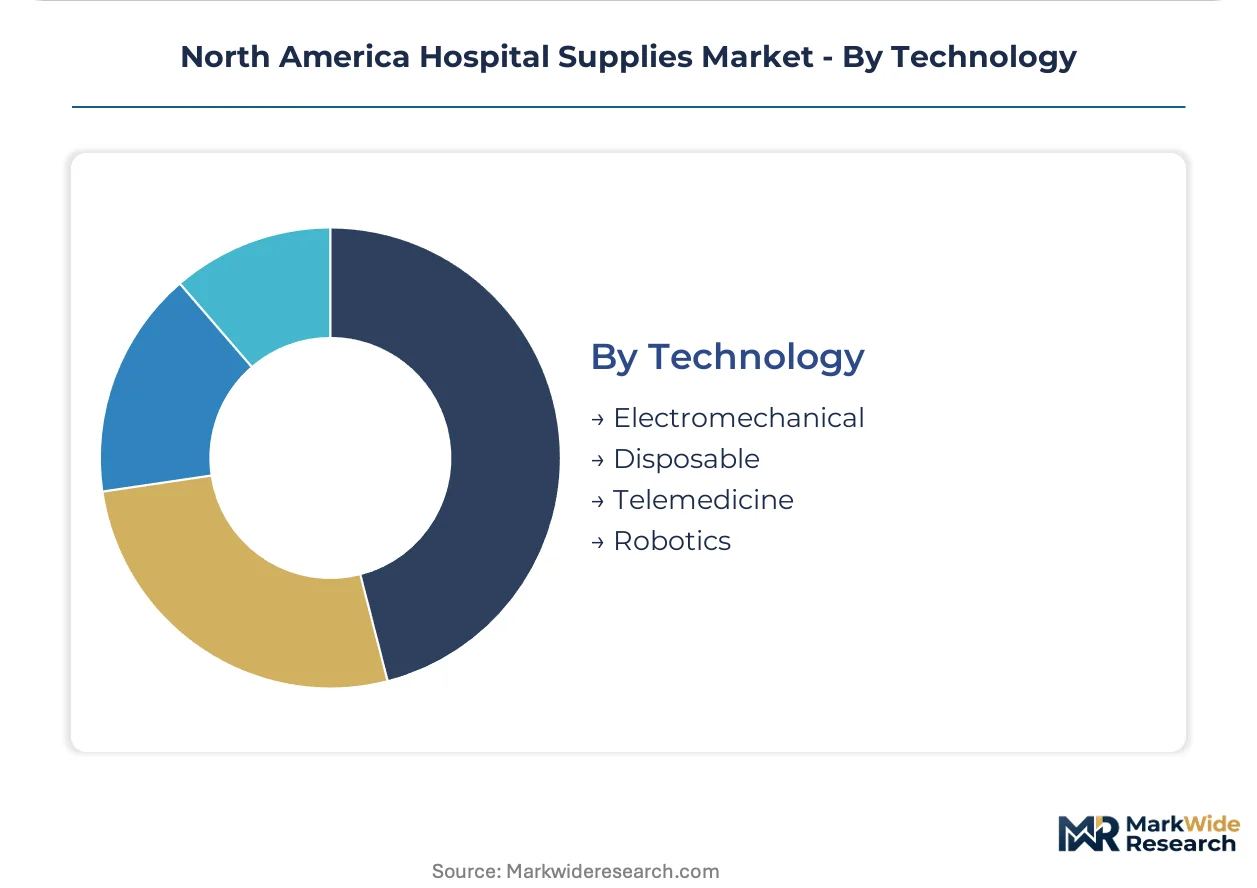
Capital intensity and regulatory pathway length separate electromechanical platforms from commodity disposables.
- Disposable:Single-use surgical kits and sterile barrier systems eliminate reprocessing validation costs. Nitrile glove conversion protocols in US academic medical centers are displacing latex alternatives with enhanced chemical resistance ratings.
- Electromechanical:Powered surgical staplers and electrosurgical generators integrate safety interlocks and tissue feedback sensors. Mexico's hospital privatization wave is importing US-standard electromechanical supply chains for Monterrey and Guadalajara facilities.
- Robotics:Minimally invasive platforms with integrated consumable ecosystems qualify for FDA Breakthrough Device Designation expedited review. Academic medical centers in Boston pilot these systems for prostate and gynecologic procedures.
- Telemedicine:Remote diagnostic peripherals and digital stethoscopes extend specialist reach into rural service areas. Broadband infrastructure gaps in Appalachian regions constrain deployment velocity.
Disposable technology anchors volume throughput; robotics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Worcester corridor anchors North American hospital supply innovation, hosting precision instrument manufacturers and sterilization validation specialists that serve academic medical centers across the continent.
United States
ASC construction booms in Texas and Florida are fragmenting procurement volumes toward freestanding facilities. FDA 21 CFR Part 820 enforcement elevates compliance costs for sterilization documentation. Minneapolis-St. Paul retains concentrated ethylene oxide sterilization expertise that constrains capacity expansion for new device entrants.
Canada
Provincial procurement consortia in Ontario and Quebec are consolidating supplier lists to incumbents with established Health Canada audit history. Health Canada's 2024 sterilization validation guidance tightens documentation for reusable devices sourced from US suppliers. Toronto's hospital networks are piloting RFID-enabled cold-chain monitoring for temperature-sensitive biologics.
Mexico
Grupo Angeles and Hospital Star Médica are expanding bed capacity in Monterrey and Guadalajara, importing US-standard supply chains for surgical drapes and electromechanical devices. The country's national pharmaceutical regulator applies device licensing timelines that delay product launches for safety-engineered needles. Tijuana and Ciudad Juárez border clinics serving medical tourism demand lack integrated supply relationships.
North America Hospital Supplies Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the sterilization documentation and distribution network dimensions. The vendor base clusters around three tiers: integrated distributors with national logistics infrastructure, specialized manufacturers with captive sterilization capacity, and regional converters serving ambulatory surgery centers with customized kit assembly. Strategic moves concentrate on direct-to-ASC contracting and cross-border logistics buildout.
Within the integrated distribution tier, Cardinal Health and Medline Industries occupy positions that exemplify scale-driven commodity flow dominance. Becton Dickinson and Company sits within the premium-device archetype, representing R&D-intensive positioning in safety-engineered categories that command placement in academic medical centers.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| McKesson Corporation |
| Becton Dickinson and Company |
| 3M Company |
| Johnson & Johnson |
| Medtronic |
| B. Braun SE |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the southeastern United States anchor procurement volumes that sustain contract-based long-term pricing for commodity consumables, while freestanding ASCs fragment purchasing into smaller lots that trade at spot-market premiums.
Pricing Analysis
Value-based pricing anchored to CMS reimbursement benchmarks governs premium safety-engineered devices in academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates FDA Breakthrough Device Designation holders from mid-tier sterilization-compliant suppliers and commodity glove converters. Cost compression in the standard tier is intensifying because Health Canada audit history requirements privilege incumbent suppliers. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with captive value analysis committees demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Regional distribution centers in Memphis and Indianapolis anchor hub-and-spoke patterns that feed hospital systems across the US Midwest and Southeast. Manufacturing concentration centers on Malaysia and Thailand for nitrile glove resin, Minnesota and Massachusetts for sterilization validation services, and Mexico for surgical kit assembly serving border clinics. Raw material dependencies include polypropylene resin, ethylene oxide sterilization capacity, and RFID-enabled temperature loggers. Single-source vulnerability in Malaysian nitrile feedstock exposes distributors to USMCA rules-of-origin disputes. Distribution runs through Cardinal Health and Medline Industries national networks with direct-to-ASC bypass emerging in Arizona and Nevada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital supply procurement consolidation is accelerating as FDA 21 CFR Part 820 compliance costs force mid-tier manufacturers toward exit or acquisition.
For Market Incumbents: Acquire sterilization validation specialist firms in Minnesota and Massachusetts to lock scarce ethylene oxide expertise before competitor consolidation. Build captive cross-border logistics infrastructure into Tijuana and Ciudad Juárez to capture medical tourism clinic demand before distributor relationships solidify. FDA third-party reprocessor guidance threatens traditional single-use device margins; preempt with reprocessing service offerings. For New Entrants and Emerging Players: The gap between premium robotics-assisted platforms and economy surgical kits creates entry space for mid-tier electromechanical device manufacturers with Health Canada pre-submission history. Target underpenetrated Mexican ASC segment in Monterrey and Guadalajara where US-standard supply chains remain unestablished. Lead with consignment inventory arrangements for federally qualified health centers facing working capital constraints. For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturers with captive sterilization capacity and established Canadian quality management infrastructure. Five-to-ten year viability hinges on positioning upstream of ASC procurement fragmentation. Monitor CMS outpatient reimbursement parity adjustments as inflection signal for ASC construction velocity and disposable kit demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Pre-Submission Investment | Accelerates Class II device licensing timelines for Ontario and Quebec market entry. |
| Cross-Border Logistics Buildout | Captures first-mover advantage in Tijuana and Ciudad Juárez medical tourism clinics. |
| RFID-Enabled Cold-Chain Partnership | Absorbs liability exposure for biologic-coated sutures in Boston academic medical centers. |
| Direct-to-ASC Contracting Program | Bypasses traditional distribution markups in Arizona and Nevada freestanding facilities. |
| Sterilization Validation Acquisition | Secures scarce ethylene oxide expertise concentrated among aging Minnesota practitioners. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and ASC operations directors combined with FDA 510(k) databases, Health Canada Medical Devices Active Licence Listing, and CMS Medicare cost report data. Bottom-up facility-level procurement modeling triangulated against top-down distributor revenue segmentation.
Granularity-level framing applied product type, end user, application, and technology dimensions at the country level across the United States, Canada, and Mexico. CAGRs derived from logistic adoption curves fitted to historical procurement volume trends, with adjustment for CMS reimbursement parity policy impacts and Mexico hospital privatization wave velocity. Industry-specific inputs included ethylene oxide sterilization capacity utilization rates and nitrile glove resin price indices.
Inputs from Health Canada and FDA regulatory databases were available through the study window; gaps in real-time ASC procurement transaction data introduce uncertainty bands around freestanding facility demand projections. Forecasts reflect documented assumptions regarding CMS policy stability and USMCA trade framework continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market