
 Sequencing Consumables Market | 2026-2036
Sequencing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Sequencing Consumables Market Analytics
The gap between premium-grade sequencing consumables and commodity reagent tiers is restructuring procurement patterns across the industry. Illumina, Inc. leverages its captive flow cell manufacturing to sustain margin capture at the high end of the market. Thermo Fisher Scientific Inc. anchors its position through integrated supply chains spanning enzymes, buffers, and library preparation kits. QIAGEN competes in sample preparation consumables where standardization pressures intensify.
Sequencing consumables comprise the disposable chemical and physical inputs required to prepare, amplify, and read nucleic acid sequences, including reagent formulations with defined pH buffers and polymerase concentrations, surface-patterned flow cells manufactured through semiconductor lithography techniques, and oligonucleotide primers synthesized via solid-phase phosphoramidite chemistry. Their primary commercial purpose is to enable repeatable, high-fidelity genetic analysis across research and clinical workflows. Reagents and kits command the largest revenue pool given their recurring purchase frequency and formulation complexity, while next-generation sequencing consumables outpace Sanger-based products in growth velocity as throughput demands rise. Cancer research applications concentrate the highest-value consumable consumption per run due to panel complexity and regulatory validation requirements.
The FDA oversees in vitro diagnostic consumables through premarket notification and quality system regulation pathways in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter performance documentation and post-market surveillance obligations on sequencing reagent manufacturers selling into Europe. ISO 13485 certification has become a baseline threshold for supplier qualification by large diagnostic lab networks, compressing margins for uncertified entrants. Stakeholders must monitor how evolving pharmacogenomic labeling requirements from regulators reshape consumable specification demands and sourcing consolidation timelines.
Market Dynamics
EU In Vitro Diagnostic Regulation enforcement is compressing supplier qualification timelines while academic medical centers consolidate reagent purchasing through multi-year framework agreements.
Growth Catalysts
- Pharmacogenomic labeling mandates:FDA guidance on companion diagnostics expands validated panel consumption in oncology workflows. Clinical laboratories must maintain larger reagent inventories to support expanded testing menus.
- Semiconductor lithography advances:Patterned flow cell manufacturing achieves higher cluster density per run. Research institutes in Germany and the United States accelerate instrument refresh cycles to capture throughput gains.
- ISO 13485 certification expansion:Diagnostic lab networks in Japan and Australia now require supplier documentation as a baseline threshold. Uncertified reagent vendors face exclusion from tender processes.
Market Restraints
- Polymerase input cost volatility:Recombinant enzyme production depends on fermentation capacity concentrated in Chinese and South Korean biomanufacturing hubs. Price swings compress margin stability for mid-tier kit suppliers.
- Flow cell supply concentration:Captive manufacturing by dominant platform vendors limits third-party substitution. Independent clinical labs face single-source dependency for high-throughput consumables.
- Sanger method residual lock-in:Validated long-read applications in forensics and paternity testing slow complete platform migration. Reference laboratories maintain dual reagent inventories.
Strategic Opportunities
- Liquid biopsy assay expansion:Cell-free DNA extraction kits represent underdeveloped white space in early cancer detection. Regulatory validation pathways in the United States create first-mover advantages for standardized preparation chemistries.
- Cloud-integrated consumable tracking:RFID-enabled reagent monitoring converges with laboratory information management systems. Academic medical centers in the Netherlands pilot subscription-based consumption models.
- India CDSCO diagnostic registration streamlining:Centralized approval pathways for imported sequencing kits reduce time-to-market for multinational suppliers. Domestic contract research organizations expand sequencing service capacity.
Industry Challenges
- Bioinformatics pipeline integration:Laboratory technicians lack cross-training in computational biology. Clinical diagnostic labs struggle to align wet-lab consumable workflows with downstream variant interpretation software.
- Post-market surveillance documentation:EU In Vitro Diagnostic Regulation requires continuous performance monitoring. Reagent manufacturers must rebuild quality management systems to capture real-world usage data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sequencing Consumables Market |
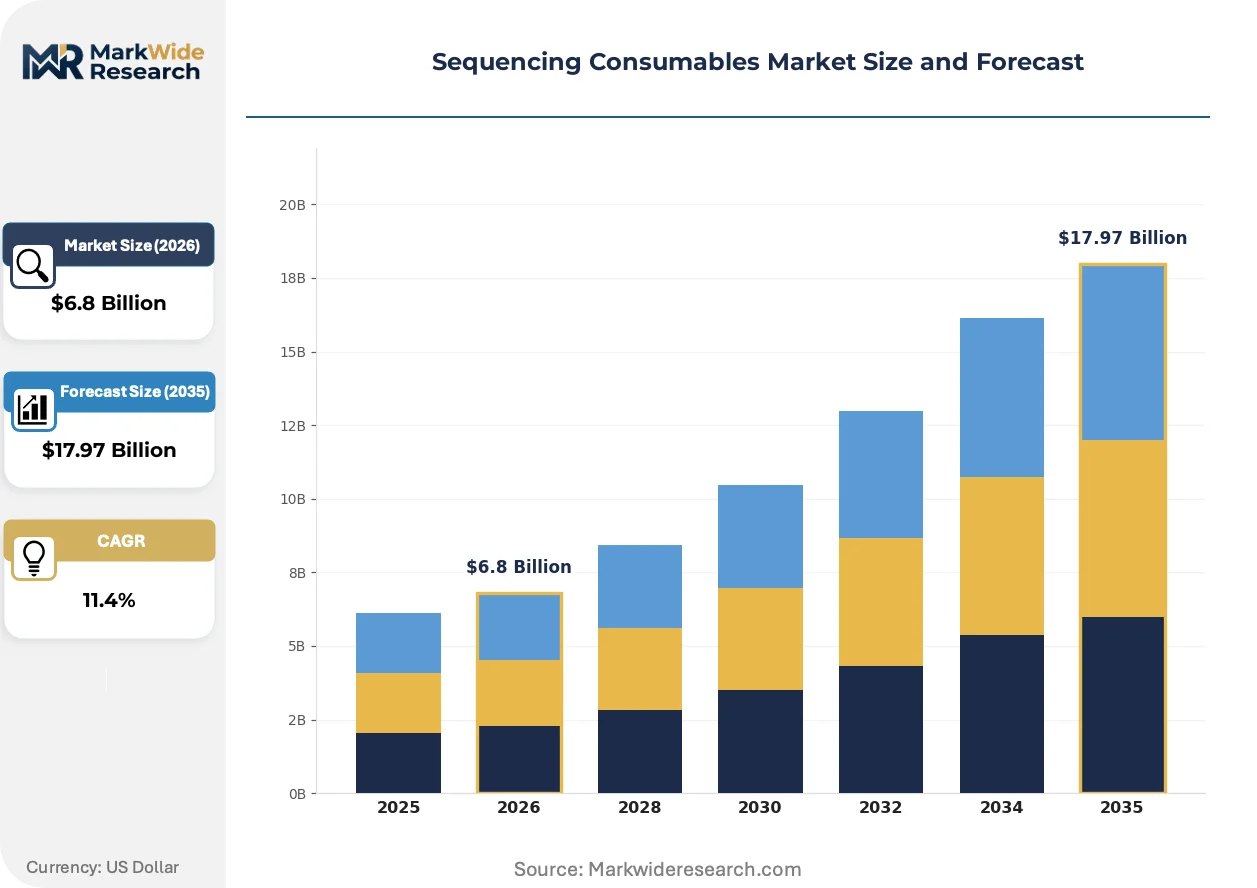
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Primers, Enzymes End User: Research Institutions, Diagnostic Labs, Pharmaceutical Companies, Biotechnology Firms Technology: Next-Generation Sequencing, Sanger Sequencing, RNA Sequencing, Whole Genome Sequencing Application: Cancer Research, Genetic Testing, Agricultural Biotechnology, Infectious Disease Research |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., Agilent Technologies, Inc., QIAGEN, F. Hoffmann-La Roche Ltd., Pacific Biosciences of California, Inc., Oxford Nanopore Technologies plc, Danaher Corporation, Twist Bioscience Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sequencing Consumables Market Evolving Landscape
Library preparation automation is collapsing manual pipetting steps while regulatory documentation requirements reshape supplier competitive positioning.
Integrated walk-away systems are automating nucleic acid extraction and normalization protocols. High-volume clinical diagnostic laboratories in the United States deploy these platforms to reduce technician hands-on time per batch. The technology is automating previously labor-intensive steps that constrained daily sample throughput.
EU In Vitro Diagnostic Regulation performance documentation requirements now extend to Class A reagents previously exempt from systematic review. Manufacturers must generate clinical evidence packages for buffer formulations and control materials. Cancer research consortia in Germany and France delay procurement decisions pending supplier certification completion.
Bulk purchasing consortia among academic medical centers are displacing individual laboratory reagent negotiations. Aggregated demand contracts in the northeastern United States secure volume discounts on flow cells and cluster generation kits. This concentration forces smaller reference laboratories into group purchasing organization membership or premium spot pricing.
Sequencing Consumables Market Segmentation
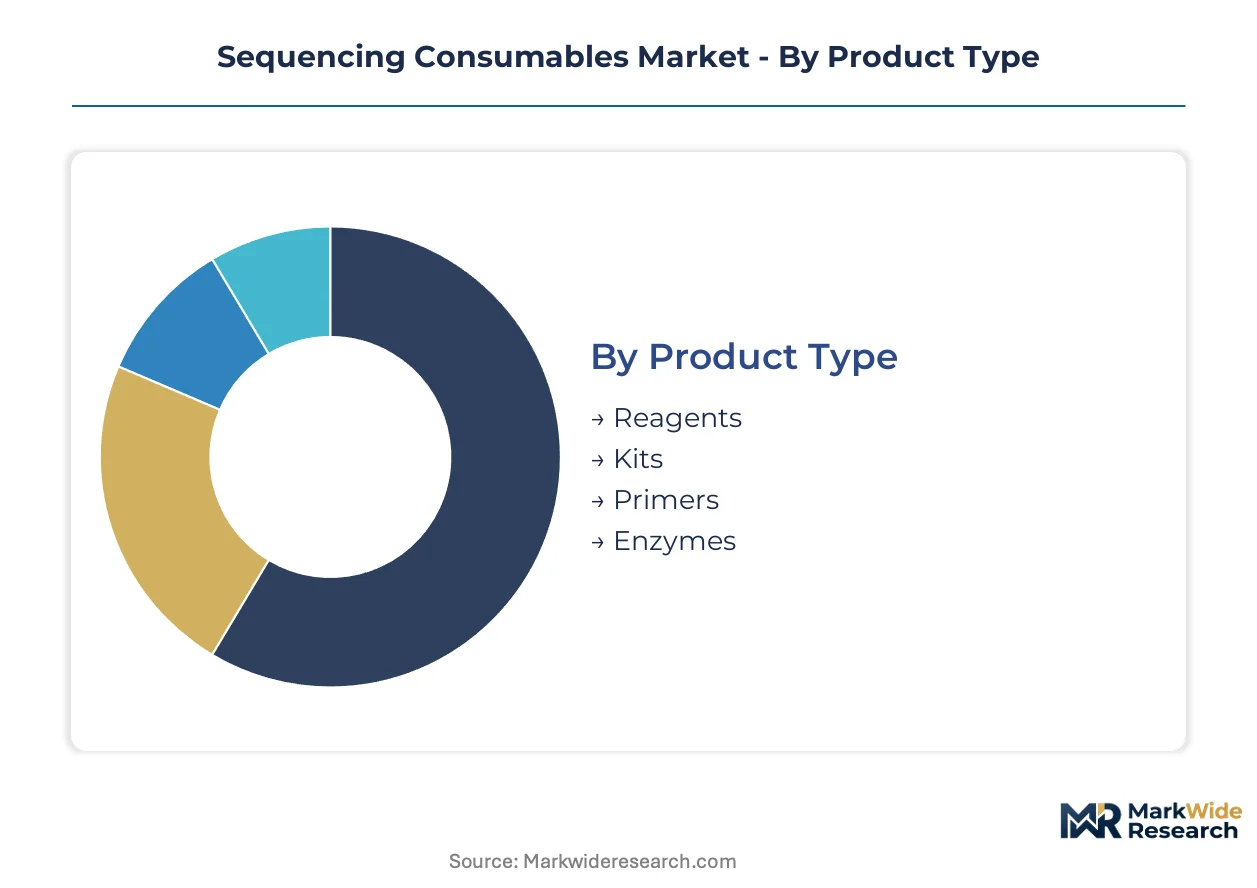
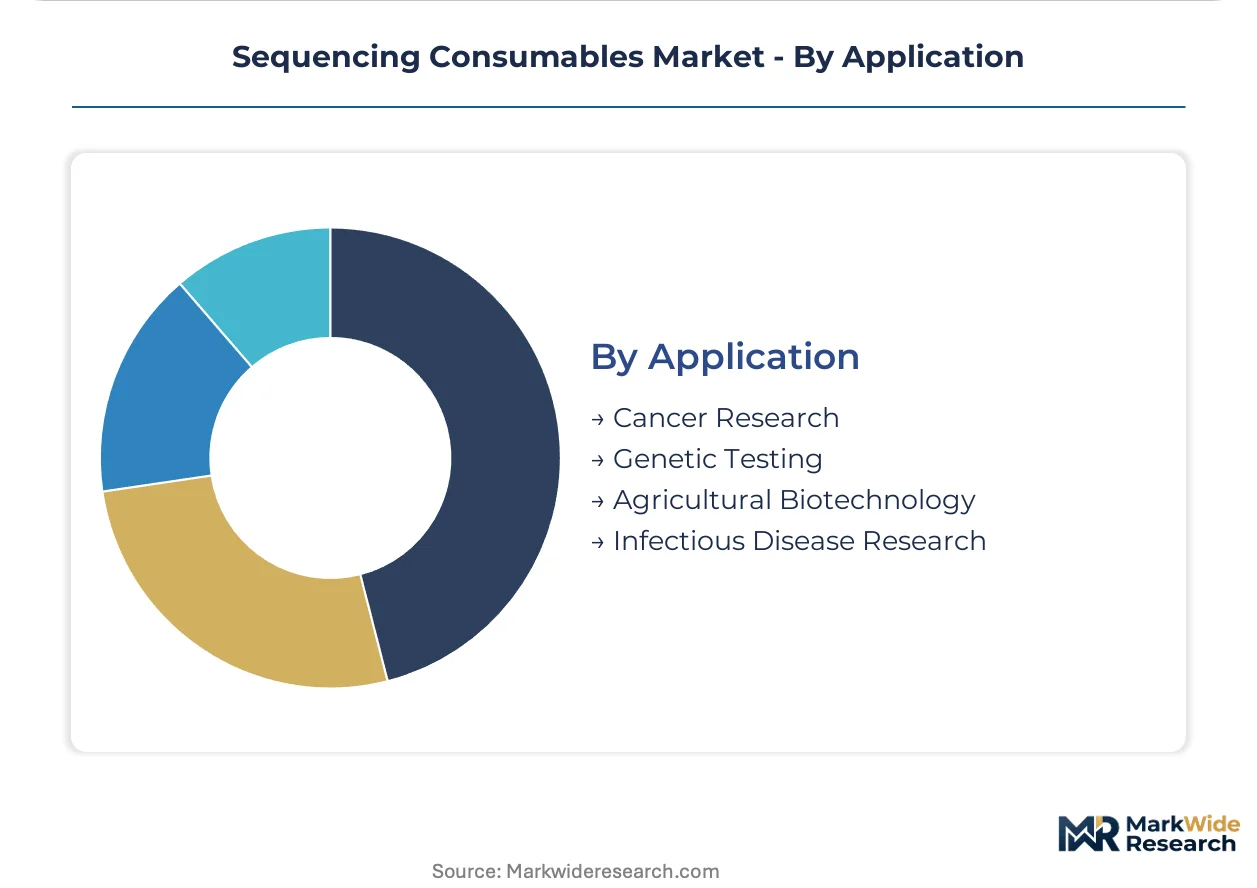
Sequencing consumables fragment across multiple orthogonal dimensions that determine procurement patterns and margin structures. Product chemistry, user workflow integration, platform technology, and disease application each create distinct specification requirements and supplier qualification hurdles.
Product Type:
Standalone reagent formulations operate independently of instrument capture systems, while embedded consumables like flow cells require hardware-locked integration.
- Reagents:Buffer formulations with defined pH stability windows and polymerase concentrations constitute the largest recurring revenue pool. Diagnostic laboratories in the United States maintain safety stock inventories to support continuous cancer panel workflows amid supply volatility.
- Kits:Pre-formulated library preparation systems bundle extraction chemistries, adapters, and quality control reagents into validated workflows. Academic medical centers in Germany and France consolidate purchasing through multi-year framework agreements to secure volume pricing.
- Primers:Solid-phase phosphoramidite synthesis produces oligonucleotide sequences for target enrichment. Custom primer pools support rare disease research cohorts with project-specific panel designs.
- Enzymes:Recombinant polymerase production depends on fermentation capacity concentrated in East Asian biomanufacturing hubs. Price swings in feedstock inputs compress margin stability for mid-tier kit suppliers.
Volume placements concentrate in Reagents; the faster expansion belongs to Kits.
End User:
Customer scale determines procurement leverage, with high-throughput operators commanding preferential pricing against fragmented research buyers.
- Research Institutions:University core facilities and government laboratories drive demand for exploratory sequencing with flexible panel configurations. Budget constraints in European public funding systems delay instrument refresh cycles.
- Diagnostic Labs:Clinical reference laboratories process reimbursable test volumes requiring regulatory-validated consumable lots. ISO 13485 certification has become a baseline threshold for supplier qualification by large diagnostic lab networks in Japan and Australia.
- Pharmaceutical Companies:Companion diagnostic development programs consume high-fidelity reagents for regulatory submission packages. Pharmacogenomic labeling mandates from the FDA expand validated panel consumption in oncology workflows.
- Biotechnology Firms:Cell therapy developers and agricultural genomics startups represent emerging demand with specialized sample preparation requirements. Venture-funded operators prioritize speed-to-result over per-run cost optimization.
Diagnostic Labs capture the highest absolute volume; Biotechnology Firms are climbing the fastest as cell therapy pipelines mature.
Technology:
Platform architecture determines consumable lock-in intensity, with closed systems capturing recurring revenue against open chemistry alternatives.
- Next-Generation Sequencing:Massively parallel cluster generation on patterned flow cells dominates throughput-intensive applications. Semiconductor lithography advances achieve higher cluster density per run, accelerating instrument refresh cycles at research institutes in Germany and the United States.
- Sanger Sequencing:Capillary electrophoresis methods retain validated positions in forensics and paternity testing workflows. Reference laboratories maintain dual reagent inventories to support long-read applications with established regulatory precedent.
- RNA Sequencing:Transcriptome analysis requires specialized library preparation chemistries for strandedness preservation and rRNA depletion. Cancer research consortia drive specification demands for low-input protocols.
- Whole Genome Sequencing:Comprehensive genomic coverage consumes the highest reagent volumes per sample with premium flow cell allocation. Neonatal screening programs and rare disease diagnostics in academic medical centers anchor demand.
Next-Generation Sequencing holds the dominant volume position; RNA Sequencing is gaining share fastest as transcriptomic biomarkers enter clinical validation.
Application:
Disease area complexity dictates panel density and regulatory documentation burden, stratifying consumable value per run.
- Cancer Research:Multi-gene solid tumor and hematologic malignancy panels concentrate the highest-value consumable consumption per run due to regulatory validation requirements. FDA guidance on companion diagnostics expands testing menu breadth at clinical laboratories.
- Genetic Testing:Hereditary disease screening and carrier testing applications standardize on targeted gene panels with established reimbursement pathways. EU In Vitro Diagnostic Regulation performance documentation now extends to Class A reagents previously exempt from systematic review.
- Agricultural Biotechnology:Crop genomics and livestock breeding programs prioritize cost-per-sample optimization over read depth. Bulk purchasing consortia among research stations displace individual laboratory negotiations.
- Infectious Disease Research:Pathogen surveillance and antimicrobial resistance tracking demand rapid turnaround with portable sequencing formats. Public health laboratories in the Netherlands pilot RFID-enabled reagent monitoring converged with laboratory information management systems.
Cancer Research commands the premium tier by revenue per run; Infectious Disease Research is expanding most quickly as genomic surveillance infrastructure deploys post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor concentrates the highest density of sequencing consumable procurement among academic medical centers, with diagnostic laboratories in the metropolitan area processing reimbursable oncology panels at scale. The United States anchors absolute demand through reference laboratory networks and pharmaceutical companion diagnostic programs. Regulatory frameworks and procurement consolidation patterns vary substantially across major national markets.
United States
FDA premarket notification pathways for in vitro diagnostic consumables drive qualification timelines at clinical reference laboratories in the Research Triangle Park corridor. Pharmacogenomic labeling mandates expand validated panel consumption across oncology workflows. Academic medical centers in the northeastern United States negotiate multi-year framework agreements for flow cells and cluster generation kits.
Germany
Research institutes in the Munich-Heidelberg corridor accelerate instrument refresh cycles to capture throughput gains from semiconductor lithography advances. EMA oversight of companion diagnostics converges with EU In Vitro Diagnostic Regulation enforcement to compress supplier documentation timelines. Cancer research consortia in Berlin delay procurement decisions pending ISO 13485 certification completion by reagent vendors.
China
NMPA registration pathways for imported sequencing kits reshape market entry strategies for multinational suppliers in the Shanghai-Zhangjiang biotech cluster. Domestic contract research organizations expand sequencing service capacity to support pharmaceutical development programs. Fermentation capacity for recombinant enzyme production concentrates in Jiangsu and Zhejiang provinces.
Japan
PMDA quality system regulations align with ISO 13485 certification requirements now demanded by diagnostic lab networks in the Kanto region. METI industrial policy supports precision medicine infrastructure deployment at university hospitals in Osaka and Nagoya. Biotechnology firms in the Tokyo-Yokohama corridor prioritize speed-to-result over per-run cost optimization in cell therapy development.
India
CDSCO diagnostic registration streamlining reduces time-to-market for imported sequencing kits entering the Delhi-NCR market. Domestic contract research organizations in Hyderabad and Bengaluru expand next-generation sequencing service capacity for agricultural genomics applications. Centralized approval pathways enable bulk purchasing consolidation among reference laboratories in Maharashtra and Gujarat.
Sequencing Consumables Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sequencing consumable value chain, with captive flow cell manufacturing distinguishing integrated platform vendors from independent chemistry suppliers. The market structure concentrates around three tiers: dominant platform vendors with hardware-locked consumable ecosystems, diversified life science conglomerates with integrated reagent portfolios, and specialized sample preparation firms competing on workflow standardization. Strategic moves center on backward integration into enzyme fermentation capacity and multi-year procurement lock-in through academic medical center framework agreements.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the integrated supply chain archetype spanning enzymes, buffers, and library preparation chemistries. Illumina, Inc. occupies the captive manufacturing position for patterned flow cells that sustain margin capture at the premium tier. QIAGEN sits within the sample preparation specialization tier where EU In Vitro Diagnostic Regulation standardization pressures intensify competitive qualification requirements.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd. |
| Pacific Biosciences of California, Inc. |
| Oxford Nanopore Technologies plc |
| Danaher Corporation |
| Twist Bioscience Corporation |
| Others |
Value Network & Pricing Analysis
Captive flow cell manufacturing by dominant platform vendors anchors supply-side control and sustains premium pricing power across the sequencing consumables value chain. This vertical integration into semiconductor lithography production in the United States and Singapore enables hardware-locked consumable ecosystems that resist third-party substitution and protect margin capture at the high-throughput tier.
Pricing Analysis
Throughput-based pricing anchors consumable contracts at academic medical centers and reference laboratories, with per-run costs scaling to cluster density and read length specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic-grade reagents from research-use-only formulations and unvalidated bulk chemistries. Pricing pressure stems from polymerase input cost volatility tied to fermentation capacity concentration in Chinese and South Korean biomanufacturing hubs. Biotechnology firms and venture-funded cell therapy developers exhibit lowest price sensitivity, prioritizing speed-to-result over per-run cost optimization, while agricultural genomics research stations drive hardest bargain negotiations through bulk purchasing consortia.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive enzyme formulations and pH-stabilized buffer systems compress margins for mid-tier kit suppliers serving fragmented research buyers. Manufacturing concentration centers on the United States for patterned flow cells, Germany for precision optical components, and China for recombinant polymerase fermentation capacity. Raw material dependencies include high-purity phosphoramidite chemistries for oligonucleotide synthesis, semiconductor-grade silicon wafers for flow cell substrates, and specialized yeast strains for enzyme production. Single-source vulnerability around captive flow cell supply creates dependency risk for independent clinical laboratories. Distribution runs through direct platform vendor relationships for high-throughput operators and laboratory distribution intermediaries for smaller research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sequencing consumables market is accelerating into a vertical-integration race, with backward control over enzyme fermentation capacity and flow cell lithography emerging as the decisive competitive lever for margin defense.
For Market Incumbents: Deepen captive manufacturing positions in semiconductor lithography and recombinant enzyme fermentation to defend against emerging open-platform chemistry suppliers. Lock in multi-year framework agreements with academic medical center purchasing consortia before EU In Vitro Diagnostic Regulation certification deadlines compress supplier qualification timelines. Prioritize ISO 13485 quality system investments to maintain baseline threshold status for diagnostic lab network tenders in Japan and Australia. For New Entrants and Emerging Players: Mid-tier reference laboratories excluded from large purchasing consortia represent the most penetrable buyer archetype for flexible reagent sourcing and competitive spot pricing. Liquid biopsy assay standardization for cell-free DNA extraction kits offers white-space entry with lower regulatory validation burden than companion diagnostic panels. Target CDSCO-registered import pathways for sequencing kits entering India's Delhi-NCR and Hyderabad markets where domestic contract research organizations expand service capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking integrated reagent portfolios and platform vendors pursuing consumable ecosystem completeness. Five-to-ten year viability hinges on regulatory validation depth and multi-year procurement lock-in density. Watch for EU In Vitro Diagnostic Regulation enforcement acceleration as the signal indicating consolidation timing for uncertified reagent vendors facing tender exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive polymerase production in Jiangsu and Zhejiang provinces insulates margin stability from feedstock volatility. |
| Multi-Year Framework Agreement Negotiation | Northeastern United States academic medical center consortia secure volume discounts on flow cells and cluster generation kits. |
| ISO 13485 Quality System Certification | Baseline threshold documentation enables supplier qualification by diagnostic lab networks in Japan and Australia. |
| Liquid Biopsy Assay Standardization | Cell-free DNA extraction kit validation creates first-mover advantage in early cancer detection workflows. |
| RFID-Enabled Reagent Tracking Integration | Cloud-converged consumption monitoring supports subscription-based procurement models at Netherlands academic medical centers. |
Research Methodology
Independent corroboration across primary interviews with laboratory directors, reagent procurement managers, regulatory affairs specialists, and biomedical engineers, combined with secondary validation against FDA premarket notification filings, EMA companion diagnostic submissions, ISO 13485 certification databases, and hospital GPO contract repositories, underwrites the qualitative findings. Bottom-up demand modeling across end-user segments triangulates against top-down supply-side capacity assessments for fermentation and lithography infrastructure.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in reagent, kit, and flow cell categories. Segmentation dimensions include product chemistry tier, end-user scale and regulatory status, platform technology architecture, and disease application complexity. CAGRs derive from instrument installed base expansion, throughput per run improvements from semiconductor lithography advances, and panel breadth expansion in pharmacogenomic labeling mandates. Forecast inputs incorporate EU In Vitro Diagnostic Regulation compliance timelines and CDSCO registration pathway streamlining for imported kit suppliers.
Revisions become necessary when polymerase fermentation capacity expansion in East Asia accelerates cost compression, when EU In Vitro Diagnostic Regulation enforcement delays extend supplier qualification bottlenecks, or when liquid biopsy regulatory validation pathways in the United States accelerate faster than modeled. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Canada Hospital Supplies Market