
 Europe Sharps Containers Market | 2026-2036
Europe Sharps Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sharps Containers Market Insights
A capital-intensity divergence between automated manufacturing lines and manual assembly operations is reorganizing competitive hierarchy in the Europe Sharps Containers Market. Daniels Health leverages vertically integrated reprocessing infrastructure across the United Kingdom and Benelux. MAUSER Group anchors its position through captive blow-molding capacity for high-density polyethylene containers serving German clinical networks. Thermo Fisher Scientific differentiates via laboratory-specialized containment formats aligned with biosafety level protocols.
Sharps containers are rigid, puncture-resistant receptacles engineered from polypropylene or high-density polyethylene with tamper-evident closures and fill-level indicators, designed to isolate needles, lancets, and scalpel blades from human contact until terminal treatment. Plastic containers sustain dominant volume share across European hospital procurement due to cost efficiency and incineration compatibility, while reusable containers represent the fastest-expanding category as circular economy mandates intensify under EU Green Deal frameworks. Direct sales channels occupy the largest margin pool through long-term service contracts bundling container supply with collection and treatment logistics.
The EU Medical Device Regulation (MDR) and ECHA REACH standards enforce material traceability and chemical safety documentation for all sharps containment systems marketed in member states. France's ANSM and Germany's BfArM reinforce these frameworks through national vigilance reporting requirements for container failures or needlestick incidents. Stakeholders must monitor pending revisions to the EU Waste Framework Directive that could mandate minimum recycled content thresholds for single-use clinical plastics.
Market Dynamics
Centralized waste management consolidation across German, French, and British hospital networks is compressing supplier margins while favoring service-integrated vendors with captive reprocessing infrastructure.
Growth Catalysts
- EU Medical Device Regulation (MDR):Material traceability mandates for polypropylene and high-density polyethylene containers are accelerating procurement standardization across member state hospital systems.
- REACH compliance documentation:ECHA chemical safety requirements are filtering out non-compliant Asian imports, creating protected demand pockets for European manufacturers with certified supply chains.
- Incineration compatibility:Terminal treatment infrastructure at clinical waste facilities sustains dominant demand for plastic containers over metal alternatives in high-volume hospital procurement.
Market Restraints
- Recycled content feedstock volatility:Post-consumer polypropylene supply constraints from German packaging waste streams are elevating input cost unpredictability for circular-economy container lines.
- Blow-molding equipment concentration:Captive high-density polyethylene production capacity clusters among three German industrial groups, creating supply bottleneck risk for independent container assemblers.
- Reusable container sterilization complexity:Autoclave validation protocols under EN 285 standards impose technical barriers that slow adoption in smaller French and Italian clinical networks.
Strategic Opportunities
- Benelux laboratory specialization:Biosafety level containment formats for pharmaceutical research facilities in Belgium and the Netherlands command premium positioning underserved by general clinical suppliers.
- EU Green Deal circular economy mandates:Pending Waste Framework Directive revisions on minimum recycled content thresholds will advantage early movers with validated reprocessing infrastructure.
- Home healthcare channel expansion:Self-injection therapy growth among diabetic and autoimmune patient populations in the United Kingdom is opening direct-to-patient container distribution through pharmacy networks.
Industry Challenges
- MDR technical documentation compilation:Small and mid-sized manufacturers face 12-18 month certification timelines for updated clinical evaluation reports and post-market surveillance systems.
- Legacy waste management contract integration:Long-term service agreements bundling collection, transport, and treatment resist unbundling, complicating pure-play container supplier market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sharps Containers Market |
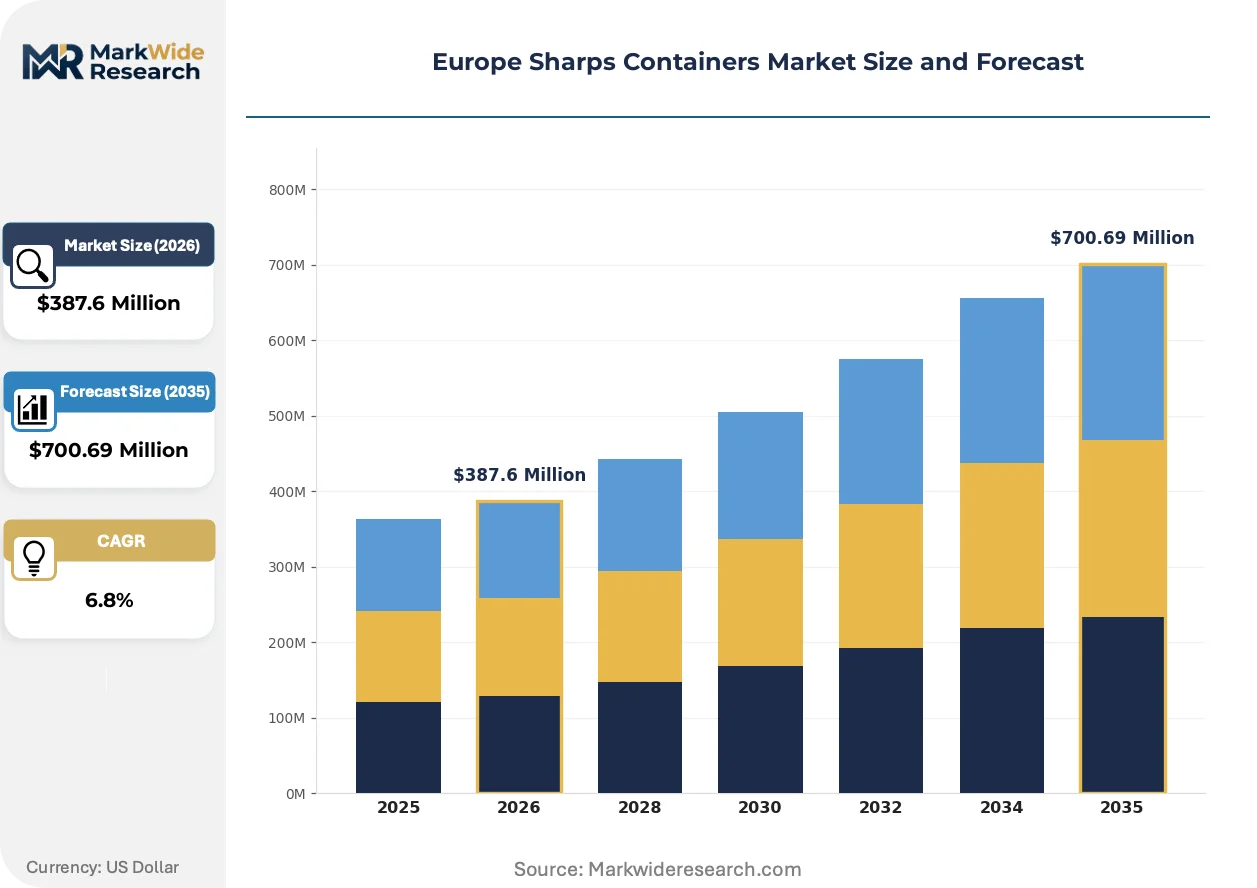
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Metal Containers, Reusable Containers, Biohazard Containers End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Direct Sales, Online Stores, Wholesale Distribution, Retail Outlets Size: Small, Medium, Large, Extra Large |
| Companies Covered | Daniels Health, MAUSER Group, Thermo Fisher Scientific, Stericycle, Becton, Dickinson and Company, Henry Schein, Cardinal Health, Bondtech Corporation, EnviroTain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sharps Containers Market Trends and Innovations
Material science advances and regulatory pressure on single-use plastics are fragmenting the traditional polypropylene-dominant supply base while creating openings for hybrid and reusable formats.
Smart fill-level monitoring systems with RFID-enabled tracking are decomposing the traditional scheduled-collection model in high-throughput German university hospitals. RFID-tagged containers transmit real-time capacity data to waste logistics platforms, enabling dynamic routing that reduces collection frequency by up to forty percent in pilot deployments. This telemetry infrastructure is decomposing margin structures for logistics-only service providers while rewarding integrated container-plus-platform vendors.
ECHA REACH substance restrictions on phthalates and heavy metal stabilizers are forcing reformulation of legacy polypropylene grades used in sharps containment. Manufacturers must submit updated safety data sheets and analytical test reports for all colorants and additives, adding six to nine months to product development cycles. German clinical procurement networks are responding by pre-qualifying suppliers with established registration dossiers, accelerating supplier consolidation.
Long-term service contracts bundling container supply with collection and terminal treatment are displacing transactional purchase orders in French and British hospital systems. These arrangements transfer inventory and compliance liability to vendors while locking in five to seven year revenue streams. The shift is most visible in National Health Service trusts undergoing estate consolidation, where procurement teams prioritize total-cost-of-ownership metrics over unit container pricing.
Europe Sharps Containers Market Segmentation
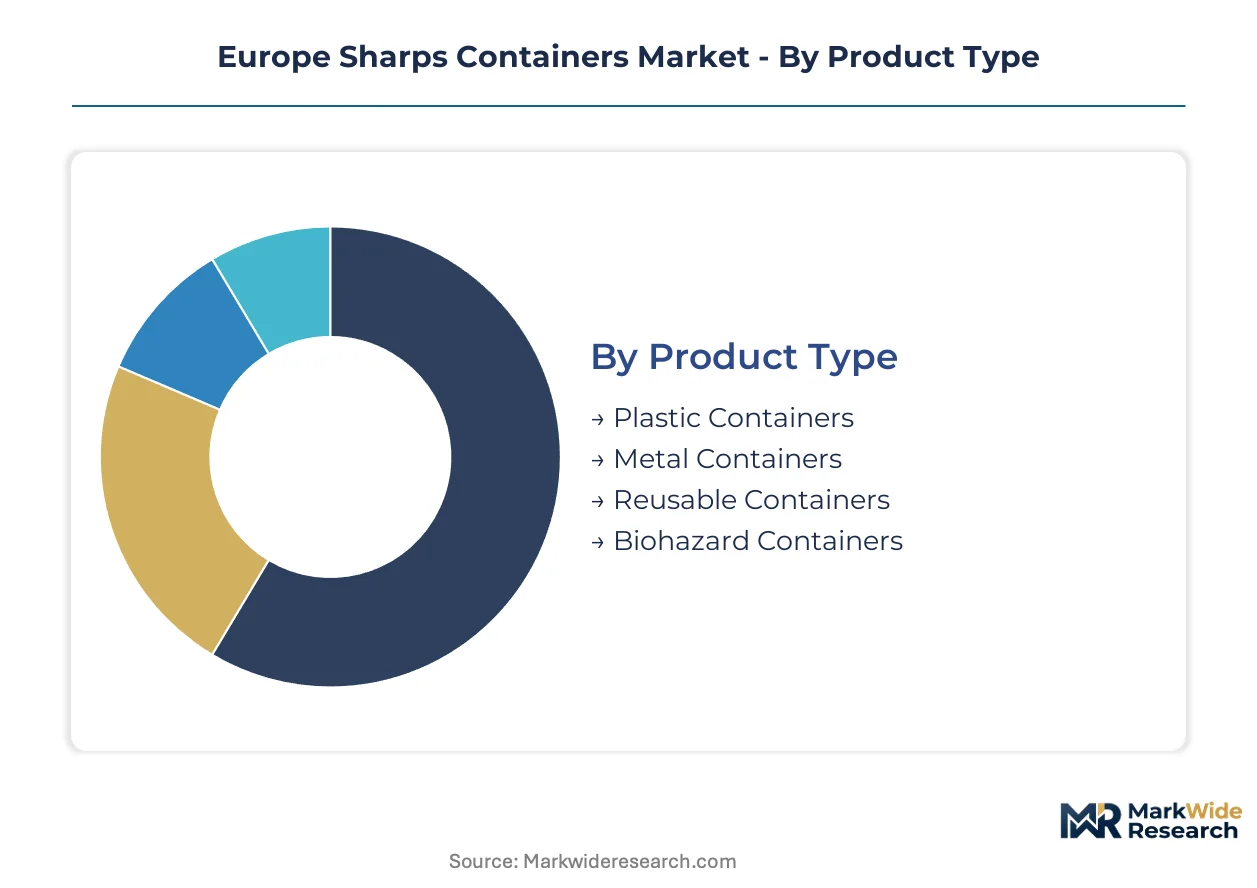
Sharps container procurement patterns across Europe diverge sharply by clinical setting and waste volume, with regulatory compliance requirements fragmenting product specifications across member states. Segmentation clarity enables vendors to align manufacturing capacity with the divergent cost structures and service intensity demands of hospital networks versus home care channels.
Product Type:
Reusable formats face the strongest substitution pressure from single-use alternatives where sterilization infrastructure is absent, while metal containers confront displacement from incineration-optimized polymers in high-throughput German clinical networks.
- Plastic Containers:Polypropylene and high-density polyethylene constructions dominate procurement volumes due to incineration compatibility at clinical waste facilities across Germany, France, and the United Kingdom. German hospital networks undergoing centralized waste management consolidation specify these materials for terminal treatment efficiency. Plastic containers retain volume leadership; reusable containers hold the steepest expansion curve.
- Reusable Containers:Circular economy mandates under EU Green Deal frameworks are accelerating demand for autoclave-validated containment systems with captive reprocessing infrastructure. EN 285 sterilization protocols create adoption barriers in smaller French and Italian clinical networks. Reusable formats gain share fastest where Daniels Health and similar operators control collection logistics.
- Metal Containers:Stainless steel constructions persist in specialized laboratory and pharmaceutical manufacturing settings requiring extreme puncture resistance, though incineration incompatibility limits hospital procurement.
- Biohazard Containers:Color-coded polypropylene formats with tamper-evident closures serve biosafety level protocols in Belgian and Dutch research facilities, commanding premium positioning distinct from general clinical waste streams.
Plastic containers retain volume leadership; reusable containers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital procurement with bundled service contracts from price-sensitive home care channels where pharmacy distribution dominates.
- Hospitals:German, French, and British hospital networks drive procurement concentration through long-term agreements bundling container supply with collection and terminal treatment logistics. NHS trusts prioritize total-cost-of-ownership metrics over unit pricing during estate consolidation. Hospitals anchor revenue concentration; home care climbs the fastest.
- Home Care:Self-injection therapy expansion among diabetic and autoimmune patient populations in the United Kingdom is opening direct-to-patient distribution through pharmacy networks. Small-format containers with patient-friendly closure mechanisms address this channel's distinct compliance requirements.
- Clinics:Independent French and Italian clinical networks face reusable container adoption barriers due to autoclave validation complexity, sustaining demand for single-use formats.
- Laboratories:Biosafety level containment specifications in Belgian and Dutch pharmaceutical research facilities command premium positioning underserved by general clinical suppliers.
Hospitals anchor revenue concentration; home care climbs the fastest.
Distribution Channel:
Margin pool concentration favors direct sales with service integration, while wholesale distribution faces compression from manufacturer disintermediation in large account procurement.
- Direct Sales:Long-term service contracts transferring inventory and compliance liability to vendors lock in five to seven year revenue streams across French and British hospital systems. Direct sales capture the largest margin pool; online stores expand most quickly.
- Online Stores:Pharmacy network e-commerce platforms are emerging as home care channel infrastructure for diabetic and autoimmune patient populations requiring self-injection containment.
- Wholesale Distribution:Independent container assemblers dependent on third-party blow-molding capacity rely on wholesale channels for smaller clinical network access.
- Retail Outlets:Limited penetration concentrated in consumer-facing pharmacy chains serving the United Kingdom home care segment.
Direct sales capture the largest margin pool; online stores expand most quickly.
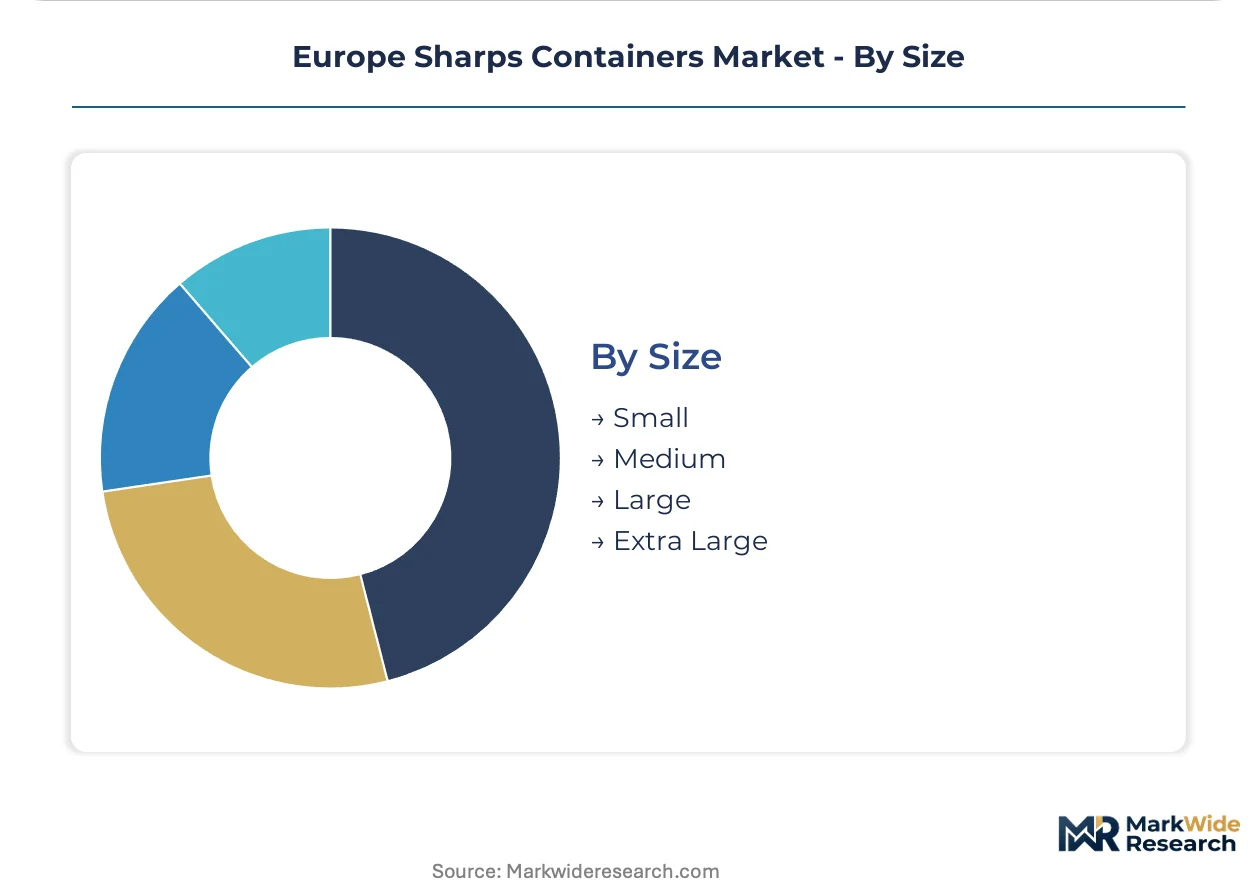
Size:
Volume scale economics concentrate manufacturing investment in large-format production lines, while small formats address fragmentation in point-of-care and home care settings.
- Large:High-throughput German university hospitals deploy RFID-enabled fill-level monitoring systems on large containers to enable dynamic collection routing. Large formats dominate capital equipment allocation; extra large segments expand fastest in centralized waste systems.
- Extra Large:Centralized waste management consolidation across German hospital networks is driving specification of extra large containers for dock-based collection infrastructure.
- Medium:Standard ward-level procurement across French and British hospital systems balances handling ergonomics with collection frequency optimization.
- Small:Point-of-care and home care applications in the United Kingdom require compact formats with patient-safe closure mechanisms for pharmacy distribution.
Large formats dominate capital equipment allocation; extra large segments expand fastest in centralized waste systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks command pricing premiums through bundled service contracts, while Italian clinical procurement operates on transactional spot purchasing with compressed margins. This asymmetry reflects divergent waste management consolidation trajectories across European member states.
Germany
Centralized waste management consolidation across university hospital networks drives specification of RFID-enabled large-format containers with dynamic collection routing. BfArM vigilance reporting requirements enforce material traceability documentation for all polypropylene containment systems. The Rhine-Ruhr industrial corridor hosts captive blow-molding capacity clusters serving clinical networks in North Rhine-Westphalia and Bavaria.
United Kingdom
NHS trust estate consolidation prioritizes total-cost-of-ownership metrics over unit pricing in long-term service agreements bundling supply with collection logistics. MHRA post-market surveillance mandates align with EU MDR transitional provisions for container failure reporting. London and Southeast England procurement hubs are consolidating vendor panels to three to four service-integrated suppliers per trust.
France
Independent clinical networks in regional hospital groupings sustain demand for single-use formats where autoclave validation infrastructure remains absent. ANSM reinforces EU MDR frameworks through national vigilance requirements for needlestick incidents linked to containment failures. The Île-de-France region concentrates pharmaceutical research facility demand for biosafety-level containment formats.
Netherlands
Benelux laboratory specialization creates premium positioning for biosafety containment formats serving pharmaceutical research facilities in Rotterdam and Eindhoven clusters. ECHA REACH compliance documentation requirements filter non-compliant imports from Asian suppliers. Randstad metropolitan procurement networks specify color-coded polypropylene systems with tamper-evident closures for research applications.
Italy
Smaller clinical networks face reusable container adoption barriers due to EN 285 autoclave validation protocol complexity, sustaining single-use format demand. Italian Ministry of Health circular economy guidance anticipates EU Waste Framework Directive recycled content thresholds. Lombardy and Emilia-Romagna hospital procurement operates through regional purchasing consortia with limited vendor consolidation compared to Northern European counterparts.
Europe Sharps Containers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with service-integrated operators commanding premium positioning through captive reprocessing infrastructure while volume manufacturers compete on blow-molding scale economies. The vendor base organizes into three strategic tiers: vertically integrated reprocessing specialists, captive polymer converters, and independent container assemblers dependent on third-party molding capacity. Dominant competitive moves include backward integration into polymer conversion and long-term service contract capture bundling supply with logistics.
Among service-integrated operators, Daniels Health and MAUSER Group exemplify distinct archetypes within the European market structure. Daniels Health anchors the reprocessing-specialist position with validated autoclave infrastructure across the United Kingdom and Benelux. MAUSER Group represents the captive-converter archetype through in-house high-density polyethylene production capacity serving German clinical networks. Thermo Fisher Scientific occupies a specialized tier aligned with laboratory containment protocols rather than general clinical procurement.
| Leading Market Players |
|---|
| Daniels Health |
| MAUSER Group |
| Thermo Fisher Scientific |
| Stericycle |
| Becton, Dickinson and Company |
| Henry Schein |
| Cardinal Health |
| Bondtech Corporation |
| EnviroTain |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts bundling container supply with collection logistics lock in supply access and price visibility across German and British hospital networks. These arrangements transfer inventory liability to vendors while compressing margins for pure-play manufacturers lacking captive reprocessing infrastructure.
Pricing Analysis
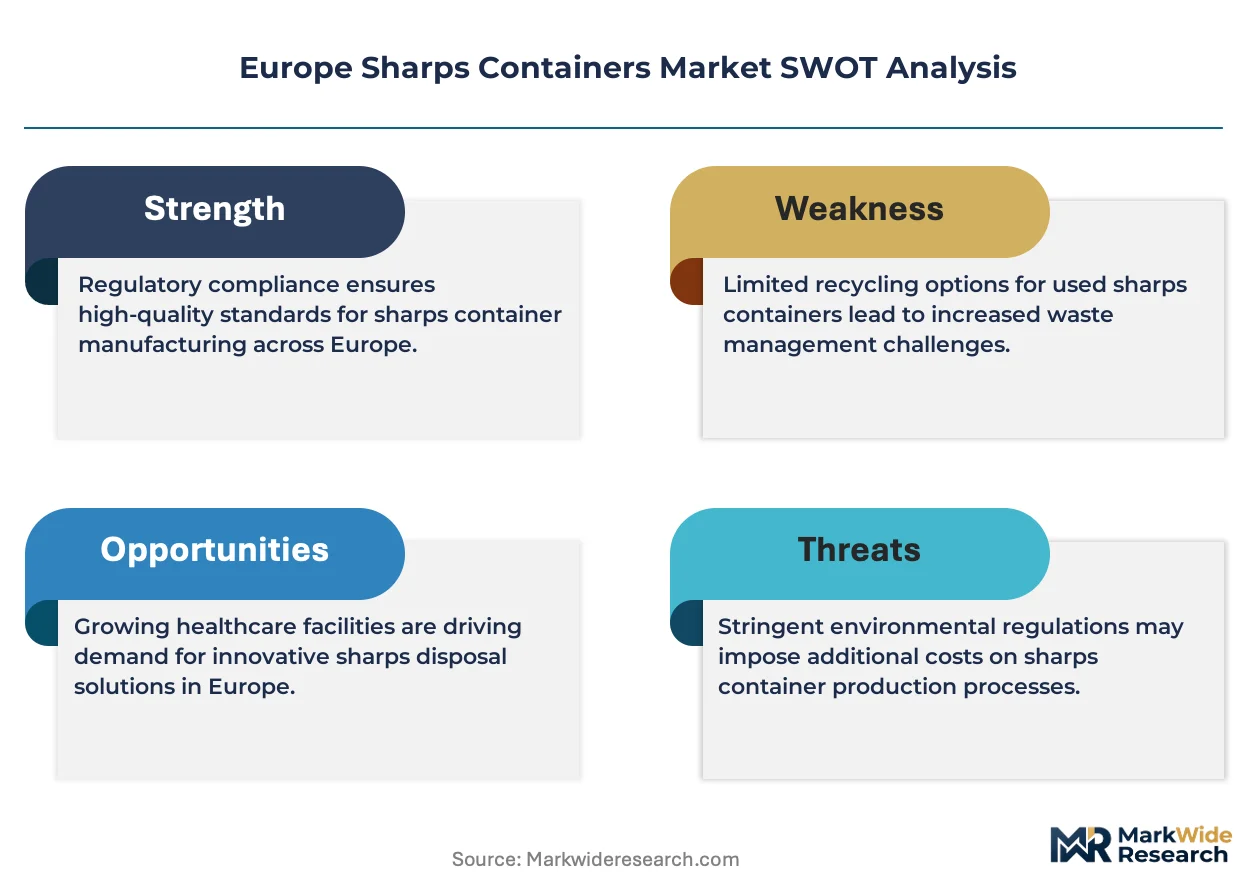
Configured-to-order pricing for RFID-enabled containers with fill-level telemetry commands a 15-25% premium over standard polypropylene formats in German university hospital procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Price compression runs through the standard tier as Asian imports filtered by REACH documentation gaps create spot-market softness. Home care channels through UK pharmacy networks exhibit the highest price sensitivity due to patient out-of-pocket exposure.
Supply Chain Analysis
Germany and Belgium anchor European blow-molding capacity for high-density polyethylene clinical containers serving hospital networks across the Rhine-Ruhr corridor and Benelux. Polypropylene resin supply draws from German packaging waste streams and Belgian petrochemical complexes, with colorant and additive formulations subject to ECHA REACH substance restrictions. Single-source vulnerability clusters around three German industrial groups controlling captive production equipment. Distribution runs through direct sales channels for large hospital accounts and wholesale networks for smaller clinical assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Sharps Containers Market represents an early-cycle expansion story as EU Green Deal circular economy mandates accelerate reusable format adoption ahead of pending Waste Framework Directive recycled content thresholds.
For Market Incumbents: Consolidate reprocessing infrastructure through backward integration into autoclave validation capacity across the United Kingdom and Benelux. Capture long-term service contracts with NHS trusts undergoing estate consolidation to lock out independent container assemblers dependent on third-party molding. Prioritize EN 285 sterilization protocol certification to defend against emerging reusable specialists. For New Entrants and Emerging Players: Differentiate on biosafety level containment formats for Belgian and Dutch pharmaceutical research facilities where general clinical suppliers hold limited presence. Target the UK home care channel through pharmacy e-commerce platforms serving self-injection therapy patients with compact patient-safe formats. Pursue white-label manufacturing partnerships with independent French clinical networks lacking autoclave infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with validated reprocessing infrastructure and captive polymer conversion capacity. The 5-10 year viability window favors service-integrated vendors over pure-play container manufacturers facing margin compression from centralized procurement consolidation. Monitor EU Waste Framework Directive recycled content threshold announcements as the primary inflection signal for circular-economy format acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blow-Molding Capacity | Captive high-density polyethylene production insulates German clinical suppliers from third-party equipment bottlenecks. |
| RFID-Enabled Container Telemetry Deployment | Smart fill-level monitoring decomposes scheduled-collection models in German university hospital networks. |
| Autoclave Validation Infrastructure Expansion | EN 285-compliant reprocessing capacity unlocks reusable format share gains under EU Green Deal mandates. |
| Long-Term Service Contract Capture | Five-to-seven year NHS trust agreements transfer compliance liability while locking revenue streams. |
| Pharmacy Network E-Commerce Partnership | Direct-to-patient distribution through UK pharmacy platforms addresses home care channel fragmentation. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and waste logistics operators provided ongoing calibration across primary fieldwork. Secondary validation drew from EU MDR registration databases, ECHA REACH dossier filings, NHS procurement transparency data, and German hospital association waste management surveys. Bottom-up container volume estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, end user, distribution channel, and size segmentation dimensions. CAGRs were derived from fitted growth curves incorporating EU regulatory timeline assumptions and hospital consolidation trajectory indicators. Modeled inputs included MDR certification pipeline data, REACH compliance registration status, and centralized waste management contract award patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated hospital consolidation timelines would require recalibration. Forecasts reflect documented assumptions regarding REACH substance restriction implementation and Waste Framework Directive revision schedules. Recalibration cycles align with material shifts in EU circular economy policy and national hospital procurement consolidation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Mortuary Bags Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Lab Trays Market
Medical Supplies
Medical Gas Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Global Needles Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Pre-Packaged Medical Supplies Market