
 Urine Meter Trays Market | 2026-2036
Urine Meter Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Meter Trays Market Analysis
Shift from reusable metal trays to polymer-based single-use systems is tilting manufacturing priorities across the supply base. Medline Industries leverages its domestic production footprint to sustain cost advantages in high-volume disposable lines. Cardinal Health anchors its position through extensive distribution contracts with integrated delivery networks. B. Braun Melsungen AG differentiates via specialized sterile packaging capabilities that reduce contamination risk in surgical settings.
Urine meter trays are calibrated receptacles, typically molded from medical-grade polypropylene or polystyrene, designed to collect, measure, and temporarily store urine output for diagnostic or monitoring purposes in clinical environments. The devices incorporate graduated volumetric markings and drainage ports to ensure accurate measurement and safe fluid transfer. Single-use trays command the largest revenue share due to hospital preference for eliminating reprocessing labor and cross-contamination liability. Reusable trays retain niche demand in research facilities where cost-per-use calculations favor durable instruments. Plastic dominates material selection because thermoforming and injection molding enable rapid scale-up with consistent dimensional tolerance.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern tray design validation, biocompatibility testing, and manufacturing documentation for US market entry. EPA regulations on medical waste classification influence disposal protocol development and end-user training obligations. Stakeholders must monitor evolving single-use plastics legislation in multiple states, as material bans or extended producer responsibility frameworks could force rapid reformulation or supply chain restructuring.
Market Dynamics
Hospital infection control mandates are accelerating the phase-out of reusable metal trays in favor of polymer-based single-use systems, forcing manufacturers to retool production lines and renegotiate resin supply contracts.
Growth Catalysts
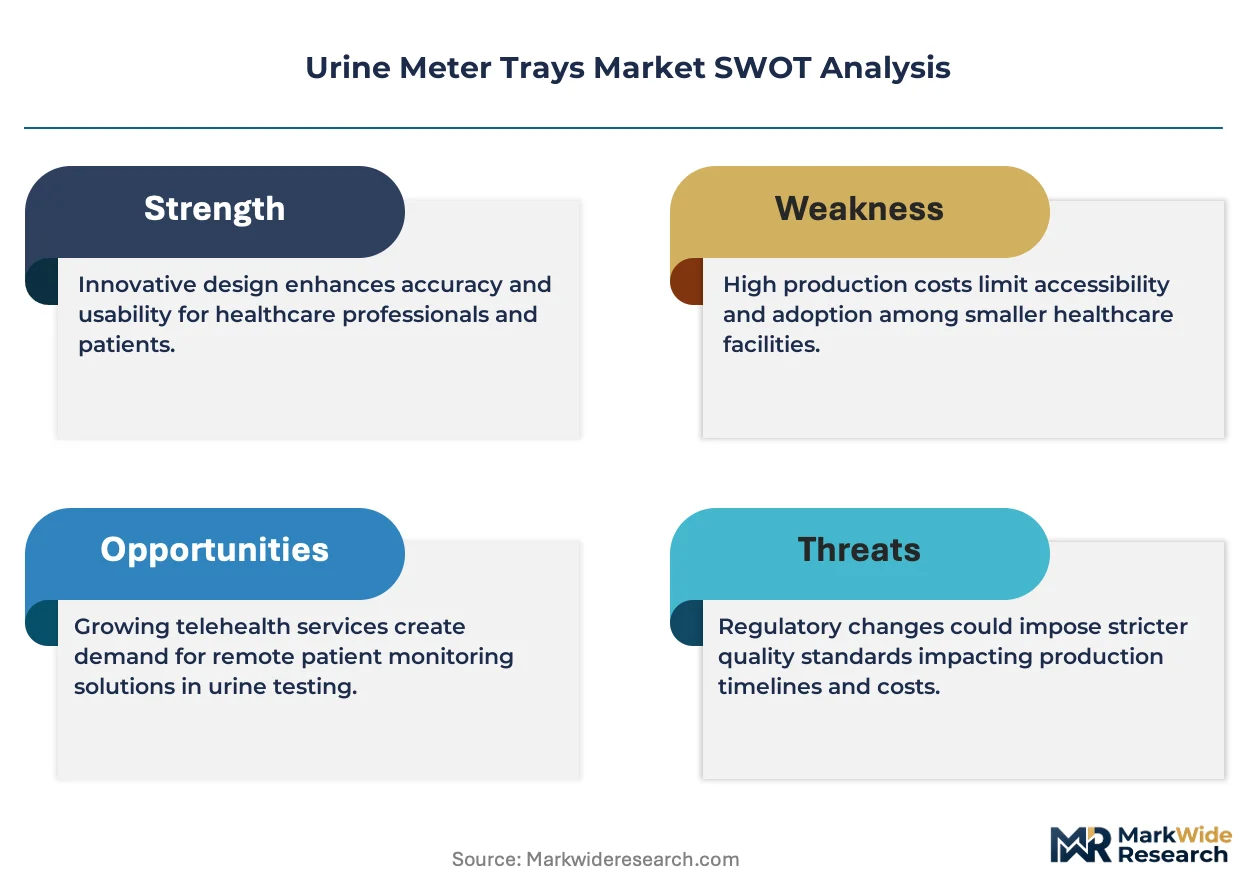
- Updated FDA 510(k) Guidelines:Tighter biocompatibility documentation requirements favor established sterile packaging specialists over smaller competitors, consolidating procurement toward compliant suppliers.
- Acute Care Volume Concentration:United States hospital systems are standardizing tray specifications across integrated delivery networks, creating pull-through demand for single-use configurations.
- Medical-Grade Polypropylene Scale-Up:Domestic thermoforming capacity expansion enables faster order fulfillment for high-volume disposable lines.
Market Restraints
- Resin Price Volatility:Polypropylene feedstock costs fluctuate with petrochemical output, squeezing margin stability for molded tray producers.
- Waste Classification Friction:EPA medical waste disposal protocols impose training burdens and liability exposure that deter smaller facilities from volume purchasing.
- Reusable Tray Substitution:Research laboratories continue deploying autoclavable metal instruments where cost-per-use calculations override infection risk concerns.
Strategic Opportunities
- Home Healthcare Penetration:Post-acute and long-term care settings in the United States represent underdeveloped demand for calibrated collection systems outside hospital walls.
- Extended Producer Responsibility Frameworks:State-level single-use plastics legislation creates first-mover advantage for biodegradable polymer formulations.
- RFID-Enabled Inventory Tracking:Convergence of molded tray production with embedded sensor technology opens subscription-based replenishment contracts.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits create 12-18 month entry barriers for new manufacturing entrants.
- Legacy Sterilization Infrastructure:Hospital central supply departments face workflow disruption when transitioning from reprocessing to disposable paradigms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Meter Trays Market |
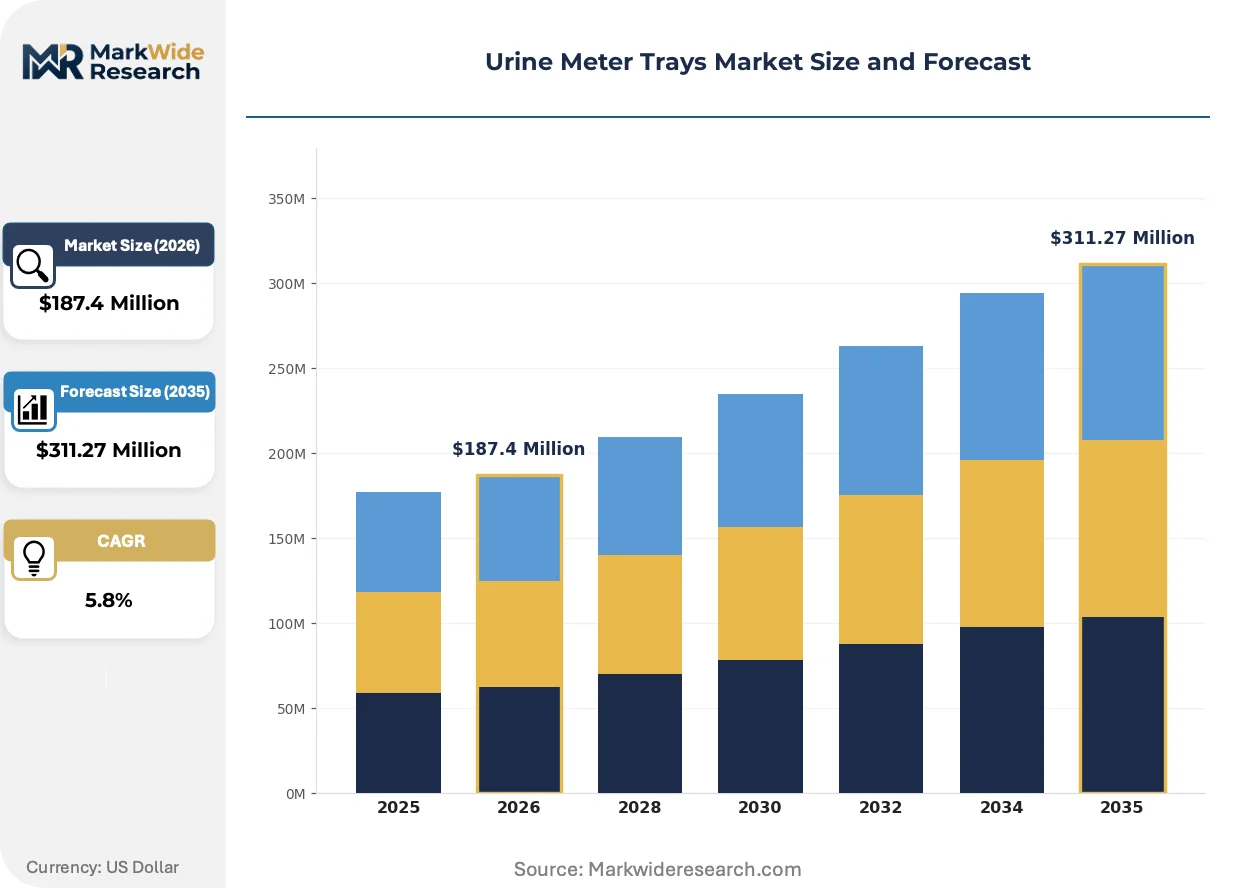
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Trays, Reusable Trays, Disposable Trays, Sterile Trays Material: Plastic, Metal, Glass, Composite Application: Clinical Labs, Home Healthcare, Hospitals, Research Facilities End User: Nursing Homes, Diagnostic Centers, Patients, Laboratories |
| Companies Covered | Medline Industries, Cardinal Health, BD, Teleflex Incorporated, B. Braun Melsungen AG, Medtronic, C. R. Bard, Smiths Medical, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Meter Trays Market Emerging Trajectories
Tray manufacturers are embedding connectivity and sustainability features into previously commoditized products, while procurement departments restructure supplier relationships around compliance documentation rather than unit pricing alone.
Embedded RFID tags and barcode systems are digitizing supply chain visibility from manufacturing floor to patient bedside. Large health systems in the United States are piloting automated restocking programs that trigger replenishment when tray inventory hits threshold levels. This connectivity infrastructure is digitizing procurement workflows and compressing the traditional distributor role toward pure logistics.
State legislatures in California, New York, and Washington are advancing extended producer responsibility bills that classify medical single-use plastics under mandatory recycling or biodegradable substitution timelines. Manufacturers with domestic compounding capabilities are reformulating polypropylene blends to meet anticipated performance standards. The regulatory pressure is concentrating investment toward bio-based resin qualification programs.
Hospital materials management departments are consolidating supplier rosters and demanding consolidated invoicing across infection control product categories. Distributors respond by bundling tray contracts with adjacent disposable lines. This purchasing consolidation is most visible in United States integrated delivery networks, where standardization committees now mandate single-source agreements for sterile procedure kits.
Urine Meter Trays Market Segmentation
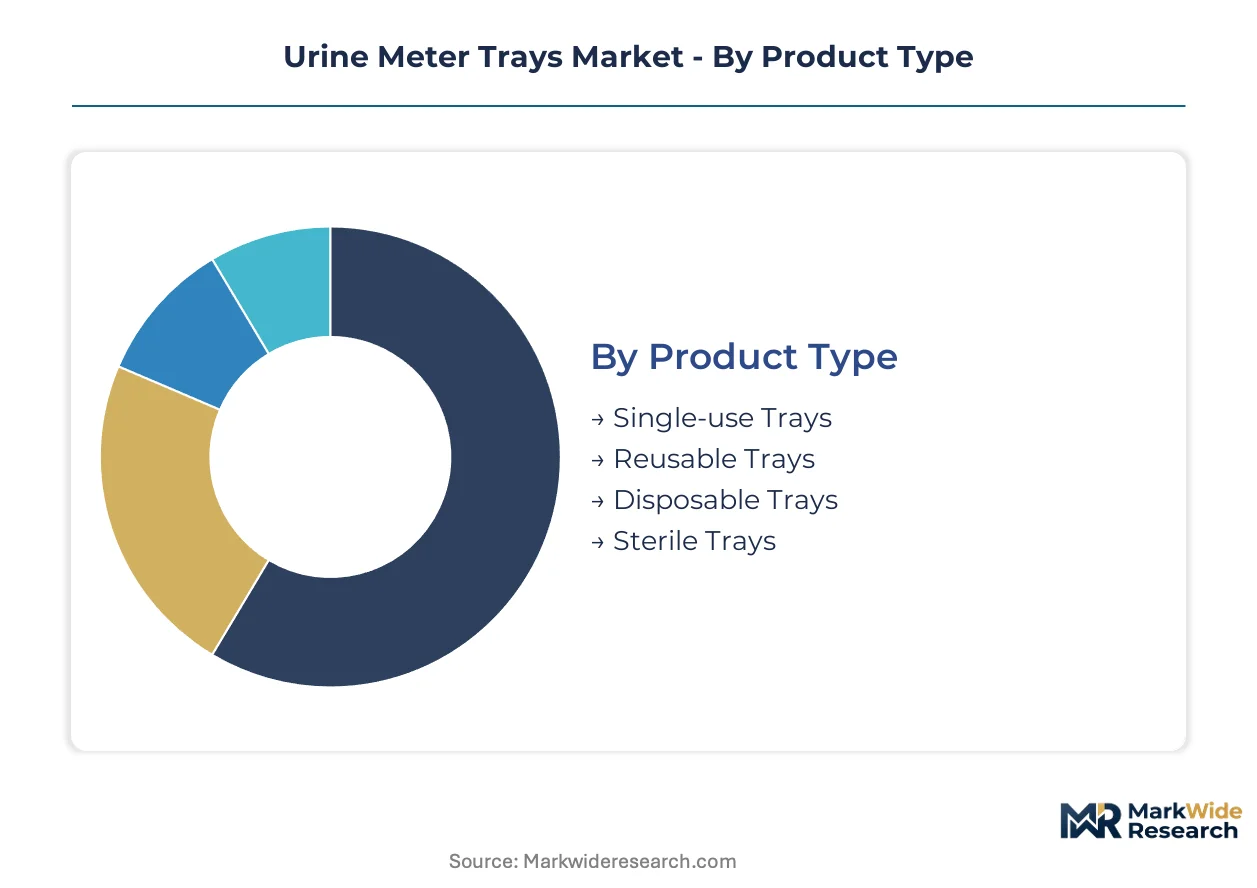
Urine meter tray procurement patterns diverge sharply across clinical settings. Cycle times, contamination protocols, and reimbursement structures create distinct demand profiles that manufacturers must address through targeted product configurations.
Product Type:
Single-use configurations turn over fastest in acute care environments, while reusable instruments persist where sterilization infrastructure justifies extended depreciation schedules.
- Single-use Trays:Molded medical-grade polypropylene with graduated volumetric markings and integrated drainage ports. United States acute care facilities drive procurement volume as infection control mandates eliminate reprocessing labor from central supply workflows.
- Reusable Trays:Autoclavable metal or polymer instruments designed for repeated sterilization cycles. Research facilities in the United States retain this category where cost-per-use calculations override single-use convenience premiums.
- Disposable Trays:Non-sterile configurations for general collection without calibrated measurement requirements. Home healthcare settings in the United States absorb volume where Medicare reimbursement constraints limit equipment expenditure.
- Sterile Trays:Individually packaged units with validated sterility assurance levels for surgical and intensive care applications. Operating room procurement committees in United States hospitals specify this category for catheterization procedures.
Single-use trays dominate installed base. Sterile trays are where expansion concentrates.
Material:
Cost tiers separate commodity thermoformed products from precision-engineered alternatives, with resin selection determining both unit economics and regulatory pathway complexity.
- Plastic:Polypropylene and polystyrene formulations processed through injection molding or thermoforming. United States hospital systems standardize on this material for its dimensional consistency and rapid scale-up potential under FDA 510(k) pathways.
- Metal:Stainless steel or aluminum alloys fabricated for autoclavable durability. Research laboratories in the United States deploy this category where instrument longevity justifies higher capital outlay.
- Glass:Borosilicate configurations for chemical resistance and optical clarity in specialized diagnostic protocols. Reference laboratories in the United States maintain limited inventory for specific analytical procedures.
- Composite:Hybrid constructions combining polymer bases with reinforcing elements for enhanced structural properties. Emerging formulations target California extended producer responsibility compliance requirements.
Plastic commands procurement volume. Composite formulations are climbing the fastest as biodegradability mandates reshape material specifications.
Application:
Customer type dictates specification stringency, with institutional buyers demanding documentation bundles that individual consumers bypass entirely.
- Clinical Labs:High-precision calibrated instruments with traceable measurement certification. United States reference laboratories drive demand for lot-controlled manufacturing and comprehensive biocompatibility documentation.
- Home Healthcare:Simplified configurations with intuitive graduated markings for patient or caregiver operation. Post-acute settings in the United States represent underdeveloped demand as remote monitoring protocols expand.
- Hospitals:Standardized sterile or single-use trays integrated into procedure kits. Integrated delivery networks in the United States consolidate specifications across member facilities to capture volume pricing.
- Research Facilities:Customizable instruments with autoclavable durability for protocol flexibility. Academic medical centers in the United States maintain diverse inventories supporting experimental methodologies.
Hospitals anchor procurement volume. Home healthcare is gaining share fastest as reimbursement shifts toward outpatient settings.
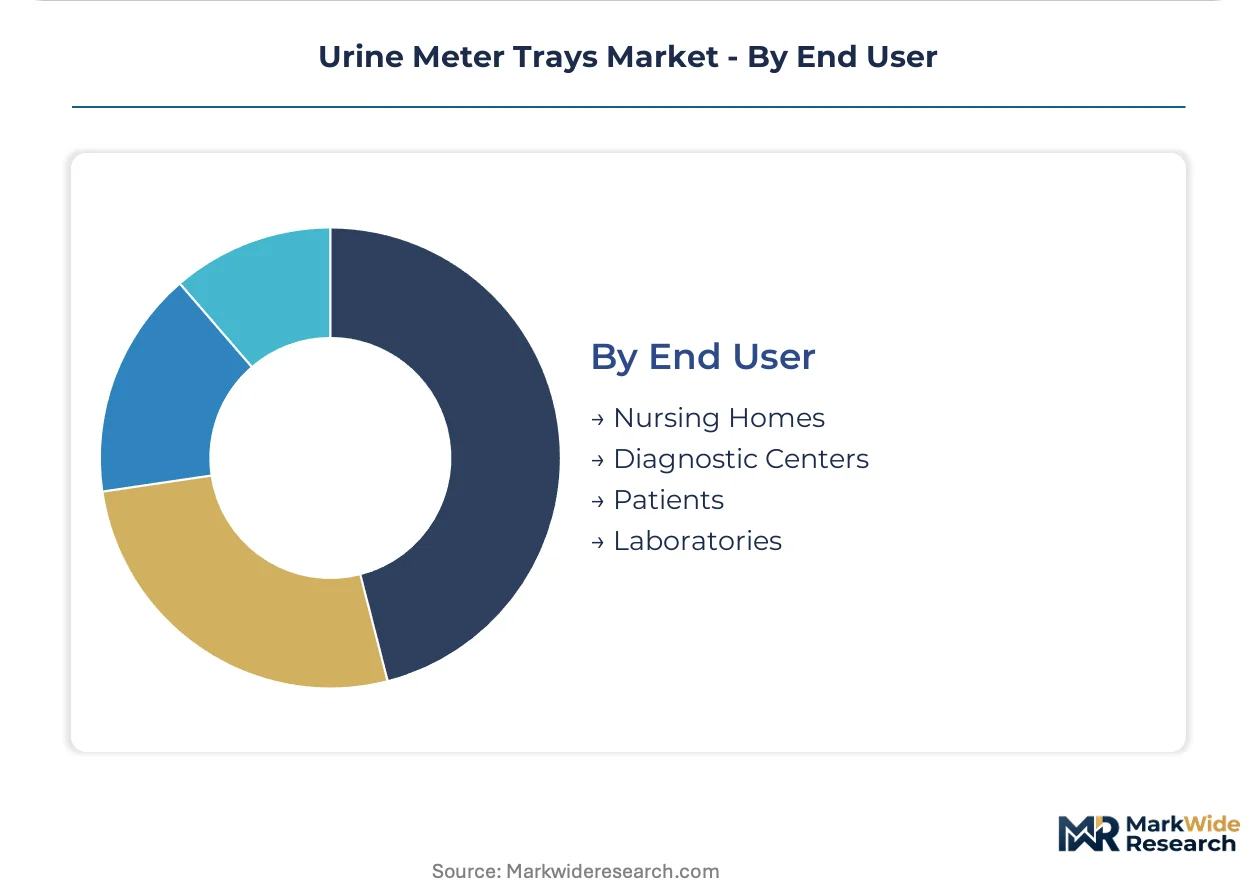
End User:
Volume concentration varies dramatically across purchaser categories, with institutional buyers consolidating spend while fragmented individual demand resists standardization.
- Nursing Homes:Cost-optimized single-use configurations for routine monitoring without intensive care precision requirements. Long-term care chains in the United States negotiate bundled contracts across infection control product categories.
- Diagnostic Centers:Calibrated instruments with rapid turnaround specifications for high-throughput urine analysis. Outpatient laboratory networks in the United States prioritize supply chain reliability over unit cost minimization.
- Patients:Direct-to-consumer configurations distributed through retail or durable medical equipment channels. Medicare Advantage plans in the United States increasingly cover home monitoring supplies.
- Laboratories:Reference-grade instruments with measurement uncertainty documentation for forensic or clinical validation. CAP-accredited facilities in the United States demand comprehensive quality management system certification from suppliers.
Diagnostic centers dominate institutional procurement. Patient-direct channels are expanding most quickly as home-based care models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in urine meter trays tilt toward net-import positions across most developed healthcare systems, with domestic thermoforming capacity concentrated in the United States and Germany supplying regional demand clusters.
United States
Acute care facilities drive procurement volume through integrated delivery network standardization committees. FDA 510(k) clearance requirements and updated biocompatibility documentation protocols favor established domestic sterile packaging specialists. Midwestern manufacturing corridors around Chicago sustain thermoforming capacity expansion for high-volume disposable lines.
Germany
Precision-engineered polymer formulations serve clinical laboratory and research facility demand across Central Europe. EU MDR compliance timelines and ISO 13485 quality management audits create certification barriers that consolidate procurement toward certified suppliers. Baden-Württemberg industrial clusters around Stuttgart maintain injection molding expertise for medical-grade polypropylene instruments.
China
Domestic hospital procurement is accelerating polymer-based single-use adoption as NMPA medical device registration pathways mature. National healthcare reform initiatives and tiered diagnosis-treatment systems expand standardized equipment purchasing across provincial hospital networks. Yangtze River Delta manufacturing zones around Shanghai scale thermoforming output for cost-optimized export configurations.
Japan
Aging demographics and home healthcare expansion generate demand for calibrated collection systems outside institutional settings. PMDA quality management requirements and JIS standards govern tray design validation and biocompatibility testing for market entry. Kanto industrial corridors around Tokyo concentrate precision molding capabilities for high-specification clinical instruments.
India
Diagnostic center networks and tier-two hospital procurement drive volume for single-use configurations as CDSCO medical device rules tighten quality documentation. Ayushman Bharat insurance expansion and public health mission programs channel standardized equipment purchasing toward accredited suppliers. Gujarat pharmaceutical manufacturing clusters around Ahmedabad extend polymer processing capabilities into medical device components.
Urine Meter Trays Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: domestic-scale thermoformers with hospital distribution contracts, multinational sterile packaging specialists with regulatory documentation depth, and research-oriented fabricators serving autoclavable niches. Strategic archetypes include volume-driven disposable manufacturers, compliance-forward sterile packaging integrators, and durable-instrument specialists serving laboratory segments. Dominant competitive moves center on integrated delivery network contract consolidation and resin supply chain backward integration to buffer feedstock volatility.
Among North American-based suppliers, Medline Industries, Cardinal Health, and B. Braun Melsungen AG occupy positions across the volume and compliance tiers. Medline Industries exemplifies domestic-scale thermoforming with distribution network density. Cardinal Health represents the consolidated procurement and logistics integration archetype. B. Braun Melsungen AG anchors the sterile packaging specialization tier with European regulatory pathway expertise.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| BD |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Medtronic |
| C. R. Bard |
| Smiths Medical |
| Coloplast |
| Others |
Supply Flow & Price Mechanics
Midwest thermoforming undercapacity across Chicago-area medical-grade polypropylene facilities is compressing order fulfillment timelines and tilting supplier bargaining power toward resin compounders with captive supply agreements.
Pricing Analysis
Hospital procurement departments anchor contract-based long-term offtake structures that stratify across FDA 510(k) certification tiers, volume scale commitments, and sterile packaging complexity. Price differentiation hinges on biocompatibility documentation depth and integrated delivery network bundling scope. Cost compression in standard single-use configurations is intensifying as domestic resin compounders pass through petrochemical feedstock volatility. Research laboratories exhibit lowest price sensitivity due to autoclavable instrument depreciation schedules, while home healthcare distributors face Medicare reimbursement ceilings that constrain equipment expenditure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material sourcing risk for medical-grade polypropylene feedstock. Manufacturing concentrates in the United States, Germany, and China, with the Yangtze River Delta scaling thermoforming output for cost-optimized export configurations. The supply chain draws from petroleum-derived propylene monomer, specialized colorants, and sterile barrier packaging films. Single-source vulnerability concentrates in domestic resin compounding capacity. Distribution runs through integrated delivery network consolidated contracts and group purchasing organization logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile packaging documentation depth functions as the scarce capability separating contract winners from commodity suppliers, with ISO 13485 certification timelines creating twelve-to-eighteen month entry barriers.
For Market Incumbents: Entrench integrated delivery network relationships through bundled infection control product contracts that capture standardization committee mandates. Backward integration into medical-grade polypropylene compounding buffers resin price volatility from petrochemical output fluctuations. Prioritize California, New York, and Washington extended producer responsibility compliance investment to preempt biodegradable formulation requirements. For New Entrants and Emerging Players: Home healthcare penetration across post-acute and long-term care settings represents the most penetrable demand cluster outside hospital procurement concentration. Medicare Advantage plan coverage expansion for remote monitoring supplies enables direct-to-consumer channel development. Target simplified calibrated collection configurations with intuitive graduated markings for patient or caregiver operation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable polymer formulation programs as state-level single-use plastics legislation accelerates. Acquisition candidates with domestic thermoforming capacity and existing FDA 510(k) clearance portfolios offer consolidated positioning. Monitor CDSCO medical device rule tightening in India as signal for quality-documentation barrier expansion across emerging market procurement.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system depth consolidates procurement toward compliant sterile packaging specialists under FDA guidelines. |
| Biodegradable Polymer Formulation Program | Extended producer responsibility compliance in California creates first-mover positioning against material substitution mandates. |
| Integrated Delivery Network Contract Consolidation | Bundled infection control product agreements capture standardization committee single-source mandates across member facilities. |
| RFID-Enabled Inventory Tracking Integration | Embedded sensor convergence opens subscription-based replenishment contracts with automated threshold-triggered restocking. |
| Domestic Thermoforming Capacity Expansion | Midwest manufacturing corridor scale-up accelerates order fulfillment for high-volume disposable lines under acute care demand. |
Methodological Framework
Cross-validation between hospital procurement database analysis and biomedical engineering director interviews anchors the qualitative findings across this study. Primary fieldwork engaged hospital purchasing committee members, GPO contracts managers, sterile packaging specialists, and central supply department heads. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement schedules, hospital procurement databases, and state extended producer responsibility legislation tracking. Bottom-up demand modeling triangulated against top-down thermoforming capacity assessments.
Calibration against historical volume trajectories and resin price elasticity patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type configuration, material formulation grade, clinical application setting, and end-user procurement archetype. CAGRs were derived from installed base turnover rates and infection control protocol adoption curves. Sterile packaging certification timelines and integrated delivery network contract renewal cycles fed industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by domestic resin compounders or rapid biodegradable formulation breakthroughs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Specimen Containers Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
United Kingdom Hospital Supplies Market