
 Saudi Arabia Hospital Supplies Market | 2026-2036
Saudi Arabia Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Hospital Supplies Market Analytics
Digital inventory management and RFID-enabled supply tracking is rewriting procurement workflows across Saudi hospital networks. B. Braun Melsungen AG leverages its German manufacturing base to sustain catheter and infusion therapy dominance in the Kingdom. Cardinal Health Inc anchors its position through direct sales contracts with Ministry of Health-affiliated facilities. Stryker Corporation differentiates via specialized surgical navigation tools aligned with SFDA orthopedic device standards.
Hospital supplies encompass single-use disposables, reusable surgical instruments, diagnostic apparatus, and patient monitoring accessories manufactured from medical-grade polymers, stainless steel, and electronic sensor arrays, serving infection control, surgical intervention, and clinical diagnostics in acute care settings. Disposable Supplies generate the largest revenue pool due to recurrent consumption patterns in high-throughput tertiary centers, while Diagnostic Equipment captures premium margins from imaging and laboratory automation upgrades. Specialty Care Facilities represent the fastest-growing end-user channel as Saudi Arabia privatizes select rehabilitation and long-term care services.
SFDA enforces medical device marketing authorization and post-market surveillance under the Medical Devices Interim Regulation, compelling foreign manufacturers to establish local authorized representatives. The Ministry of Health's Unified Procurement Company centralizes bulk purchasing for public hospitals, reshaping vendor qualification criteria and contract structures. Stakeholders must monitor Health Sector Transformation Program procurement reforms and SFDA localization incentives to align manufacturing partnerships with Saudi supply chain priorities.
Market Dynamics
The Ministry of Health's Unified Procurement Company is consolidating bulk purchasing authority for public hospital networks, compressing vendor margins while forcing manufacturers to restructure distribution partnerships around Riyadh-centric logistics hubs.
Growth Catalysts
- Health Sector Transformation Program:Government procurement reforms mandate standardized consumable specifications across tertiary care facilities, creating predictable volume commitments for qualified suppliers.
- RFID-enabled supply tracking:Real-time inventory visibility reduces stockout incidents in high-throughput surgical departments and cuts carrying costs for centralized warehouse operations.
- Central Region hospital clustering:Riyadh and Jeddah tertiary centers account for disproportionate surgical volume, concentrating demand pull for advanced disposable catheter and infusion therapy products.
Market Restraints
- SFDA registration timelines:Medical device marketing authorization under the Interim Regulation extends product entry cycles by 12-18 months for foreign manufacturers lacking local authorized representatives.
- Polymer feedstock volatility:Medical-grade polypropylene and PVC resin prices fluctuate with petrochemical export quotas, compressing margins on high-volume disposable categories.
- Single-source sterilization services:Gamma and ethylene oxide sterilization capacity concentrates in Jeddah industrial zones, creating geographic bottlenecks for nationwide distribution.
Strategic Opportunities
- Eastern Province expansion:Dammam and Khobar hospital networks remain underpenetrated relative to Riyadh, offering first-mover advantages for catheter and wound care suppliers establishing local distribution.
- SFDA localization incentives:Domestic manufacturing partnerships qualify foreign vendors for preferential procurement scoring under Ministry of Health tender evaluations.
- Long-term care privatization:Rehabilitation and skilled nursing facility licenses are opening to private operators, creating new channels for patient monitoring accessories and mobility aids.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital supply chain departments lack personnel trained in RFID system integration and predictive analytics platforms.
- Legacy ERP integration:Public hospital networks operate fragmented inventory management systems that resist real-time data exchange with centralized procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Hospital Supplies Market |
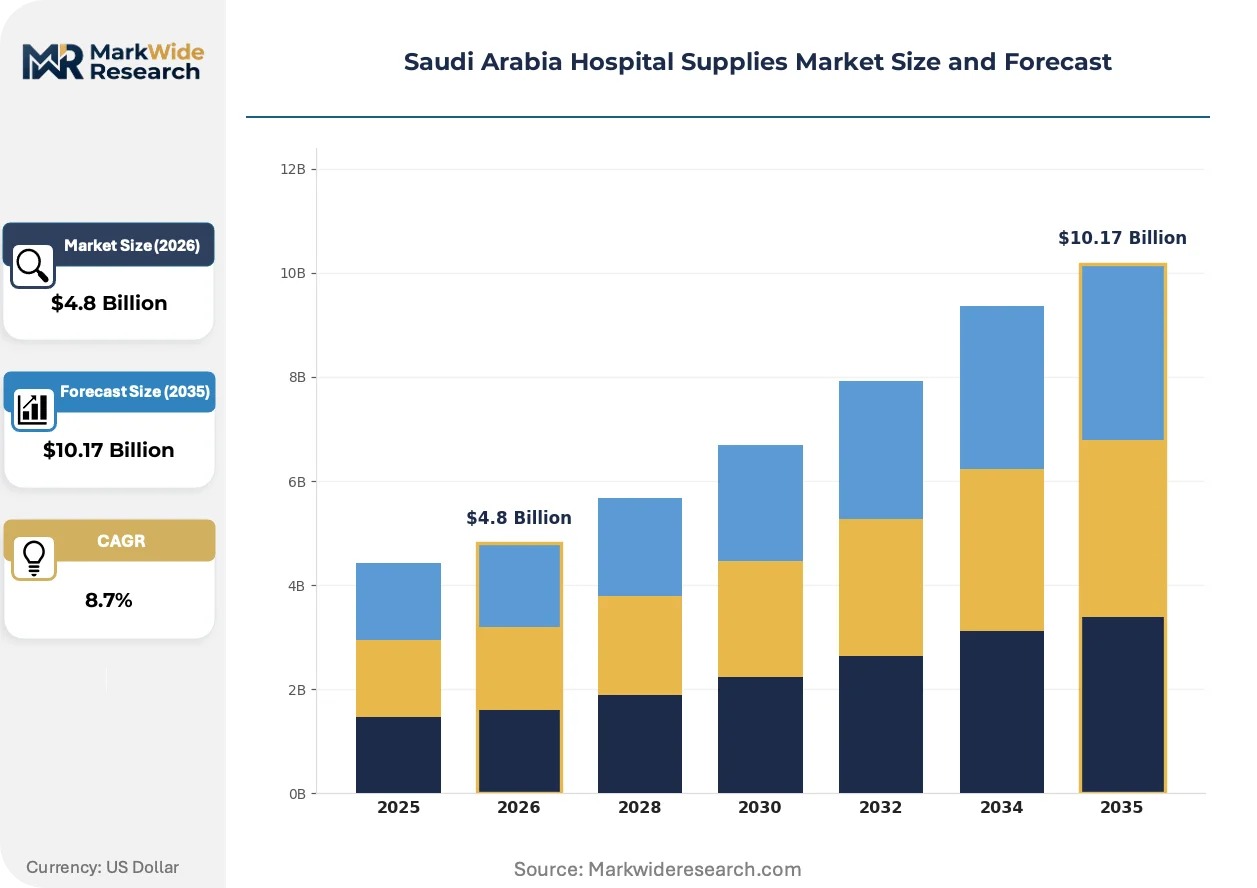
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Supplies, Surgical Instruments, Diagnostic Equipment, Diagnostics End User: Hospitals, Clinics, Diagnostic Centers, Specialty Care Facilities Application: Emergency Care, Surgical Procedures, Patient Monitoring, Rehabilitation Delivery Mode: Direct Sales, Online Distribution, Wholesale, Retail |
| Companies Covered | B. Braun Melsungen AG, Cardinal Health Inc, Becton Dickinson and Company, Smith & Nephew, Johnson & Johnson Inc, 3M Company, Stryker Corporation, Baxter International, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Hospital Supplies Market Evolving Landscape
Digital infrastructure investments are rewriting how Saudi hospital networks forecast demand, authenticate product provenance, and manage vendor relationships across geographically dispersed facilities.
Smart infusion pumps with embedded drug library databases are migrating from standalone devices to networked platforms integrated with electronic medical record systems. Tertiary care anesthesia departments in Riyadh are piloting wireless pump connectivity to reduce medication error incidents. This convergence is compressing service contracts toward software-subscription models that bundle hardware, updates, and clinical decision support.
SFDA post-market surveillance requirements now mandate unique device identification for Class II and III medical devices entering the Kingdom. Manufacturers must submit periodic safety reports and maintain complaint handling systems with local authorized representatives. High-risk implantable device suppliers face the steepest compliance burden, with several European orthopedic firms restructuring Saudi distribution partnerships to satisfy direct liability obligations.
Consolidated procurement through the Unified Procurement Company is compressing vendor access to individual hospital purchasing committees. Ministry of Health-affiliated facilities now route consumable orders through centralized tenders with standardized technical specifications. This channel concentration is most visible in the Central Region, where Riyadh-based procurement officers negotiate multi-year framework agreements that displace spot purchasing from traditional medical distributors.
Saudi Arabia Hospital Supplies Market Segmentation
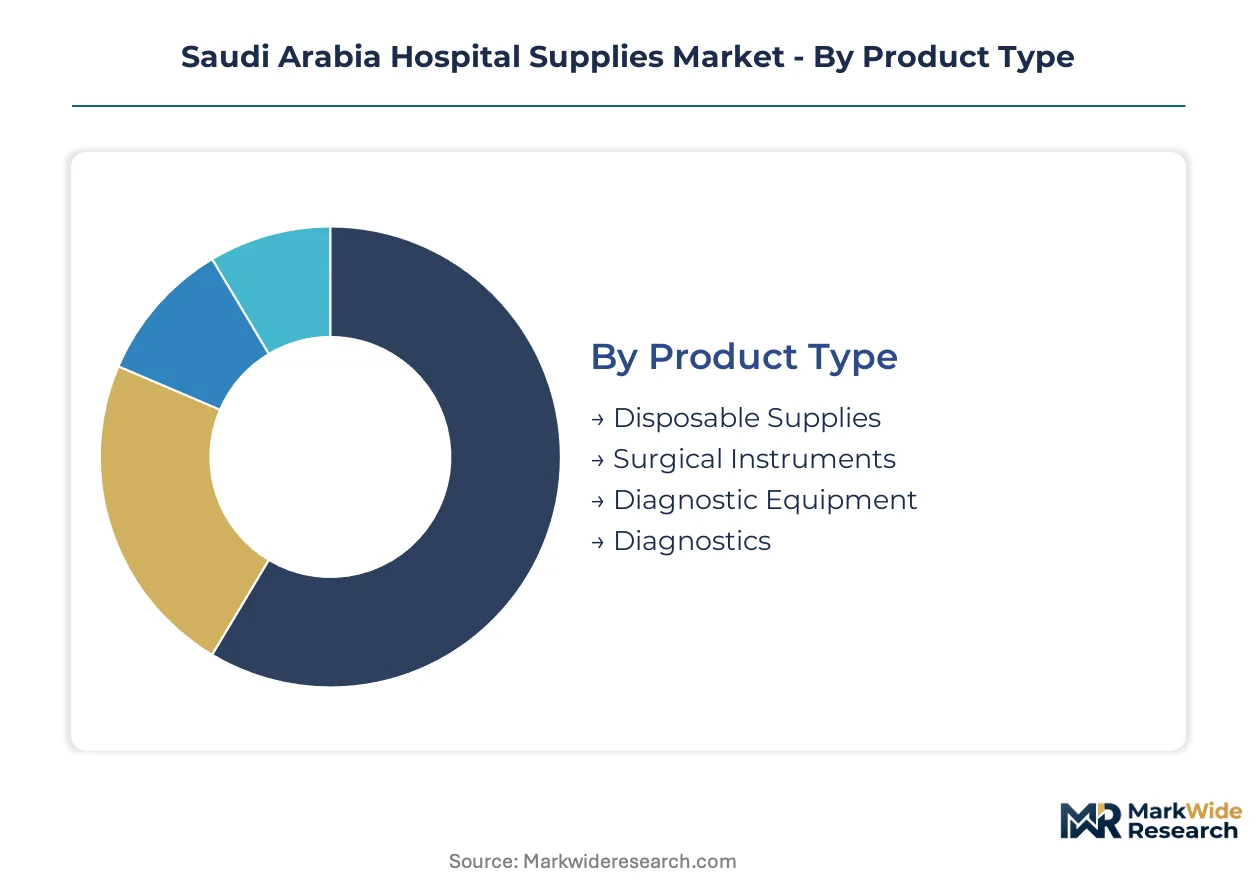
Hospital supplies in Saudi Arabia fragment across four distinct dimensions that determine procurement pathways and margin structures. Product type dictates manufacturing partnerships and SFDA registration complexity. End-user concentration shapes distribution economics, while application specificity drives technology selection and service bundling.
Product Type:
Cost tier separates commodity disposables from capital-intensive diagnostic platforms, with procurement authority concentrating differently across each stratum.
- Disposable Supplies:Single-use items manufactured from medical-grade polymers and non-woven fabrics dominate procurement volumes across Ministry of Health facilities. Riyadh tertiary centers generate recurrent demand for catheters, infusion sets, and wound dressings under centralized tender frameworks.
- Surgical Instruments:Reusable stainless steel and advanced alloy instruments command premium pricing contingent on sterilization validation and traceability compliance. Jeddah surgical hubs are consolidating reprocessing contracts with gamma sterilization providers to secure instrument turnover rates.
- Diagnostic Equipment:Imaging and laboratory automation systems capture capital budget allocations with extended depreciation schedules.
- Diagnostics:In-vitro testing consumables and point-of-care devices link recurring reagent revenue to installed base expansion.
Disposable Supplies hold installed capacity. Diagnostic Equipment is rotating up the share rankings.
End User:
Customer type determines contract structure, with public procurement centralization diverging sharply from private facility spot purchasing.
- Hospitals:Acute care facilities ranging from primary health centers to tertiary referral hospitals constitute the dominant demand channel. The Unified Procurement Company aggregates consumable volumes across Ministry of Health networks, compressing vendor margins in exchange for multi-year commitment security.
- Specialty Care Facilities:Rehabilitation centers and long-term care institutions are expanding fastest as Saudi Arabia privatizes select service lines. Dammam and Khobar private operators are licensing skilled nursing capacity, creating new demand channels for patient monitoring accessories and mobility aids.
- Clinics:Outpatient facilities purchase lower volumes with higher SKU fragmentation.
- Diagnostic Centers:Standalone imaging and laboratory operations concentrate equipment procurement decisions.
Hospitals anchor volume concentration. Specialty Care Facilities are climbing the fastest.
Application:
Clinical use case dictates performance specifications and regulatory scrutiny intensity across the SFDA classification framework.
- Surgical Procedures:Operating room consumables and instruments face the steepest quality benchmarks under Health Sector Transformation Program standardization mandates. Riyadh tertiary centers are piloting RFID-enabled instrument tracking to reduce retained foreign object incidents.
- Emergency Care:Resuscitation and trauma supplies require immediate availability with expiration date management protocols. Central Region ambulance services are consolidating pre-hospital supply kits through Ministry of Interior procurement channels.
- Patient Monitoring:Continuous vital signs acquisition devices integrate with electronic medical record platforms.
- Rehabilitation:Physical therapy equipment and assistive devices align with privatization incentives for post-acute services.
Surgical Procedures command specification authority. Emergency Care is gaining share fastest.
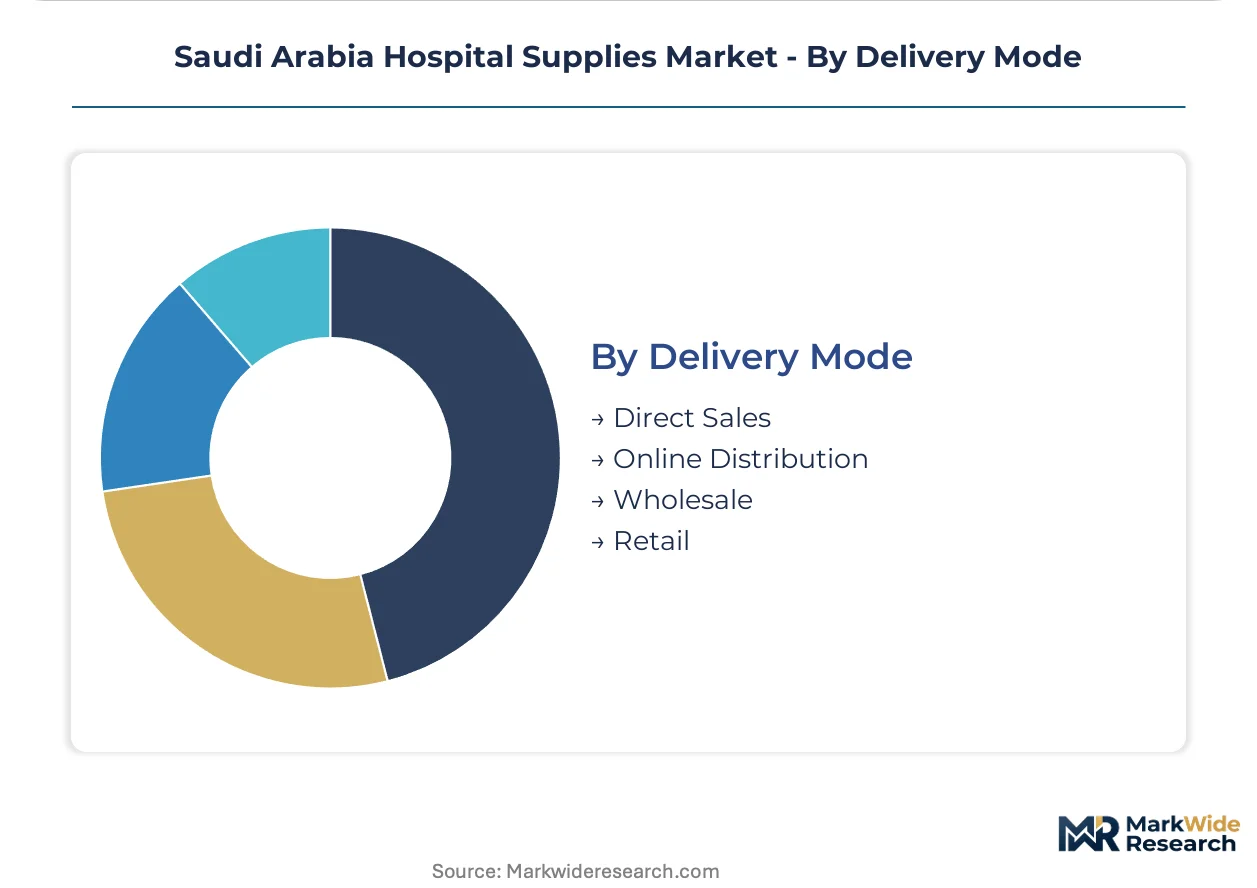
Delivery Mode:
Supply chain configuration determines vendor access to purchasing committees and working capital requirements.
- Direct Sales:Manufacturer-to-hospital contracts bypass distributor markups for high-volume consumable categories. Cardinal Health and B. Braun maintain dedicated Saudi sales organizations to service Ministry of Health framework agreements.
- Wholesale:Traditional medical distributors retain relevance for fragmented clinic and primary care procurement. Jeddah-based logistics hubs aggregate inventory for nationwide distribution to facilities outside Riyadh concentration zones.
- Online Distribution:E-procurement platforms are penetrating spot purchasing for non-critical supplies.
- Retail:Pharmacy and consumer channels serve limited home care and self-pay segments.
Direct Sales holds contract value. Online Distribution is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia imports the majority of its hospital supplies from European and American manufacturers, with domestic production concentrated in Jeddah industrial zones for sterilization services and basic consumables. The Kingdom's medical device trade deficit reflects limited polymer processing and precision instrument fabrication capacity.
Riyadh
Riyadh tertiary centers generate the highest surgical throughput in the Kingdom, driving concentrated demand for advanced catheter and infusion therapy products. The Ministry of Health's Unified Procurement Company centralizes all public hospital purchasing decisions from its Riyadh headquarters under Health Sector Transformation Program mandates. King Faisal Specialist Hospital and King Fahd Medical City anchor procurement volume for disposable supplies and diagnostic equipment.
Eastern Province
Dammam and Khobar hospital networks remain underpenetrated relative to Central Region facilities, creating first-mover opportunities for wound care and patient monitoring suppliers. Saudi Aramco's healthcare infrastructure and private hospital licensing reforms are expanding specialty care capacity across the province. The Dammam medical city cluster is consolidating supply chain operations to serve the growing population of expatriate workers in oil and petrochemical industries.
Western Region
Jeddah serves as the primary entry point for imported medical devices, hosting gamma and ethylene oxide sterilization facilities that process supplies for nationwide distribution. The city concentrates logistics infrastructure and local authorized representative offices for European and American manufacturers seeking SFDA marketing authorization. King Abdulaziz University Hospital and Jeddah National Hospital anchor demand for surgical instruments and diagnostic platforms.
NEOM Northwest
The NEOM giga-project is designing hospital infrastructure around predictive analytics and automated supply chain systems from initial construction phases. Healthcare facilities under development will deploy RFID-enabled inventory tracking and direct-to-department delivery models that bypass traditional distributor networks. This greenfield deployment offers vendors opportunities to establish reference sites for digital procurement technologies.
Saudi Arabia Hospital Supplies Market Competitive Landscape
On the supply side, the industry is consolidating around multinational manufacturers with established SFDA registration pathways and Ministry of Health framework contracts. Three strategic archetypes dominate: German precision instrument specialists with catheter and infusion therapy dominance, American diversified health conglomerates leveraging direct sales organizations, and orthopedic navigation tool providers aligned with SFDA implantable device standards. Competitive intensity centers on localization partnerships for preferential tender scoring and multi-year service contract bundling.
Within the multinational tier, B. Braun Melsungen AG, Cardinal Health Inc, and Stryker Corporation exemplify divergent positioning strategies. B. Braun Melsungen AG represents German manufacturing-based supply continuity for high-volume consumable categories. Cardinal Health Inc occupies a position anchored by dedicated Saudi sales organizations servicing public procurement channels. Stryker Corporation sits within the specialized surgical navigation segment where SFDA orthopedic standards create compliance barriers for smaller competitors.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Cardinal Health Inc |
| Becton Dickinson and Company |
| Smith & Nephew |
| Johnson & Johnson Inc |
| 3M Company |
| Stryker Corporation |
| Baxter International |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
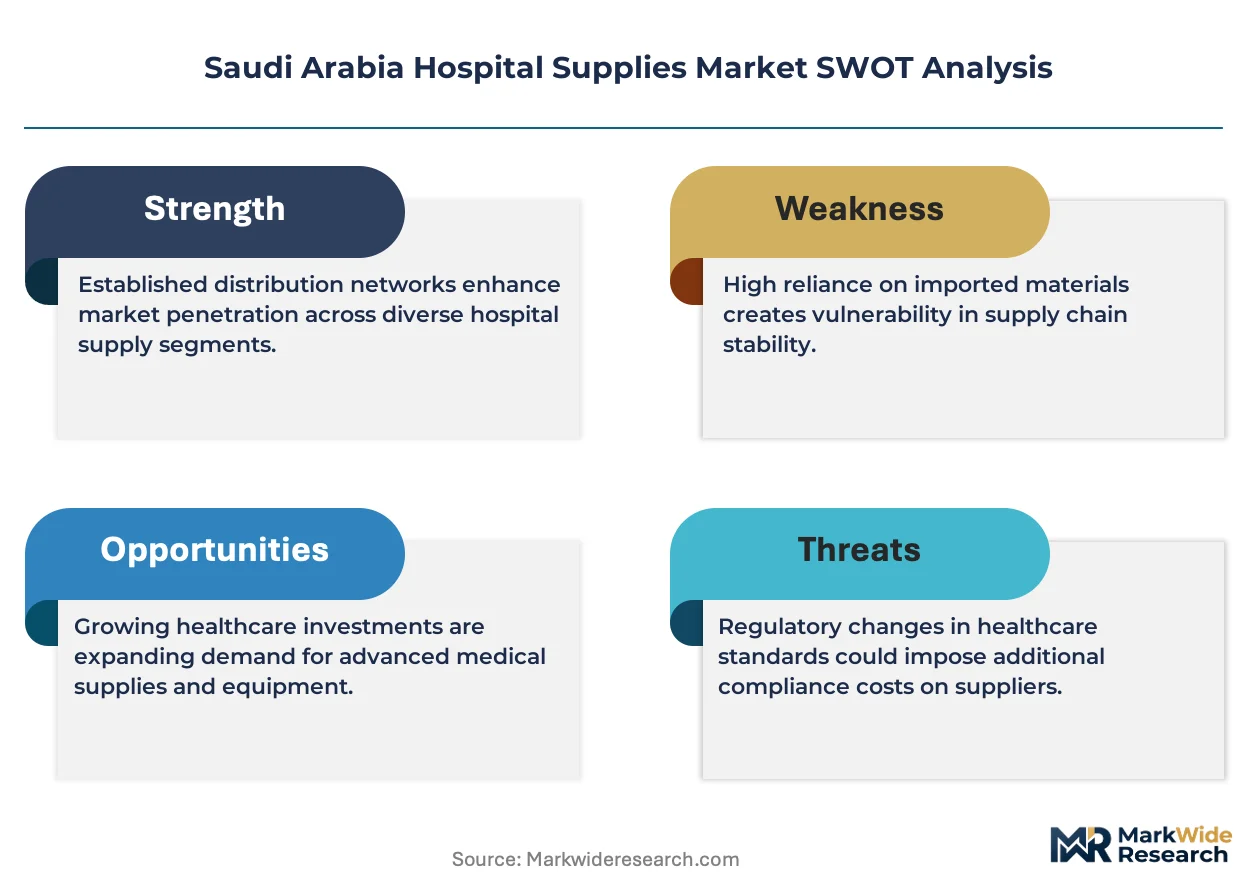
SFDA registration timeline extensions for foreign manufacturers lacking local authorized representatives compress margins across imported disposable categories while simultaneously forcing distributors to consolidate warehousing around Riyadh-centric logistics hubs. This regulatory chokepoint widens pricing spreads between established suppliers with in-country infrastructure and spot-market entrants dependent on Jeddah sterilization bottlenecks.
Pricing Analysis
Technology-generation pricing gaps separate RFID-enabled smart infusion platforms from conventional pump hardware and legacy standalone devices. Three-tier pricing structure across premium, standard, and economy levels reflects SFDA certification grade and after-sales service bundling rather than pure manufacturing cost. Pricing pressure stems from Ministry of Health framework agreement standardization that eliminates brand premiums for commodity catheter and wound care categories. Public hospital procurement committees exhibit highest price sensitivity, while NEOM greenfield facilities prioritize total-cost-of-ownership over per-unit acquisition cost.
Supply Chain Analysis
Upstream medical-grade polymer feedstock draws from Germany, the United States, and domestic petrochemical derivatives processed in Jubail industrial zones. Raw material dependencies center on polypropylene resin, PVC compounds, and stainless steel surgical alloys. Single-source sterilization capacity concentrates in Jeddah industrial zones, creating geographic vulnerability for nationwide distribution of gamma and ethylene oxide processed supplies. Distribution runs through manufacturer-direct sales organizations for high-volume consumables, with wholesale distributors retaining relevance for fragmented clinic procurement outside Riyadh concentration zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi hospital supply procurement is transitioning toward platform-economy dynamics where RFID-enabled inventory systems and unified procurement databases reshape vendor access and contract structures. Interoperability between electronic medical record platforms and supply chain management systems is compressing service models toward subscription-based recurring revenue.
For Market Incumbents: Pre-empt displacement by emerging regional manufacturers through backward integration into Jeddah sterilization capacity and accelerated SFDA localization partnership formation. Anchor multi-year framework agreements with Ministry of Health before procurement centralization eliminates spot purchasing channels. Defensive consolidation around predictive analytics service bundling counters software-native entrants threatening hardware commoditization.
For New Entrants and Emerging Players: Eastern Province hospital networks in Dammam and Khobar represent the most penetrable entry point given underdeveloped distributor infrastructure and expanding Saudi Aramco healthcare facilities. Specialty care privatization channels for rehabilitation and long-term care create alternative pathways bypassing Unified Procurement Company concentration. Go-to-market execution through direct biomedical engineering engagement rather than traditional distributor relationships accelerates credentialing with hospital supply chain departments.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with established SFDA registration pathways and Riyadh logistics presence. Acquisition targets should demonstrate existing Ministry of Health framework contract participation or sterilization facility ownership. Monitor Health Sector Transformation Program procurement reform announcements as inflection indicators for channel access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Localization Partnership | Domestic manufacturing presence qualifies vendors for preferential Ministry of Health tender scoring under emerging procurement rules. |
| RFID Inventory Platform Integration | Real-time supply tracking contracts with Riyadh tertiary centers secure multi-year consumable commitments and displace spot purchasing. |
| Eastern Province Distribution Expansion | Dammam and Khobar logistics infrastructure captures underpenetrated demand from oil sector healthcare facilities. |
| Long-Term Care Channel Development | Rehabilitation and skilled nursing privatization creates new revenue streams outside centralized hospital procurement. |
| Sterilization Capacity Acquisition | Jeddah gamma and ethylene oxide facility ownership eliminates geographic bottlenecks and secures nationwide distribution reach. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and SFDA regulatory affairs consultants converged on the working assumptions underpinning this analysis. Primary field engagement with supply chain executives at Ministry of Health-affiliated facilities combined with secondary validation against hospital procurement databases, GPO contract repositories, and SFDA marketing authorization filings. Bottom-up demand modeling across product categories triangulated with top-down macroeconomic indicators to establish volume and value estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling incorporating product type, end-user channel, clinical application, and delivery mode dimensions. CAGRs were derived from fitted growth curves calibrated to historical procurement volumes and policy implementation timelines. Forecast inputs included Health Sector Transformation Program procurement reform schedules, SFDA localization incentive weightings, and tertiary care capacity expansion pipelines.
Practitioners should monitor SFDA regulatory amendment announcements, polymer feedstock export quota adjustments, and Unified Procurement Company tender specification changes for early signals requiring forecast revision. Cross-checking against Ministry of Health budget appropriation disclosures and hospital construction pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Foley Trays Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Sterilization Wrap Market