
 Port Access Needles Market | 2026-2036
Port Access Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Port Access Needles Market Analytics
ISO 80369-7 compliance tier is collapsing the gap between premium safety-engineered and standard port access needles, forcing manufacturers to requalify entire product lines. Becton Dickinson leverages its integrated manufacturing scale to sustain cost leadership across safety needle platforms. ICU Medical anchors its position through proprietary needleless connector ecosystems that lock in hospital system loyalty. B. Braun differentiates via European regulatory pre-certification that accelerates site approvals in German and French oncology networks.
Port access needles are hollow, beveled-tip instruments designed for percutaneous entry into implanted vascular ports, typically manufactured from 304-grade stainless steel with 19-21 gauge lumens and non-coring Huber tips to preserve septum integrity during repeated access. Single lumen configurations dominate current hospital purchasing due to standardized chemotherapy protocols, while safety needle segments capture expanding margin pools as OSHA-compliant sharps protection becomes non-negotiable in US acute care settings. Home healthcare application growth reflects structural migration of long-term infusion therapy from inpatient to ambulatory environments.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape US product development timelines, while EMA MDR Class IIa reclassification in Europe extends conformity assessment durations for non-EU manufacturers. ISO 7864 and ISO 9626 dimensional specifications govern global interchangeability, creating compliance barriers for regional suppliers lacking metrology infrastructure. Stakeholders must monitor whether emerging state-level sharps injury databases in California and Massachusetts trigger procurement specification changes ahead of federal rulemaking.
Market Dynamics
OSHA Bloodborne Pathogens Standard enforcement is compressing replacement cycles for non-safety port access devices across US acute care networks, forcing rapid portfolio transitions before federal compliance deadlines.
Growth Catalysts
- OSHA needlestick prevention mandates:US hospital systems face escalating penalties for sharps injuries, accelerating bulk procurement of safety-engineered Huber needles with integrated shield mechanisms.
- Ambulatory oncology expansion:Freestanding infusion centers in Texas, Florida, and California are multiplying treatment chair counts, driving recurring needle consumption for port maintenance protocols.
- ISO 80369-7 harmonization:Global dimensional standardization is reducing SKU complexity for manufacturers, enabling cross-border production scale without regional retooling.
Market Restraints
- 304-grade stainless steel price volatility:Nickel and chromium input costs swing with London Metal Exchange futures, squeezing margin on safety needle platforms with complex shield assemblies.
- EMA MDR Class IIa reclassification:European conformity assessment durations have doubled for non-EU manufacturers, freezing market entry timelines for mid-tier Asian suppliers.
- Needleless connector substitution:ICU Medical and Becton Dickinson proprietary ecosystems are capturing port access occasions that previously required steel puncture, eroding addressable volume in long-term implant patients.
Strategic Opportunities
- Home healthcare channel development:Medicare reimbursement shifts toward ambulatory infusion are creating demand for patient-administered port access training and simplified safety needle designs.
- German and French oncology network pre-certification:B. Braun's regulatory positioning demonstrates pathway value for competitors seeking accelerated site approval in Europe's largest chemotherapy markets.
- State-level sharps injury database expansion:California and Massachusetts mandatory reporting systems are generating procurement specification changes ahead of anticipated federal rulemaking, rewarding early compliance investment.
Industry Challenges
- ISO 7864 and ISO 9626 metrology infrastructure:Regional suppliers lacking precision dimensional verification capabilities face exclusion from hospital system tenders requiring documented interchangeability certification.
- Legacy port inventory integration:Implanted vascular access devices with non-standard septum depths require needle length customization, fragmenting production runs and complicating automated assembly line economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Access Needles Market |
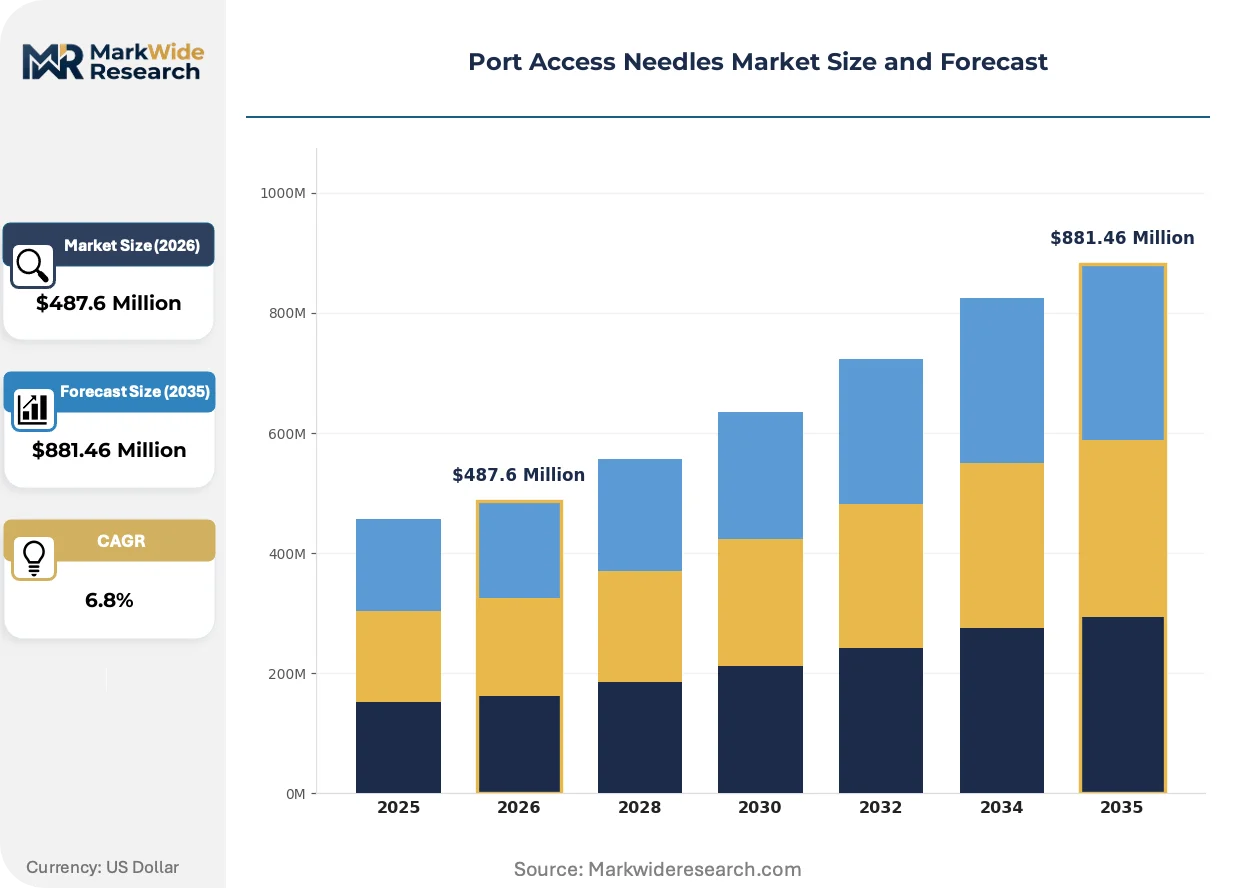
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lumen, Double Lumen, Triple Lumen, Safety Needles Application: Oncology, Pediatrics, Dialysis, Surgery End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Material: Stainless Steel, Plastic, Coated, Others |
| Companies Covered | Becton Dickinson, ICU Medical, B. Braun, Teleflex, AngioDynamics, Medical Components, Terumo Corporation, Medtronic, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Access Needles Market Evolving Landscape
Active needle tip engineering and connector ecosystem lock-in are reshaping competitive differentiation, with regulatory compliance timelines now determining product development roadmaps more than clinical performance metrics alone.
Passive safety Huber needle designs with automatic shield deployment upon needle withdrawal are displacing manual-activation alternatives in US hospital purchasing. Oncology infusion centers in metropolitan Texas and California systems are specifying these devices exclusively in 2024 tenders. The technology is displacing standard non-safety needles from premium tier procurement, compressing residual demand to price-sensitive home health segments where OSHA enforcement remains fragmented.
EMA MDR Class IIa reclassification for vascular access devices has extended technical documentation requirements and notified body queue times for European market entry. Manufacturers now face 18-24 month conformity assessment cycles versus 6-9 months under prior directives. German oncology networks are responding by consolidating supplier lists to pre-certified incumbents, accelerating B. Braun and Becton Dickinson share concentration in Western Europe.
Hospital system procurement offices are unbundling needle purchases from broader infusion therapy contracts, creating standalone competitive bidding events for port access devices. Group purchasing organizations are losing exclusive supplier arrangements as IDN-level sourcing committees assert direct vendor relationships. This pattern is most visible in southeastern US health systems where HCA and Tenet facility clusters are negotiating safety needle pricing independently of national GPO frameworks.
Port Access Needles Market Segmentation
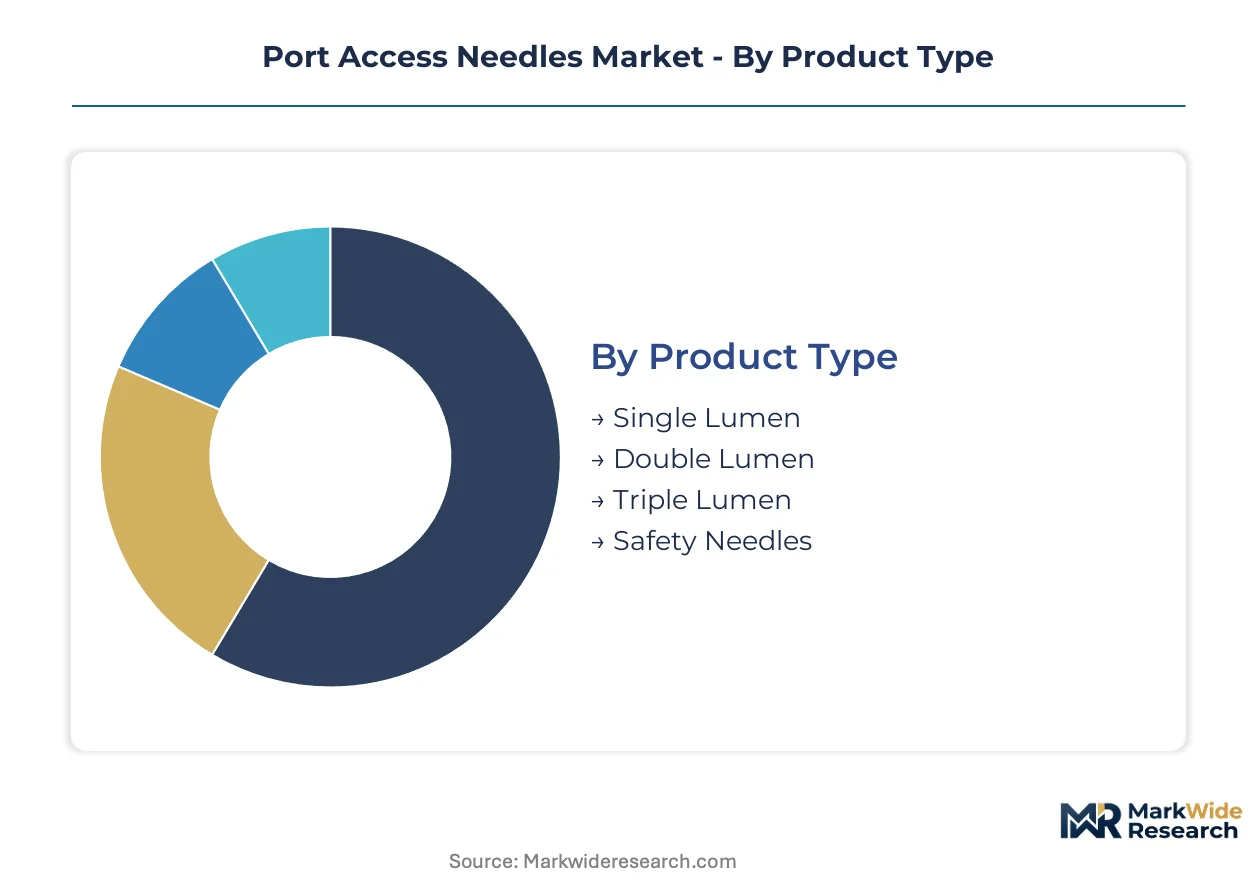
Port access needle procurement divides sharply between standardized acute care configurations and emerging ambulatory formats. FDA needlestick prevention mandates and ISO 80369-7 compliance tiers are collapsing legacy segment boundaries, forcing manufacturers to requalify entire product lines across multiple categories simultaneously.
Product Type:
OSHA Bloodborne Pathogens Standard enforcement and ISO 7864 dimensional specifications differentiate segments by shield complexity and interchangeability certification requirements.
- Safety Needles:Integrated shield mechanisms deploy automatically upon withdrawal, satisfying OSHA-compliant sharps protection mandates in US acute care networks. Texas and California oncology infusion centers specify these devices exclusively in current procurement tenders, compressing residual demand for non-safety alternatives.
- Single Lumen:19-21 gauge 304-grade stainless steel configurations with non-coring Huber tips dominate standardized chemotherapy protocols. Hospital purchasing concentrates here due to protocol uniformity, though margin pools erode as safety-engineered platforms capture premium tier positioning.
- Double Lumen:Parallel channel designs enable simultaneous infusion and blood draw, finding application in complex oncology regimens requiring concurrent medication delivery.
- Triple Lumen:Multi-channel architectures serve specialized surgical and intensive care applications where simultaneous access for incompatible solutions proves clinically necessary.
Established volume favors Single Lumen; emerging adoption favors Safety Needles.
Application:
Patient population acuity and treatment duration determine needle specification complexity across clinical settings.
- Oncology:Repeated port access for chemotherapy administration drives consumption volume, with ambulatory infusion center expansion in Florida and Texas multiplying treatment chair counts and associated needle demand.
- Dialysis:Long-term vascular access maintenance requires specialized Huber tip geometries to preserve septum integrity across extended implant lifecycles.
- Pediatrics:Smaller gauge requirements and modified insertion angles address anatomical constraints in neonatal and adolescent patient populations.
- Surgery:Perioperative fluid management and emergency access protocols utilize standard configurations with emphasis on rapid deployment reliability.
Clinical volume concentrates in Oncology; steepest expansion trajectory appears in Dialysis as home-based renal therapy migration accelerates.
End User:
Procurement authority centralization and reimbursement pathway structure segment demand by channel economics.
- Hospitals:IDN-level sourcing committees in southeastern US systems negotiate safety needle pricing independently of national GPO frameworks, fragmenting traditional supplier arrangements.
- Home Healthcare:Medicare reimbursement shifts toward ambulatory infusion create demand for patient-administered port access training and simplified safety designs.
- Clinics:Freestanding infusion centers operate under distinct OSHA enforcement profiles, enabling continued non-safety needle utilization in select jurisdictions.
- Long-term Care Facilities:Extended stay populations with implanted ports require maintenance access protocols distinct from acute care replacement cycles.
Procurement concentration favors Hospitals; channel development investment favors Home Healthcare.
Material:
Raw material cost volatility and biocompatibility certification requirements stratify manufacturing economics.
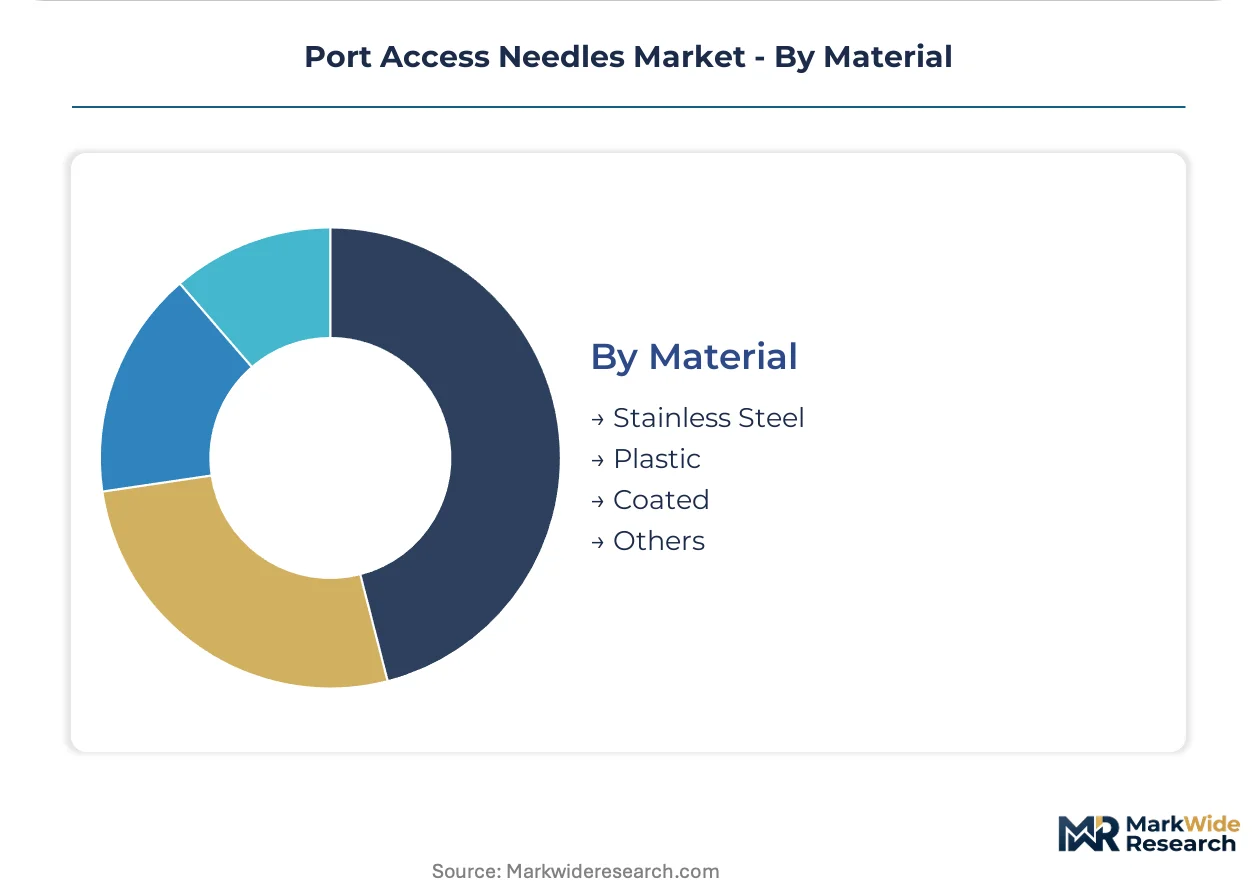
- Stainless Steel:304-grade compositions with nickel and chromium alloying dominate safety needle platforms, though London Metal Exchange futures volatility squeezes margin on complex shield assemblies.
- Coated:Surface modification technologies enhance lubricity and reduce insertion force, commanding premium positioning in pediatric and sensitive patient applications.
- Plastic:Polymer-based alternatives address cost-sensitive segments where metallic puncture resistance requirements relax.
- Others:Specialty alloys and composite formulations serve niche applications requiring magnetic resonance compatibility or specific chemical resistance profiles.
Manufacturing scale favors Stainless Steel; technology differentiation favors Coated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial export surplus in safety-engineered port access devices, while Germany and Japan supply precision-manufactured components to Asian assembly operations. Import dependency concentrates in nickel-alloy raw materials sourced from Australian and Indonesian mining operations.
United States
Texas and Florida oncology infusion center expansion drives recurring needle consumption for port maintenance protocols. OSHA Bloodborne Pathogens Standard enforcement accelerates bulk procurement of safety-engineered Huber needles with integrated shield mechanisms. Metropolitan hospital systems in California negotiate safety needle pricing independently of national GPO frameworks.
Germany
EMA MDR Class IIa reclassification extends conformity assessment durations for vascular access devices entering European markets. German oncology networks consolidate supplier lists to pre-certified incumbents, accelerating share concentration among established safety needle platforms. Bavarian and North Rhine-Westphalia medical device clusters specialize in precision Huber tip manufacturing for export markets.
Japan
PMDA regulatory pathways emphasize biocompatibility certification for long-term implantable device accessories. Japanese stainless steel fabricators supply 304-grade needle stock to regional safety device assemblers. The Kanto region around Tokyo hosts specialized metrology infrastructure for ISO 7864 dimensional verification.
China
NMPA medical device registration reforms streamline domestic market entry for locally manufactured port access needles. Yangtze River Delta production clusters scale automated assembly of standard non-safety configurations for cost-sensitive export markets. Shanghai-based distributors increasingly serve Southeast Asian hospital procurement networks.
India
CDSCO medical device rules classify port access needles under regulated import categories, creating compliance barriers for non-domestic manufacturers. Maharashtra and Gujarat specialty steel processors develop nickel-chromium alloy capabilities to reduce raw material import dependency. Chennai and Hyderabad hospital systems expand ambulatory oncology capacity, driving localized safety needle demand.
Port Access Needles Market Competitive Landscape
Concentration sits with integrated medical device conglomerates possessing captive manufacturing scale and regulatory pre-certification across multiple jurisdictions. The vendor base stratifies between safety-engineered platform specialists and standard configuration commodity suppliers. Three archetypes dominate: diversified infusion therapy conglomerates with needleless connector ecosystems, precision metal-forming specialists with ISO-certified metrology infrastructure, and regional fabricators serving price-sensitive home health segments. Competitive moves center on European MDR pre-certification acceleration and unbundled procurement negotiations with IDN-level sourcing committees.
Among diversified infusion therapy conglomerates, Becton Dickinson and ICU Medical exemplify platform-level competition through integrated safety needle and connector ecosystem offerings. B. Braun occupies a position within the European regulatory pre-certification tier, leveraging accelerated site approval pathways in German and French oncology networks. These three anchors represent distinct strategic positions: manufacturing scale leadership, proprietary ecosystem lock-in, and regulatory compliance acceleration respectively.
| Leading Market Players |
|---|
| Becton Dickinson |
| ICU Medical |
| B. Braun |
| Teleflex |
| AngioDynamics |
| Medical Components |
| Terumo Corporation |
| Medtronic |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
ISO 80369-7 compliance certification gates both supplier qualification and price tiering simultaneously, forcing manufacturers to absorb dimensional verification costs that separate premium safety-engineered platforms from commodity alternatives. Hospital procurement committees leverage this regulatory barrier to justify three-tier pricing stratification across premium, standard, and economy levels, with OSHA-mandated shield mechanisms commanding sustained margin premiums.
Pricing Analysis
Industrial OEM buyers anchor pricing structures around contract-based long-term offtake agreements with volume-scaled discounts. Price differentiation rests on ISO 7864 dimensional certification tier and integrated shield complexity, with safety-engineered platforms capturing premium positioning. Cost compression in standard non-safety configurations is intensifying because Asian fabricators scale automated assembly for export markets. Home healthcare distributors exhibit highest price sensitivity due to fragmented OSHA enforcement, while IDN-level hospital systems show lowest sensitivity given regulatory liability exposure.
Supply Chain Analysis
Inventory cycles for 304-grade stainless steel needle stock have lengthened as nickel-chromium alloy sourcing faces commodity volatility. Manufacturing concentrates in the United States, Germany, and China, with Yangtze River Delta clusters feeding cost-sensitive export demand. Raw material dependencies center on Australian and Indonesian nickel mining, Japanese precision metrology equipment, and German Huber tip forming technology. Single-source vulnerability concentrates in specialty steel processors capable of medical-grade certification. Distribution runs through hospital system IDN procurement committees, GPO frameworks, and direct-to-clinic channels for ambulatory infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision metrology infrastructure for ISO 7864 dimensional verification represents the critical asset gap separating qualified suppliers from market exclusion, concentrating viable manufacturing among firms with captive calibration capabilities.
For Market Incumbents: Shield market position through backward integration into 304-grade stainless steel processing to offset London Metal Exchange volatility, while accelerating EMA MDR Class IIa pre-certification to lock German and French oncology network supplier lists before conformity assessment queues extend further. Needleless connector substitution from ICU Medical and Becton Dickinson ecosystems poses the primary volume threat to steel puncture occasions. For New Entrants and Emerging Players: Lead with simplified safety needle designs targeting Medicare-reimbursed home healthcare channels where patient self-administration training creates white-space demand. California and Massachusetts state-level sharps injury database expansion offers the most penetrable regulatory entry point ahead of anticipated federal rulemaking. A direct-to-clinic distribution model bypasses consolidated GPO frameworks. For Investors and Strategic Acquirers: EMA MDR Class IIa reclassification reshapes the acquisition landscape by extending conformity assessment timelines and consolidating Western European supplier lists around pre-certified incumbents. Over the projection horizon, vertically integrated manufacturers with ISO-certified metrology infrastructure offer superior viability versus assembly-only operations. Monitor California and Massachusetts procurement specification changes as early indicators of federal OSHA rulemaking acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Class IIa Pre-Certification | Accelerates site approvals in German and French oncology networks ahead of competitor entry. |
| Backward Integration into Specialty Steel | Captive 304-grade stainless steel processing insulates margins from nickel price volatility. |
| Home Healthcare Channel Development | Medicare reimbursement shifts create patient-administered port access training demand. |
| ISO 80369-7 Product Line Requalification | Collapses gap between premium safety-engineered and standard configurations for unified sourcing. |
| IDN-Level Direct Procurement Negotiation | Southeastern US health system clusters bypass GPO frameworks for standalone safety needle contracts. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and oncology infusion center directors; and secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and ISO certification registries. Bottom-up and top-down triangulation cross-validated volume estimates against manufacturer capacity disclosures and regional import-export records.
Across the modeling period, forecasts segmented by product type, application, end user, material composition, and regional regulatory cluster generated volume and value outputs. CAGRs derived from replacement cycle analysis, ambulatory expansion trajectories, and compliance-driven upgrade patterns. Forecast inputs incorporated OSHA enforcement intensity indices, nickel futures volatility bands, and Medicare reimbursement pathway shifts.
The analysis sits within stated boundaries; outcomes outside sustained FDA needlestick prevention mandate enforcement or abrupt EMA MDR process acceleration would require recalibration. Forecasts reflect documented assumptions regarding ambulatory oncology center expansion rates and stainless steel input cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Crutch Pads Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market