
 Nasal Splints Market | 2026-2036
Nasal Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Splints Market Outlook
EU MDR sterilization and biocompatibility requirements are expanding the compliance burden for nasal splint manufacturers exporting into European markets. Medtronic leverages its vertically integrated sterilization infrastructure to sustain CE-marked product flows without third-party bottlenecks. Smith & Nephew anchors its competitive stance through specialized ENT channel relationships across Western Europe. Boston Medical Products Inc competes on manual fabrication expertise for custom anatomical fits in revision rhinology cases.
Nasal splints are mechanical or semi-rigid devices inserted post-operatively or post-trauma to maintain nasal patency, prevent synechiae formation, and stabilize septal positioning; bioabsorbable variants typically incorporate polylactic-glycolic acid copolymers that hydrolyze within 7–14 days, eliminating removal trauma. Silicone splints dominate current procedural volumes due to their cost-positioning and established reimbursement codes across hospital settings. 3D printed splints represent the fastest-growing technology segment, enabling patient-specific geometries derived from preoperative CT datasets that reduce revision rates. Injection molding occupies the mature, high-volume tier where margin pools have compressed amid polymer raw material volatility.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for nasal splint manufacturers. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 govern material selection and sterilization validation across all major jurisdictions. Stakeholders must monitor evolving ambulatory surgery center accreditation standards and polymer supply chain constraints as determinants of manufacturing location and pricing power.
Market Dynamics
Ambulatory surgical center accreditation standards are compressing device validation timelines while expanding the addressable base for single-use nasal splint formats.
Growth Catalysts
- EU MDR sterilization mandates:Technical documentation requirements for bioabsorbable polymers are accelerating manufacturer investment in automated quality systems.
- Outpatient rhinology migration:United States ambulatory surgery centers now handle septoplasty volumes previously reserved for hospital settings.
- CT-derived 3D printing:Preoperative imaging workflows are enabling patient-specific splint geometries that reduce revision procedural rates.
Market Restraints
- Polymer raw material volatility:Polylactic-glycolic acid copolymer feedstock costs fluctuate with agricultural commodity markets and biofuel policy shifts.
- Silicone supply concentration:Medical-grade silicone precursor production clusters in Northeast Asian chemical manufacturing corridors.
- Extended EU MDR transition timelines:CE marking recertification bottlenecks delay product launches for manufacturers without notified body pre-arrangements.
Strategic Opportunities
- Indian outpatient ENT expansion:CDSCO streamlined medical device registration pathways open private clinic channels previously dominated by hospital procurement.
- Bioresorbable-polymer antibiotic elution:Convergence of controlled-release pharmaceutical coatings with splint substrates addresses post-operative infection protocols.
- Direct-to-ambulatory distribution:Specialized ENT supply cooperatives bypass traditional hospital purchasing committees for same-day surgical kit fulfillment.
Industry Challenges
- ISO 10993-5 cytotoxicity testing capacity:Biocompatibility laboratory backlogs extend sterilization validation timelines for novel polymer formulations.
- Legacy ERP integration with track-and-trace:EU MDR unique device identifier requirements force mid-tier manufacturers into expensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Splints Market |
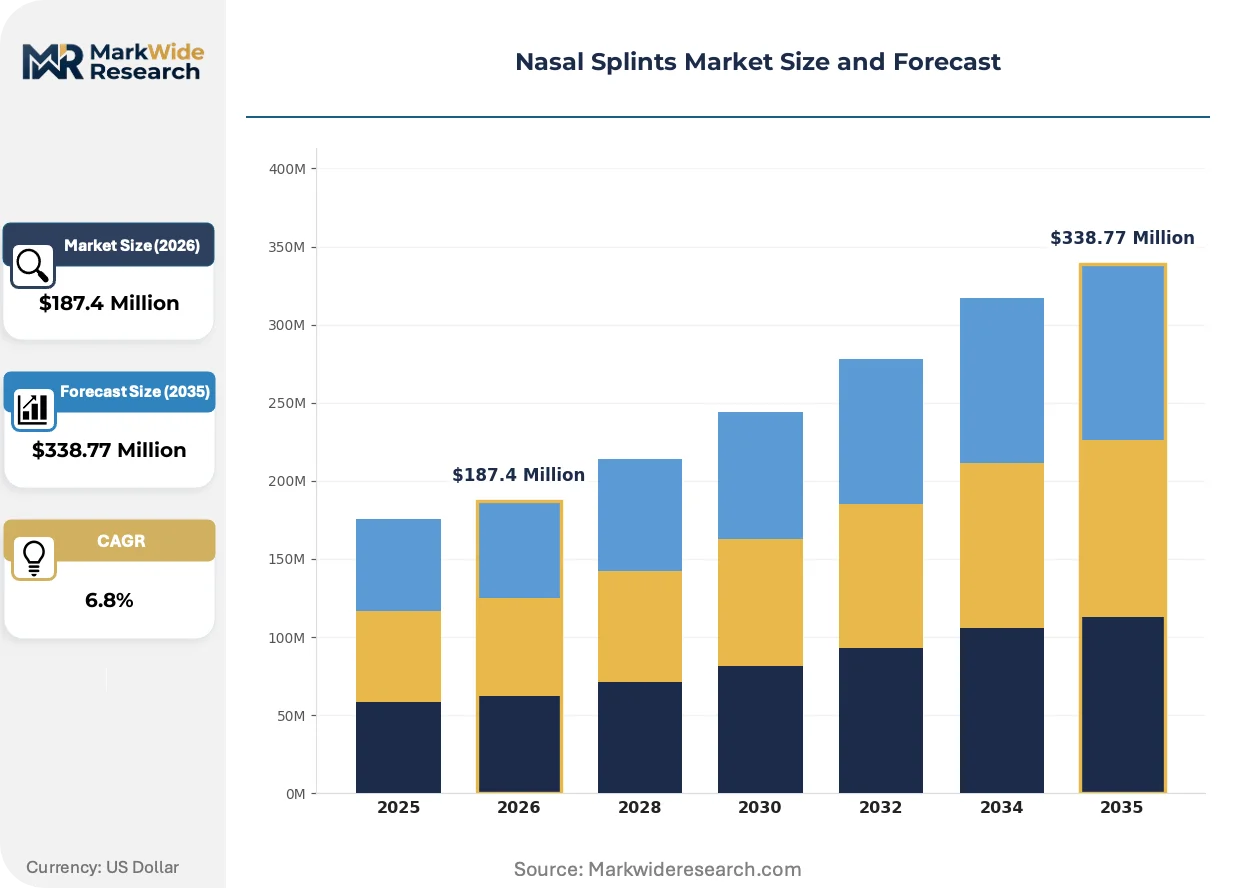
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioabsorbable Splints, Silicone Splints, Polymer Splints, Metal Splints End User: Hospitals, ENT Clinics, Home Care, Ambulatory Surgical Centers Technology: 3D Printed Splints, Extrusion Molding, Injection Molding, Manual Fabrication Application: Nasal Surgery, Trauma Care, Cosmetic Procedures, Sinus Surgery |
| Companies Covered | Medtronic, Olympus Corporation, Smith & Nephew, Stryker Corporation, Teleflex Incorporated, Boston Medical Products Inc, Surgiform Innovative Surgical Products, Anthony Products Inc., Audio Technologies SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Splints Market Strategic Shifts
Digital manufacturing workflows and regulatory data requirements are converging to reshape how nasal splint specifications are developed, validated, and distributed across care settings.
3D printed patient-specific splints derived from preoperative CT datasets are electrifying revision rhinology practice patterns. Academic medical centers with in-house additive manufacturing capabilities now produce custom geometries within 24-hour surgical windows. This capability is compressing demand for standardized silicone stock sizes in complex anatomical cases.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports with post-market surveillance data for all bioabsorbable device classes. Manufacturers without legacy product performance databases face disproportionate compliance burdens. Western European notified bodies are prioritizing submissions from firms with vertically integrated sterilization validation.
After-sales service unbundling is fragmenting traditional distributor relationships in United States ambulatory settings. ENT surgery centers now procure splints through specialized group purchasing organizations that negotiate direct manufacturer contracts. This channel shift is most visible in high-volume metropolitan markets where same-day turnover demands compress inventory holding periods.
Nasal Splints Market Segmentation
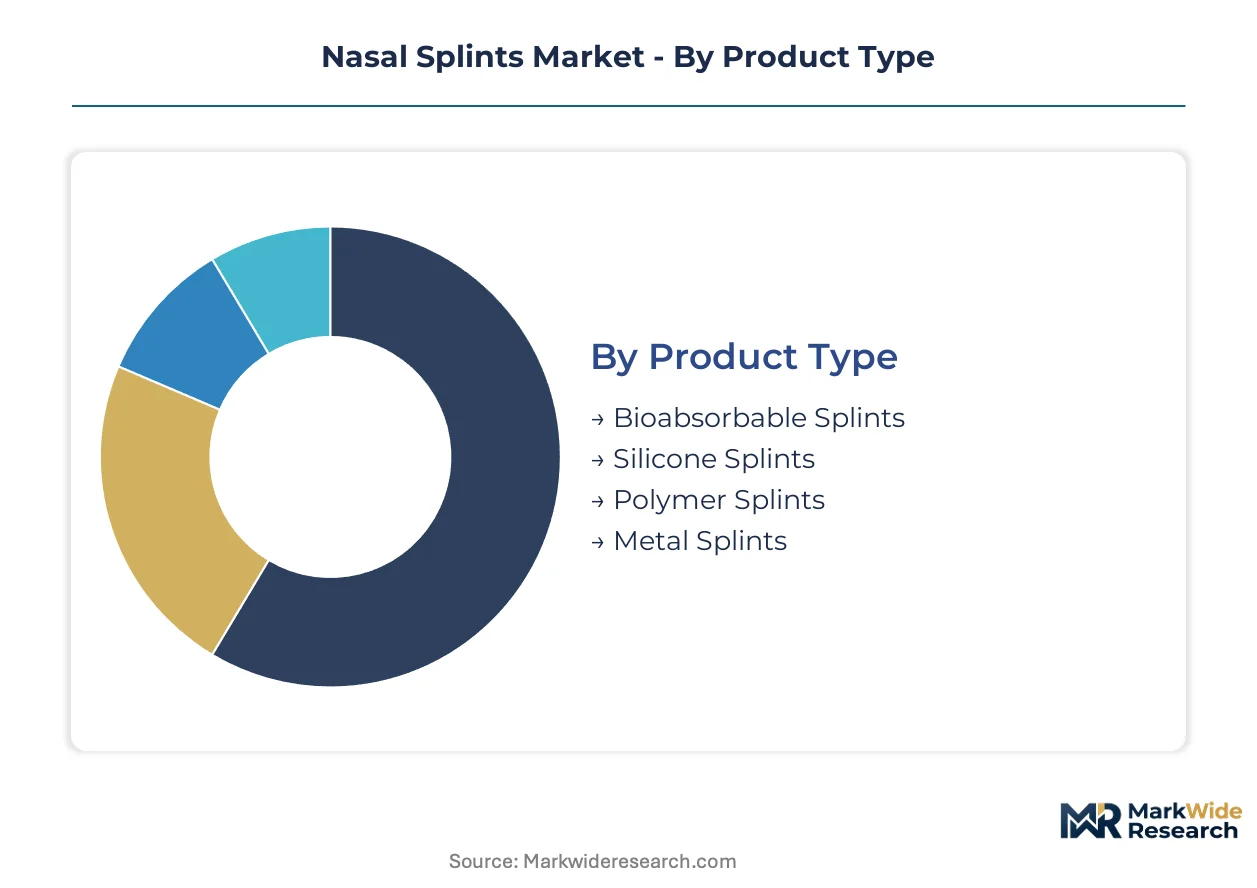
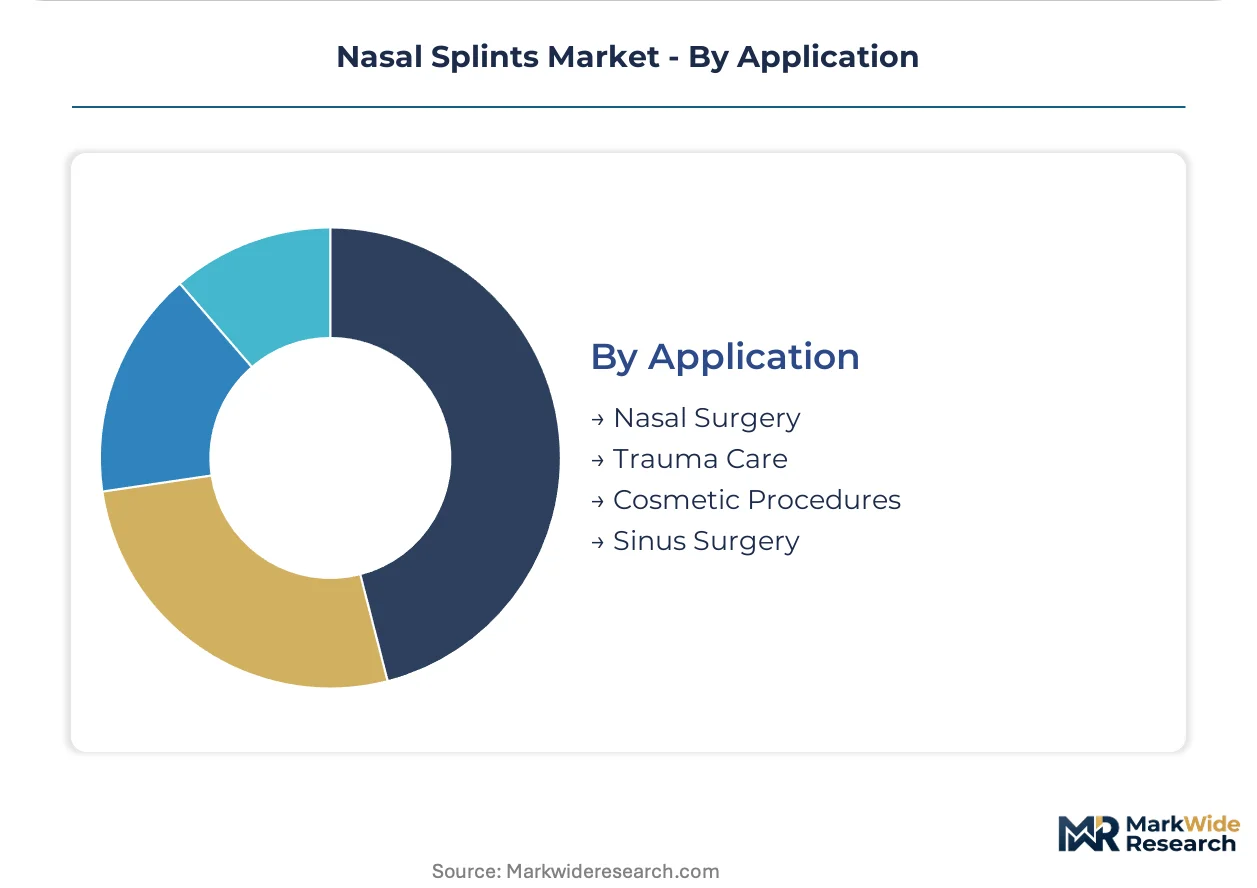
Segmentation in the nasal splints market reflects divergent clinical workflows across acute surgical settings and outpatient recovery pathways. Material selection, manufacturing precision, and reimbursement environment shape procurement decisions at each tier.
Product Type:
Material composition dictates removal protocols, infection risk profiles, and total cost of care across rhinology practice settings.
- Silicone Splints:Thermoset elastomer constructions withstand autoclave cycles and repeated sterilization in hospital central supply departments. United States ambulatory surgery centers procure silicone variants in highest volumes due to established CPT reimbursement codes and same-day discharge protocols.
- Bioabsorbable Splints:Polylactic-glycolic acid copolymers hydrolyze within 7–14 days post-insertion, eliminating secondary removal procedures. Academic medical centers in Germany and the United States are expanding bioabsorbable utilization where bundled payment models reward reduced follow-up visit frequency.
- Polymer Splints:Thermoplastic polyurethane and polyethylene terephthalate glycol formulations occupy mid-tier pricing positions in Asian outpatient markets.
- Metal Splints:Aluminum and titanium alloy constructs persist in maxillofacial trauma protocols requiring rigid external fixation.
Volume sits with silicone formats across hospital and ambulatory channels; growth tilts toward bioabsorbable platforms where reimbursement incentives align with reduced procedural touchpoints.
End User:
Site-of-care migration is fragmenting procurement authority and compressing inventory holding periods.
- Ambulatory Surgical Centers:Standalone ENT facilities in Texas, Florida, and California now handle septoplasty volumes previously routed to hospital operating suites. These centers demand single-use sterile packaging and just-in-time delivery cadences incompatible with traditional distributor warehousing models.
- Hospitals:Integrated delivery networks maintain bulk purchasing leverage through centralized materials management, favoring multi-procedure SKUs with cross-departmental utility.
- ENT Clinics:Office-based rhinology practices in India and Brazil are expanding splint utilization for minor trauma and post-cosmetic monitoring.
- Home Care:Post-operative nasal packing removal kits for sleep apnea and turbinate reduction patients are penetrating direct-to-consumer channels in markets with limited specialist access.
Procurement authority is dispersing from hospital supply chains toward ambulatory-specific purchasing cooperatives.
Technology:
Manufacturing modality determines geometric precision, lot-to-lot consistency, and regulatory documentation burden.
- 3D Printed Splints:Fused deposition modeling and selective laser sintering workflows convert DICOM datasets into patient-specific geometries with sub-millimeter anatomical fidelity. Cleveland Clinic and Mayo Clinic additive manufacturing labs now produce custom splints within 24-hour surgical windows for revision rhinology cases.
- Injection Molding:High-volume thermoplastic processing dominates standardized silicone splint production, though polymer feedstock volatility has compressed margin pools for mid-tier contract manufacturers.
- Extrusion Molding:Continuous profile manufacturing serves high-volume nasal stent applications with minimal geometric complexity.
- Manual Fabrication:Artisanal thermoforming persists in custom revision cases where CT-derived digital workflows remain unavailable.
Capacity concentrates in injection molding; capability differentiation is climbing the fastest in additive manufacturing segments serving academic referral centers.
Application:
Procedure type dictates splint rigidity requirements, dwell time, and antibiotic elution specifications.
- Nasal Surgery:Septoplasty and rhinoplasty procedures require bilateral intranasal splinting to prevent synechiae formation and stabilize cartilaginous positioning. United States procedural volumes exceed European aggregates due to higher per-capita cosmetic surgery incidence.
- Trauma Care:Maxillofacial fracture reduction protocols demand rigid external nasal splinting combined with internal Doyle-type devices for complex nasal bone displacement.
- Sinus Surgery:Endoscopic sinus surgery adjuncts prioritize middle meatal spacing and frontal recess patency maintenance.
- Cosmetic Procedures:Post-rhinoplasty aesthetic monitoring drives demand for transparent silicone variants permitting visual inspection without device removal.
Utilization intensity peaks in functional nasal surgery; cosmetic application volumes are expanding most quickly in Gulf Cooperation Council private healthcare markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Northeast Asian chemical corridors while consumption concentrates in Western ambulatory surgery centers and emerging Asian ENT clinics. This divergence shapes logistics networks and regulatory compliance investments across supplier geographies.
United States
Texas, Florida, and California ambulatory surgery centers now handle septoplasty volumes previously routed to hospital operating suites. FDA 510(k) clearance pathways establish predictable market access timelines for silicone and bioabsorbable formats. The Cleveland Clinic additive manufacturing lab in Ohio produces patient-specific splints within 24-hour surgical windows for revision rhinology cases.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia are expanding bioabsorbable utilization where bundled payment models reward reduced follow-up visit frequency. EU MDR Article 10 technical documentation requirements mandate clinical evaluation reports with post-market surveillance data for all bioabsorbable device classes. Berlin-based notified bodies prioritize submissions from manufacturers with vertically integrated sterilization validation.
India
Maharashtra and Karnataka office-based ENT clinics are expanding splint utilization for minor trauma and post-cosmetic monitoring. CDSCO streamlined medical device registration pathways open private clinic channels previously dominated by hospital procurement. Mumbai and Bengaluru medical device distributors now stock single-use sterile packaging formats compatible with just-in-time delivery cadences.
China
Yangtze River Delta chemical manufacturing corridors concentrate medical-grade silicone precursor production. NMPA medical device registration requirements for imported nasal splints emphasize biocompatibility testing under GB/T 16886 standards. Shanghai and Suzhou contract manufacturers serve as export hubs for standardized thermoplastic splint formats bound for Southeast Asian markets.
United Arab Emirates
Dubai and Abu Dhabi private healthcare markets are expanding cosmetic rhinology volumes most quickly among Gulf Cooperation Council states. MOHAP medical device import licensing requires Arabic labeling and local authorized representative arrangements. Dubai Healthcare City clusters now demand transparent silicone variants permitting visual inspection without device removal for post-operative aesthetic monitoring.
Nasal Splints Market Competitive Environment
The competitive structure tilts toward diversified medtech conglomerates with captive sterilization infrastructure and specialized ENT channel relationships. Tier-one positions concentrate among firms with vertically integrated quality systems capable of sustaining CE-marked product flows through EU MDR transition bottlenecks. Three archetypes dominate: hospital-centric suppliers with central supply department contracts, ambulatory-focused specialists with same-day surgical kit fulfillment capabilities, and academic medical center partners with in-house additive manufacturing integration. Dominant competitive moves include backward integration into polymer feedstock sourcing and strategic partnerships with CT imaging workflow providers.
Among diversified medtech conglomerates, Medtronic and Stryker Corporation exemplify the hospital-centric archetype with established central supply department relationships. Smith & Nephew occupies a position within the specialized ENT channel tier, anchoring competitive stance through dedicated otolaryngology sales networks across Western Europe. Boston Medical Products Inc represents the artisanal fabrication segment, sitting within the custom anatomical fit niche for revision rhinology cases where standardized geometries prove inadequate.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| Smith & Nephew |
| Stryker Corporation |
| Teleflex Incorporated |
| Boston Medical Products Inc |
| Surgiform Innovative Surgical Products |
| Anthony Products Inc. |
| Audio Technologies SRL |
| Others |
Value Chain & Pricing Dynamics
Polymer chemist concentrations in the Yangtze River Delta and Gujarat chemical corridors create labor-cost differentials that spread three-tier pricing across premium bioabsorbable, standard silicone, and economy thermoplastic tiers.
Pricing Analysis
Cost-down pressure on mid-tier silicone splints accelerates because polymer feedstock volatility compresses contract manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared bioabsorbables from CE-marked silicone stock sizes from unbranded Asian thermoplastics. Price differentiation hinges on sterilization validation depth and notified body pedigree. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity; German academic medical centers show lowest sensitivity where bundled payments obscure unit costs.
Supply Chain Analysis
ISO 13485 certification gating concentrates viable supplier pools in China, Germany, and the United States where quality system audits are enforceable. Medical-grade silicone precursor production draws from Yangtze River Delta petrochemical corridors; polylactic-glycolic acid copolymer feedstock rests on agricultural commodity markets in the American Midwest and Brazilian soy belts. Single-source vulnerability persists in medical-grade silicone precursor supply. Distribution runs through specialized ENT supply cooperatives that bypass traditional hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization validation laboratory capacity constraints prop pricing power for manufacturers with in-house ethylene oxide infrastructure. This supply-constrained structure favors incumbents with captive compliance capabilities.
For Market Incumbents: Cement market position by securing exclusive contracts with ambulatory surgery center purchasing cooperatives in high-volume metropolitan corridors. Deepen backward integration into polymer feedstock sourcing to buffer agricultural commodity volatility. Prioritize EU MDR notified body pre-arrangements ahead of recertification bottlenecks. For New Entrants and Emerging Players: Capture white-space in Indian office-based ENT clinics where CDSCO streamlined registration opens private channels. Target Maharashtra and Karnataka metros with just-in-time sterile packaging formats. Pursue direct-to-clinic distribution partnerships bypassing traditional hospital procurement. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier manufacturers possessing vertically integrated sterilization infrastructure given EU MDR transition bottlenecks. Five-to-ten year viability favors firms with captive ethylene oxide validation and established notified body relationships. Monitor ambulatory surgery center accreditation expansion rates as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 technical documentation mandates clinical evaluation reports with post-market surveillance data. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic additive manufacturing labs integrate CT-derived splint workflows within 24-hour surgical windows. |
| Backward Integration | Captive polymer feedstock sourcing buffers PLGA copolymer cost volatility from agricultural commodity markets. |
| Software Companion Development | DICOM-to-print workflows enable patient-specific geometries that reduce revision rhinology procedural rates. |
| Reimbursement Strategy | Bundled payment models in German and United States academic centers reward bioabsorbable formats with reduced follow-up frequency. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers cross-referenced against FDA 510(k) clearances, EU MDR technical documentation, and CDSCO registration databases. Bottom-up procedure volume estimates triangulated with top-down manufacturer shipment data.
Segment-level modeling deployed product type, end user, technology, and application dimensions across the projection horizon. CAGRs derived from spline-interpolated growth rates applied to base-year volume estimates. Forecast inputs incorporated ambulatory surgery center accreditation expansion trajectories and polymer feedstock price indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR transition timeline extensions and notified body capacity constraints. Model assumptions reflect sterilization validation laboratory backlogs and polymer supply chain concentration risks. A model refresh is warranted upon material change in ambulatory surgery center procedural migration rates or notified body recertification bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Cryotubes Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Global Sterilization Container Systems Market