
 North America Healthcare Packaging Market | 2026-2036
North America Healthcare Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Packaging Market Intelligence
Project finance and equipment leasing for barrier-film production lines is narrowing the capital gap between established converters and mid-tier entrants. Amcor leverages its North American blown-film footprint to sustain supply security for sterile pharmaceutical pouches. West Pharmaceutical Services anchors demand through its dominance in elastomeric closure systems for injectable formats. Berry Global competes aggressively in multi-layer coextrusion capacity serving hospital and clinic end users.
Healthcare packaging encompasses materials and containers engineered to maintain sterility, chemical stability, and tamper evidence for pharmaceuticals, biologics, and medical devices, with specifications typically requiring oxygen transmission rates below 0.1 cc per square meter per day and compliance with USP Class VI biocompatibility testing. Rigid packaging formats lead in value contribution due to their dominance in glass vial and high-density polyethylene bottle applications for oral solid doses, while flexible pouches represent the fastest-expanding structural category as biologic manufacturers adopt multi-chamber bags for lyophilized drug reconstitution. Plastic materials sustain the largest volume share across bottles and blister lidding, though glass retains premium positioning in parenteral and ophthalmic segments where inertness and barrier performance command price premiums.
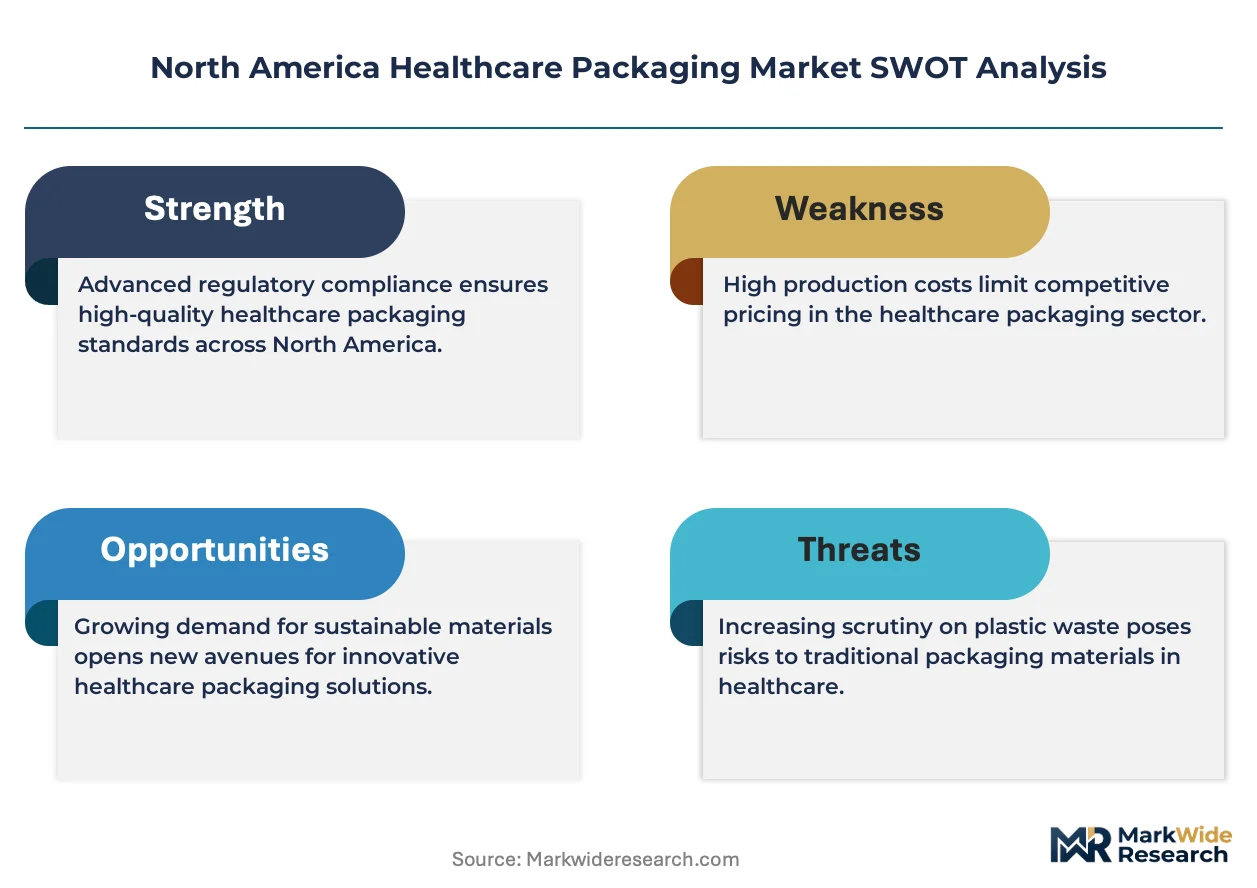
FDA enforcement of Drug Supply Chain Security Act serialization deadlines shapes demand for integrated label and track-and-trace solutions, while EPA regulations on per- and polyfluoroalkyl substances are forcing material transitions in barrier coatings. Health Canada and PMRA alignment with FDA packaging integrity standards facilitates cross-border supplier qualification, reducing duplicative testing burdens for converters serving both markets. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York, as these frameworks will determine whether recycling infrastructure investments or material substitution becomes the lower-risk compliance pathway.
Market Dynamics
FDA serialization mandates under the Drug Supply Chain Security Act are compressing qualification timelines for integrated smart-label infrastructure, forcing packagers to reconfigure production lines ahead of 2027 enforcement windows while biologic cold-chain requirements simultaneously expand barrier-film specifications.
Growth Catalysts
- Biologics cold-chain expansion:Temperature-sensitive therapies require multi-layer thermal packaging with validated stability profiles, pulling investment into qualified cold-chain infrastructure across specialty pharmacy networks.
- Drug Supply Chain Security Act:FDA track-and-trace deadlines compel pharmaceutical manufacturers to procure serialization-capable labels and aggregation hardware, creating dedicated demand for integrated packaging-IT systems.
- Hospital consolidation:Health system mergers in the United States are standardizing procurement specifications for high-barrier primary formats, concentrating volume with converters capable of multi-site supply contracts.
Market Restraints
- Fluoropolymer coating phase-out:EPA restrictions on per- and polyfluoroalkyl substances are forcing material transitions in oxygen-barrier films, raising qualification costs and compressing approved supplier lists.
- Blown-film capacity concentration:Sterile pharmaceutical pouch supply concentrates among established converters with validated cleanroom extrusion lines, limiting mid-tier entrants' access to hospital formulary approvals.
- Glass-to-plastic substitution limits:Parenteral and ophthalmic segments retain glass vial dominance where USP Class VI inertness requirements exclude polymer alternatives, constraining flexible format penetration in high-value injectables.
Strategic Opportunities
- Extended producer responsibility frameworks:California and New York state legislation on healthcare packaging recovery creates first-mover advantage for converters investing in mono-material recyclable barrier structures or certified recycling infrastructure.
- Multi-chamber lyophilized drug formats:Biologic manufacturers are adopting flexible pouches with separate diluent and powder chambers, opening flexible packaging penetration in reconstitution workflows historically served by glass vials.
- Health Canada-PMRA alignment:Harmonized packaging integrity standards with FDA reduce duplicative testing for converters serving cross-border supply chains, lowering qualification barriers for integrated North American production footprints.
Industry Challenges
- Serialization engineering talent scarcity:Integrated label-track-and-trace systems require specialists fluent in both pharmaceutical compliance and industrial automation, with qualified personnel concentrated among incumbent packagers.
- Legacy equipment retrofit timelines:Existing blister and bottle lines require substantial modification to accommodate aggregation hardware and vision systems, extending capital deployment cycles and delaying revenue recognition on qualified formats.
- Biocompatibility testing backlog:USP Class VI and ISO 10993 validation queues at certified laboratories are extending new material introduction timelines, compressing windows for PFAS-transition formulations to reach market before regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Packaging Market |
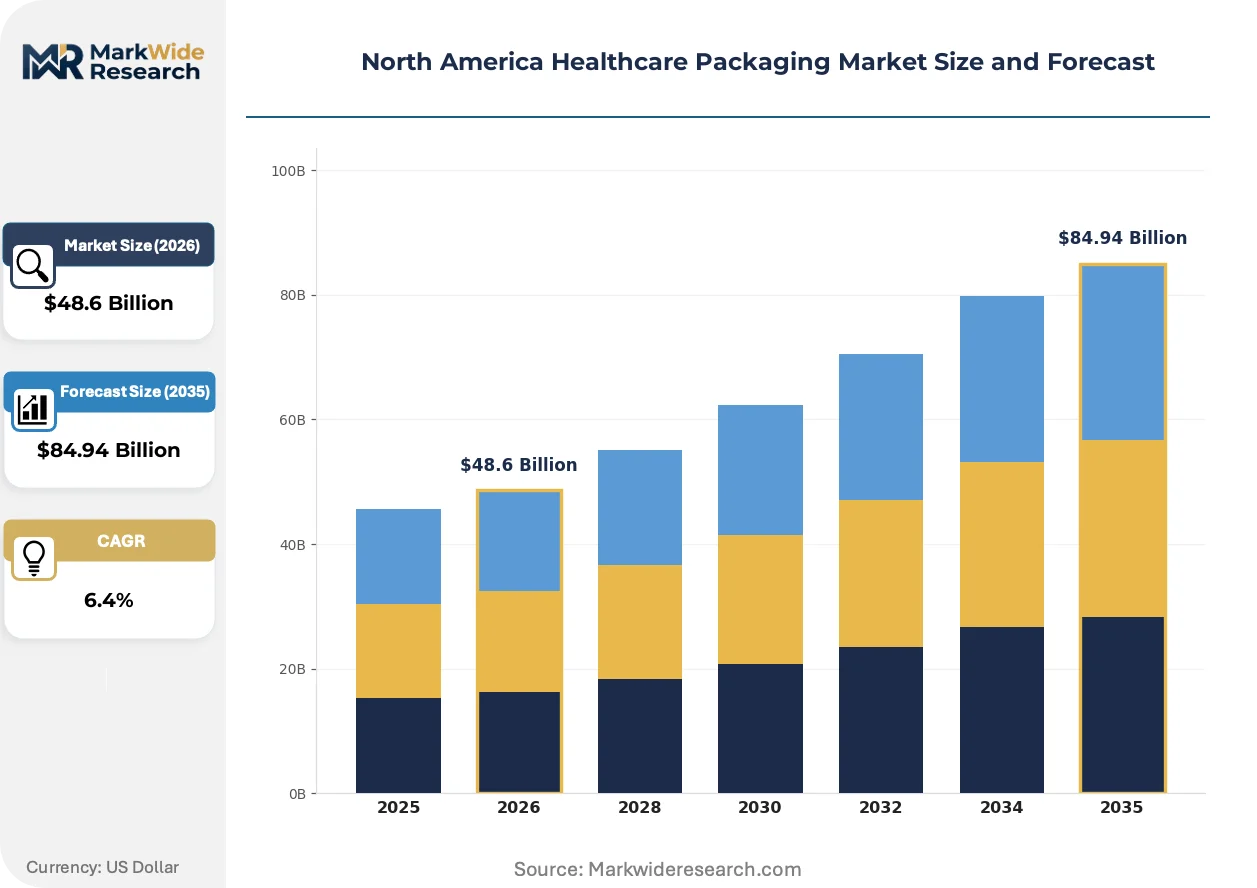
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Pouches, Labels Material: Plastic, Glass, Paper, Metal End User: Pharmacies, Hospitals, Clinics, Laboratories Packaging Type: Rigid, Semi-Rigid, Flexible, Shrink Wrap |
| Companies Covered | Amcor, West Pharmaceutical Services, Berry Global, Gerresheimer AG, Corning Incorporated, Nipro Corporation, SGD Pharma, WestRock, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Packaging Market Strategic Shifts & Innovations
Active packaging intelligence and material science convergence are redefining competitive capability requirements, with regulatory compliance automation and sustainability-driven material transitions now inseparable from core packaging value propositions.
Multi-layer coextrusion with embedded sensor films is hybridizing traditional barrier performance with real-time environmental monitoring. Biologic manufacturers adopting these formats for cold-chain distribution are compressing insurance and spoilage cost structures while enabling continuous temperature logging that satisfies FDA distribution documentation requirements. The technology is hybridizing quality assurance and packaging into unified compliance artifacts.
California's extended producer responsibility legislation and New York's pending packaging reduction mandates are accelerating mono-material recyclable barrier development. Converters are qualifying polyethylene-based oxygen barriers to replace fluoropolymer coatings before EPA enforcement windows tighten, with hospital systems beginning to specify recyclable formats in sustainability scorecards. Sterile pharmaceutical pouch suppliers serving West Coast health networks face the most compressed reformulation timelines.
Specialty pharmacy direct-to-patient distribution is consolidating procurement authority with centralized pharmacy benefit managers. Hospital discharge packaging and home-infusion formats are displacing traditional wholesale-dependent supply patterns, with patient-facing unit-dose designs replacing bulk institutional formats. United States-based specialty pharmacy networks are driving the most visible specification changes in tamper-evident and child-resistant closure systems.
North America Healthcare Packaging Market Segmentation
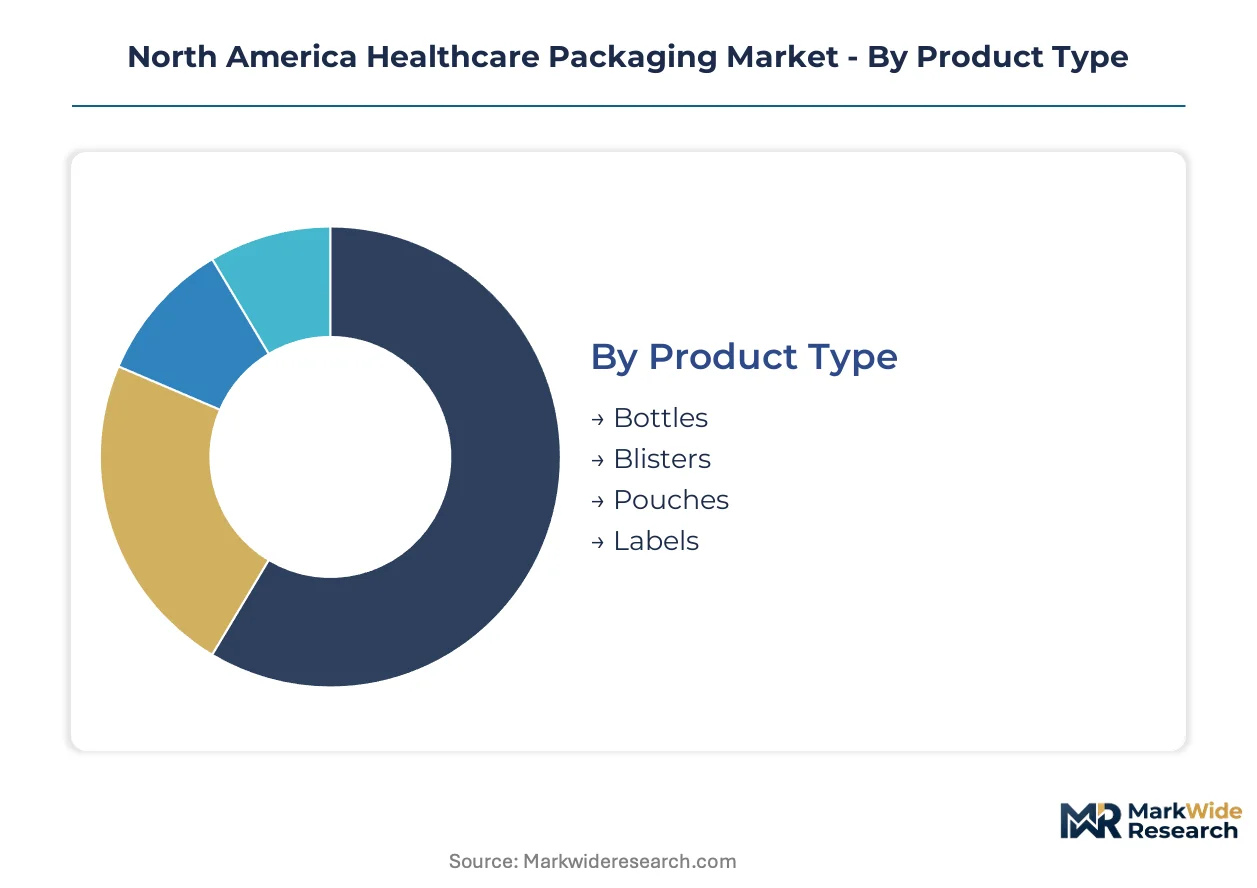
Healthcare packaging segmentation reveals how material specifications, regulatory pathways, and distribution channels fragment procurement authority across North American supply chains. Format selection directly determines barrier performance requirements and serialization infrastructure investments.
Product Type:
Application context determines format selection, with oral solid doses, injectable biologics, and diagnostic reagents each demanding distinct primary packaging architectures.
- Bottles:High-density polyethylene and polypropylene containers dominate oral solid dose dispensing across retail pharmacy networks. Hospital consolidation in the United States is standardizing child-resistant closure specifications, concentrating volume with converters capable of multi-site supply contracts.
- Blisters:Cold-form foil and push-through lidding configurations protect unit-dose medications from moisture ingress. FDA serialization mandates are forcing line reconfigurations to accommodate integrated label-track-and-trace hardware ahead of enforcement windows.
- Pouches:Multi-layer coextrusion formats serve sterile pharmaceutical and medical device applications. California extended producer responsibility legislation is accelerating mono-material recyclable barrier development among West Coast suppliers.
- Labels:Smart-label infrastructure integrates serialization, tamper evidence, and patient instruction layers. Specialty pharmacy direct-to-patient distribution is compressing lead times for customized variable-data printing.
Bottles hold installed capacity. Pouches are rotating up the share rankings.
Material:
Cost tier and performance requirements stratify material selection, with barrier specifications and regulatory compliance timelines determining viable substitutions.
- Plastic:Polyethylene, polypropylene, and polyester formulations sustain the largest volume share across bottles, blister lidding, and flexible formats. EPA restrictions on per- and polyfluoroalkyl substances are forcing transitions in oxygen-barrier films.
- Glass:Borosilicate and soda-lime vials retain premium positioning in parenteral and ophthalmic segments where USP Class VI inertness requirements exclude polymer alternatives. Glass-to-plastic substitution limits constrain flexible format penetration in high-value injectables.
- Paper:Sterilization wraps and secondary packaging substrates serve hospital central supply operations. Sustainability scorecards from United States health systems are expanding demand for certified fiber sourcing.
- Metal:Aluminum lidding foils and collapsible tubes provide absolute moisture and light barriers. Cold-form blister applications concentrate demand among oral solid dose manufacturers.
Plastic holds installed capacity. Paper is rotating up the share rankings.
End User:
Customer type dictates packaging complexity, with regulatory documentation requirements and handling protocols varying sharply across dispensing settings.
- Pharmacies:Retail chains and specialty pharmacy networks drive standardization in unit-dose and compliance-prompting formats. Centralized pharmacy benefit managers are consolidating procurement authority for patient-facing packaging designs.
- Hospitals:Health system mergers are standardizing high-barrier primary formats and driving multi-site supply contracts with validated converters. Blown-film capacity concentration limits mid-tier entrants' access to formulary approvals.
- Clinics:Outpatient and ambulatory settings favor cost-optimized formats with simplified opening features for elderly patient populations. Berry Global competes aggressively in multi-layer coextrusion capacity serving this channel.
- Laboratories:Diagnostic reagent and specimen transport packaging demands validated thermal stability profiles. Biocompatibility testing backlogs at certified laboratories are extending new material introduction timelines.
Pharmacies hold installed capacity. Laboratories are rotating up the share rankings.
Packaging Type:
Structural rigidity determines protection level, manufacturing capital intensity, and compatibility with automated dispensing systems.
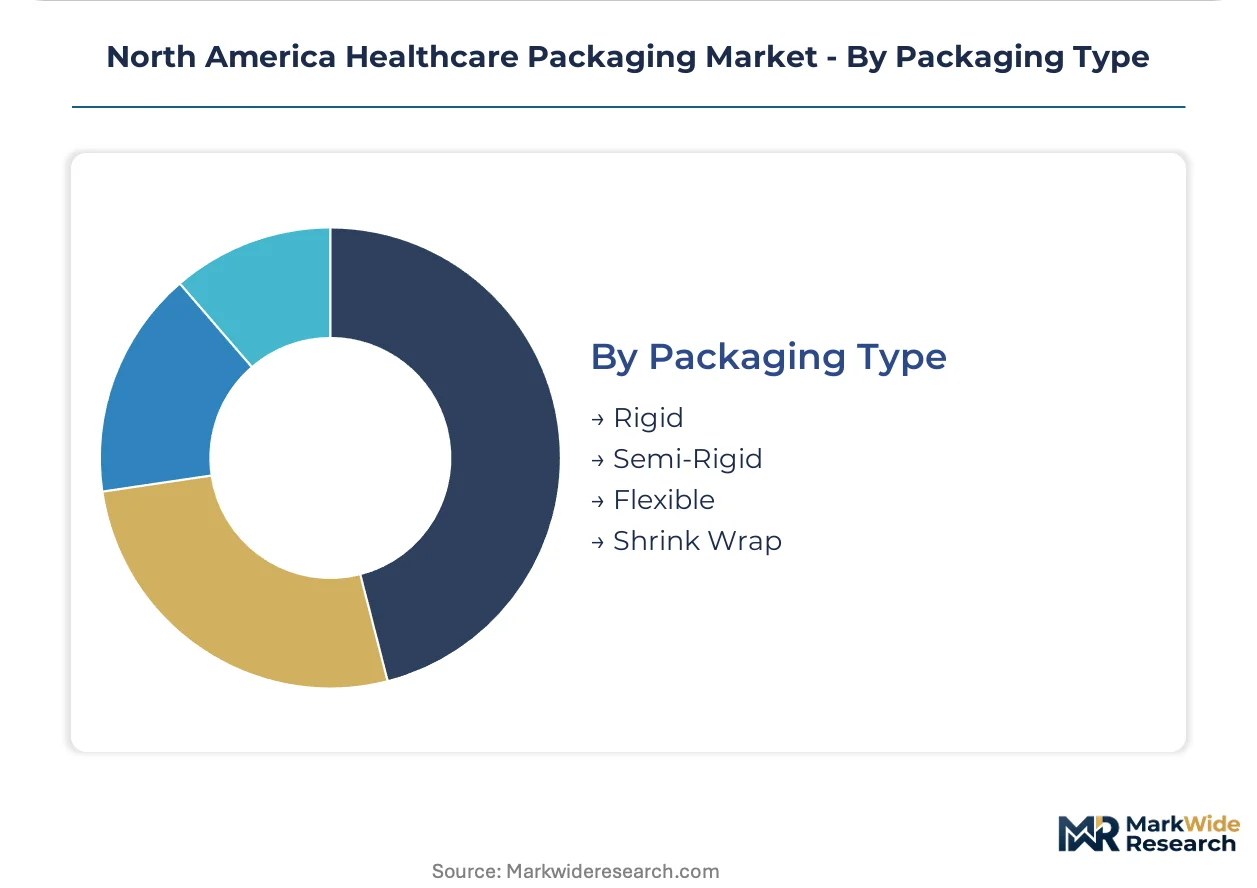
- Rigid:Glass vials, high-density polyethylene bottles, and injection-molded containers dominate oral solid and parenteral applications. Rigid formats lead in value contribution due to established supply chains and premium pricing in sterile segments.
- Flexible:Multi-chamber pouches for lyophilized drug reconstitution represent the steepest expansion trajectory as biologic manufacturers adopt separate diluent and powder chamber designs. Flexible pouches are gaining share fastest in reconstitution workflows historically served by glass vials.
- Semi-Rigid:Thermoformed trays and blister formats bridge protection and material efficiency for medical devices and combination products. Health Canada and PMRA alignment with FDA standards reduces duplicative testing for cross-border suppliers.
- Shrink Wrap:Secondary bundling and pallet stabilization films serve distribution logistics rather than primary product protection. Limited regulatory qualification requirements sustain commodity pricing dynamics.
Rigid holds installed capacity. Flexible is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates asymmetrically between the United States and Canada, with American health system consolidation driving volume premiums while Canadian regulatory alignment reduces qualification overhead for cross-border suppliers.
United States
Specialty pharmacy networks and hospital mergers are standardizing high-barrier primary packaging specifications across multi-site procurement contracts. FDA serialization mandates under the Drug Supply Chain Security Act compress qualification timelines for integrated smart-label infrastructure ahead of enforcement windows. The Greater Boston biotech corridor anchors demand for sterile elastomeric closure systems serving injectable biologics manufacturers.
Canada
Health Canada alignment with FDA packaging integrity standards facilitates supplier qualification for converters serving cross-border supply chains. PMRA regulatory harmonization reduces duplicative testing burdens for multi-layer coextrusion formats entering both markets. Ontario's pharmaceutical manufacturing corridor concentrates blown-film capacity serving hospital central supply operations across the Great Lakes region.
Mexico
Nearshoring of medical device assembly is pulling demand for sterilization wraps and secondary packaging substrates serving export-oriented production facilities. COFEPRIS regulatory convergence with FDA standards accelerates approval pathways for barrier-film suppliers. The Bajío Region's growing pharmaceutical manufacturing base is attracting pouch converters seeking proximity to oral solid dose producers.
North America Healthcare Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in materials and closure technologies. The vendor base stratifies between multinational converters with validated cleanroom extrusion lines and mid-tier entrants constrained by hospital formulary approval barriers. Two archetypes dominate: integrated packaging-IT system providers and mono-material recyclable barrier developers. Competitive moves concentrate on capacity expansion in multi-layer coextrusion and strategic partnerships bridging serialization hardware with label manufacturing.
Among North American packaging conglomerates, Amcor and Berry Global exemplify scale-driven platform integrators with continental production footprints, while West Pharmaceutical Services occupies a specialized position in elastomeric closure systems for injectable formats. These three entities represent contrasting strategic postures—materials diversification, multi-layer capacity aggregation, and component-level clinical validation—each anchoring distinct competitive vectors within the healthcare packaging value chain.
| Leading Market Players |
|---|
| Amcor |
| West Pharmaceutical Services |
| Berry Global |
| Gerresheimer AG |
| Corning Incorporated |
| Nipro Corporation |
| SGD Pharma |
| WestRock |
| CCL Industries |
| Others |
Cost & Logistics Intelligence
Blown-film capacity utilization above 85 percent across the United States and Ontario is compressing lead times for sterile pharmaceutical pouches while simultaneously hardening minimum order quantities for mid-tier buyers. This tightness rewards validated converters with pricing power on configured-to-order barrier specifications while forcing hospital procurement committees toward longer-term offtake commitments.
Pricing Analysis
The customization-premium spread widens to three distinct levels across the North American healthcare packaging value chain. Standard high-density polyethylene bottles for oral solid doses trade on commodity terms with minimal differentiation, while multi-layer coextrusion pouches with embedded temperature-logging sensors command substantial premiums tied to FDA 21 CFR Part 11 compliance documentation. Price differentiation stems from USP Class VI certification tier and geographic delivery cost to specialty pharmacy networks. Cost compression in standard blister lidding is intensifying because EPA fluoropolymer phase-outs are forcing material transitions before qualification windows close. Retail pharmacy chains exhibit the highest price sensitivity, whereas biologic manufacturers prioritizing cold-chain integrity show minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material cost volatility for aluminum lidding foils and specialty polymer resins. Supply concentrates in the United States, Canada, and Mexico under the USMCA framework, with Ontario and the American Midwest anchoring blown-film extrusion capacity. Raw material dependencies rest on polyethylene feedstocks, medical-grade aluminum, and elastomeric closure compounds. Single-source vulnerability concentrates in validated cleanroom extrusion lines serving hospital formulary approvals. Distribution runs through specialty pharmacy benefit managers and consolidated health system procurement committees rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American healthcare packaging incumbents face sustained substitution pressure from mono-material recyclable barrier technologies as California and New York extended producer responsibility legislation compress reformulation timelines. Defending market position requires proactive capability investments rather than reactive compliance.
For Market Incumbents: Harden barrier-film qualification pipelines by securing captive supply of polyethylene-based oxygen barriers ahead of EPA enforcement windows. Deepen backward integration into medical-grade resin compounding to insulate margin structures from petrochemical volatility. Consolidate multi-site supply contracts with merged hospital systems before mid-tier entrants achieve formulary approval.
For New Entrants and Emerging Players: Build out mono-material recyclable pouch capacity targeting West Coast health networks with compressed sustainability scorecard deadlines. Specialty pharmacy direct-to-patient distribution represents the most penetrable channel, with patient-facing unit-dose designs displacing bulk institutional formats. Pursue strategic partnerships with serialization hardware providers to bypass legacy equipment retrofit barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-layer coextrusion formats with embedded sensor films. The five-to-ten year viability window favors converters with validated cleanroom infrastructure and cross-border Health Canada-FDA qualification capabilities. Acquisition targets should demonstrate integrated packaging-IT system expertise. The signal to watch is hospital system sustainability scorecard adoption rates as an indicator of recyclable format demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Coextrusion Capacity Expansion | Addresses biologic cold-chain requirements while qualifying for hospital formulary contracts. |
| Backward Integration into Medical-grade Resin Compounding | Reduces exposure to petrochemical price volatility and EPA material transition risks. |
| Smart-label Infrastructure Partnership | Bridges serialization hardware with pharmaceutical track-and-trace compliance mandates. |
| Mono-material Recyclable Barrier Development | Aligns with California and New York extended producer responsibility legislation timelines. |
| Cross-border Health Canada-FDA Qualification | Reduces duplicative testing burdens for converters serving integrated North American supply chains. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with pharmaceutical packaging procurement managers, FDA regulatory affairs consultants, hospital GPO contract specialists, and multi-layer coextrusion plant engineers informed demand-side and supply-side dynamics. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, Health Canada packaging integrity standards, EPA fluoropolymer restriction notices, and hospital system sustainability scorecard disclosures. Bottom-up capacity estimates for blown-film and coextrusion lines were triangulated against top-down pharmaceutical production forecasts across the analysis window.
Calibration against historical qualification timelines and regulatory enforcement patterns shaped the projection framework. Segmentation dimensions modeled include packaging format, material substrate, end-user channel, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis applied to base-year market sizing. Forecast inputs incorporated biologic pipeline expansion rates, hospital merger activity trajectories, and state-level extended producer responsibility adoption schedules.
Practitioners should monitor EPA enforcement timeline acceleration, Health Canada-FDA harmonization scope expansion, and specialty pharmacy network consolidation rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Scintillation Vials Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Specimen Containers Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Combat Dressing Market
Medical Supplies
China Hospital Supplies Market