
 Medical Tourniquets Market | 2026-2036
Medical Tourniquets Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tourniquets Market Outlook
REACH compliance is realigning the cost-of-entry calculus for European manufacturers of composite-based tourniquets. Stryker Corporation leverages its orthopedic device distribution network to sustain channel control across North American hospital systems. Zimmer Biomet anchors its position through surgical procedure integration, while Delfi Medical Innovations specializes in pneumatic pressure regulation technology for operating room environments.
Medical tourniquets are mechanical or pneumatic devices designed to temporarily occlude arterial and venous blood flow to a limb, typically employing bladder pressures of 250-350 mmHg for surgical applications and windlass mechanisms for emergency field use. Their primary commercial purpose centers on creating bloodless operative fields in orthopedic and trauma surgery while enabling rapid hemorrhage control in pre-hospital and military settings. Pneumatic tourniquets dominate hospital revenue pools due to precision pressure monitoring requirements, whereas tactical tourniquets represent the fastest-growing end user category driven by military and emergency medical services procurement. Composite materials are displacing traditional nylon in premium segments as manufacturers pursue single-use sterility and reduced latex allergen profiles.
The FDA governs Class II device clearances through 510(k) pathways, while the EU Medical Device Regulation mandates notified body conformity assessments for pneumatic systems sold in Europe. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements further constrain material selection and control unit design for electronic tourniquets. Stakeholders must monitor evolving battlefield trauma protocols and civilian Stop the Bleed campaign expansions to anticipate procurement specification shifts.
Market Dynamics
Military trauma protocol standardization is compressing procurement cycles for tactical tourniquets while civilian Stop the Bleed mandates expand institutional purchasing requirements across emergency medical services and educational facilities.
Growth Catalysts
- NATO battlefield trauma protocols:Alliance-wide medical modernization programs mandate windlass tourniquet carriage for all deployed personnel, creating pooled procurement volumes that reduce per-unit acquisition costs for member defense ministries.
- EU Medical Device Regulation:MDR conformity assessment streamlines cross-border hospital purchasing by harmonizing pneumatic tourniquet safety standards across German, French, and Italian healthcare networks.
- Composite material substitution:Single-use sterile tourniquets utilizing polymer-fiber blends replace reusable nylon systems in orthopedic surgery suites, eliminating latex allergen liability and sterilization infrastructure burdens.
Market Restraints
- Silicone bladder supply concentration:Three Asian specialty chemical manufacturers control 70% of medical-grade elastomer supply for pneumatic cuff production, exposing European and North American device assemblers to input price volatility and allocation risk.
- REACH compliance cost escalation:ECHA substance-of-very-high-concern listings for legacy plasticizers force reformulation of PVC-based inflation tubing, adding 12-18 months to product recertification timelines.
- Manual windlass substitution ceiling:Tactical tourniquets face functional performance limits in multi-limb amputation scenarios where junctional hemorrhage control requires alternative interventions, capping addressable trauma mortality reduction claims.
Strategic Opportunities
- Rural EMS network penetration:Under-equipped ambulance services in India's tier-2 and tier-3 cities lack standardized hemorrhage control protocols, creating first-mover advantage for trauma device distributors establishing training partnerships with state health ministries.
- Integrated surgical system convergence:Pneumatic tourniquets incorporating Bluetooth pressure telemetry and EMR data logging capture premium positioning in robotic-assisted orthopedic procedures requiring precise ischemia time documentation.
- Federal Stop the Bleed mandates:US Department of Education guidance incentivizing tourniquet placement in K-12 institutions generates institutional procurement channels distinct from traditional hospital supply chains.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel polymer formulations face 6-9 month queue times at accredited laboratories, delaying 510(k) submission readiness for pneumatic system upgrades.
- Legacy hospital capital equipment integration:Electronic tourniquet control units require RS-232 or proprietary interface compatibility with installed surgical boom systems, forcing manufacturers to maintain obsolete communication protocol support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tourniquets Market |
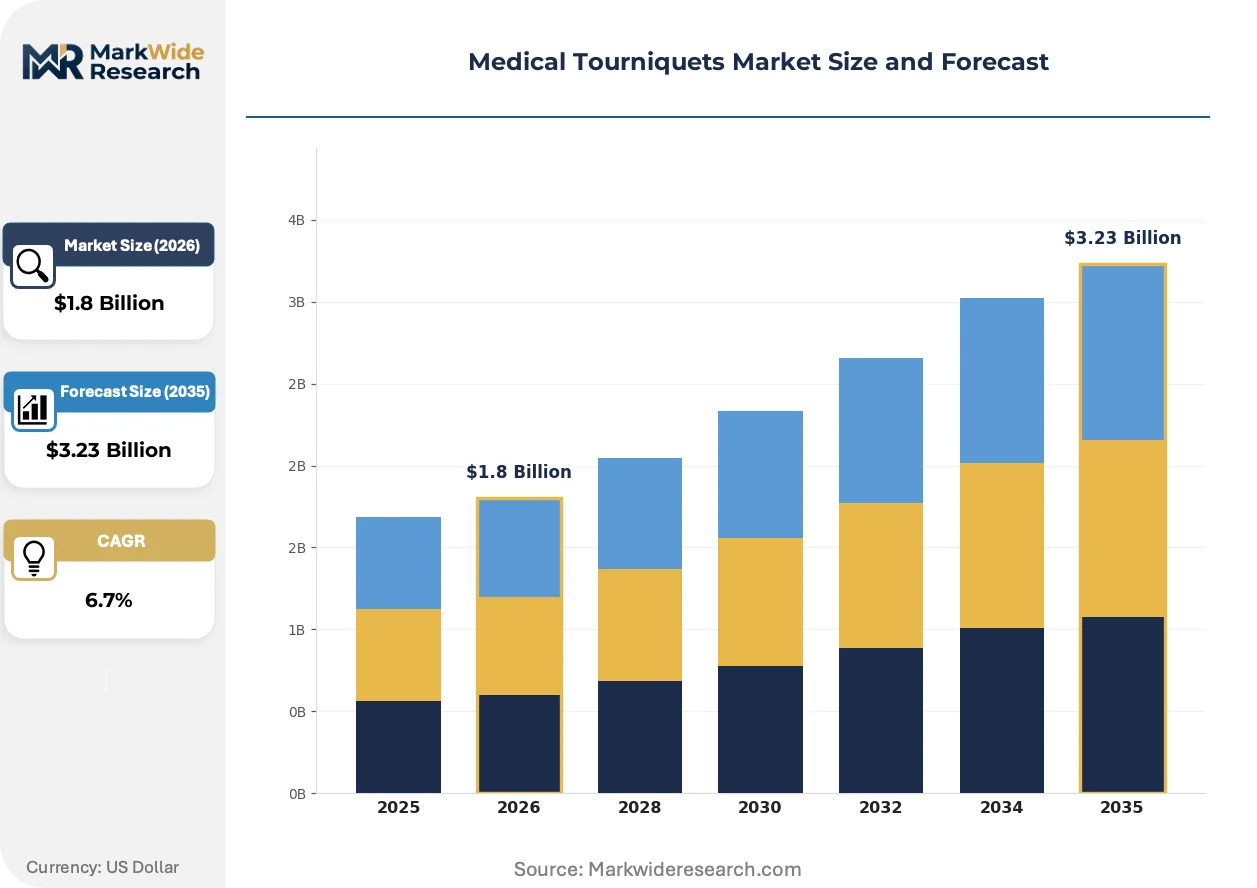
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tactical Tourniquets, Elastic Tourniquets, Pneumatic Tourniquets, Training Tourniquets End User: Hospitals, Emergency Medical Services, Military, Home Care Application: Trauma Management, Surgical Procedures, Pre-Hospital Care, Sports Medicine Material: Nylon, Rubber, Plastic, Composite |
| Companies Covered | Hammarplast Medical, Ulrich Medical, Zimmer Biomet, Anetic Aid, OHK Medical Devices, Stryker Corporation, VBM Medizintechnik, Rudolf Riester, Delfi Medical Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tourniquets Market Strategic Shifts
Electrification of pressure control systems and material science advances are redefining performance benchmarks across surgical and emergency applications while regulatory harmonization accelerates cross-border product standardization.
Pneumatic tourniquet electrification is displacing mechanical gauge systems with microprocessor-controlled pressure regulation. German and Japanese orthopedic surgery centers are adopting these platforms for total joint replacement procedures requiring sustained limb occlusion exceeding 90 minutes. This transition is electrifying competitive differentiation around pressure accuracy claims and automated safety cutoff features.
FDA's updated 510(k) predicate device pathways for Class II pneumatic systems compress premarket notification review timelines for manufacturers demonstrating substantial equivalence to cleared reference devices. The industrial consequence accelerates feature iteration cycles for pressure monitoring electronics while maintaining clinical safety documentation burdens. North American hospital procurement departments are responding by shortening vendor qualification periods for tourniquet system upgrades.
Institutional purchasing departments are consolidating hemorrhage control device procurement under integrated trauma kit contracts rather than standalone tourniquet requisitions. This behavior disrupts traditional distributor relationships by favoring suppliers offering bundled hemostatic gauze, chest seals, and airway adjuncts alongside windlass systems. The pattern is most visible in US municipal emergency services and Canadian provincial health authorities standardizing tactical emergency casualty care equipment across regional response networks.
Medical Tourniquets Market Segmentation
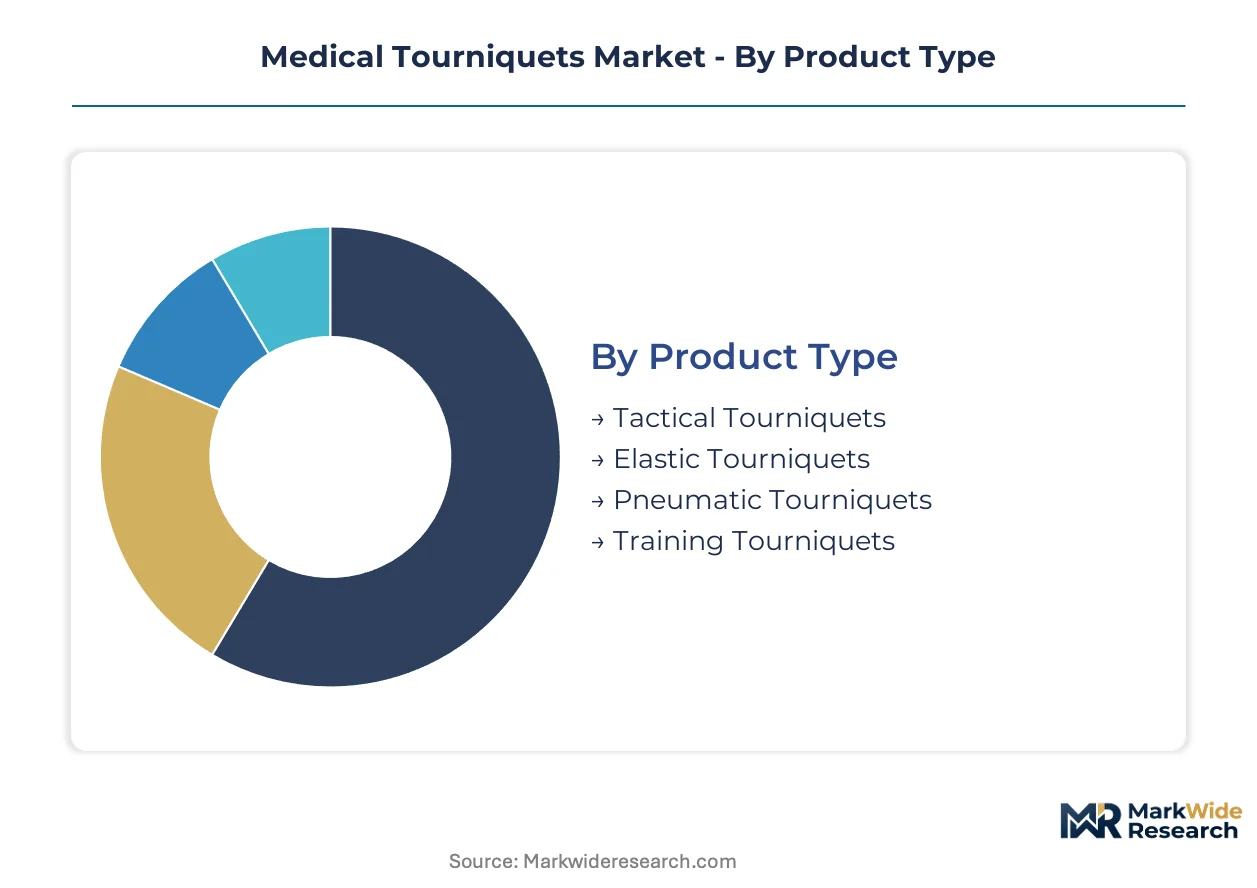
Medical tourniquets serve divergent clinical environments requiring fundamentally different engineering specifications. Product architectures must reconcile the precision demands of operating rooms with the durability imperatives of battlefield trauma protocols.
Product Type:
Pneumatic systems integrate into surgical suites as capital equipment with electronic control units, while tactical variants function as standalone disposable devices carried by individual operators.
- Tactical Tourniquets:Windlass-mechanism devices constructed from polymer-fiber composites achieve single-handed application under combat stress. NATO procurement standardization across German, French, and Polish defense ministries is consolidating specification requirements and compressing vendor qualification cycles.
- Pneumatic Tourniquets:Microprocessor-controlled bladder systems deliver 250-350 mmHg pressure regulation with automatic safety cutoffs. German orthopedic surgery centers are adopting these platforms for total joint replacement procedures requiring sustained limb occlusion exceeding 90 minutes.
- Elastic Tourniquets:Latex-free rubber band systems serve phlebotomy and intravenous access in outpatient clinics.
- Training Tourniquets:Non-functional replicas replicate tactile feedback for hemorrhage control education programs.
Volume placements concentrate in Pneumatic Tourniquets; the faster expansion belongs to Tactical Tourniquets.
End User:
Customer procurement patterns stratify by capital intensity, with institutional buyers demanding multi-year service contracts and individual operators prioritizing unit portability.
- Hospitals:Integrated surgical suites in Germany and Japan specify pneumatic systems with Bluetooth pressure telemetry and EMR data logging for robotic-assisted orthopedic procedures requiring precise ischemia time documentation.
- Military:Defense ministries mandate windlass carriage for all deployed personnel, with Bundeswehr medical modernization programs driving dual-use procurement that channels tactical variants into civilian emergency response training.
- Emergency Medical Services:Municipal ambulance services in tier-2 and tier-3 Indian cities lack standardized hemorrhage control protocols, creating first-mover opportunities for distributors establishing state health ministry partnerships.
- Home Care:Post-surgical patients requiring limb occlusion for lymphedema management represent a nascent consumer segment.
Revenue concentration sits with Hospitals; Military procurement is climbing the fastest.
Application:
Clinical use cases impose distinct performance benchmarks, from the bloodless field requirements of elective surgery to the time-critical demands of pre-hospital trauma.
- Surgical Procedures:Orthopedic and trauma surgery suites require sustained occlusion with pressure monitoring accuracy within 5 mmHg. FDA 510(k) predicate pathways for Class II pneumatic systems are compressing premarket review timelines for manufacturers demonstrating substantial equivalence.
- Trauma Management:Junctional hemorrhage control in multi-limb amputation scenarios faces functional performance limits, capping addressable mortality reduction claims and driving alternative intervention development.
- Pre-Hospital Care:Emergency medical technicians require rapid-deployment devices compatible with confined-space extrication.
- Sports Medicine:Athletic training facilities utilize tourniquets for blood flow restriction therapy and acute injury response.
Procedure volume aggregates in Surgical Procedures; Trauma Management is gaining share fastest.
Material:
Material selection determines sterility protocols, allergen profiles, and supply chain exposure to petrochemical feedstock volatility.
- Composite:Polymer-fiber blends enable single-use sterile tourniquets that eliminate latex allergen liability and sterilization infrastructure burdens in orthopedic surgery suites. REACH compliance is realigning cost-of-entry calculus for European manufacturers.
- Nylon:Legacy reusable systems face displacement as hospitals retire sterilization equipment.
- Rubber:Natural and synthetic elastomers remain prevalent in phlebotomy applications.
- Plastic:PVC-based inflation tubing requires reformulation following ECHA substance-of-very-high-concern listings for legacy plasticizers.
Production volume still concentrates in Nylon; Composite materials are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the highest absolute demand for pneumatic surgical systems, while United States military procurement and Indian emergency services expansion create divergent growth vectors across three continents.
United States
Department of Defense trauma protocol standardization and K-12 Stop the Bleed mandates drive institutional procurement. FDA 510(k) clearance pathways for Class II pneumatic devices compress manufacturer time-to-market. Boston and Philadelphia surgical device clusters host orthopedic capital equipment distributors integrating Bluetooth-enabled tourniquets into robotic surgery suites.
Germany
Bundeswehr medical modernization and civilian hospital network upgrades generate dual-use procurement volumes. EU Medical Device Regulation harmonizes cross-border safety standards for pneumatic systems. Baden-Württemberg and Bavaria manufacturing corridors concentrate composite material processors serving sterile single-use tourniquet production.
India
Tier-2 and tier-3 city ambulance services lack standardized hemorrhage control protocols, creating first-mover openings for trauma device distributors. CDSCO medical device registration requirements govern import licensing for pneumatic systems. Maharashtra and Karnataka state health ministries pilot training partnerships with emergency medical services equipment suppliers.
Japan
Orthopedic surgery centers adopt microprocessor-controlled pressure regulation for total joint replacement procedures exceeding 90 minutes. PMDA Class II device approvals align with international safety benchmarks. Tokyo and Osaka metropolitan hospital networks specify EMR-integrated tourniquet systems for robotic-assisted procedures.
United Kingdom
NHS procurement frameworks consolidate hemorrhage control device purchasing under integrated trauma kit contracts. MHRA conformity assessment procedures apply post-Brexit device regulations. London and Greater Manchester trauma networks standardize tactical emergency casualty care equipment across regional ambulance trusts.
Medical Tourniquets Market Competitive Environment
North American producers anchor the pneumatic surgical equipment tier; European specialists hold windlass mechanism fabrication. The vendor base splits between diversified orthopedic conglomerates and focused trauma device fabricators. Three strategic archetypes dominate: diversified medical device conglomerates with hospital system distribution control, pneumatic pressure regulation specialists, and tactical equipment pure-plays serving defense ministries. Competitive moves concentrate on surgical suite integration partnerships and military procurement qualification cycles.
Among diversified orthopedic device manufacturers, Stryker Corporation and Zimmer Biomet exemplify the capital equipment integration archetype. Delfi Medical Innovations occupies a specialist position within pneumatic pressure regulation technology. German fabricators including Ulrich Medical and VBM Medizintechnik sit within the European surgical device cluster, while Hammarplast Medical represents Nordic-based disposable medical equipment production.
| Leading Market Players |
|---|
| Hammarplast Medical |
| Ulrich Medical |
| Zimmer Biomet |
| Anetic Aid |
| OHK Medical Devices |
| Stryker Corporation |
| VBM Medizintechnik |
| Rudolf Riester |
| Delfi Medical Innovations |
| Others |
Value Chain & Pricing Dynamics
Captive production of medical-grade silicone bladders anchors supply security for pneumatic tourniquet manufacturers while simultaneously locking in premium pricing tiers for European and North American device assemblers. This integration choice insulates compliant players from Asian elastomer price volatility but forces higher capital deployment that transmits into hospital procurement contracts.
Pricing Analysis
Volume placements concentrate in economy-tier reusable nylon systems, while margins accrue to premium single-use composite tourniquets with sterile packaging and latex-free certification. Price differentiation hinges on FDA 510(k) clearance tier and ISO 10993 biocompatibility grade, with pneumatic systems commanding substantial premiums over windlass mechanisms. Pricing pressure stems from REACH compliance cost escalation for PVC tubing reformulation, compressing margins for mid-tier European manufacturers. Military procurement departments exhibit lowest price sensitivity due to NATO standardization mandates, while Indian tier-2 ambulance services face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese specialty chemical manufacturers controlling medical-grade silicone elastomer supply for pneumatic cuff production. Raw material dependencies center on polymer-fiber composites, synthetic rubber compounds, and microprocessor pressure sensors sourced from Taiwan and Germany. Supply chain risk concentrates in tariff exposure for Chinese-sourced PVC inflation tubing following ECHA substance-of-very-high-concern regulatory actions. Distribution runs through orthopedic device distributors in North America and hospital procurement consortiums in Germany, with direct defense ministry contracts bypassing traditional channels for tactical variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Medical Device Regulation conformity assessments erect barrier-to-entry moats favoring incumbents with established notified body relationships and recertification capital reserves.
For Market Incumbents: Cement channel control through multi-year service contracts with German hospital networks while acquiring composite material processors in Baden-Württemberg to secure sterile single-use supply chains. Stryker Corporation and Zimmer Biomet exemplify this defensive posture, leveraging orthopedic distributor relationships against emerging pneumatic specialists. Priority investment belongs to Bluetooth-enabled pressure telemetry integration for robotic surgery suite compatibility. For New Entrants and Emerging Players: Enter via training tourniquet partnerships with Indian state health ministries in Maharashtra and Karnataka, where tier-2 and tier-3 city ambulance services lack standardized hemorrhage control protocols. This white-space geography offers first-mover positioning before CDSCO registration requirements tighten. Go-to-market execution should anchor on distributor relationships with emergency medical services equipment suppliers rather than direct hospital sales. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking pneumatic pressure regulation capabilities, with Delfi Medical Innovations representing the specialist archetype. Long-term viability favors targets with FDA 510(k) clearance portfolios and Bundeswehr procurement qualifications. The signal to watch is NATO battlefield trauma protocol revision cycles, which reset vendor qualification windows and compress incumbent advantage.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment accelerates cross-border hospital purchasing across German, French, and Italian networks. |
| Hospital System Partnership | Integration with Stryker's orthopedic distribution network secures channel control for pneumatic system upgrades. |
| Software Companion Development | Bluetooth pressure telemetry and EMR data logging capture premium positioning in robotic-assisted procedures. |
| FDA Submission | 510(k) predicate device pathways compress premarket review timelines for microprocessor-controlled systems. |
| Reimbursement Strategy | Coding alignment with Medicare surgical procedure bundles determines hospital capital equipment adoption velocity. |
Study Parameters
Multi-period observation of NATO procurement volumes, FDA 510(k) clearance timelines, and REACH compliance cost trajectories anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and defense ministry procurement officers. Secondary validation drew from FDA device registration databases, EUDAMED conformity assessments, Bundeswehr medical modernization disclosures, and CDSCO import licensing records. Bottom-up demand modeling across surgical procedure volumes and trauma kit placements triangulated against top-down market sizing from distributor revenue disclosures.
Segment-weighting applied product type splits between pneumatic, tactical, elastic, and training variants, crossed with end-user stratification across hospitals, military, emergency medical services, and home care. Application segmentation distinguished surgical procedures from trauma management and pre-hospital care. CAGRs were derived from installed base replacement cycles, NATO personnel deployment forecasts, and Stop the Bleed campaign expansion trajectories across the projection horizon. Industry-specific inputs incorporated silicone elastomer price indices and ISO 10993 testing queue times at accredited laboratories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance-of-very-high-concern listing acceleration or NATO trauma protocol specification shifts. Forecasts reflect assumptions regarding MDR implementation timelines, Bundeswehr budget continuity, and Indian state health ministry training partnership execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Respiratory Masks Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Luer Plug Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Global Needles Market