
 Keloid Treatment Market | 2026-2036
Keloid Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Keloid Treatment Market Outlook
Multi-source procurement for laser and cryotherapy platforms is decoupling from legacy single-vendor contracts in large hospital systems. Sensus Healthcare sustains its position through focused manufacturing of superficial radiation therapy systems for post-surgical keloid management. Lumenis leverages diversified photonics portfolios spanning aesthetic and therapeutic indications. Candela Medical differentiates through specialized energy-based device portfolios targeting fibroproliferative disorders.
Keloid treatment encompasses therapeutic interventions targeting pathological scar formation characterized by excessive collagen deposition beyond original wound boundaries, including corticosteroid injections, laser-based photothermolysis, cryogenic tissue destruction, and surgical excision with adjuvant radiation. These modalities serve to reduce lesion volume, alleviate pruritus and pain, restore functional tissue mobility, and prevent recurrence following traumatic or surgical injury. Laser therapy occupies the premium tier among product types due to capital intensity and specialized operator training requirements, while injections retain the broadest addressable base across dermatology clinics and hospitals. Device-assisted delivery commands disproportionate margin capture compared with topical and systemic alternatives, reflecting reimbursement differentials and clinical efficacy thresholds. Recurrence management represents an emerging treatment stage segment as awareness of keloid reformation rates drives protocol standardization.
FDA 510(k) clearance frameworks govern device-assisted modalities in the United States, while the EU MDR and CE marking requirements reshape market access timelines for laser and cryotherapy equipment across European member states. Japan's PMDA and METI oversight of medical laser classifications adds a distinct regulatory layer for manufacturers seeking Asian market penetration. ISO 13485 quality management certification functions as a baseline expectation for contract manufacturers supplying components to branded device producers. Stakeholders must monitor evolving reimbursement coding for combination therapy protocols as payers scrutinize cost-effectiveness evidence across preventive and active treatment stages.
Market Dynamics
FDA 510(k) clearance acceleration for laser and cryotherapy platforms is compressing commercialization timelines while dermatology clinics in the United States, Germany, and South Korea expand dedicated scar management service lines. This regulatory velocity is reshaping competitive entry patterns and capital deployment priorities across device manufacturers.
Growth Catalysts
- Superficial Radiation Therapy:Post-surgical adjuvant protocols are gaining protocol standardization in tertiary care centers, reducing recurrence rates and expanding addressable treatment stages.
- FDA 510(k) Framework:Streamlined clearance pathways for energy-based devices are accelerating market access timelines compared with premarket approval alternatives.
- South Korea Dermatology Cluster:Seoul-based aesthetic medicine hubs are driving adoption of combination therapy protocols integrating laser photothermolysis with intralesional corticosteroids.
Market Restraints
- Capital Equipment Intensity:Laser platforms require specialized operator training and facility infrastructure that limits penetration in independent dermatology practices.
- Recurrence Biology:Pathological fibroproliferation mechanisms remain incompletely understood, constraining predictive biomarker development and personalized protocol design.
- Reimbursement Compression:Payer scrutiny of combination therapy cost-effectiveness is narrowing coverage for device-assisted modalities relative to pharmaceutical alternatives.
Strategic Opportunities
- Home-Use Cryotherapy Devices:Consumer-grade temperature-controlled applicators for early-stage keloid management represent an underdeveloped channel beyond clinical settings.
- EU MDR Transition:CE marking requirements under the Medical Device Regulation are creating competitive moats for manufacturers with established quality management systems.
- Telemedicine Integration:Remote lesion monitoring and treatment response tracking are enabling protocol adherence improvements in rural and underserved geographies.
Industry Challenges
- Operator Certification Bottlenecks:Laser safety credentialing and energy-based device training programs face capacity constraints relative to installation growth.
- Supply Chain Reconfiguration:Optical component sourcing for photonics platforms is experiencing lead time volatility from specialized germanium and sapphire suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keloid Treatment Market |
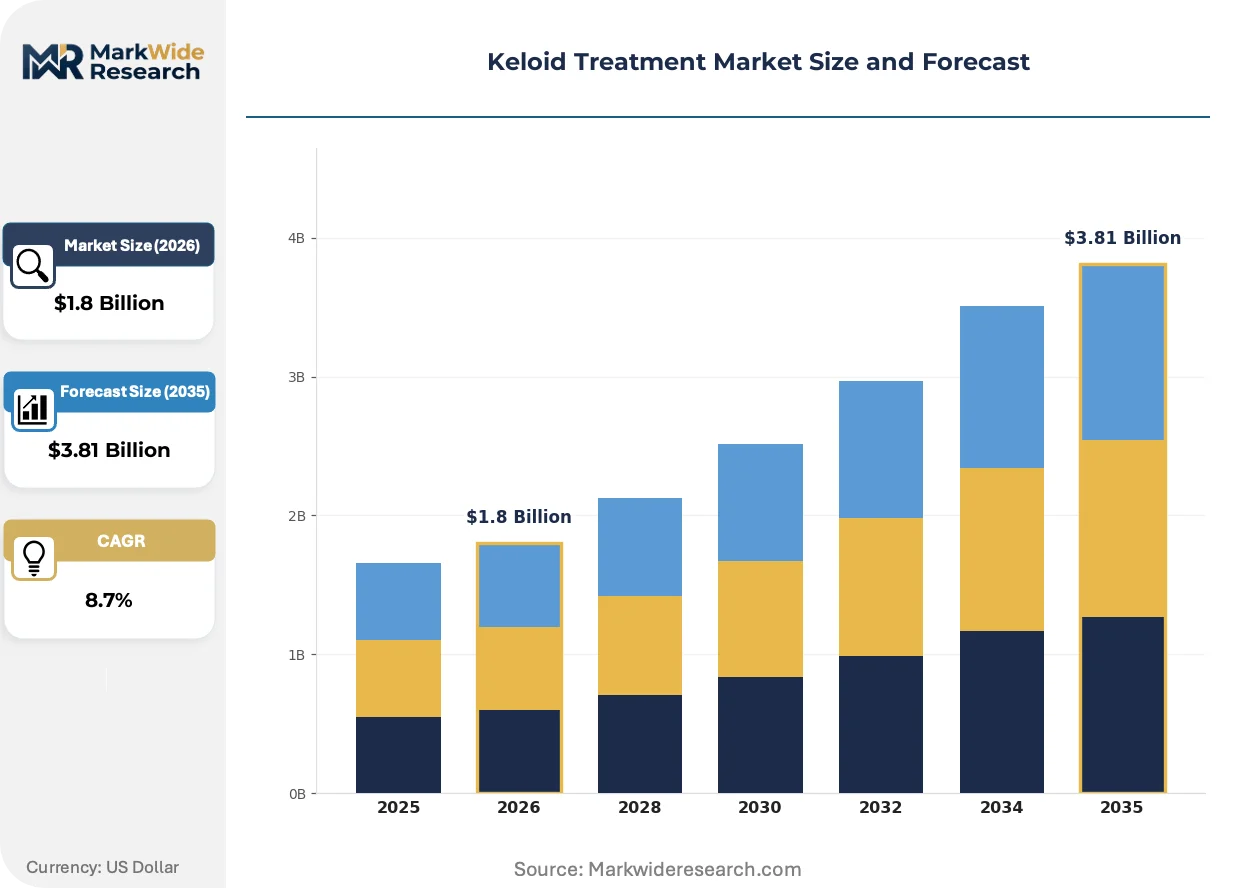
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Laser Therapy, Surgical Excision, Cryotherapy End User: Dermatology Clinics, Hospitals, Medical Spas, Homecare Settings Delivery Mode: Injectable, Topical, Systemic, Device-Assisted Treatment Stage: Preventive, Active, Post-operative, Recurrence Management |
| Companies Covered | Novartis AG, Sensus Healthcare, Perrigo Company plc, Sonoma Pharmaceuticals, Bausch Health Companies, Candela Medical, Lumenis, Smith & Nephew plc, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keloid Treatment Market Strategic Shifts
Photonics miniaturization and algorithmic treatment planning are converging to reshape device architecture and clinical workflow integration. These developments are compressing the gap between capital-intensive hospital installations and scalable clinic-based deployment.
Fractional laser technology is absorbing demand from conventional ablative platforms by enabling tunable penetration depths with reduced thermal injury zones. Dermatology clinics in metropolitan United States markets are adopting these systems at replacement-cycle intervals of 36-48 months. The technology is absorbing margin pressure from reimbursement compression while expanding treatable lesion size ranges.
EU MDR technical documentation requirements are extending market access preparation timelines for cryotherapy equipment manufacturers. European notified bodies are prioritizing clinical evidence standards that favor established device producers with legacy data portfolios. Laser classification systems under this framework are experiencing reevaluation delays that disadvantage novel wavelength platforms.
Multi-year service contracts are displacing transactional equipment purchases in large hospital procurement departments. Integrated maintenance and software upgrade provisions are capturing recurring revenue streams that offset capital sale compression. This shift is most pronounced in German and South Korean healthcare systems with centralized purchasing authorities.
Keloid Treatment Market Segmentation
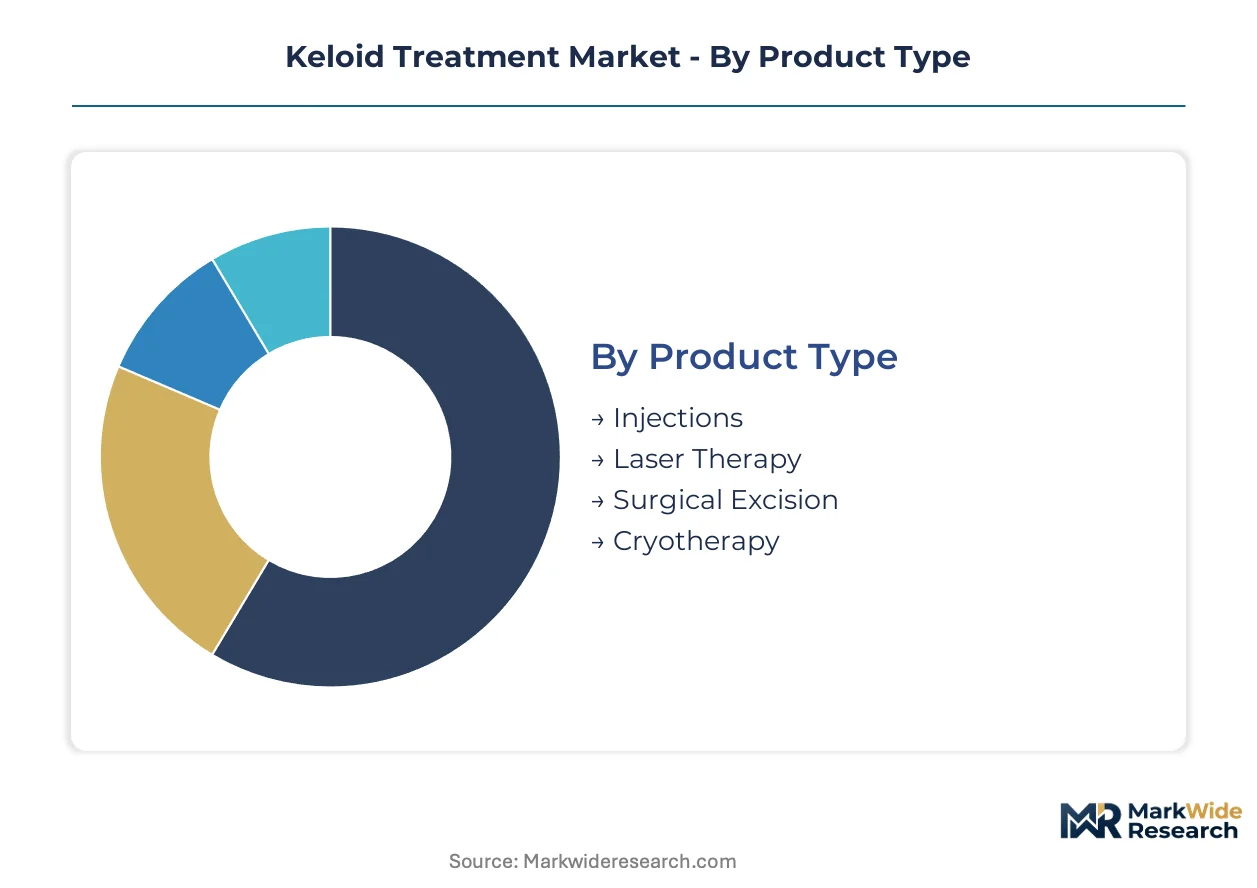
Segmentation in keloid treatment reveals divergent margin structures and capital requirements across therapeutic modalities. Product type and delivery mode classifications determine reimbursement pathways, while end-user channels dictate equipment scale and operator certification intensity.
Product Type:
Capital intensity and reimbursement tiers drive purchasing decisions across clinical settings, with facility infrastructure and operator training requirements filtering adoption.
- Laser Therapy:Photonics platforms deliver selective photothermolysis targeting collagen remodeling through tunable wavelengths. United States dermatology clinics absorb premium installations despite capital intensity, constrained by specialized operator credentialing and extended training programs.
- Injections:Intralesional corticosteroid formulations represent the foundational intervention with minimal facility requirements. Broad penetration across independent dermatology practices and hospital outpatient departments reflects low barrier to entry and established reimbursement coding.
- Surgical Excision:Excisional techniques with adjuvant protocols address large or refractory lesions. Tertiary care centers concentrate demand where combined modality approaches justify facility investment.
- Cryotherapy:Temperature-controlled tissue destruction devices span clinical and emerging consumer applications. Device miniaturization is expanding addressable settings beyond traditional dermatology environments.
Injections lead on scale; laser therapy leads on momentum.
End User:
Channel concentration varies by procedure complexity and capital equipment requirements, with service line expansion reshaping competitive positioning.
- Dermatology Clinics:Specialized scar management service lines in Seoul, Los Angeles, and Munich drive combination protocol adoption. These facilities capture margin from device-assisted modalities through volume-based purchasing arrangements.
- Hospitals:Tertiary centers manage complex or recurrent cases requiring multidisciplinary coordination. Post-surgical adjuvant radiation protocols concentrate in academic medical centers with integrated oncology services.
- Medical Spas:Aesthetic medicine facilities in South Korea and United States metropolitan markets address early-stage lesions. Regulatory boundaries between cosmetic and therapeutic indications constrain service scope.
- Homecare Settings:Consumer-grade temperature applicators and topical systems target preventive and maintenance stages. Channel development remains nascent relative to clinical alternatives.
Dermatology clinics lead on scale; homecare settings expand most quickly.
Delivery Mode:
Reimbursement differentials and clinical efficacy thresholds determine margin capture, with device-assisted modalities commanding premium positioning.
- Device-Assisted:Energy-based and temperature-controlled platforms enable precise tissue targeting with operator-dependent outcomes. Payer scrutiny of cost-effectiveness evidence is narrowing coverage relative to pharmaceutical alternatives.
- Injectable:Direct intralesional administration of corticosteroids and other agents remains the reimbursement baseline. Formulation stability and injection technique standardization support broad clinical adoption.
- Topical:Transdermal preparations address early-stage or small lesions with minimal invasiveness. Efficacy limitations relative to invasive alternatives constrain addressable severity ranges.
- Systemic:Oral or parenteral agents target multifocal or severe presentations with generalized fibroproliferative patterns. Off-label use patterns dominate pending targeted therapy development.
Injectable leads on scale; device-assisted leads on momentum.
Treatment Stage:
Protocol standardization across the care continuum is expanding addressable intervention points, with recurrence awareness driving post-treatment monitoring services.
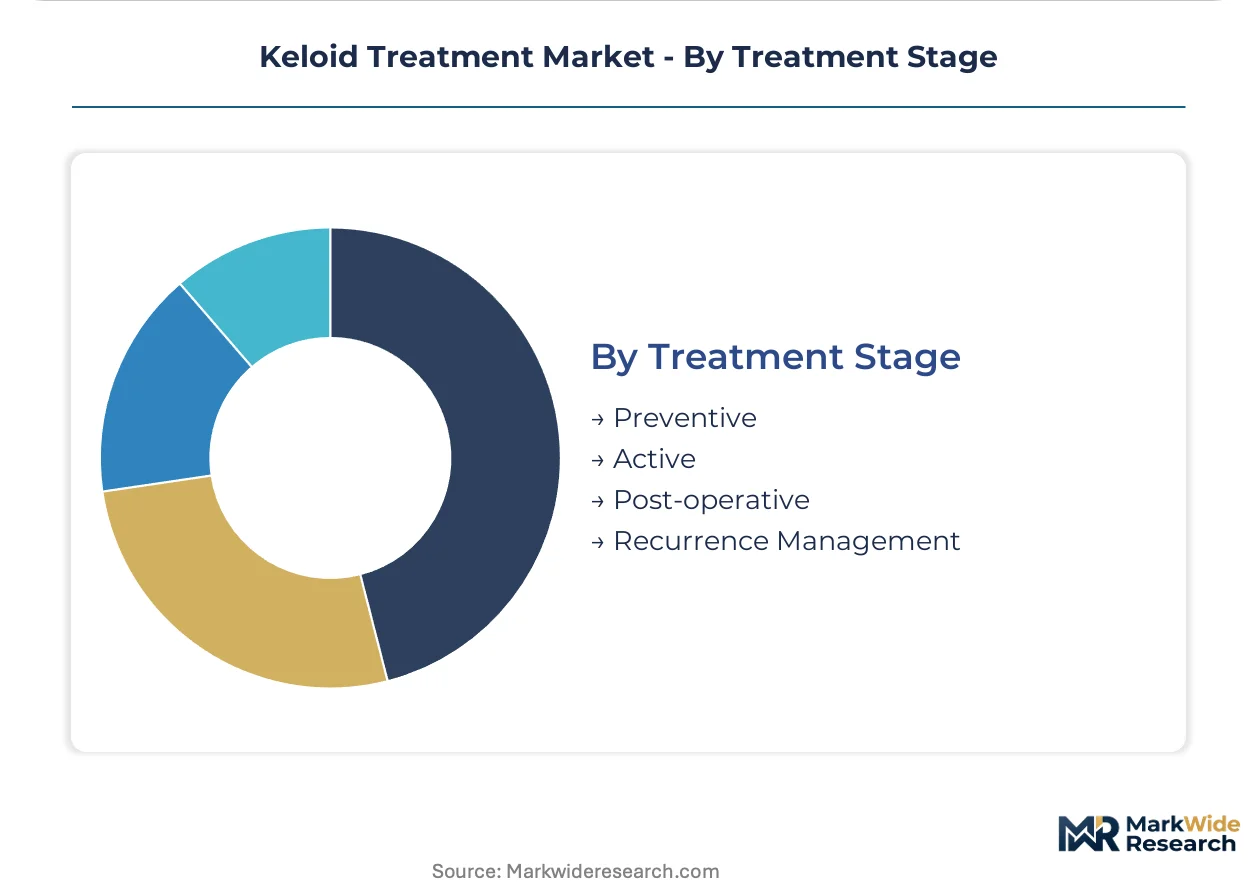
- Active:Established lesion intervention through primary therapeutic modalities captures the majority of current procedure volume. Treatment selection depends on lesion age, size, anatomical location, and prior intervention history.
- Recurrence Management:Reformation protocols following surgical or traumatic injury are gaining protocol standardization. Awareness of keloid biology is driving adjuvant radiation and combination therapy adoption.
- Preventive:Prophylactic intervention in high-risk patients and anatomical sites represents an emerging service category. Genetic and phenotypic risk stratification remains underdeveloped.
- Post-operative:Adjuvant protocols immediately following surgical procedures are standardizing in tertiary care. Superficial radiation therapy timing and dosing regimens are achieving protocol consensus.
Active leads on scale; recurrence management climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping device manufacturing footprints as FDA 510(k) clearance velocity contrasts with EU MDR documentation burdens. Manufacturers are optimizing production location against compliance cost differentials while clinical demand concentrates in dermatology clusters with established reimbursement pathways.
United States
FDA 510(k) pathways for laser and cryotherapy platforms compress commercialization timelines versus premarket approval alternatives. Dermatology clinics in Los Angeles and Miami expand dedicated scar management service lines with combination therapy protocols. Superficial radiation therapy installations concentrate in tertiary care centers across the Southeast and Pacific Coast.
Germany
EU MDR technical documentation requirements extend market access preparation timelines for cryotherapy equipment manufacturers. Notified bodies prioritize clinical evidence standards favoring established device producers with legacy data portfolios. Munich and Hamburg anchor dermatology service line expansion with centralized hospital procurement driving multi-year service contracts.
South Korea
Seoul-based aesthetic medicine hubs drive adoption of laser photothermolysis integrated with intralesional corticosteroids. MFDS oversight of medical laser classifications adds distinct regulatory layers for Asian market penetration. The Seoul Capital Area concentrates device-assisted delivery demand with volume-based purchasing arrangements.
Japan
METI and PMDA oversight of medical laser classifications creates specialized compliance requirements for energy-based devices. Tokyo and Osaka dermatology clinics standardize post-surgical adjuvant protocols with superficial radiation therapy timing consensus. Domestic quality management certification functions as baseline expectation for component suppliers.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for laser and cryotherapy platforms. London and Manchester dermatology centers navigate CE marking recognition transitions while expanding hypertrophic scar management services. NHS procurement frameworks favor established device producers with integrated maintenance provisions.
Keloid Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue home-use cryotherapy and telemedicine-integrated monitoring systems. The market structures around three tiers: capital-intensive photonics manufacturers, diversified dermatology device portfolios, and pharmaceutical injectable specialists. Two dominant competitive moves are reshaping positioning: multi-year service contracts displacing transactional equipment purchases, and EU MDR transition creating competitive moats for quality-certified manufacturers.
Among device-centric manufacturers, Sensus Healthcare, Lumenis, and Candela Medical exemplify distinct strategic archetypes. Sensus Healthcare represents focused manufacturing of radiation therapy systems for post-surgical applications. Lumenis occupies a position spanning aesthetic and therapeutic photonics portfolios. Candela Medical anchors specialized energy-based device positioning targeting fibroproliferative disorders. These three companies illustrate how diversification breadth versus therapeutic focus shapes competitive differentiation in device-assisted keloid management.
| Leading Market Players |
|---|
| Novartis AG |
| Sensus Healthcare |
| Perrigo Company plc |
| Sonoma Pharmaceuticals |
| Bausch Health Companies |
| Candela Medical |
| Lumenis |
| Smith & Nephew plc |
| Cynosure |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up photonics specialists have consolidated optical component sourcing networks across Germany and South Korea, compressing procurement timelines for dermatology clinics while enforcing volume-based pricing discipline on mid-tier laser platform manufacturers.
Pricing Analysis
Distributor margin layers absorb 15-25 points before hospital procurement committees negotiate final terms. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared platforms from CE-marked equivalents and uncertified aesthetic devices. Pricing pressure stems from payer scrutiny of combination therapy cost-effectiveness, narrowing coverage differentials. Independent dermatology practices exhibit highest price sensitivity; tertiary care centers with bundled payment contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with specialized germanium and sapphire suppliers concentrated in Germany, Japan, and the United States. Laser cavity assemblies draw from precision optical foundries in these jurisdictions, while cryotherapy cooling systems rest on compressor component networks anchored in South Korea and China. Tariff exposure on photonics subassemblies creates margin volatility for device producers lacking captive supply. Distribution runs through authorized dealer networks serving dermatology clinic clusters before direct hospital contracting at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The keloid treatment market reads as a late-cycle quality story where recurrence management protocols and adjuvant radiation timing are shifting demand toward premium-certified device platforms with validated clinical outcomes.
For Market Incumbents: Deepen backward integration into optical component supply by acquiring specialized germanium foundries in Germany or Japan, insulating margin from lead time volatility. Expand multi-year service contract penetration in South Korean hospital systems to lock recurring revenue against emerging home-use cryotherapy entrants. Prioritize ISO 13485 certification maintenance as EU MDR documentation burdens extend competitor access timelines. For New Entrants and Emerging Players: Enter via consumer-grade temperature-controlled applicators for early-stage keloid management, exploiting the underdeveloped homecare channel where clinical incumbents lack presence. Target United States metropolitan dermatology clinics with telemedicine-integrated lesion monitoring systems, leveraging reimbursement gaps in rural geographies. Pursue direct-to-consumer positioning with algorithmic treatment planning apps to bypass capital-intensive device manufacturing barriers. For Investors and Strategic Acquirers: Diversified dermatology device manufacturers with established FDA 510(k) clearance track records are the most active acquirer in this space, seeking bolt-on photonics capabilities. Target acquisition archetypes include mid-cap radiation therapy specialists with superficial x-ray platform installed bases and recurring service contract portfolios. Watch for MFDS accelerated approval pathways in South Korea as inflection signal for Asian market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Service Contract Expansion | Captures recurring revenue streams in German hospital procurement systems with centralized purchasing authority. |
| FDA 510(k) Clearance Acceleration | Compresses commercialization timelines versus premarket approval for novel laser wavelength platforms. |
| EU MDR Quality Certification Investment | Creates competitive moats as notified bodies prioritize legacy clinical evidence portfolios. |
| Telemedicine Integration Development | Enables protocol adherence improvements in rural United States geographies with dermatology access gaps. |
| Home-Use Cryotherapy Channel Buildout | Expands addressable settings beyond traditional dermatology clinic infrastructure constraints. |
Study Parameters
Direct dialogue with dermatology clinic operators, hospital purchasing committee members, biomedical engineers at device manufacturers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement coding records, and hospital procurement system contract disclosures. Bottom-up procedure volume estimates and top-down equipment installation counts were triangulated to cross-validate market sizing.
Segment-level outputs across product type, delivery mode, end user channel, and treatment stage were generated through the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle intervals, and protocol adoption curves. Forecast inputs incorporated superficial radiation therapy timing standardization in tertiary care, reimbursement coding evolution for combination therapies, and operator certification program capacity constraints.
Inputs from regulatory filing databases and hospital procurement records were available through the study window; gaps in real-time pricing transparency for multi-year service contracts introduce uncertainty bands around margin estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Folliculitis Market
Dermatology
Dermatological Products Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Darier Disease Drugs Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Australia Skin Laser Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Common Warts Market
Dermatology
Australia Skin Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Scleroderma Treatment Market