
 Americas Medical Rubber and Balloon Product Market | 2026-2036
Americas Medical Rubber and Balloon Product Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Medical Rubber and Balloon Product Market Analysis
US Pharmacopeia Class VI compliance is rotating toward the center of procurement decisions for critical-care balloon products. Abbott Laboratories leverages captive polymer compounding to secure batch-to-batch consistency in silicone balloon membranes. Boston Scientific Corporation anchors its Americas position through vertically integrated catheter assembly lines in Costa Rica and Massachusetts. Medtronic differentiates via proprietary surface treatment technologies that reduce thrombogenicity in angioplasty balloons.
Americas Medical Rubber and Balloon Products encompass elastomeric components manufactured from natural latex, synthetic polyisoprene, silicone rubber, and thermoplastic elastomers, typically formed through dip molding, extrusion, or blow-molding processes to achieve wall thickness tolerances of 0.001–0.005 inches for pressure-rated applications. These components function as inflatable occlusive elements, fluid conduits, and protective barriers in minimally invasive procedures, diagnostic inflation systems, and sterile surgical environments. Silicone balloons command premium positioning in neurovascular and urological applications where biostability and extended dwell times justify higher unit economics. Latex balloons retain volume leadership in diagnostic and short-duration therapeutic uses, though allergen concerns are shifting procurement toward synthetic alternatives in hospital systems. Home healthcare channels represent the fastest-growing distribution vector, driven by outpatient catheterization and enteral feeding protocols that bypass traditional wholesale distributor markups.
FDA 510(k) clearance requirements and USP Class VI biocompatibility standards govern market access for the United States, while Brazil's ANVISA registration pathways and Mexico's COFEPRIS medical device vigilance rules shape commercialization timelines across Latin America. These regulatory frameworks elevate barriers for uncertified manufacturers and concentrate purchasing power among distributors with established quality management systems. Stakeholders must monitor evolving FDA guidance on patient-specific 3D-printed balloon molds and ANVISA's accelerated review track for breakthrough catheter designs.
Market Dynamics
Catheterization laboratories across the Americas are consolidating procurement around USP Class VI-certified silicone balloon membranes, compressing supplier margins for uncertified natural latex alternatives and accelerating backward integration among tier-one device manufacturers.
Growth Catalysts
- FDA 510(k) pathway maturation:Established premarket notification frameworks reduce regulatory uncertainty for catheter innovators, shortening time-to-revenue for balloon dilation devices in interventional cardiology suites.
- Brazil's southeastern hospital corridor:Private healthcare networks in São Paulo and Rio de Janeiro states are modernizing surgical suites, generating concentrated demand for sterile elastomeric barriers and inflation systems.
- Silicone biostability:Extended dwell-time performance in neurovascular applications justifies premium unit economics, pulling procurement away from short-duration latex alternatives in critical-care settings.
Market Restraints
- Medical-grade silicone feedstock concentration:Specialty polymer compounding capacity clusters among a handful of North American chemical suppliers, exposing catheter manufacturers to input cost volatility and allocation risk during supply shocks.
- ANVISA registration timelines:Brazil's national health surveillance agency maintains extended review periods for novel balloon catheter designs, delaying commercialization and tying up working capital for entrants without established quality management systems.
- Synthetic polyisoprene substitution ceiling:Latex allergen concerns drive hospital procurement toward synthetic alternatives, yet polyisoprene exhibits inferior elastic recovery in high-cycle inflation applications, limiting displacement in diagnostic catheter segments.
Strategic Opportunities
- Mexico's COFEPRIS vigilance modernization:Accelerated medical device review tracks for breakthrough catheter designs create first-mover advantages for manufacturers with established regulatory affairs capabilities in Latin America's second-largest market.
- Home healthcare channel expansion:Outpatient catheterization and enteral feeding protocols bypass traditional wholesale distributor markups, enabling direct-to-provider pricing models that capture margin otherwise lost to intermediaries.
- 3D-printed patient-specific balloon molds:Evolving FDA guidance on additive manufacturing for medical devices opens regulatory pathways for customized occlusion geometries in complex anatomical cases, differentiating specialty manufacturers from commoditized volume producers.
Industry Challenges
- Polymer compounding talent scarcity:Batch-to-batch consistency in silicone balloon membranes demands specialized formulation chemists, a skill set concentrated among legacy medical device hubs in Massachusetts and Costa Rica with limited pipeline replenishment.
- Surface treatment IP complexity:Proprietary thrombogenicity-reduction technologies involve overlapping patent estates and trade-secret licensing, creating litigation exposure and royalty stacking for catheter manufacturers developing next-generation angioplasty balloons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Medical Rubber and Balloon Product Market |
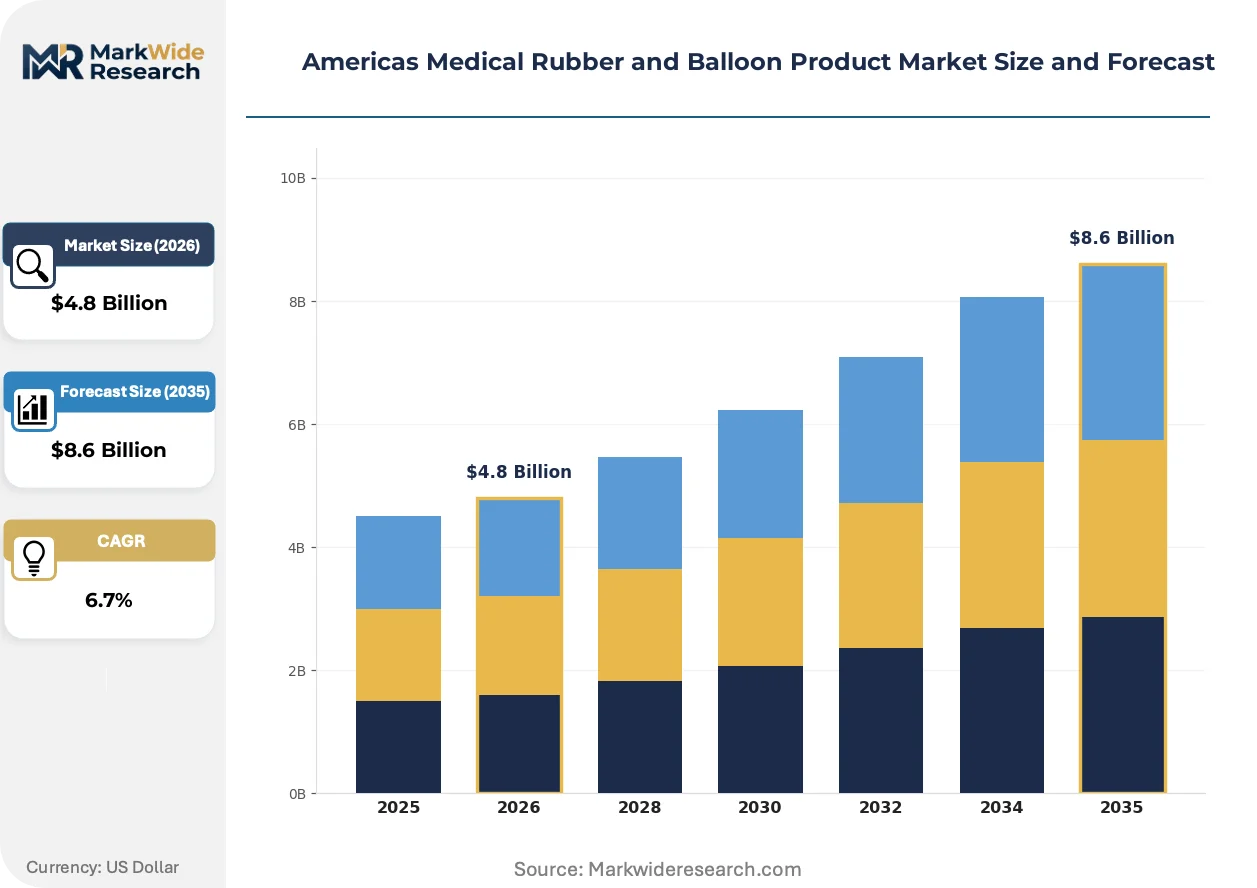
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex Balloons, Silicone Balloons, Rubber Tubing, Medical Gloves Application: Diagnostic Devices, Therapeutic Equipment, Surgical Instruments, Patient Monitoring End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Medical Supply Stores |
| Companies Covered | Cardinal Health, Abbott Laboratories, Boston Scientific Corporation, Medtronic, Johnson & Johnson, B. Braun Melsungen, AngioDynamics, Cordis Corporation, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Medical Rubber and Balloon Product Market Emerging Trajectories
Silicone rubber formulation science and regulatory science are converging to redefine competitive advantage in balloon catheter manufacturing, with biocompatibility certification and additive manufacturing capabilities separating investable suppliers from commodity elastomer processors.
Thermoplastic elastomer blow-molding is fragmenting traditional silicone dip-molding dominance in diagnostic balloon segments. Outpatient clinics and ambulatory surgical centers are adopting TPE-based inflation systems for cost-sensitive short-duration procedures. This material transition is compressing margins for established silicone processors while enabling new entrants with plastics extrusion expertise to capture volume in price-elastic market tiers.
FDA guidance evolution on patient-specific 3D-printed medical devices is tightening documentation requirements for additive manufacturing validation. Catheter manufacturers must demonstrate layer-by-layer process control and post-processing biocompatibility retention for customized balloon molds. Neurovascular and structural heart applications face the steepest compliance ramps, with early filers capturing regulatory exclusivity windows before standardization commoditizes the pathway.
Hospital procurement departments are consolidating vendor panels around integrated catheter-balloon suppliers capable of single-source accountability. Group purchasing organizations in the United States are penalizing fragmented supply chains that require multiple contract negotiations for interventional cardiology kits. This buyer concentration is visible most acutely in the southeastern United States, where health system mergers have collapsed preferred supplier lists from twelve vendors to three in major metropolitan markets.
Americas Medical Rubber and Balloon Product Market Segmentation
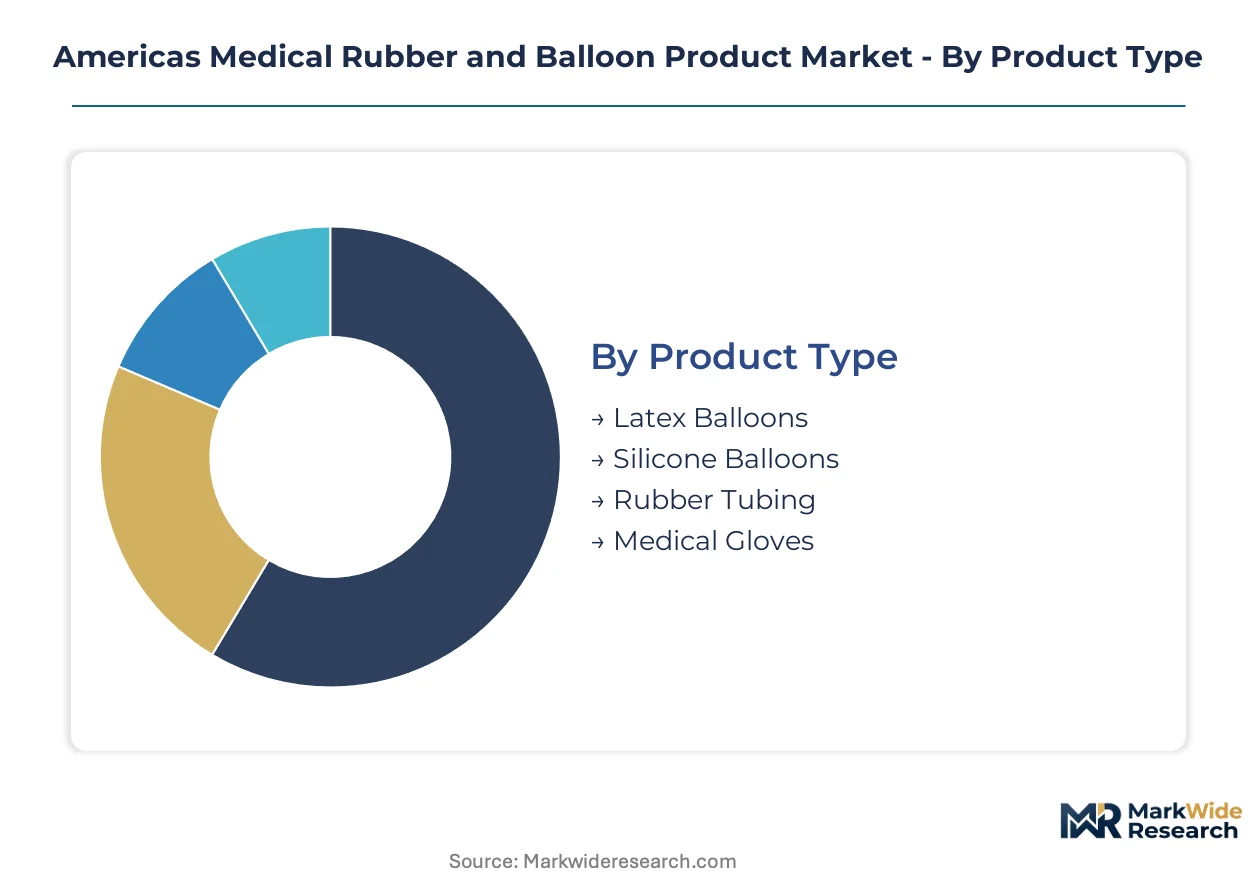
Product differentiation in medical rubber and balloon components hinges on biocompatibility certification tiers and dwell-time performance specifications. Procurement departments across catheterization laboratories and surgical suites segment purchases by material chemistry, clinical application intensity, and regulatory compliance burden rather than unit cost alone.
Product Type:
FDA 510(k) clearance pathways and USP Class VI biocompatibility standards stratify this category into distinct regulatory risk tiers that shape supplier qualification requirements and hospital procurement protocols.
- Silicone Balloons:Manufactured from platinum-cured polydimethylsiloxane with wall thickness tolerances of 0.001–0.003 inches for pressure-rated neurovascular applications. Catheterization laboratories in the United States concentrate purchases here for interventional cardiology suites where extended dwell times and thrombogenicity reduction justify premium positioning.
- Latex Balloons:Dip-molded from natural rubber latex with ammonia-stabilized compounding for diagnostic inflation systems. Brazil's southeastern hospital corridor maintains volume demand despite allergen concerns, though procurement is shifting toward synthetic alternatives in pediatric and immunocompromised patient settings.
- Rubber Tubing:Extruded from synthetic polyisoprene or thermoplastic elastomers for fluid conduit applications in enteral feeding and drainage systems.
- Medical Gloves:Sterile barrier products manufactured through coagulant dipping processes for surgical suite compliance.
Silicone balloons handle the majority of critical-care throughput; rubber tubing is gaining share fastest in home healthcare channels.
Application:
Clinical use intensity determines material specification requirements, with high-cycle therapeutic applications demanding superior elastic recovery and surface treatment technologies.
- Therapeutic Equipment:Angioplasty balloon catheters and occlusion devices requiring proprietary surface treatments to reduce thrombogenicity in structural heart and peripheral vascular interventions. Massachusetts and Costa Rica manufacturing clusters supply these components to integrated catheter assembly lines.
- Diagnostic Devices:Inflation systems for pressure monitoring and contrast media delivery in cardiac catheterization laboratories. Thermoplastic elastomer blow-molding is fragmenting traditional silicone dominance in this cost-sensitive tier.
- Surgical Instruments:Protective barriers and occlusion elements for sterile field maintenance in operating suites.
- Patient Monitoring:Inflation cuffs and pressure transducer interfaces for continuous hemodynamic assessment.
Therapeutic equipment commands the steepest compliance ramps; diagnostic devices are expanding most quickly in ambulatory surgical centers.
End User:
Facility type dictates purchasing consolidation patterns, with integrated health systems leveraging group purchasing organization leverage against fragmented clinic procurement.
- Hospitals:Comprehensive surgical and interventional cardiology departments with consolidated vendor panels around single-source catheter-balloon suppliers. Southeastern United States health system mergers have collapsed preferred supplier lists from twelve vendors to three in major metropolitan markets.
- Home Healthcare:Outpatient catheterization and enteral feeding protocols bypassing traditional wholesale distributor markups through direct-to-provider pricing models. This channel captures margin otherwise lost to intermediaries and represents the steepest expansion trajectory in distribution evolution.
- Ambulatory Surgical Centers:Cost-sensitive short-duration procedure facilities adopting TPE-based inflation systems.
- Clinics:Diagnostic and minor procedure settings with decentralized procurement authority.
Hospitals anchor procurement volume concentration; home healthcare is climbing the fastest on share gains.
Distribution Channel:
Channel selection reflects customer scale and regulatory documentation requirements, with complex catheter kits demanding direct manufacturer relationships.
- Direct Sales:Manufacturer-to-provider relationships for custom silicone balloon specifications and batch-to-batch consistency guarantees. Abbott Laboratories and Boston Scientific Corporation leverage captive polymer compounding and vertically integrated assembly to secure these accounts.
- Wholesale Distributors:Traditional intermediaries serving smaller clinics and non-integrated hospital systems with standardized latex and TPE products.
- Online Retail:E-commerce platforms for home healthcare consumables and replacement catheter supplies.
- Medical Supply Stores:Local distribution for emergency replenishment and small-volume clinic purchases.
Direct sales handles the majority of high-value catheter throughput; online retail is the fastest mover on share in home healthcare segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica exports catheter assembly components to United States catheterization laboratories, while Massachusetts compounds silicone polymers for balloon membrane production. This trade corridor channels Latin American manufacturing precision into North American interventional cardiology demand.
United States
Catheterization laboratories in the Southeast and Northeast corridor concentrate procurement of silicone balloon catheters for interventional cardiology. FDA 510(k) premarket notification pathways govern device clearance, elevating compliance costs for new entrants without established quality management systems. Boston Scientific Corporation anchors vertically integrated assembly lines in Massachusetts, securing batch-to-batch consistency in silicone balloon membranes through captive polymer compounding.
Brazil
Private healthcare networks in São Paulo and Rio de Janeiro states are modernizing surgical suites, generating concentrated demand for sterile elastomeric barriers. ANVISA registration timelines extend review periods for novel balloon catheter designs, delaying commercialization for entrants without regulatory affairs capabilities. The southeastern hospital corridor drives procurement volume despite extended working capital tie-ups during agency review.
Mexico
Costa Rican catheter assembly operations supply Mexican healthcare distributors serving border-state hospitals and central Mexico medical centers. COFEPRIS medical device vigilance rules shape commercialization timelines, though accelerated review tracks for breakthrough catheter designs create first-mover advantages. Manufacturing clusters in the Bajío Region assemble components for export to United States hospital systems.
Canada
Health Canada and PMRA oversight applies to imported balloon catheter devices distributed through provincial healthcare procurement systems. Ontario and Quebec health authorities consolidate vendor panels around USP Class VI-certified suppliers, mirroring United States procurement patterns. Toronto and Montreal hospital networks source silicone balloon membranes from Massachusetts and Costa Rica manufacturing hubs.
Americas Medical Rubber and Balloon Product Market Vendor Landscape
Listed leaders compete with private specialists across regulatory certification tiers, creating a tiered structure where public company scale advantages clash with private firm agility in niche catheter segments. The market concentrates among integrated device manufacturers with captive polymer compounding capabilities, while smaller elastomer processors serve cost-sensitive diagnostic tiers. Three archetypes dominate: vertically integrated giants with global assembly networks, regional specialists in latex and synthetic alternatives, and contract manufacturers serving private-label hospital brands. Competitive moves center on backward integration into polymer compounding and strategic partnerships with 3D-printing service bureaus for patient-specific mold production.
Among United States-based listed manufacturers, Abbott Laboratories, Boston Scientific Corporation, and Medtronic occupy positions as archetype representatives of vertically integrated scale. Abbott exemplifies captive polymer compounding strategy through in-house silicone membrane production. Boston Scientific anchors Americas positioning through dual-hemisphere assembly presence. Medtronic represents proprietary surface treatment differentiation in thrombogenicity-reduction technologies. These three listed entities sit within the premium-tier procurement channel that hospital group purchasing organizations favor for single-source accountability.
| Leading Market Players |
|---|
| Cardinal Health |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen |
| AngioDynamics |
| Cordis Corporation |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
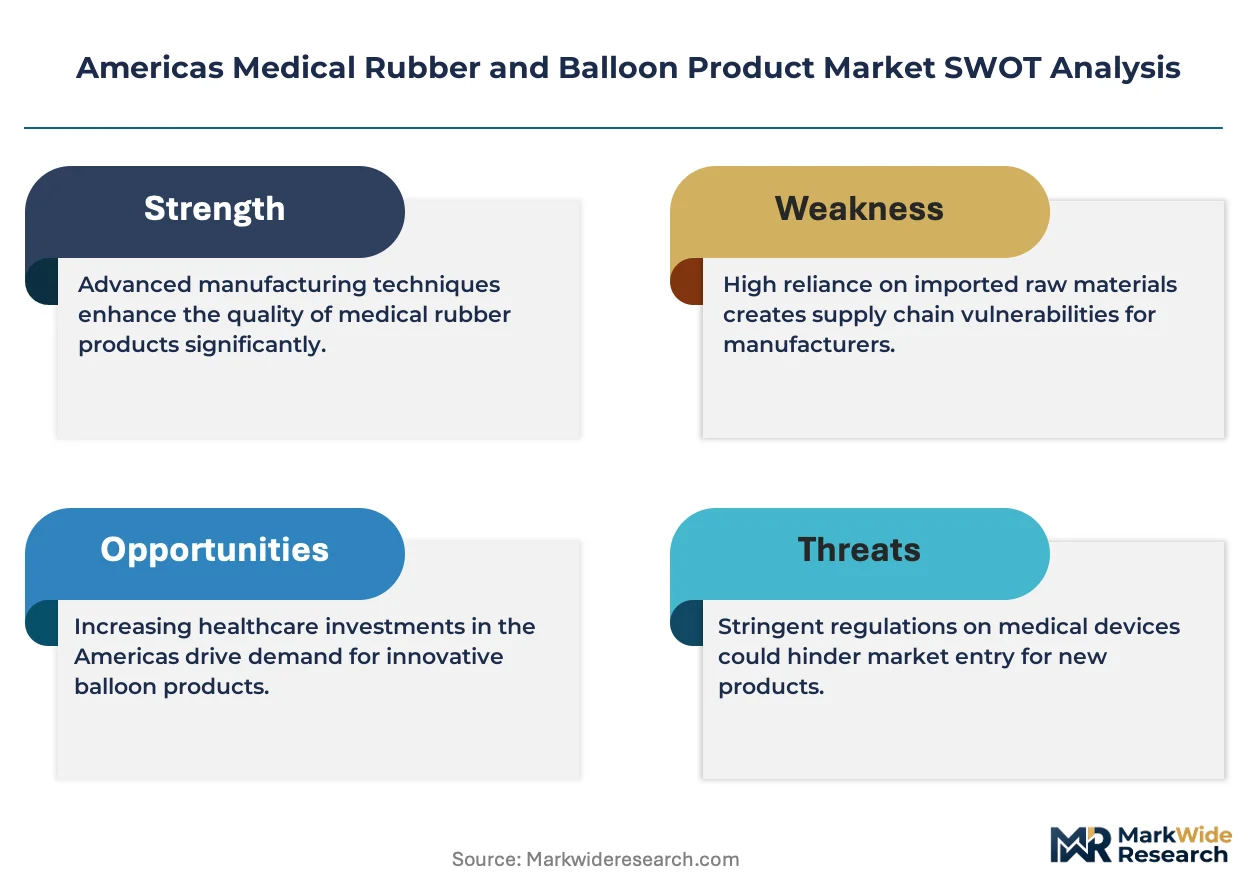
FDA 510(k) clearance pathways and USP Class VI biocompatibility standards gate both supplier qualification and price differentiation across silicone balloon catheter procurement. Certification burdens compress margins for uncertified latex processors while enabling premium capture among integrated device manufacturers with captive polymer compounding capabilities.
Pricing Analysis
Hospital group purchasing organizations anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on USP Class VI certification grade and volume scale commitments, with integrated manufacturers commanding premium positioning through batch-to-batch consistency guarantees. Cost compression in diagnostic TPE balloon segments is intensifying because thermoplastic elastomer blow-molding enables plastics extrusion specialists to undercut silicone processors. Ambulatory surgical centers exhibit highest price sensitivity; neurovascular catheterization laboratories show lowest.
Supply Chain Analysis
Medical-grade silicone feedstock concentration in Massachusetts and Costa Rica manufacturing clusters underwrites supply vulnerability for catheter assembly operations. Specialty polymer compounding draws from platinum-cured polydimethylsiloxane, synthetic polyisoprene, and thermoplastic elastomer inputs. Single-source vulnerability runs through North American chemical suppliers during allocation shocks. Distribution runs through direct manufacturer relationships for custom specifications and wholesale distributors for standardized latex products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home healthcare channel expansion signals early-cycle penetration opportunity for outpatient catheterization and enteral feeding protocols bypassing traditional distributor markups.
For Market Incumbents: Shield proprietary surface treatment IP estates through aggressive patent enforcement against emerging contract manufacturers developing thrombogenicity-reduction alternatives. Deepen backward integration into silicone polymer compounding to secure batch-to-batch consistency guarantees that hospital GPOs demand for single-source accountability.
For New Entrants and Emerging Players: Regulatory affairs capabilities in Mexico's COFEPRIS accelerated review track represent the most penetrable white-space target for breakthrough catheter designs. Target Brazil's southeastern hospital corridor through ANVISA registration partnerships with established quality management system holders. Pursue direct-to-provider pricing models in home healthcare channels to capture margin lost to wholesale intermediaries.
For Investors and Strategic Acquirers: Evolving FDA guidance on patient-specific 3D-printed balloon molds reshapes the acquisition landscape toward additive manufacturing validation capabilities. Five-to-ten-year viability favors contract manufacturers with layer-by-layer process control expertise serving neurovascular applications. Watch ANVISA registration timeline compression as inflection signal for Brazil market access premium.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | 510(k) clearance reduces regulatory uncertainty for balloon dilation devices in interventional cardiology suites. |
| USP Class VI Certification Investment | Class VI biocompatibility gates procurement decisions in critical-care balloon product segments. |
| Hospital System Partnership | GPO consolidation around single-source suppliers collapses vendor panels from twelve to three in major markets. |
| Backward Integration into Polymer Compounding | Captive silicone membrane production secures batch-to-batch consistency for premium catheter positioning. |
| 3D-Printed Mold Capability Development | Additive manufacturing validation opens regulatory pathways for customized occlusion geometries in complex anatomical cases. |
Methodological Framework
Desk research of FDA 510(k) filings, ANVISA registration databases, hospital procurement contracts, and trade customs data preceded structured interviews with catheterization laboratory directors, biomedical engineers, GPO contracts managers, and polymer compounding specialists. Bottom-up demand modeling across product type, application, end user, and distribution channel segments was cross-validated against top-down market sizing from manufacturer revenue disclosures and import-export trade flows.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in silicone versus latex versus TPE material tiers. Modeled segmentation spans material chemistry, clinical application intensity, facility type, and channel structure. CAGRs were derived from weighted average of historical trajectory and forward-looking penetration assumptions for home healthcare channels and patient-specific 3D-printed mold adoption.
Forecasts assume regulatory continuity in FDA 510(k) pathways, ANVISA registration timelines, and COFEPRIS vigilance rules; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as FDA additive manufacturing guidance and ANVISA accelerated review track implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Medical Gas Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Children's Antipyretic Patch Market