
 India Cardiovascular Devices Market | 2026-2036
India Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Cardiovascular Devices Market Foresight
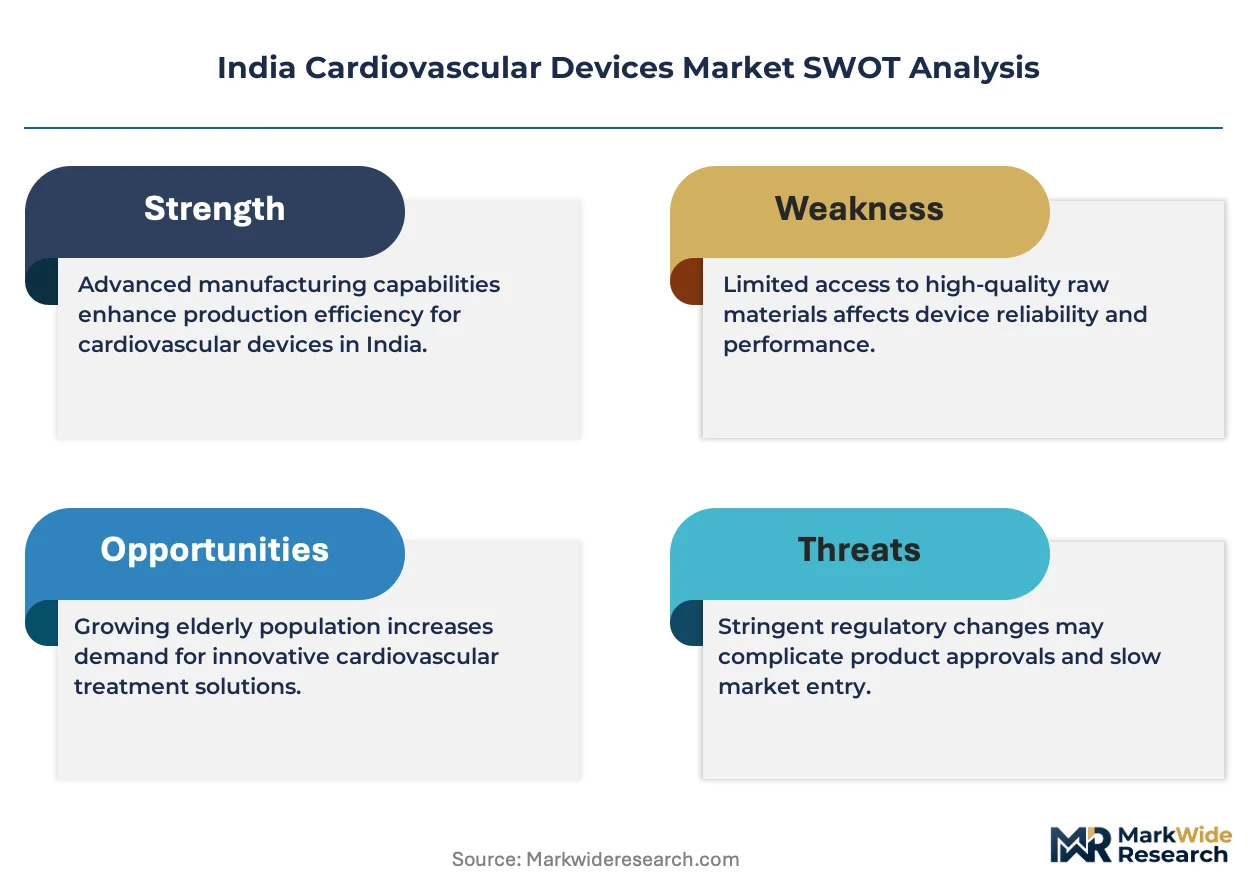
The capability gap between multinational capital reserves and domestic R&D scale is collapsing as Sahajanand Medical Technologies leverages in-house stent manufacturing to compete on price. Medtronic PLC sustains technology leadership through its pacemaker and catheter portfolio. Abbott Laboratories anchors premium positioning with drug-eluting stent platforms across major Indian cities.
Cardiovascular devices encompass implantable and interventional instruments—stents, catheters, pacemakers, and valves—typically fabricated from nitinol, cobalt-chromium, or biocompatible polymers and engineered for hemodynamic compatibility under pulsatile blood flow conditions. These devices restore or augment cardiac function in coronary artery disease, structural heart defects, and rhythm disorders. Stents and catheters dominate current volume, while bioabsorbable technology captures expanding margin pools as interventional cardiologists seek reduced long-term complication profiles. Hospitals and cardiac centers absorb the bulk of procurement spend, though specialty clinics are gaining traction for arrhythmia diagnostics and follow-up interventions.
CDSCO regulates medical device safety and efficacy under the Drugs and Cosmetics Act, while BIS mandates conformance to Indian standards for electrical safety and material biocompatibility. The PLI scheme for medical devices is redirecting capital toward domestic manufacturing of high-value cardiovascular components, reshaping supplier economics. Stakeholders must weigh local production incentives against the technology transfer timelines required to match imported device performance benchmarks.
Market Dynamics
CDSCO's streamlined approval pathways under the Medical Device Rules are compressing time-to-market for stent manufacturers, while tier-2 and tier-3 city hospitals accelerate catheterization lab expansion faster than established metro centers.
Growth Catalysts
- PLI scheme for medical devices:Production-linked incentives redirect domestic capital toward high-value cardiovascular component manufacturing, lowering import dependency for critical stent platforms.
- Tier-2 city hospital expansion:Cardiac catheterization lab capacity in secondary cities is scaling faster than metro infrastructure, generating procurement volume outside traditional Maharashtra-Karnataka-Tamil Nadu clusters.
- Bioabsorbable stent technology:Interventional cardiologists are migrating toward polymer-based scaffolds that eliminate long-term metal retention complications, expanding addressable patient pools.
Market Restraints
- Cobalt-chromium alloy supply concentration:Specialty metal feedstock for drug-eluting stents remains import-dependent, exposing margins to currency volatility and geopolitical supply interruptions.
- CDSCO technical documentation requirements:Biocompatibility testing protocols for nitinol-based devices create extended validation timelines that delay commercialization of next-generation platforms.
- Balloon angioplasty substitution:Cost-conscious government hospital procurement committees continue favoring plain balloon interventions over stent deployment in stable coronary lesions.
Strategic Opportunities
- Uttar Pradesh and Bihar cardiac centers:Underpenetrated northern states with rising ischemic heart disease burden present greenfield catheterization lab deployment opportunities.
- Remote cardiac monitoring integration:Convergence of implantable pacemakers with cloud-based arrhythmia detection platforms enables post-intervention revenue streams beyond device sale.
- Ayushman Bharat reimbursement expansion:Government health scheme coverage for percutaneous coronary intervention procedures is widening addressable patient demographics beyond private-pay segments.
Industry Challenges
- Interventional cardiology specialist scarcity:Trained operator availability limits catheterization lab utilization rates in tier-3 cities where infrastructure investment has outpaced workforce development.
- BIS electrical safety certification timelines:Pacemaker and implantable cardioverter-defibrillator platforms face extended conformity assessment periods that compress product launch windows against competitor entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cardiovascular Devices Market |
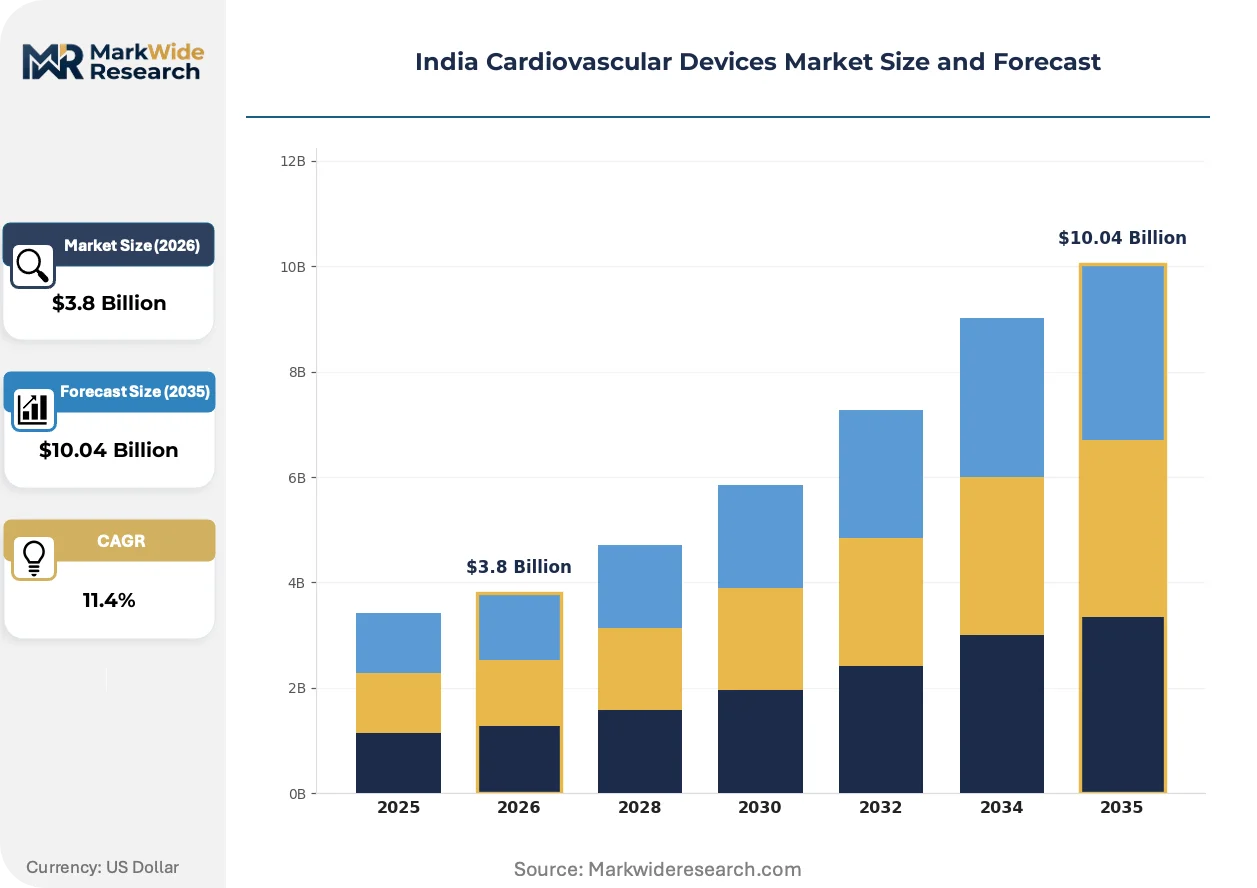
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Pacemakers, Valves Technology: Bioabsorbable, Drug-Eluting, Mechanical, Hybrid End User: Hospitals, Cardiac Centers, Specialty Clinics, Outpatient Facilities Application: Coronary Artery Disease, Heart Failure, Arrhythmias, Structural Heart Disease |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Boston Scientific Corporation, Terumo Corporation, W. L. Gore & Associates, Edward Lifesciences Corporation, Sahajanand Medical Technologies Limited, Meril Life Science, Opto Circuits (India) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cardiovascular Devices Market Shifts & Advancements
Bioabsorbable polymer technology and digital cardiac monitoring integration are compressing traditional metal stent dominance while reshaping post-intervention care economics across Indian hospital networks.
Drug-eluting stents with biodegradable polymer coatings are displacing durable polymer platforms in premium hospital segments. Interventional cardiologists at Apollo, Fortis, and Narayana Health chains are adopting these scaffolds for diabetic and complex lesion cases where long-term endothelial healing determines outcomes. This transition is compressing margin pools for conventional cobalt-chromium bare metal stent manufacturers while elevating procurement specifications toward hemodynamic performance metrics.
CDSCO's risk-based classification system under the Medical Device Rules is accelerating market access for Class C and D cardiovascular implants. The regulator's parallel review track for devices with prior US FDA or EU MDR approval compresses technical documentation burdens by 40-60 days for qualifying submissions. Domestic manufacturers with BIS-certified quality management systems are leveraging this pathway to challenge multinational incumbents in drug-eluting stent tenders at government medical colleges.
Hospital procurement committees are unbundling device supply from procedure-based reimbursement contracts. Cardiac centers in Tamil Nadu and Karnataka are negotiating direct manufacturer relationships for stent inventory, bypassing traditional distributor markups that previously captured 12-18% of landed cost. This disintermediation is most visible in corporate hospital chains where centralized purchasing aggregates volume across multi-state networks, forcing legacy distribution channels toward logistics-only service models.
India Cardiovascular Devices Market Segmentation
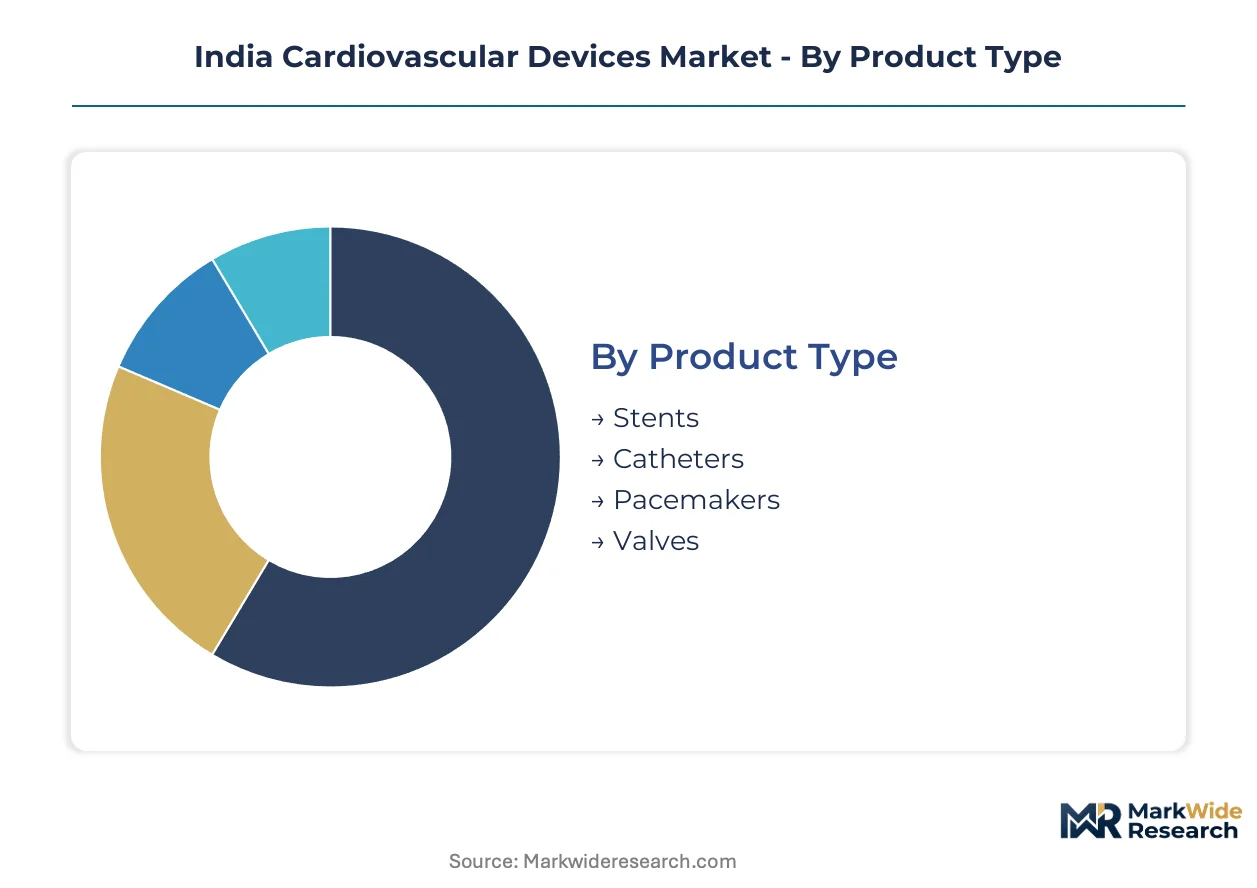
Segmentation in India's cardiovascular device market reveals how CDSCO risk classifications and PLI scheme incentives reshape procurement patterns across product categories. Understanding these divisions exposes where domestic manufacturing investments concentrate versus import-dependent segments.
Product Type:
CDSCO's Class C and D risk classifications apply differential technical documentation burdens across implantable versus interventional categories, directly affecting time-to-market economics for domestic versus imported platforms.
- Stents:Fabricated from nitinol, cobalt-chromium, or bioresorbable polymers and deployed via catheter-based delivery systems to scaffold coronary lesions. Maharashtra, Karnataka, and Tamil Nadu hospital chains anchor procurement volumes as tier-2 cities accelerate catheterization lab expansion.
- Catheters:Diagnostic and interventional catheters manufactured from biocompatible polymers with radiopaque markers for fluoroscopic guidance. Government medical colleges in northern states favor cost-optimized balloon catheters over premium guiding catheters under Ayushman Bharat reimbursement constraints.
- Pacemakers:Implantable pulse generators with lithium-iodine batteries and transvenous leads for rhythm management.
- Valves:Surgical and transcatheter heart valve replacements addressing structural defects.
Stents handle the majority of throughput; bioabsorbable variants within this category are expanding most quickly on share as interventional cardiologists migrate from durable polymer platforms.
Technology:
Cost tiers separate premium bioabsorbable platforms from economy mechanical alternatives, with reimbursement policy determining which technology strata penetrate government versus private hospital procurement.
- Bioabsorbable:Polymer-based scaffolds that fully resorb within 24-36 months, eliminating long-term metal retention and enabling restored vasomotion. Apollo, Fortis, and Narayana Health chains in metro markets drive adoption for diabetic patients requiring enhanced endothelial healing profiles.
- Drug-Eluting:Metal stents with polymer coatings delivering antiproliferative agents to suppress neointimal hyperplasia. Tier-2 city hospitals expanding cardiac catheterization capacity source these as standard-of-care for complex lesions, balancing efficacy against bioabsorbable price premiums.
- Mechanical:Bare metal and balloon-expandable platforms without pharmacological coatings.
- Hybrid:Combined mechanical-drug delivery architectures with specialized surface engineering.
Drug-eluting technology commands the dominant revenue position; bioabsorbable platforms are gaining share fastest as CDSCO parallel review tracks accelerate market access for prior-approved devices.
End User:
Procurement concentration varies by facility scale, with corporate hospital chains leveraging centralized purchasing to disintermediate traditional distributor networks.
- Hospitals:Multi-specialty institutions with dedicated cardiac catheterization laboratories performing percutaneous coronary intervention and structural procedures. Tier-2 and tier-3 city hospitals are scaling capacity faster than metro infrastructure, generating volume outside traditional Maharashtra-Karnataka-Tamil Nadu clusters.
- Cardiac Centers:Dedicated cardiovascular facilities with hybrid operating rooms and electrophysiology suites. These centers absorb premium device procurement for complex arrhythmia and structural heart interventions.
- Specialty Clinics:Focused outpatient facilities for diagnostic catheterization and follow-up monitoring.
- Outpatient Facilities:Ambulatory settings for same-day diagnostic and minor interventional procedures.
Hospitals manage the bulk of device throughput; cardiac centers are climbing the fastest as specialist concentration and procedure complexity drive referral consolidation.
Application:
Geographic disease burden patterns shape demand, with ischemic heart disease prevalence in northern states creating greenfield expansion opportunities.
- Coronary Artery Disease:Atherosclerotic plaque accumulation requiring revascularization via stent deployment or bypass surgery. Uttar Pradesh and Bihar present underpenetrated markets where rising ischemic burden meets limited existing catheterization infrastructure.
- Heart Failure:Progressive pump dysfunction addressed through cardiac resynchronization therapy and ventricular assist devices. Government medical colleges in southern states anchor procurement for device-based heart failure management under expanding public health scheme coverage.
- Arrhythmias:Electrical conduction disorders treated with pacemakers, implantable cardioverter-defibrillators, and ablation systems.
- Structural Heart Disease:Congenital and acquired valve defects requiring surgical or transcatheter intervention.
Coronary artery disease applications dominate procedure volumes; structural heart disease interventions are expanding most rapidly as transcatheter techniques displace open surgery in aging patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Maharashtra and Karnataka commands premium procurement terms, while Uttar Pradesh and Bihar operate under cost-constrained government reimbursement schedules that compress margins for identical stent platforms.
Maharashtra
Private hospital chains in Mumbai and Pune drive procurement volumes for drug-eluting and bioabsorbable stent platforms. CDSCO's parallel review track accelerates market access for devices with prior US FDA approval. The Mumbai-Pune corridor anchors catheterization lab density, with corporate hospitals centralizing purchasing across multi-state networks.
Karnataka
Bangalore's cardiac centers absorb premium device procurement for complex arrhythmia and structural heart interventions. The state's medical device manufacturing clusters benefit from PLI scheme incentives redirecting capital toward domestic stent production. Bangalore and Mysore host expanding catheterization capacity as tier-2 city hospitals scale faster than metro infrastructure.
Tamil Nadu
Chennai-based government medical colleges anchor procurement for device-based heart failure management under expanding Ayushman Bharat coverage. BIS electrical safety certification requirements extend timelines for pacemaker commercialization. The Chennai-Coimbatore belt concentrates cardiac center density, with specialty clinics gaining traction for diagnostic catheterization.
Uttar Pradesh
Rising ischemic heart disease burden meets limited existing catheterization infrastructure, creating greenfield deployment opportunities. Government hospital procurement committees favor plain balloon interventions over stent deployment under cost-conscious reimbursement constraints. Lucknow and Kanpur emerge as focal points for cardiac center expansion as private operators target underpenetrated northern markets.
Bihar
Underpenetrated patient pools with coronary artery disease prevalence drive demand for basic stent and catheter platforms. CDSCO technical documentation requirements for nitinol-based devices delay validation of next-generation platforms. Patna anchors emerging cardiac infrastructure as regional medical colleges expand intervention capabilities.
India Cardiovascular Devices Market Competitive Landscape
Concentration sits with multinational technology leaders, though domestic manufacturers are compressing price premiums through in-house production scale. The market structure tiers across premium technology providers, mid-scale domestic fabricators, and cost-optimized local suppliers. Strategic archetypes include technology licensors maintaining patent-protected platforms, vertically integrated domestic champions, and distribution-focused regional assemblers. Competitive moves center on direct hospital contracting to disintermediate distributor markups and PLI scheme qualification to capture domestic manufacturing incentives.
Among multinational technology providers, Abbott Laboratories and Medtronic PLC exemplify premium-tier positioning through pacemaker and drug-eluting stent portfolios. Sahajanand Medical Technologies Limited occupies a position within the domestic champion archetype, leveraging in-house manufacturing to compete on price against imported platforms. These three anchors illustrate the competitive tension between technology leadership and cost optimization reshaping procurement patterns across Indian hospital networks.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Boston Scientific Corporation |
| Terumo Corporation |
| W. L. Gore & Associates |
| Edward Lifesciences Corporation |
| Sahajanand Medical Technologies Limited |
| Meril Life Science |
| Opto Circuits (India) Ltd. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day cobalt-chromium alloy lead times from European specialty metal suppliers compress margin buffers for domestic stent manufacturers while amplifying pricing power for integrated multinationals with captive inventory positions. CDSCO's parallel review track shortens regulatory lead times but cannot offset raw material delivery volatility, forcing procurement committees at Apollo and Fortis chains to stockpile premium drug-eluting platforms ahead of anticipated price movements.
Pricing Analysis
The customization-premium spread between patient-specific bioabsorbable scaffolds and standard cobalt-chromium drug-eluting stents reaches three-to-one in Mumbai and Bangalore cardiac centers. Three-tier pricing structure across premium, standard, and economy levels separates Apollo-Fortis-Narayana procurement from government medical college tenders and Ayushman Bharat-reimbursed procedures. Price compression stems from Sahajanand Medical Technologies' in-house nitinol fabrication challenging Abbott's import-dependent cost structure. Government hospital procurement committees in Uttar Pradesh and Bihar exhibit highest price sensitivity, deferring to plain balloon interventions.
Supply Chain Analysis
Port congestion at Nhava Sheva and Mundra extends inbound logistics costs for nitinol wire and cobalt-chromium tubing sourced from Germany, Belgium, and the United States. Domestic manufacturing draws from Japanese polymer feedstock for bioabsorbable scaffolds and Swiss precision machining equipment for catheter delivery systems. Single-source vulnerability concentrates in specialty alloy smelters supplying Medtronic's pacemaker electrode materials. Distribution runs through disintermediated direct manufacturer relationships with corporate hospital chains, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CDSCO's risk-based classification acceleration constitutes a regulatory inflection compressing multinational incumbents' historical time-to-market advantage and enabling domestic champions to capture tier-2 city expansion volume.
For Market Incumbents: Secure catheterization lab supply contracts through exclusive device-procedure bundling at Narayana Health and Fortis chains before PLI-qualified domestic competitors achieve BIS certification parity. Anchor technology leadership in bioabsorbable polymer platforms where patent-protected formulations resist price erosion. Vertical integration into cobalt-chromium alloy recycling mitigates European supply concentration risk.
For New Entrants and Emerging Players: CDSCO's parallel review track for prior US FDA-approved devices offers fastest market access for tier-2 city hospital tenders. Target Uttar Pradesh and Bihar greenfield cardiac center deployments where procurement committees prioritize cost-optimized drug-eluting stents over premium bioabsorbable platforms. Pursue direct contracting relationships with government medical colleges under expanding Ayushman Bharat reimbursement coverage.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational medtech parents divesting non-core pacemaker or structural heart portfolios to focus on high-margin bioabsorbable stent platforms. Long-term viability centers on domestic manufacturing scale qualifying for PLI scheme incentives and BIS certification enabling government tender participation. Monitor CDSCO approval velocity for imported devices as signal of competitive intensity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Parallel Review Track Utilization | Compresses time-to-market for prior US FDA-approved stent platforms by 40-60 days. |
| PLI Scheme Qualification | Redirects capital toward domestic nitinol and polymer scaffold manufacturing, lowering import dependency. |
| Direct Hospital System Partnership | Disintermediates distributor markups, capturing 12-18% cost savings for corporate chain procurement. |
| Bioabsorbable Technology Investment | Positions manufacturers for premium pricing at Apollo and Fortis chains treating diabetic lesion cases. |
| Ayushman Bharat Reimbursement Strategy | Expands addressable patient pools beyond private-pay segments into government hospital procurement. |
Research Methodology
Cross-validation between hospital procurement database analysis and CDSCO regulatory filing review anchors the qualitative findings on competitive positioning. Primary interviews with interventional cardiologists, biomedical engineers at government medical colleges, GPO contracts managers, and catheterization lab directors combined with secondary validation from CDSCO device approval records, BIS certification registries, and PLI scheme beneficiary disclosures. Bottom-up stent volume modeling and top-down cardiovascular procedure incidence triangulation establish market size boundaries.
Sensitivity analysis around cobalt-chromium alloy price volatility and CDSCO approval timeline assumptions tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user facility scale, and application category. CAGRs derive from procedure volume elasticity to cardiac catheterization lab expansion rates and reimbursement policy shifts. Industry-specific inputs incorporate tier-2 city hospital infrastructure investment pipelines and interventional cardiology specialist workforce growth trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained PLI scheme funding and stable CDSCO regulatory velocity; material deviation would warrant model refresh. Specific risk factors include cobalt-chromium supply disruption from European smelter consolidation and BIS electrical safety certification delays for next-generation pacemaker platforms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market