
 Measured Volume Burette Set Market | 2026-2036
Measured Volume Burette Set Market Size, Share, and Industry Trends Forecast 2026-2036
Measured Volume Burette Set Market Intelligence
Aftermarket calibration and recertification revenue is fragmenting across regional service networks, pulling margin pools away from original equipment transactions. B. Braun leverages its European manufacturing footprint to sustain direct hospital channel control. Fresenius Kabi anchors institutional procurement contracts across South Asian diagnostic chains. Thermo Fisher differentiates through digital burette integration with laboratory information management systems.
A measured volume burette set is a precision liquid-dispensing apparatus comprising a graduated cylindrical tube with a stopcock valve, typically manufactured from borosilicate glass or inert fluoropolymer, designed to deliver variable but quantified volumes of reagent during analytical procedures. The device serves primary commercial purpose in quantitative chemical analysis, pharmaceutical assay verification, and educational titration protocols where volumetric accuracy directly determines experimental validity. Glass burettes retain dominant share in analytical-grade applications where thermal stability and chemical inertness justify premium positioning, while polypropylene variants gain traction in educational and high-throughput screening environments where cost efficiency and breakage resistance outweigh extreme precision requirements. Digital burettes command concentrated margin pools in automated laboratory workflows, though manual types persist across budget-constrained institutional buyers.
FDA 21 CFR Part 820 quality system regulations and ISO 8655 piston-operated volumetric apparatus standards shape product design, calibration protocols, and market access requirements for manufacturers serving North American and European buyers. India's CDSCO Medical Device Rules 2017, harmonized with IMDRF risk classification frameworks, impose incremental conformity assessment burdens on imported burette sets destined for clinical diagnostic use. China's NMPA and Japan's PMDA maintain divergent volumetric accuracy tolerance specifications that complicate unified product platform strategies. Stakeholders must monitor evolving harmonization negotiations between ISO and national pharmacopeia committees to anticipate whether unified tolerance standards will consolidate testing requirements or perpetuate regional certification fragmentation.
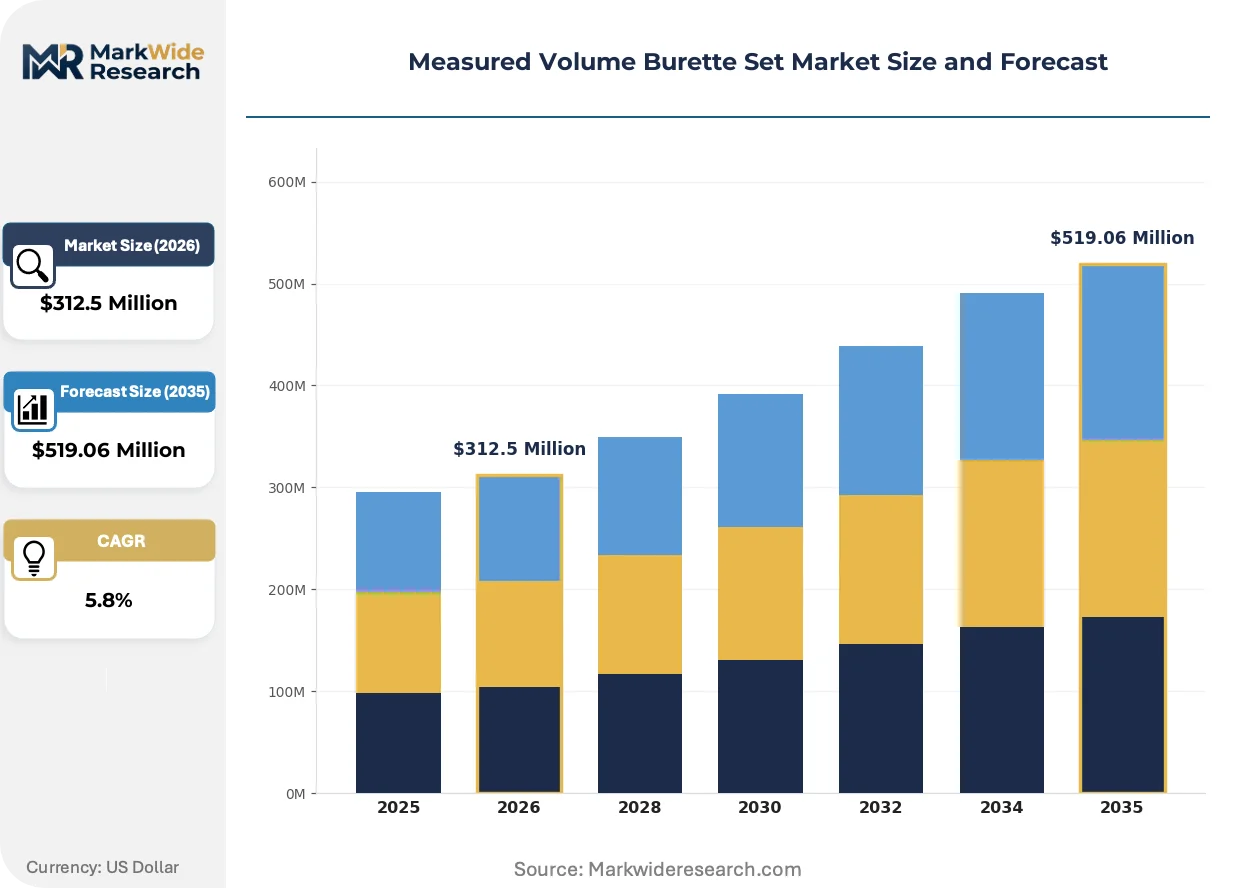
Market Dynamics
Calibration protocol fragmentation is splitting margin pools between original equipment manufacturers and regional service networks, forcing producers to defend channel control through direct hospital contracting or risk disintermediation in aftermarket revenue streams.
Growth Catalysts
- CDSCO Medical Device Rules 2017:Harmonization with IMDRF risk classification frameworks in India is expanding formal procurement channels for calibrated burette sets in pharmaceutical quality control laboratories.
- Digital burette integration:Laboratory information management system connectivity is creating new specification requirements in automated analytical workflows.
- German chemical titration demand:Premium glass burette procurement sustains volume in European analytical-grade applications where thermal stability justifies higher unit economics.
Market Restraints
- Borosilicate glass supply concentration:Specialty glass manufacturing clusters in Central Europe create single-source vulnerability for analytical-grade tube production.
- Divergent national pharmacopeia tolerances:China's NMPA and Japan's PMDA maintain incompatible volumetric accuracy specifications that prevent unified product platform strategies.
- Polypropylene substitution ceiling:Educational and screening applications accept lower precision, compressing addressable margin in volume segments.
Strategic Opportunities
- ISO 8655 harmonization negotiations:Pending convergence between ISO and national pharmacopeia committees could consolidate testing requirements and reduce certification duplication costs.
- South Asian diagnostic chain consolidation:Institutional procurement contract centralization creates volume aggregation points for direct manufacturer relationships.
- Fluoropolymer material advancement:Inert polymer formulations are opening clinical diagnostic applications previously reserved for glass construction.
Industry Challenges
- Metrology technician scarcity:Piston-operated volumetric apparatus calibration requires specialized training that outpaces educational pipeline output in emerging markets.
- Legacy manual burette integration:Budget-constrained institutional buyers resist digital workflow transitions, fragmenting product development priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Measured Volume Burette Set Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Burettes, Automatic Burettes, Digital Burettes, Glass Burettes Material: Glass, Plastic, Polypropylene, Fluoropolymer Application: Chemical Analysis, Titration, Laboratory Experiments, Educational Purposes Volume Capacity: 25ml, 50ml, 100ml, 250ml |
| Companies Covered | PL Medical, Agniplast, B. Braun, Merck, Globalmedikit, Baxter International, Wellmed International Industries Pvt. Ltd., Fresenius Kabi, Thermo Fisher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Measured Volume Burette Set Market Strategic Shifts & Innovations
Digital connectivity and material science advances are restructuring how volumetric accuracy is verified, delivered, and monetized across laboratory workflows.
Cloud-connected digital burettes with embedded gravimetric verification are virtualizing the traditional calibration service model. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these systems at accelerated replacement cycles. This technology is virtualizing aftermarket revenue streams by shifting margin from periodic third-party recertification to embedded software subscription architectures.
REACH substance restriction proposals targeting boron compounds are forcing reformulation timelines for borosilicate glass alternatives. European manufacturers face incremental raw material qualification burdens that extend new product introduction cycles by twelve to eighteen months. Analytical-grade glass burette suppliers are responding with accelerated fluoropolymer pilot programs to preserve market access under anticipated restriction scenarios.
Diagnostic chain procurement centralization is compressing vendor count in South Asian markets. Institutional buyers in India are consolidating measured volume burette specifications across multi-site networks, displacing fragmented distributor relationships with direct manufacturer contracts. This pattern is most visible in Mumbai and Bangalore diagnostic laboratory clusters where CDSCO compliance documentation has become a mandatory bid qualification threshold.
Measured Volume Burette Set Market Segmentation
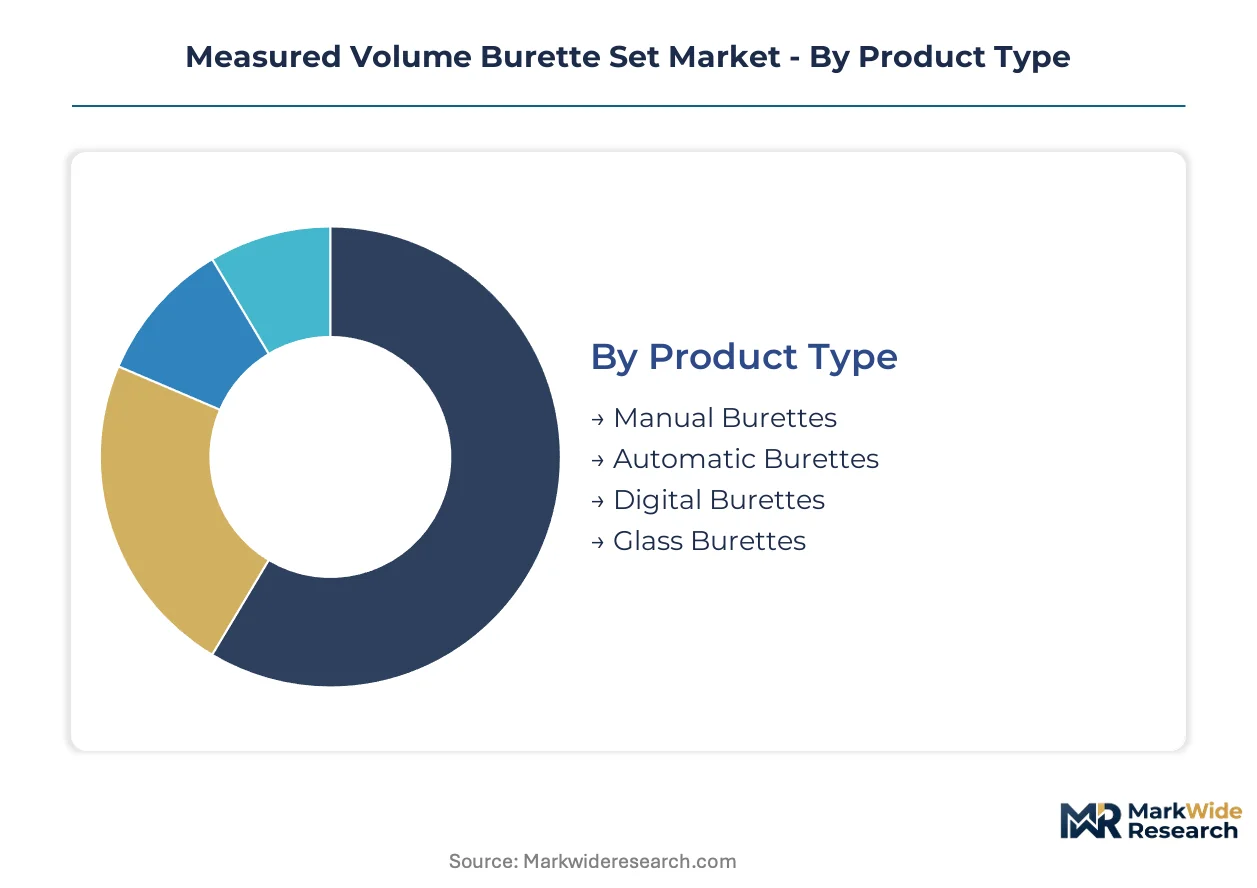
Precision requirements vary dramatically across analytical workflows, educational settings, and high-throughput screening environments. Manufacturers must align construction materials, calibration protocols, and connectivity features with specific use-case tolerances to capture margin pools effectively.
Product Type:
Analytical workflows span manual precision techniques through fully automated liquid handling systems with embedded gravimetric verification.
- Manual Burettes:Traditional stopcock-operated glass cylinders deliver variable reagent volumes under direct technician control. Budget-constrained educational institutions in India and secondary schools across Germany sustain procurement volume despite limited digital integration capabilities.
- Automatic Burettes:Motorized piston-driven systems eliminate operator variability in repetitive titration sequences. Pharmaceutical quality control laboratories in Switzerland and diagnostic chains in Mumbai are adopting these units to reduce technician-to-technician measurement deviation.
- Digital Burettes:Cloud-connected units with laboratory information management system integration command premium positioning. These systems are expanding most quickly in automated workflows where data integrity requirements override capital cost sensitivity.
- Glass Burettes:Borosilicate construction retains dominance in analytical-grade thermal stability applications. CDSCO-compliant procurement channels in Indian pharmaceutical laboratories specify these units for assay verification protocols.
Established volume favors manual burettes; emerging adoption favors digital burettes.
Material:
Cost tiers and chemical compatibility requirements drive material selection across end-use segments.
- Glass:Borosilicate formulations offer thermal shock resistance and chemical inertness for aggressive reagent contact. REACH substance restriction proposals targeting boron compounds are forcing European manufacturers toward accelerated alternative qualification timelines.
- Plastic:General-purpose polymer construction serves educational markets where breakage resistance outweighs extreme precision requirements. Secondary school laboratories across India specify these units for introductory titration curricula.
- Polypropylene:Lightweight, shatter-resistant properties support high-throughput screening environments. Cost efficiency in volume procurement contracts limits margin capture despite substantial unit shipments.
- Fluoropolymer:Inert formulations are penetrating clinical diagnostic applications previously reserved for glass construction. Pilot programs by European manufacturers aim to preserve market access under anticipated borosilicate restriction scenarios.
Glass retains the highest margin concentration; fluoropolymer exhibits the steepest expansion trajectory.
Application:
Customer maturity and regulatory burden intensity separate commercial segments.
- Chemical Analysis:Quantitative determination of substance composition demands certified volumetric accuracy. Industrial laboratories in Germany sustain premium procurement for ISO 8655-compliant apparatus.
- Titration:Endpoint detection workflows in pharmaceutical quality control require traceable calibration documentation. CDSCO medical device rules mandate conformity assessment for clinical diagnostic deployments in India.
- Laboratory Experiments:Research and development settings prioritize flexibility over standardized protocols. Academic institutions balance precision requirements against capital budget constraints.
- Educational Purposes:Introductory chemistry instruction accepts wider tolerance ranges. Polypropylene substitution compresses addressable margin despite substantial aggregate volume.
Titration commands the strictest compliance burden; educational purposes drive the highest shipment volumes.
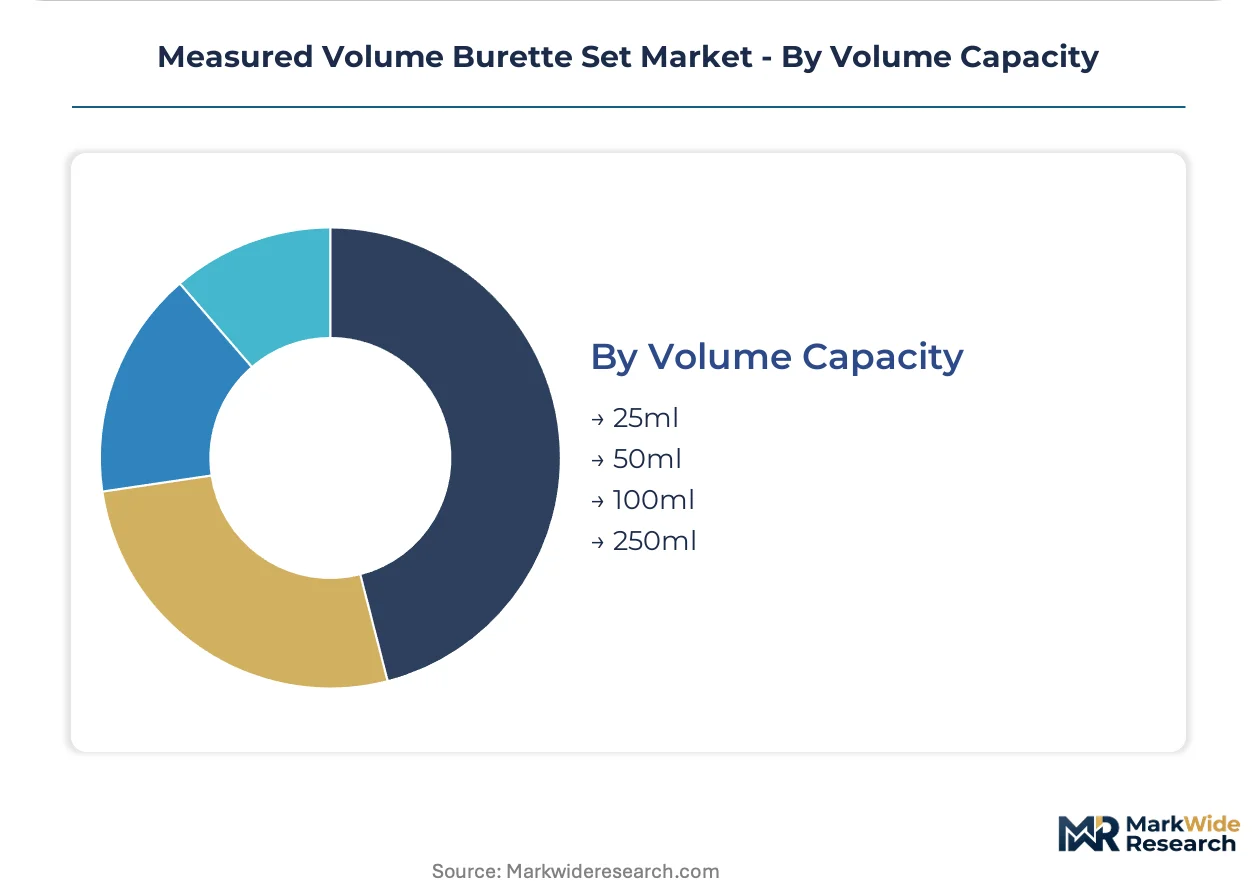
Volume Capacity:
Scale of analytical operation determines capacity specification distribution.
- 25ml:Micro-scale titration and precious reagent conservation favor compact capacity. Pharmaceutical development laboratories in Switzerland specify these units for early-stage compound screening.
- 50ml:Standard analytical workflows balance reagent economy with operational efficiency. This specification dominates procurement contracts across South Asian diagnostic chains.
- 100ml:Extended titration sequences and industrial quality control applications require intermediate capacity. Chemical manufacturing facilities in Germany specify these units for routine assay verification.
- 250ml:Bulk reagent dispensing and preparatory scale operations demand maximum capacity. Limited adoption outside industrial process control and specialized educational demonstrations.
50ml capacity anchors procurement volume; 25ml specifications gain share fastest in pharmaceutical development settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement contexts. German chemical laboratories absorb premium glass burette costs without volume compression, while Indian educational institutions drive hard polypropylene substitution. This demand-elasticity contrast structures regional opportunity allocation.
Germany
Industrial titration workflows in chemical manufacturing sustain premium borosilicate procurement. REACH substance restriction proposals targeting boron compounds are forcing accelerated fluoropolymer qualification timelines. The Rhine-Ruhr and Bavarian chemical clusters anchor ISO 8655-compliant apparatus demand.
India
Pharmaceutical quality control laboratory expansion drives calibrated burette set procurement. CDSCO Medical Device Rules 2017 impose conformity assessment burdens on imported clinical diagnostic equipment. Mumbai and Bangalore diagnostic chains are consolidating specifications across multi-site networks.
Switzerland
Pharmaceutical development laboratories specify micro-scale 25ml capacity for early-stage compound screening. Swissmedic maintains stringent volumetric accuracy tolerances that exceed ISO baseline requirements. Basel and Zurich pharmaceutical clusters are adopting cloud-connected digital burettes at accelerated replacement cycles.
United States
FDA 21 CFR Part 820 quality system regulations shape product design and calibration protocols for North American buyers. Automated laboratory workflows in biopharmaceutical quality control are creating specification requirements for LIMS-integrated digital burettes. Boston and San Francisco Bay Area biotech clusters are virtualizing aftermarket revenue through embedded software subscription architectures.
China
NMPA maintains divergent volumetric accuracy tolerance specifications that complicate unified product platform strategies. Domestic fluoropolymer formulation advancement is opening clinical diagnostic applications previously reserved for glass construction. Shanghai and Jiangsu province chemical equipment manufacturing clusters are piloting alternative material programs.
Measured Volume Burette Set Market Key Industry Players
Capability concentration sits with precision glass fabrication specialists; scale advantage sits with diversified medical device conglomerates. The vendor base structures around three tiers: European precision instrument heritage brands, Asian cost-optimized manufacturers, and diversified healthcare conglomerates with hospital channel control. Strategic moves center on direct hospital contracting to defend aftermarket calibration revenue and fluoropolymer material advancement to preserve market access under REACH restriction scenarios.
Among diversified healthcare conglomerates, B. Braun and Fresenius Kabi occupy positions anchored by European manufacturing footprints and institutional procurement contract penetration. Thermo Fisher sits within the analytical instrumentation tier, exemplifying digital connectivity differentiation. Wellmed International Industries Pvt. Ltd. represents the Asia-Pacific manufacturing base. These three anchors illustrate the competitive structure: conglomerate scale, analytical precision capability, and regional manufacturing cost positioning.
| Leading Market Players |
|---|
| PL Medical |
| Agniplast |
| B. Braun |
| Merck |
| Globalmedikit |
| Baxter International |
| Wellmed International Industries Pvt. Ltd. |
| Fresenius Kabi |
| Thermo Fisher |
| Others |
Cost & Logistics Intelligence
Borosilicate glass manufacturing clusters in Central Europe concentrate feedstock supply for analytical-grade burette production, anchoring premium pricing power with heritage precision instrument brands while forcing cost-optimized competitors toward polymer substitution strategies.
Pricing Analysis
Aftermarket calibration and recertification revenue drives lifetime value capture beyond initial equipment transactions. Three-tier pricing structure across premium ISO 8655-certified glass, standard polypropylene educational units, and economy manual burettes segments buyer willingness-to-pay. Pricing pressure stems from polypropylene substitution in high-throughput screening environments where precision tolerance widening compresses addressable margin. Educational institutions in India exhibit highest price sensitivity; pharmaceutical quality control laboratories in Germany absorb premium positioning without volume compression.
Supply Chain Analysis
Specialty borosilicate glass feedstock draws from Czech Republic, Germany, and select Central European fabrication sites with limited alternative qualification pathways. Raw material dependencies center on boron compound availability, precision glass tubing capacity, and fluoropolymer resin supply for substitution programs. Single-source vulnerability concentrates in analytical-grade glass tube production where REACH substance restriction proposals threaten feedstock continuity. Distribution runs through direct hospital contracting networks and regional diagnostic chain procurement consolidation, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
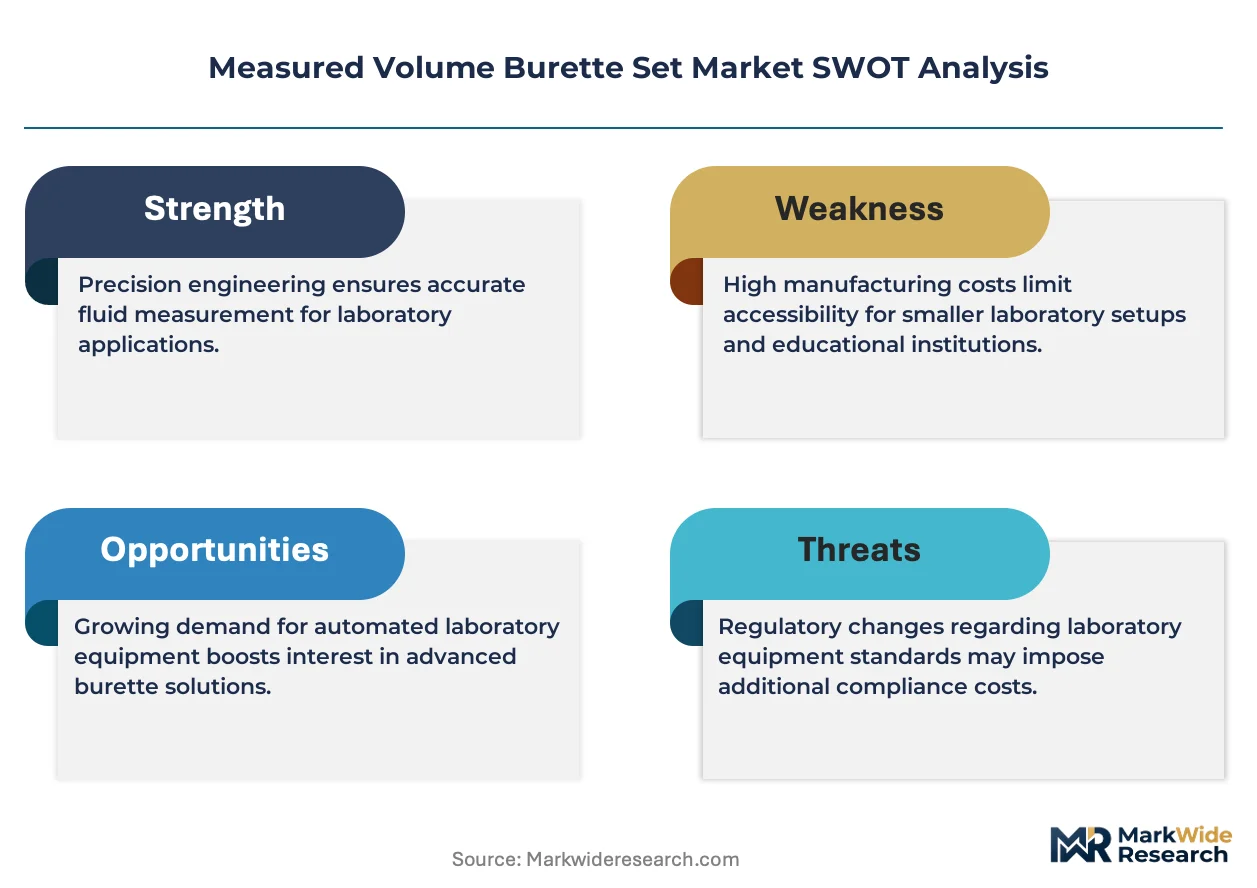
This market demands substitution defense against fluoropolymer and automated liquid handling platform displacement, as material science advances and workflow digitization threaten incumbent glass-burette positioning.
For Market Incumbents: Insulate analytical-grade glass positioning through accelerated fluoropolymer pilot programs that preserve market access under anticipated REACH boron compound restrictions. Secure direct hospital channel control via embedded software subscription architectures that virtualize aftermarket calibration revenue and disintermediate regional service networks. Counter polypropylene substitution by emphasizing CDSCO and FDA 21 CFR Part 820 compliance documentation as mandatory bid thresholds.
For New Entrants and Emerging Players: Establish a beachhead in South Asian diagnostic chain procurement consolidation where institutional buyers are displacing fragmented distributor relationships with direct manufacturer contracts. Target 50ml capacity specifications that anchor volume procurement across Mumbai and Bangalore laboratory clusters. Lead with CDSCO Medical Device Rules 2017 conformity assessment capabilities as a go-to-market differentiator against unqualified imports.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument heritage brands with captive borosilicate supply relationships and established ISO 8655 calibration service networks. Long-term viability hinges on substitution defense execution across the next decade as fluoropolymer formulations penetrate clinical diagnostic applications. Monitor ISO and national pharmacopeia harmonization negotiations as the inflection signal—convergence would consolidate testing requirements and reward scaled certification infrastructure, while continued fragmentation favors regional specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Material Qualification | Preserves market access under REACH boron restriction scenarios for European manufacturers. |
| Digital Burette LIMS Integration | Captures pharmaceutical quality control laboratory specification requirements in automated workflows. |
| Direct Hospital Channel Contracting | Defends aftermarket calibration revenue against regional service network disintermediation. |
| CDSCO Compliance Infrastructure | Unlocks formal procurement channels in Indian pharmaceutical quality control laboratory expansion. |
| Cloud-Connected Gravimetric Verification | Virtualizes recertification revenue through embedded software subscription architectures. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory managers, biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket calibration service technicians. Secondary validation drew from FDA 21 CFR Part 820 filings, CDSCO medical device registration databases, ISO 8655 technical documentation, SEC 10-K disclosures from diversified healthcare conglomerates, and European chemical equipment trade data. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Calibration approaches anchored projections across the analysis window using product type, material construction, application workflow, and volume capacity segmentation dimensions. CAGRs were derived from replacement cycle analysis, regulatory compliance timeline modeling, and procurement contract visibility. Industry-specific forecast inputs included CDSCO harmonization implementation pace, REACH substance restriction proposal advancement, and diagnostic chain consolidation patterns across South Asian markets.
Stress conditions across borosilicate supply disruption, fluoropolymer substitution acceleration, and pharmacopeia tolerance divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization trajectory and material science advancement timelines. Cross-checking against hospital procurement database benchmarks and GPO contract award records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Endoscope Protective Barrier Covers Market