
 Fibrin Sealants Market | 2026-2036
Fibrin Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Fibrin Sealants Market Intelligence
Aftermarket service revenue for sealant application systems is reconfiguring margin pools away from standalone product sales toward bundled device-consumable contracts. Baxter International dominates installed base maintenance for sprayer platforms across North American hospital networks. Johnson & Johnson (Ethicon) leverages its suture and mechanical hemostat portfolio to anchor bundled procurement decisions in integrated delivery networks. CSL Behring competes on plasma fractionation scale, sustaining cost advantages in human fibrinogen sourcing that smaller manufacturers cannot replicate.
Fibrin sealants comprise biologically active adhesive formulations derived from pooled human plasma or recombinant sources, combining fibrinogen with thrombin to mimic the final coagulation cascade phase and achieve hemostasis or tissue bonding within 10-60 seconds of application. Recombinant fibrinogen variants command premium positioning as regulatory scrutiny of transfusion-transmitted infection risks intensifies, while the general surgery application segment anchors volume demand through open abdominal and thoracic procedures where suture-line sealing remains critical. Delivery mode selection increasingly stratifies by procedure setting: syringe formats dominate operating room workflows, whereas patch configurations penetrate orthopedic and cardiovascular niches where conformability to irregular tissue surfaces determines efficacy.
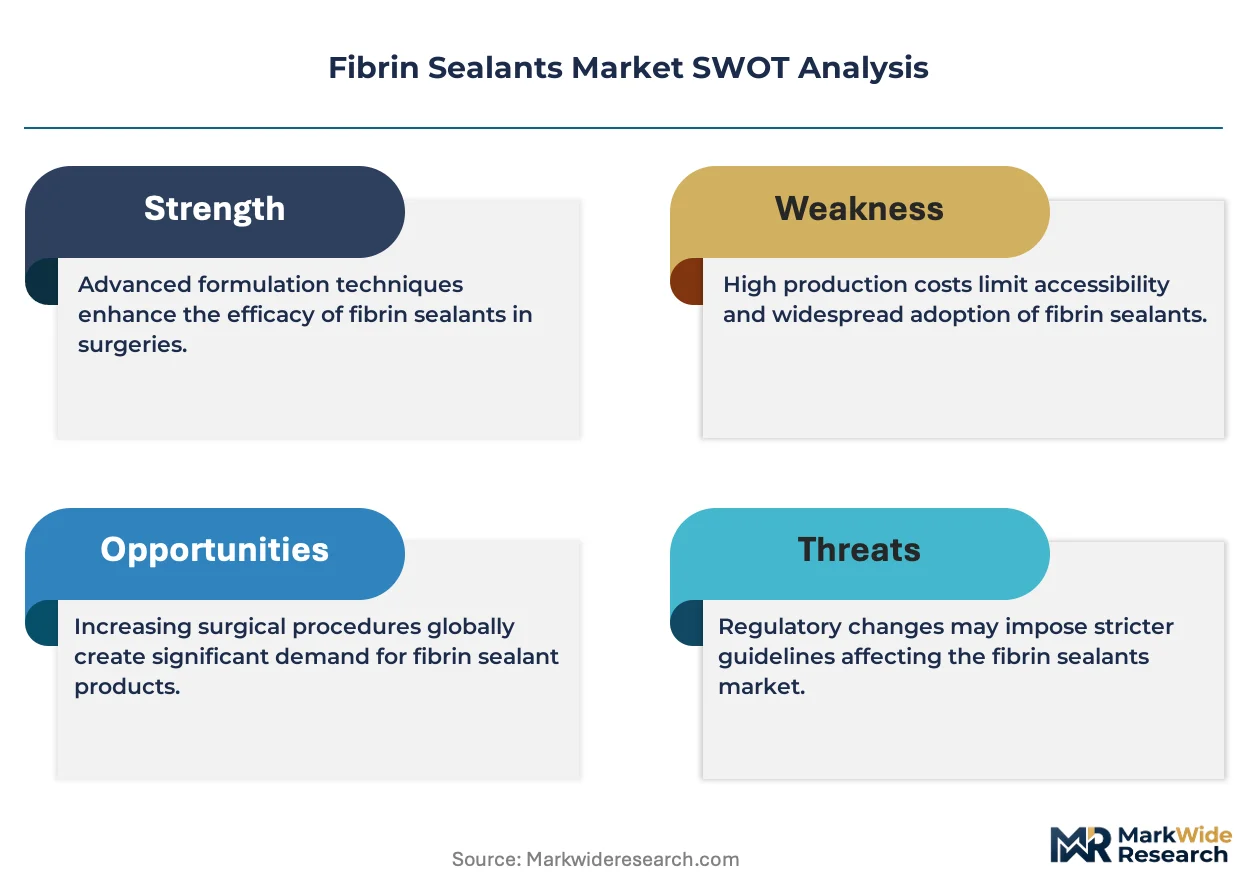
The FDA's Center for Biologics Evaluation and Research governs plasma-derived sealants under 21 CFR 600 series standards, while the EU MDR reclassifies fibrin sealants from Class III to higher-scrutiny pathways requiring enhanced clinical evidence for CE marking renewal. Japan's PMDA maintains distinct viral inactivation validation requirements that fragment approval timelines for multinational manufacturers. Stakeholders must monitor evolving biosimilar frameworks for recombinant coagulation factors, as regulatory convergence on immunogenicity standards could reshape competitive barriers and sourcing economics for fibrinogen raw materials.
Market Dynamics
EU MDR reclassification of fibrin sealants to higher-scrutiny pathways is compressing approval timelines and forcing manufacturers to rebuild clinical evidence packages for CE marking renewal.
Growth Catalysts
- Ambulatory Surgery Center Consolidation:United States ASC networks are standardizing fibrin sealant protocols across multi-site platforms, creating volume commitments that stabilize procurement forecasting.
- EU MDR Clinical Evidence Mandates:Enhanced post-market surveillance requirements are accelerating manufacturer investment in real-world outcome registries that demonstrate hemostatic efficacy.
- Cardiovascular Procedure Volumes:Rising aortic repair and coronary bypass operations in tertiary hospitals sustain demand for rapid-seal formulations in suture-line reinforcement.
Market Restraints
- Plasma Fractionation Concentration:Human fibrinogen sourcing depends on a limited base of plasma collection centers in the United States and Germany, exposing supply chains to donor availability fluctuations.
- Recombinant Production Costs:Mammalian cell culture systems for fibrinogen expression require capital-intensive bioreactor infrastructure that smaller manufacturers cannot access.
- Transfusion-Transmitted Infection Scrutiny:Persistent regulatory attention to prion disease and emerging pathogen risks sustains validation burdens that extend development timelines.
Strategic Opportunities
- Orthopedic Patch Configurations:Conformable fibrin sealant patches for joint reconstruction procedures in Germany and France represent underpenetrated demand relative to cardiovascular applications.
- Biosimilar Framework Convergence:Harmonizing immunogenicity standards for recombinant coagulation factors across FDA and EMA pathways could streamline multi-jurisdictional approvals.
- Japan PMDA Viral Validation:Dedicated inactivation studies for Japanese regulatory submission create first-mover advantages for manufacturers investing in region-specific dossier preparation.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Plasma fractionation and aseptic filling operations require specialized technicians that command premium compensation in competitive labor markets.
- Legacy Sprayer Platform Integration:Hospital networks with installed Baxter or Ethicon application systems face switching costs when evaluating alternative sealant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibrin Sealants Market |
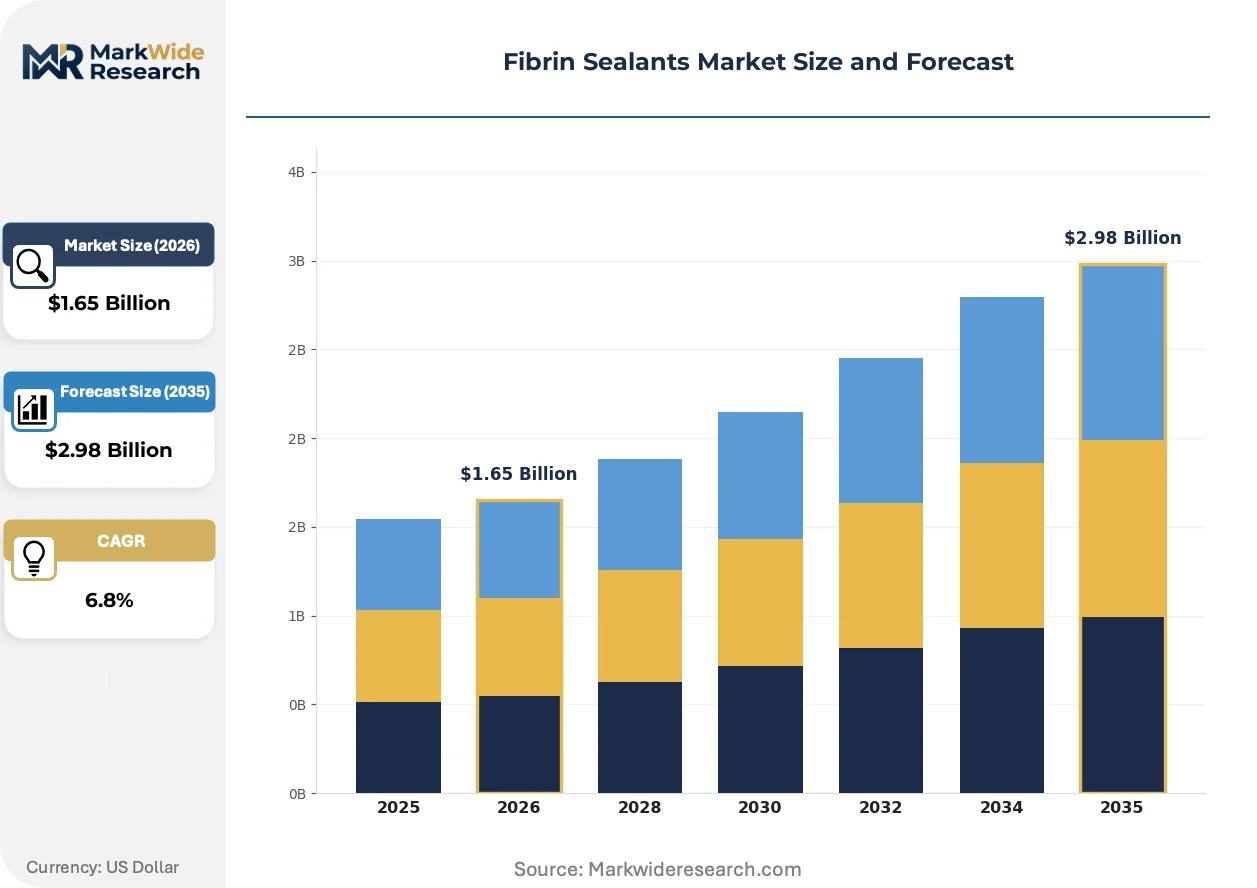
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Fibrinogen, Bovine Fibrinogen, Recombinant Fibrinogen, Fibrin Glue Application: General Surgery, Orthopedic Surgery, Cardiovascular Surgery, Neurosurgery Delivery Mode: Syringe, Sprayer, Patch, Injectable End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Clinics |
| Companies Covered | Baxter International, Johnson & Johnson (Ethicon), CSL Behring, Grifols, Takeda Pharmaceutical Company, Octapharma, Pfizer, Vivostat, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibrin Sealants Market Strategic Shifts & Innovations
Formulation science and delivery mechanism design are converging to reshape competitive positioning, with recombinant sourcing and patch-based application formats commanding disproportionate R&D investment.
Recombinant fibrinogen production is migrating from plasma-dependent extraction toward genetically engineered expression systems. Academic medical centers in the United States are piloting these formulations in complex cardiac procedures where immunogenicity profiles justify premium positioning. This technology shift is compressing the addressable market for traditional plasma-derived sealants to price-sensitive general surgery applications.
EU MDR Article 120 transitional provisions are forcing manufacturers to resubmit technical documentation for legacy products previously approved under the Medical Devices Directive. Industrial consequence includes extended notified body queue times that delay product modifications. Cardiovascular sealant variants with predicate device histories face the steepest compliance burdens as they require new clinical investigations to support renewed CE certificates.
Aftermarket service contracts for sealant application systems are displacing standalone consumable purchasing in integrated delivery networks. Hospital procurement committees in the United States now bundle device maintenance with consumable supply agreements, compressing vendor margins on product-only sales. This behavioral shift is most visible in cardiovascular service lines where sprayer platform standardization across cath labs and OR suites creates captive supply relationships.
Fibrin Sealants Market Segmentation
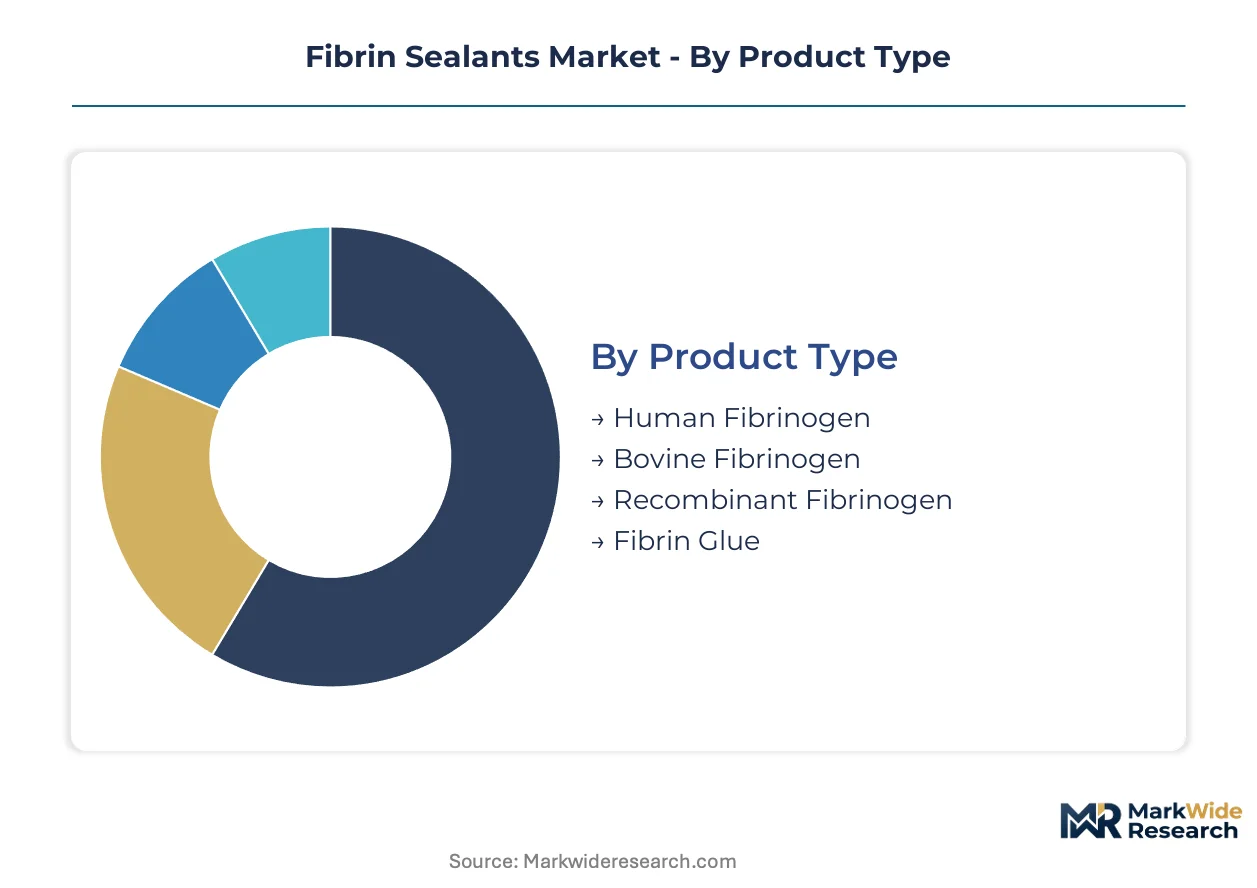
Fibrin sealant procurement stratifies across product sourcing, surgical application, delivery mechanism, and care setting. Each dimension shapes service contract structures and margin capture for manufacturers.
Product Type:
After-sales-service intensity varies sharply by product type, with recombinant variants demanding specialized handling protocols and cold-chain validation that extend manufacturer field support obligations.
- Human Fibrinogen:Plasma-derived formulations combine fibrinogen with thrombin in dual-chamber syringes requiring frozen storage. Demand concentrates in United States tertiary hospitals where established blood banking infrastructure supports inventory management. Baxter International and CSL Behring dominate supply through captive plasma fractionation networks.
- Recombinant Fibrinogen:Genetically engineered expression in mammalian cell cultures eliminates transfusion-transmitted infection risks. Academic medical centers in Germany and France pilot these formulations in complex cardiac procedures where immunogenicity profiles justify premium positioning and dedicated technical service contracts.
- Bovine Fibrinogen:Xenogenic sourcing from controlled cattle herds serves price-sensitive general surgery applications with simpler regulatory pathways than human plasma derivatives.
- Fibrin Glue:Pre-mixed single-component preparations reduce preparation time in emergency settings but sacrifice dosing flexibility preferred in microsurgical applications.
Human fibrinogen holds the largest share; momentum sits with recombinant fibrinogen.
Application:
Application segmentation maps directly to procedure reimbursement tiers, with cardiovascular and neurosurgery commanding service line budgets that accommodate premium sealant procurement.
- General Surgery:Open abdominal and thoracic procedures anchor volume demand through suture-line sealing requirements. United States ASC networks standardize fibrin sealant protocols across multi-site platforms, creating predictable consumable forecasting.
- Cardiovascular Surgery:Aortic repair and coronary bypass operations sustain demand for rapid-seal formulations. Tertiary hospitals in Germany and France maintain dedicated cardiovascular service lines with integrated device-consumable contracts.
- Orthopedic Surgery:Joint reconstruction and spine fusion applications favor patch configurations where conformability to irregular bone surfaces determines hemostatic efficacy.
- Neurosurgery:Microvascular anastomosis and dural sealing require ultra-low thrombin concentrations to prevent cerebral vasospasm, limiting supplier qualification to specialized manufacturers.
General surgery generates the highest procedure volume; cardiovascular surgery shows the steepest expansion trajectory.
Delivery Mode:
Delivery mode selection determines capital equipment requirements and switching costs, with sprayer platforms creating captive supply relationships through installed base maintenance contracts.
- Syringe:Dual-barrel manual formats dominate operating room workflows where immediate control over fibrinogen-thrombin mixing ratios supports technique customization. United States hospital networks favor syringe standardization for inventory simplification.
- Sprayer:Pneumatic or gas-powered atomization enables uniform tissue coverage in large surface area procedures. Baxter International's installed base across North American hospital networks creates substantial switching costs for competing formulations.
- Patch:Lyophilized fibrinogen-impregnated matrices conform to irregular tissue geometries in orthopedic and cardiovascular niches. German and French orthopedic centers show accelerating adoption for joint reconstruction applications.
- Injectable:Catheter-delivered formulations penetrate minimally invasive procedures where direct visualization is limited, requiring radiopaque markers for placement confirmation.
Syringe formats command the greatest volume; patch configurations are gaining share fastest.
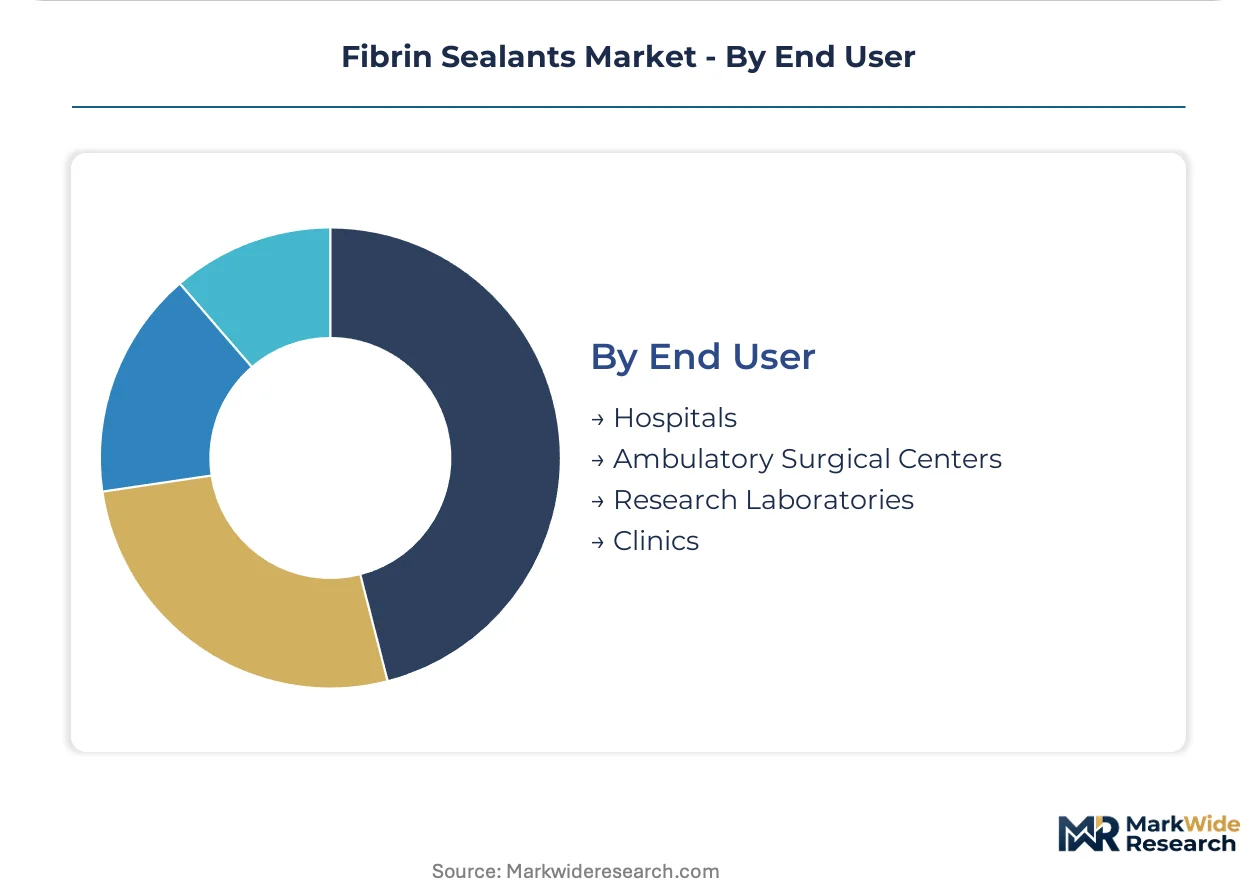
End User:
End user segmentation reflects care setting consolidation trends, with ASC network standardization disrupting traditional hospital-centric procurement patterns.
- Hospitals:Tertiary academic centers in the United States and Germany maintain diversified sealant formularies across service lines. EU MDR compliance burdens fall heaviest on hospital procurement committees evaluating CE marking renewal status.
- Ambulatory Surgical Centers:United States ASC consolidation creates multi-site volume commitments that stabilize manufacturer forecasting. Standardized protocols across platform networks favor single-source device-consumable contracts.
- Research Laboratories:Academic institutions in France and Japan drive early-stage recombinant formulation development through investigator-initiated trials.
- Clinics:Office-based procedural settings in dermatology and wound care represent fragmented, price-sensitive demand with limited sealant utilization.
Hospitals retain the dominant procurement position; ASCs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies: United States hospital networks absorb premium recombinant formulations, while price-sensitive procurement in emerging markets concentrates demand on plasma-derived alternatives.
United States
Ambulatory surgery center consolidation drives standardized fibrin sealant protocols across multi-site platforms. FDA Center for Biologics Evaluation and Research governs plasma-derived sealants under 21 CFR 600 series standards. The Greater Boston cluster anchors cardiovascular research programs piloting recombinant formulations in complex cardiac procedures.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia maintain dedicated cardiovascular service lines with integrated device-consumable contracts. EU MDR reclassification to higher-scrutiny pathways forces manufacturers to rebuild clinical evidence packages for CE marking renewal. The Frankfurt-Rhine-Main biotech corridor concentrates plasma fractionation infrastructure supporting regional supply security.
France
Orthopedic centers in Île-de-France show accelerating adoption of patch configurations for joint reconstruction applications. ANSM enforces post-market surveillance requirements that accelerate manufacturer investment in real-world outcome registries. The Lyon-Grenoble medical technology cluster specializes in conformable sealant matrices for irregular tissue geometries.
Japan
Academic medical centers in Kanto drive early-stage recombinant formulation development through investigator-initiated trials. PMDA maintains distinct viral inactivation validation requirements that fragment approval timelines for multinational manufacturers. The Osaka-Kobe pharmaceutical corridor hosts specialized manufacturers qualified for ultra-low thrombin concentration neurosurgical formulations.
United Kingdom
London-based integrated delivery networks bundle device maintenance with consumable supply agreements, compressing vendor margins on product-only sales. MHRA alignment with EU MDR transitional provisions extends notified body queue times delaying product modifications. The Cambridge-London life sciences corridor concentrates translational research on genetically engineered fibrinogen expression systems.
Fibrin Sealants Market Key Industry Players
Capability concentration sits with plasma fractionation specialists; scale advantage sits with diversified medical device conglomerates. The market structures around three tiers: captive plasma sourcing networks, recombinant biotechnology platforms, and regional application system integrators. Dominant competitive moves include backward integration into plasma collection infrastructure and strategic bundling of sealant formulations with proprietary delivery devices.
Within the plasma-sourcing tier, Baxter International and CSL Behring anchor supply security through captive fractionation networks. Johnson & Johnson (Ethicon) occupies a position at the device-integration end, leveraging mechanical hemostat portfolios to standardize procurement decisions. Grifols represents the mid-tier specialist archetype, concentrating on regional plasma collection scale without full device ecosystem control.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson (Ethicon) |
| CSL Behring |
| Grifols |
| Takeda Pharmaceutical Company |
| Octapharma |
| Pfizer |
| Vivostat |
| Asahi Kasei Corporation |
| Others |
Cost & Logistics Intelligence
Plasma fractionation undercapacity in the United States and Germany compresses supplier margins while elevating pricing power for CSL Behring and Baxter International through captive collection networks. This utilization squeeze forces smaller manufacturers toward recombinant alternatives or bovine sourcing, fragmenting procurement tiers across hospital networks.
Pricing Analysis
Aftermarket service revenue for sprayer platform maintenance drives lifetime value capture for device-integrated suppliers. Three-tier pricing structure across premium recombinant, standard human plasma-derived, and economy bovine formulations separates academic medical centers from community hospitals from price-sensitive ASCs. Cost compression in the plasma-derived tier intensifies because EU MDR compliance burdens extend development timelines without commensurate reimbursement expansion. Ambulatory surgical centers exhibit the sharpest price sensitivity, whereas tertiary cardiovascular service lines absorb premium positioning for rapid-seal formulations.
Supply Chain Analysis
Contract manufacturing for aseptic filling concentrates with Baxter International's internal network and specialized European CMOs serving mid-tier entrants. Geographic supply concentration centers on the United States, Germany, and Austria, where plasma collection infrastructure and fractionation capacity cluster. Raw material dependencies rest on pooled human plasma, recombinant cell culture media, and thrombin enzyme preparations. Single-source vulnerability runs through the limited base of FDA-inspected plasma collection centers. Distribution runs through GPO-negotiated contracts with integrated delivery networks and direct hospital agreements in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fibrin sealants market faces high-growth disruption as EU MDR reclassification and recombinant biotechnology convergence reshape competitive barriers. This regulatory-technological inflection compresses legacy product timelines while opening premium positioning for genetically engineered alternatives.
For Market Incumbents: Build installed-base moats through sprayer platform standardization across cardiovascular service lines. Deepen backward integration into plasma collection infrastructure in the United States to secure fibrinogen supply against donor availability fluctuations. Anchor bundled procurement decisions in integrated delivery networks by leveraging mechanical hemostat portfolios as loss leaders. Invest in viral inactivation validation studies for PMDA submission to capture first-mover advantage in Japan's neurosurgical niche. For New Entrants and Emerging Players: Orthopedic patch configurations for joint reconstruction in Germany and France represent the most penetrable entry point given underpenetrated demand relative to cardiovascular saturation. Recombinant formulation development for academic medical centers in the United States offers white-space positioning where immunogenicity profiles justify technical service premiums. Partner with regional plasma fractionators in Austria or Spain to access EU MDR-compliant sourcing without captive collection infrastructure. Target GPO contracts in consolidating ASC networks through syringe-format standardization and predictable consumable forecasting. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-integrated suppliers with installed sprayer platforms and multi-year service contracts. Long-term viability over the next decade hinges on recombinant biotechnology scale and regulatory dossier depth across FDA, EMA, and PMDA pathways. Acquisition targets should display plasma fractionation expertise or mammalian cell culture capacity with existing viral validation frameworks. Monitor biosimilar immunogenicity standard convergence between FDA and EMA as the critical inflection signal for recombinant sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Rebuild | Enhanced post-market surveillance registries demonstrate hemostatic efficacy for CE marking renewal in Germany and France. |
| Recombinant Fibrinogen Scale-Up | Mammalian cell culture expansion eliminates transfusion-transmitted infection risks for academic medical center positioning. |
| ASC Network Standardization | Multi-site volume commitments in United States ambulatory surgery centers stabilize manufacturer forecasting and procurement. |
| PMDA Viral Validation Investment | Dedicated inactivation studies for Japanese regulatory submission create first-mover advantages in neurosurgical formulations. |
| Patch Configuration Development | Lyophilized matrix conformability captures orthopedic joint reconstruction demand in German and French centers. |
Research Approach
Cross-validation between hospital procurement database analysis and plasma fractionator capacity disclosures anchors the qualitative findings in this study. Primary interviews with cardiovascular surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers were combined with secondary validation through FDA 510(k) filings, EMA CE marking databases, ClinicalTrials.gov entries, and hospital formulary records. Bottom-up procedure volume modeling and top-down plasma fractionation capacity analysis were triangulated to establish market sizing boundaries.
Calibration against historical approval timelines and reimbursement pathway changes shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product sourcing tier, surgical application specialty, delivery mechanism format, and care setting consolidation stage. CAGRs were derived from procedure volume elasticity coefficients and pricing trajectory assumptions. Forecast inputs incorporated EU MDR transition timeline uncertainty and recombinant formulation adoption curves in academic medical centers.
Stress conditions across plasma donor availability, regulatory approval queue delays, and recombinant production yield variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ASC consolidation velocity and cardiovascular procedure volume sustainability. Biosimilar framework harmonization progress and emerging pathogen validation burdens represent specific risk factors that could revise projections. Quarterly review of notified body queue times and recombinant clinical trial enrollment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Skin Tac Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Trauma Products Market
Medical Supplies
Blood Bags Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Global Povidone Iodine Market