
 Medical Supply Delivery Service Market | 2026-2036
Medical Supply Delivery Service Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Supply Delivery Service Market Intelligence
ISO 13485 certification for medical device quality management is rotating as the primary gatekeeping standard for logistics providers seeking hospital and laboratory contracts. McKesson Corporation leverages its wholesale pharmaceutical infrastructure to sustain same-day delivery density in metropolitan corridors. DHL anchors European cold-chain compliance through dedicated GDP-certified healthcare campuses. Zipline dominates autonomous aerial distribution in rural and remote access zones.
Medical supply delivery service encompasses the specialized transport, warehousing, and last-mile fulfillment of healthcare goods requiring temperature control, chain-of-custody documentation, and time-definite performance standards. Cold-chain integrity mandates typically require validated packaging maintaining 2-8°C for biologics and real-time GPS-telemetry logging across the distribution path. Same-day delivery and express delivery modes command premium positioning due to emergency replenishment needs and perishable pharmaceutical windows. Scheduled delivery sustains margin pools through predictable inventory routing for consumables and equipment to hospitals and home healthcare networks.
FDA enforcement of Drug Supply Chain Security Act traceability rules and EMA Good Distribution Practice guidelines are reshaping fleet investment toward serialized tracking and temperature-validated vehicles. The EU AI Act and emerging FAA frameworks for beyond-visual-line-of-sight drone operations will determine which delivery modalities achieve regulatory clearance at scale. Stakeholders must evaluate whether autonomous platforms or contracted courier networks offer superior compliance adaptability as jurisdictional requirements diverge.
Market Dynamics
Hospital-at-home programs and decentralized patient care are compressing delivery timelines from bulk replenishment to unit-dose fulfillment, forcing logistics networks to reconfigure for last-mile temperature integrity at residential addresses rather than loading docks.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialized tracking mandates are expanding fleet investment in telematics-equipped vehicles, pulling demand for compliant third-party logistics providers.
- Biologics cold-chain:Temperature-sensitive monoclonal antibodies and cell therapies require validated 2-8°C packaging through final delivery, sustaining premium service tiers.
- Germany hospital-at-home expansion:Regional health insurers are reimbursing domiciliary infusion services, creating dense delivery corridors for same-day pharmaceutical fulfillment.
Market Restraints
- Refrigerant input volatility:Phase-down of hydrofluorocarbons under EU F-Gas Regulation is elevating costs for passive cold-box manufacturing.
- Pilot certification scarcity:Beyond-visual-line-of-sight drone operations face FAA waiver bottlenecks, constraining autonomous aerial scaling in the United States.
- Specialized fleet concentration:GDP-certified refrigerated vehicle pools cluster with major pharmaceutical wholesalers, limiting independent carrier capacity.
Strategic Opportunities
- Japan rural access gaps:Mountainous terrain and aging demographics in prefectures like Nagano and Gifu create demand for autonomous drone corridors to isolated patient populations.
- EU AI Act compliance services:Algorithmic route-optimization tools require audit trails for high-risk categorization, opening advisory revenue streams for logistics technology vendors.
- Real-time temperature logging:Integration of IoT sensors with blockchain documentation is decomposing traditional paper-based chain-of-custody verification.
Industry Challenges
- ISO 13485 audit timelines:Medical device quality certification cycles stretch 12-18 months, delaying contract eligibility for emerging regional carriers.
- Legacy warehouse management system integration:Hospital procurement portals require EDI connectivity that smaller delivery operators lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Supply Delivery Service Market |
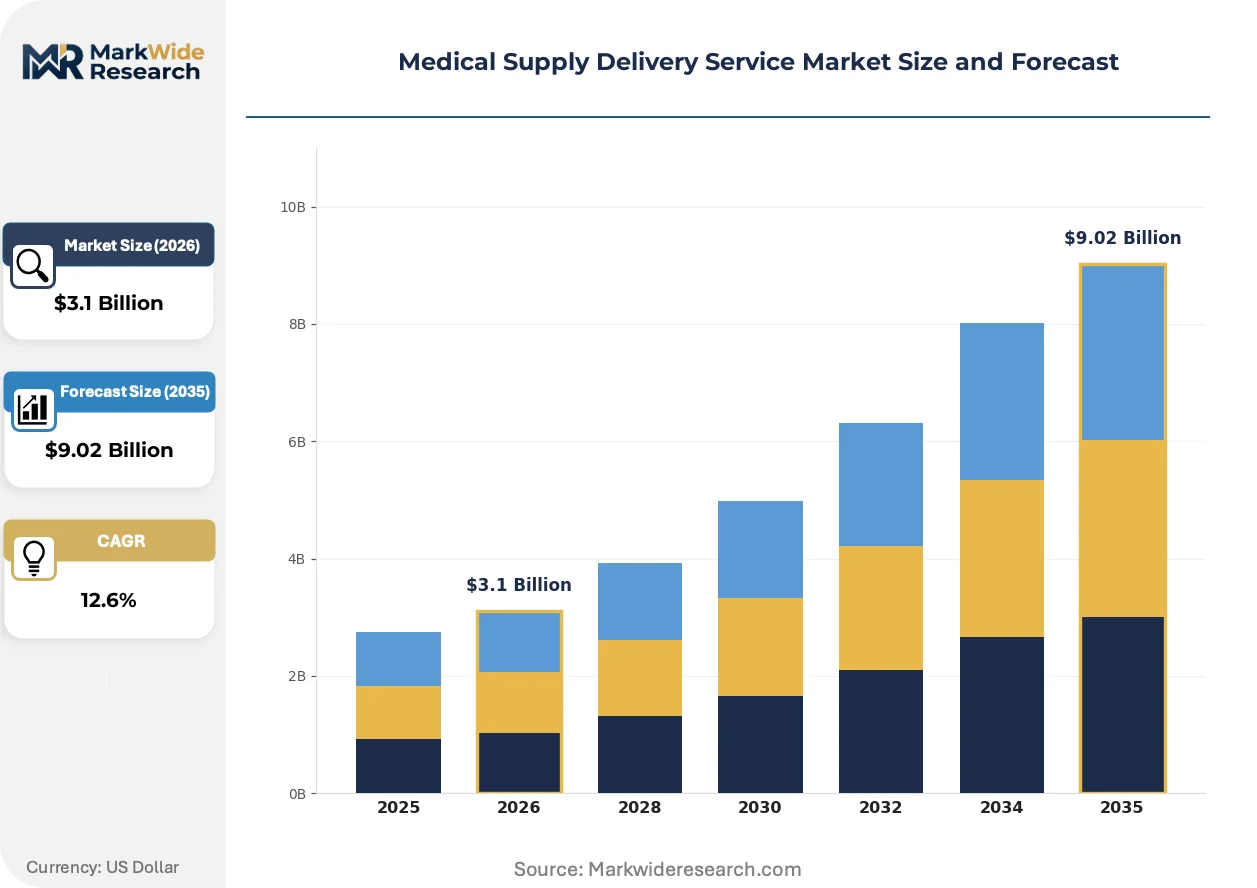
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.02 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Same-Day Delivery, Scheduled Delivery, Express Delivery, Standard Delivery Product Type: Consumables, Instruments, Pharmaceuticals, Equipment End User: Hospitals, Clinics, Home Healthcare, Laboratories Service Type: Pharmacy Delivery, Medical Equipment Rental, Inventory Management, Custom Logistics |
| Companies Covered | UPS, FedEx, DHL, McKesson Corporation, Cardinal Health, CEVA Logistics, Agility, Zipline, ModivCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Supply Delivery Service Market Strategic Shifts & Innovations
Autonomous platforms and predictive analytics are fragmenting the traditional hub-and-spoke pharmaceutical distribution model into dynamic, patient-addressable networks that bypass centralized inventory holding.
Autonomous aerial drones are decomposing the rural last-mile bottleneck that has historically required expensive ground courier dispatch to remote patient addresses. Home healthcare agencies in Rwanda and Ghana have operationalized Zipline's fixed-wing systems for blood product delivery, demonstrating regulatory acceptance of unmanned aircraft in pharmaceutical transport. The technology is decomposing the cost structure of emergency replenishment by eliminating driver labor and vehicle depreciation from low-density routes.
EMA Good Distribution Practice guidelines are tightening documentation requirements for temperature excursions during transit, compelling fleet operators to deploy continuous digital monitoring rather than spot-check validation. Wholesale distributors must now maintain centralized repositories of GPS-telemetry logs for multi-year retrieval. Cold-chain service providers in the Netherlands and Belgium are consolidating compliance infrastructure to serve cross-border hospital networks under unified audit frameworks.
Consignment inventory arrangements are displacing traditional purchase-order cycles for high-value implantable devices, transferring carrying risk from hospitals to delivery-integrated suppliers. Orthopedic and cardiac device manufacturers in the United States are embedding logistics personnel directly into hospital supply chain departments to manage consigned stock rotation. This model concentrates purchasing influence with integrated distributor-manufacturer alliances rather than independent hospital procurement offices.
Medical Supply Delivery Service Market Segmentation
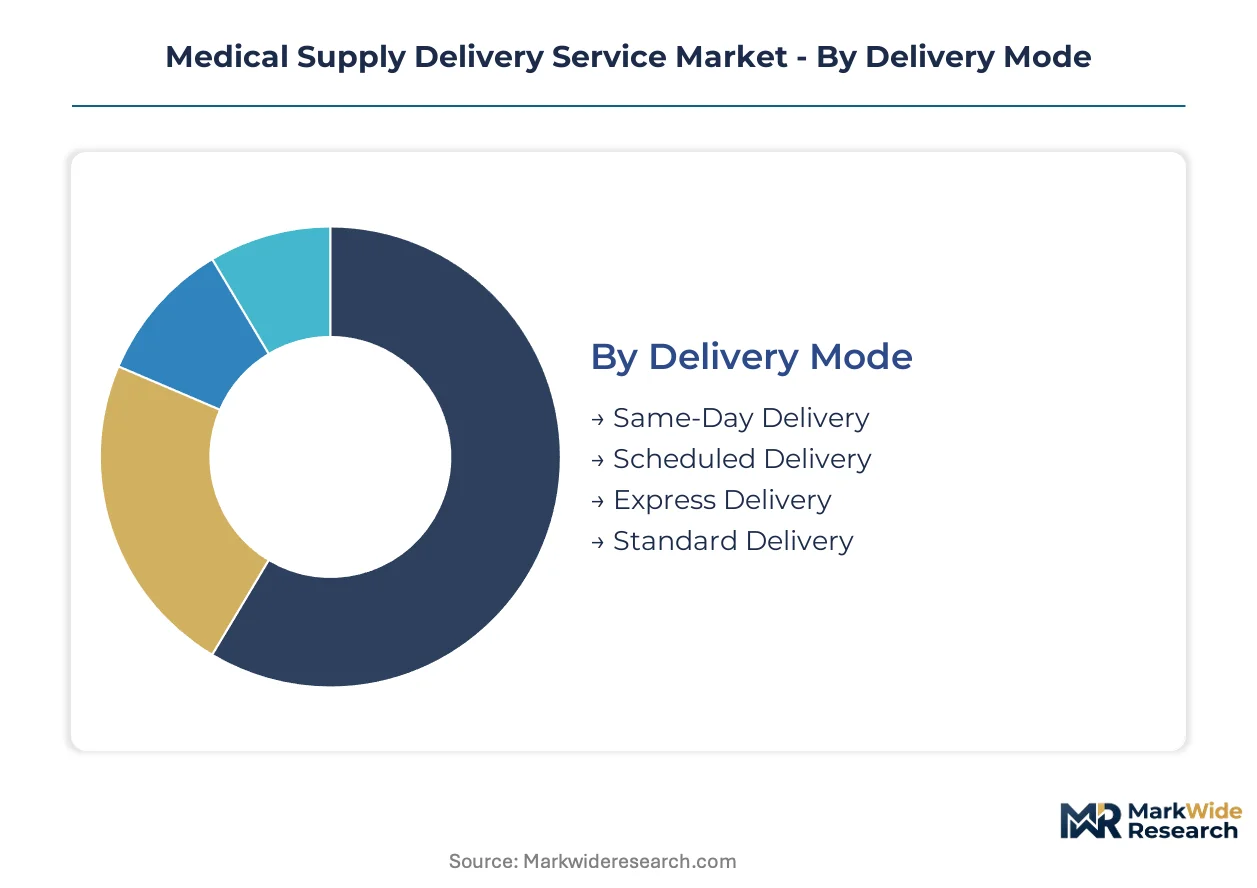
Medical supply delivery networks route distinct product categories through specialized channel configurations. Temperature sensitivity, regulatory documentation requirements, and delivery velocity demands fragment service architectures across mode, product, and end-user dimensions.
Delivery Mode:
Same-day and express channels capture emergency replenishment flows, while scheduled and standard modes consolidate predictable inventory cycles into density-optimized routes.
- Same-Day Delivery:Validated cold-chain packaging maintains 2-8°C for biologics through residential final-mile drops. Hospital-at-home programs in Germany and Japan compress procurement cycles into unit-dose fulfillment windows.
- Scheduled Delivery:Predictable routing sustains margin pools for consumables and capital equipment through bulk replenishment contracts. EDI-integrated warehouse management systems anchor recurring hospital procurement portals.
- Express Delivery:Time-definite performance standards command premium positioning for perishable pharmaceutical windows.
- Standard Delivery:Non-urgent consumables and durable equipment move through consolidated freight networks with extended transit tolerances.
By volume, Scheduled Delivery leads. By expansion pace, Same-Day Delivery is climbing the fastest.
Product Type:
Margin concentration aligns with regulatory burden — temperature-validated segments sustain premium service tiers while commoditized flows compete on route density.
- Pharmaceuticals:Monoclonal antibodies and cell therapies demand GDP-certified vehicles with continuous GPS-telemetry logging. FDA Drug Supply Chain Security Act traceability rules pull fleet investment toward serialized tracking infrastructure.
- Consumables:Gloves, syringes, and disposables move through high-frequency replenishment cycles with minimal documentation overhead. Home healthcare networks in the United States drive dense corridor economics.
- Instruments:Sterile surgical tools require chain-of-custody verification through hospital central supply departments.
- Equipment:Capital assets and implantable devices increasingly flow through consignment inventory arrangements transferring carrying risk to suppliers.
Pharmaceuticals command the steepest price premiums. Consumables generate the highest shipment frequency.
End User:
Customer-type fragmentation forces logistics operators to maintain parallel fleet certifications — ISO 13485 for hospital contracts versus residential-capable temperature integrity for home delivery.
- Home Healthcare:Domiciliary infusion services in Germany's regional insurer networks create dense same-day corridors. Patient-addressable networks bypass centralized inventory holding through dynamic routing algorithms.
- Hospitals:Academic medical centers and community hospitals anchor wholesale distributor relationships with GDP-certified refrigerated vehicle pools. EMA cold-chain mandates tighten multi-year retrieval requirements for telemetry logs.
- Clinics:Ambulatory surgical centers and specialty practices consolidate procurement through group purchasing organizations.
- Laboratories:Reference labs and pathology networks demand time-deficient specimen transport with validated custody documentation.
Hospitals retain the largest contract values. Home Healthcare is gaining share fastest as care decentralizes.
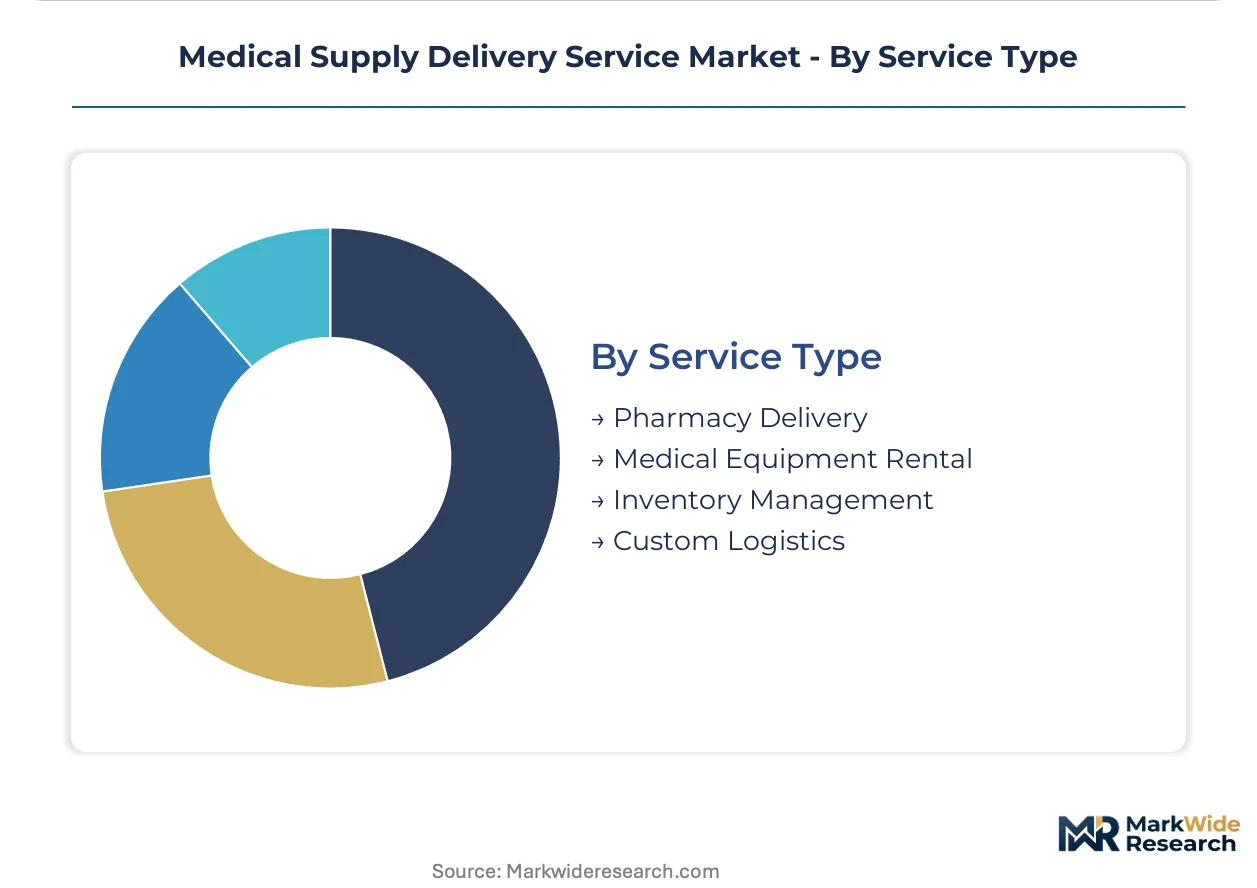
Service Type:
Value-added layers differentiate commodity transport through regulatory compliance infrastructure and inventory risk transfer mechanisms.
- Pharmacy Delivery:Direct-to-patient prescription fulfillment requires HIPAA-aligned documentation and residential address verification systems.
- Medical Equipment Rental:Circulating capital assets through utilization-based pricing models transfers obsolescence risk from providers to logistics-integrated suppliers.
- Inventory Management:Consignment stock rotation embeds logistics personnel into hospital supply chain departments.
- Custom Logistics:Tailored cold-chain solutions for clinical trial materials and cell therapy distribution command project-based pricing.
Inventory Management commands the longest contract durations. Pharmacy Delivery shows the steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Drug Supply Chain Security Act traceability mandates and EMA Good Distribution Practice guidelines are pulling fleet investment toward serialized tracking infrastructure across major pharmaceutical corridors. Hospital-at-home reimbursement programs in Germany and aging demographics in Japan are compressing delivery timelines from bulk replenishment to unit-dose fulfillment.
United States
Hospital-at-home expansion through CMS waiver programs is driving same-day pharmaceutical delivery density in metropolitan corridors. FAA beyond-visual-line-of-sight drone regulations constrain autonomous aerial scaling, though waiver activity concentrates in North Carolina and Nevada test zones. McKesson Corporation anchors wholesale distribution through GDP-certified refrigerated vehicle pools serving academic medical centers.
Germany
Regional health insurers now reimburse domiciliary infusion services, creating dense delivery corridors for temperature-sensitive biologics. EMA cold-chain mandates require multi-year retrieval repositories for GPS-telemetry logs, compelling fleet consolidation. The Rhine-Ruhr and Bavarian pharmaceutical clusters host cross-border compliance infrastructure serving Benelux hospital networks.
Japan
Aging demographics in Nagano and Gifu prefectures generate demand for autonomous drone corridors to isolated patient populations. METI guidelines on medical device distribution quality align with PMDA traceability expectations for last-mile pharmaceutical transport. Tokyo-Osaka pharmaceutical logistics corridors sustain premium cold-chain service tiers through validated 2-8°C packaging networks.
United Kingdom
NHS hospital-at-home pilots are compressing procurement cycles for domiciliary care consumables and emergency pharmaceutical replenishment. MHRA post-Brexit regulatory divergence from EMA guidelines creates dual compliance burdens for cross-channel distributors. The Greater London logistics cluster hosts specialized GDP-certified fleets serving southeast England hospital networks.
India
CDSCO cold-chain guidelines for temperature-sensitive vaccines and biologics are tightening documentation requirements for last-mile distribution. PLI scheme incentives for domestic pharmaceutical manufacturing are expanding outbound logistics demand from Ahmedabad and Hyderabad clusters. Tier-2 city hospital networks drive scheduled delivery volume for consumables through EDI-integrated procurement portals.
Medical Supply Delivery Service Market Key Industry Players
Listed logistics majors compete with private healthcare specialists across certification depth and cold-chain infrastructure density. The vendor base separates into wholesale pharmaceutical distributors, global express carriers with GDP-certified healthcare divisions, and autonomous delivery platform operators. Three archetypes dominate: integrated healthcare wholesalers leveraging existing pharmaceutical infrastructure, global logistics providers anchoring regional compliance campuses, and autonomous aerial specialists targeting rural access gaps. Competitive positioning sharpens through M&A consolidation of regional cold-chain operators and strategic partnerships between drone platform developers and national postal services.
Among integrated healthcare wholesalers, McKesson Corporation and Cardinal Health occupy positions anchored to hospital procurement relationships and pharmaceutical distribution density. DHL exemplifies the global carrier archetype through its European GDP-certified healthcare campus network. Zipline represents the autonomous aerial tier, with operational platforms demonstrating regulatory acceptance of unmanned pharmaceutical transport in Rwanda and Ghana corridors.
| Leading Market Players |
|---|
| UPS |
| FedEx |
| DHL |
| McKesson Corporation |
| Cardinal Health |
| CEVA Logistics |
| Agility |
| Zipline |
| ModivCare |
| Others |
Cost & Logistics Intelligence
Long-term GDP-certified fleet contracts lock in both cold-chain capacity access and predictable unit-cost visibility for hospital networks across Germany and Japan. These multi-year service agreements transfer refrigerant input volatility risk to logistics operators while securing dedicated vehicle pools for temperature-sensitive biologics distribution.
Pricing Analysis
Certification level (ISO 13485 versus GDP-only) creates the primary spread between premium and standard service tiers. Pricing stratifies across GDP-certified cold-chain, temperature-monitored standard, and non-validated economy tiers based on documentation depth and real-time telemetry inclusion. Cost compression in the economy tier is intensifying because hospital procurement consolidation favors bundled service contracts. Home healthcare networks show highest price sensitivity due to reimbursement rate constraints, while academic medical centers prioritize compliance over unit cost.
Supply Chain Analysis
Specialized refrigerant manufacturing concentrates in Germany, Japan, and the United States as the EU F-Gas Regulation phases down hydrofluorocarbon availability. Validated cold-box production draws from specialized foam insulation, phase-change materials, and GPS-telemetry modules. Single-source vulnerability runs through consolidated GDP-certified vehicle pool operators serving major pharmaceutical wholesalers. Distribution feeds from wholesale pharmaceutical campuses through hub-and-spoke networks into last-mile residential drops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of pilots certified for beyond-visual-line-of-sight drone operations constrains autonomous aerial scaling, concentrating advantage with operators that secured early FAA waiver access. This capability gap separates regional carriers from platform operators capable of rural corridor penetration.
For Market Incumbents: Compound certification depth by pursuing ISO 13485 accreditation alongside existing GDP compliance to defend hospital laboratory contracts against emerging regional carriers. Anchor fleet investment in telematics-equipped refrigerated vehicles ahead of FDA Drug Supply Chain Security Act serialized tracking mandates. Channel control through embedded logistics personnel in hospital supply chain departments protects against consignment inventory displacement.
For New Entrants and Emerging Players: Rural access gaps in Japan's Nagano and Gifu prefectures present white-space opportunity where terrain constraints exclude ground courier density. Autonomous drone corridors to isolated patient populations offer the most penetrable entry vector. Partner with national postal services for regulatory clearance rather than pursuing independent airworthiness certification.
For Investors and Strategic Acquirers: Regional cold-chain operators with existing GDP certification but lacking ISO 13485 represent the target acquisition archetype for consolidation plays. Long-term viability hinges on regulatory adaptability across diverging FDA and EMA documentation requirements. Watch FAA beyond-visual-line-of-sight waiver approval velocity as the inflection indicator for autonomous platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Expansion | EMA multi-year telemetry log requirements pull fleet investment toward compliant infrastructure. |
| ISO 13485 Accreditation | Hospital and laboratory contract eligibility rotates around medical device quality management certification. |
| Autonomous Platform Partnership | FAA waiver bottlenecks favor alliance structures over independent drone operator development. |
| Consignment Inventory Integration | Implantable device manufacturers embed logistics personnel to transfer carrying risk from hospitals. |
| Real-Time Temperature Logging | IoT sensor integration with blockchain documentation displaces paper-based chain-of-custody verification. |
Research Approach
Desk research of FDA enforcement actions, EMA Good Distribution Practice guidelines, and hospital procurement database structures preceded structured interviews with cold-chain logistics directors, hospital supply chain managers, GPO contracts specialists, and autonomous platform regulatory leads. Secondary validation drew from FAA waiver filings, pharmaceutical wholesaler SEC disclosures, and EU F-Gas Regulation implementation reports. Bottom-up shipment volume modeling triangulated against top-down pharmaceutical distribution revenue estimates.
Variance decomposition across delivery mode, product temperature sensitivity, and end-user certification requirements shaped the analytical framework throughout the forecast period. Modeled segmentation dimensions included same-day versus scheduled velocity tiers, 2-8°C biologics against ambient consumables, and home healthcare against hospital network destination types. CAGRs derived from pharmaceutical wholesale growth trajectories, hospital-at-home reimbursement expansion curves, and cold-chain fleet capacity addition pipelines.
Forecasts assume regulatory continuity in FDA Drug Supply Chain Security Act traceability timelines and EMA GDP documentation regimes; material policy acceleration or relaxation would require re-modeling. Practitioners should keep alternative scenarios live as FAA beyond-visual-line-of-sight waiver velocity and EU refrigerant phase-down schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Combat Dressing Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Wash Bottle Market