
 Healthcare Mobile Computers Market | 2026-2036
Healthcare Mobile Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Mobile Computers Market Foresight
China is fragmenting as domestic manufacturers expand assembly capacity for medical-grade tablets and handheld scanners. Zebra Technologies dominates enterprise mobility deployments across acute care networks through its specialized printer-integrated workstation lines. Honeywell International Inc. competes in ruggedized data collection hardware with sustained investment in disinfectant-ready housing materials. Panasonic Holdings Corporation anchors premium clinical tablet supply through its controlled distribution of fanless, sealed-enclosure designs for sterile environments.
Healthcare mobile computers are purpose-built computing devices engineered with antimicrobial surfaces, IEC 60601-1 electrical safety compliance, and drop-resistant chassis rated for repeated sanitization cycles; they enable real-time electronic health record access, barcode medication administration, and bedside diagnostic connectivity. Handheld devices occupy the largest installed base due to their portability during nurse rounding and specimen collection workflows, while tablets capture expanding margin pools as telemedicine application requirements drive larger-screen form factors. Wearable devices represent the fastest-growing product category, though from a smaller base, as ambient clinical monitoring and hands-free documentation protocols gain traction in surgical suites and long-term care facilities.
FDA 510(k) clearance pathways shape hardware design requirements for devices touching diagnostic or therapeutic workflows, while HIPAA security standards mandate encryption modules that restrict vendor eligibility to suppliers with certified key-management architectures. The EU MDR and CE marking framework impose additional electromagnetic compatibility and biocompatibility testing burdens on models sold into European hospital systems. Stakeholders must monitor evolving interoperability mandates from ONC and comparable national health IT bodies, as these standards will determine which connectivity stacks—RFID, Wi-Fi 6E, or private 5G—become embedded in next-generation procurement specifications.
Market Dynamics
Hospital procurement cycles are compressing as integrated delivery networks consolidate vendor relationships around single-platform enterprise mobility architectures, forcing hardware suppliers to certify across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- FDA 510(k) clearance pathways:Accelerated device approvals for barcode medication administration systems are expanding the addressable installed base across acute care networks in the United States.
- Wi-Fi 6E and private 5G:New spectrum allocations are enabling real-time diagnostic imaging transmission at bedside, eliminating workstation tethering requirements in surgical suites.
- HIPAA security rule updates:Encryption mandates for endpoint devices are disqualifying consumer-grade hardware from hospital procurement lists, concentrating demand on certified medical-grade platforms.
Market Restraints
- IEC 60601-1 certification costs:Electrical safety testing for clinical environments adds substantial fixed cost per SKU, compressing margins for mid-tier manufacturers without volume scale.
- Antimicrobial housing material supply:Concentrated sourcing of ionic silver and copper-infused polymers from East Asian chemical suppliers creates input cost volatility and single-source risk.
- EU MDR electromagnetic compatibility requirements:Expanded testing burdens for CE marking are extending product launch timelines by months for devices targeting European hospital systems.
Strategic Opportunities
- Long-term care facility digitization:Skilled nursing facilities in the United States remain underpenetrated for mobile point-of-care deployments relative to acute care hospitals.
- Ambient clinical monitoring convergence:Integration of wearable sensors with handheld documentation platforms is opening new workflow automation protocols in perioperative settings.
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting assembly capacity for medical-grade tablets, creating regional supply alternatives to East Asian manufacturing.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise combining clinical workflow knowledge with RF engineering and cybersecurity architecture remains concentrated at top-tier vendors.
- EHR integration complexity:Proprietary APIs from Epic Systems and Oracle Health require custom middleware development, extending deployment timelines and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Mobile Computers Market |
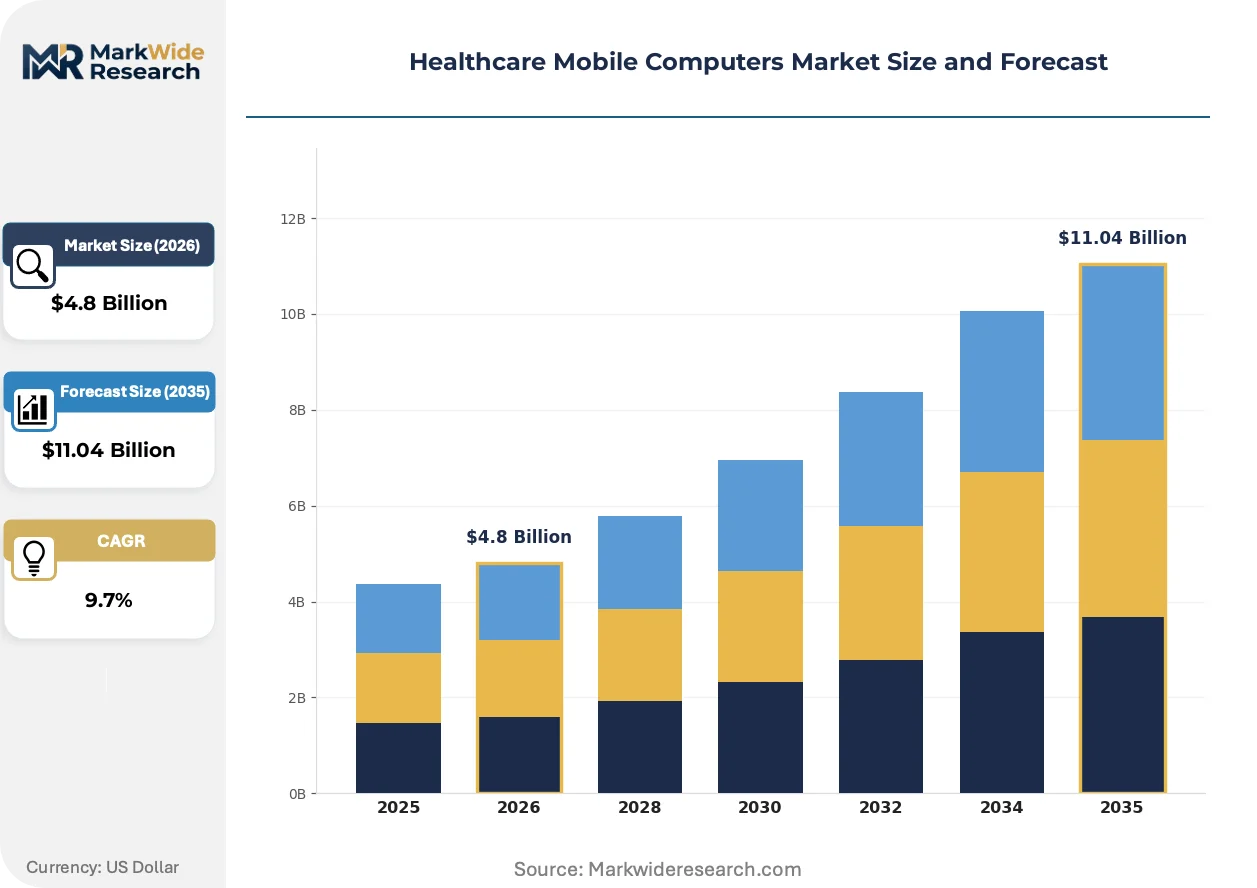
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tablets, Laptops, Wearable Devices Application: Patient Monitoring, Data Collection, Telemedicine, Asset Tracking End User: Hospitals, Clinics, Nursing Homes, Home Healthcare Technology: RFID, Wi-Fi, 4G LTE, Bluetooth |
| Companies Covered | Advantech Co., Ltd., Getac Technology Corporation, Zebra Technologies, DT Research Inc., Hewlett-Packard Enterprise (HPE), Honeywell International Inc., Panasonic Holdings Corporation, Xplore Technologies Corp., Datalogic S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Mobile Computers Market Shifts & Advancements
Hardware form factors are bifurcating as telemedicine requirements demand larger screens while nurse mobility workflows prioritize one-handed operation, forcing suppliers to maintain parallel development tracks.
Fanless sealed-enclosure designs with passive thermal management are rendering obsolete legacy ventilated tablets in sterile environments such as operating rooms and isolation wards. Surgical suites at academic medical centers in Germany and the United States are adopting these fully sealed units to eliminate particulate contamination risks. The technology is compressing the addressable market for conventional ruggedized tablets that rely on active cooling.
EU MDR biocompatibility testing requirements for devices with prolonged skin contact are reshaping wearable device material selection across European hospital systems. Manufacturers must now submit cytotoxicity and sensitization data for wrist-worn and belt-clip form factors. Wearable deployments in long-term care facilities face the steepest compliance burden, with several vendors withdrawing economy-tier SKUs from the European market entirely.
Buyers are consolidating vendor relationships through enterprise-wide framework agreements that bundle hardware, software licenses, and managed services into single-source contracts. Integrated delivery networks in the United States are displacing fragmented departmental purchasing that previously allowed multiple competing device brands within the same hospital. This concentration is most visible among nonprofit health systems in the Midwest and Southeast, where standardization committees now mandate interoperability testing across all new procurements.
Healthcare Mobile Computers Market Segmentation
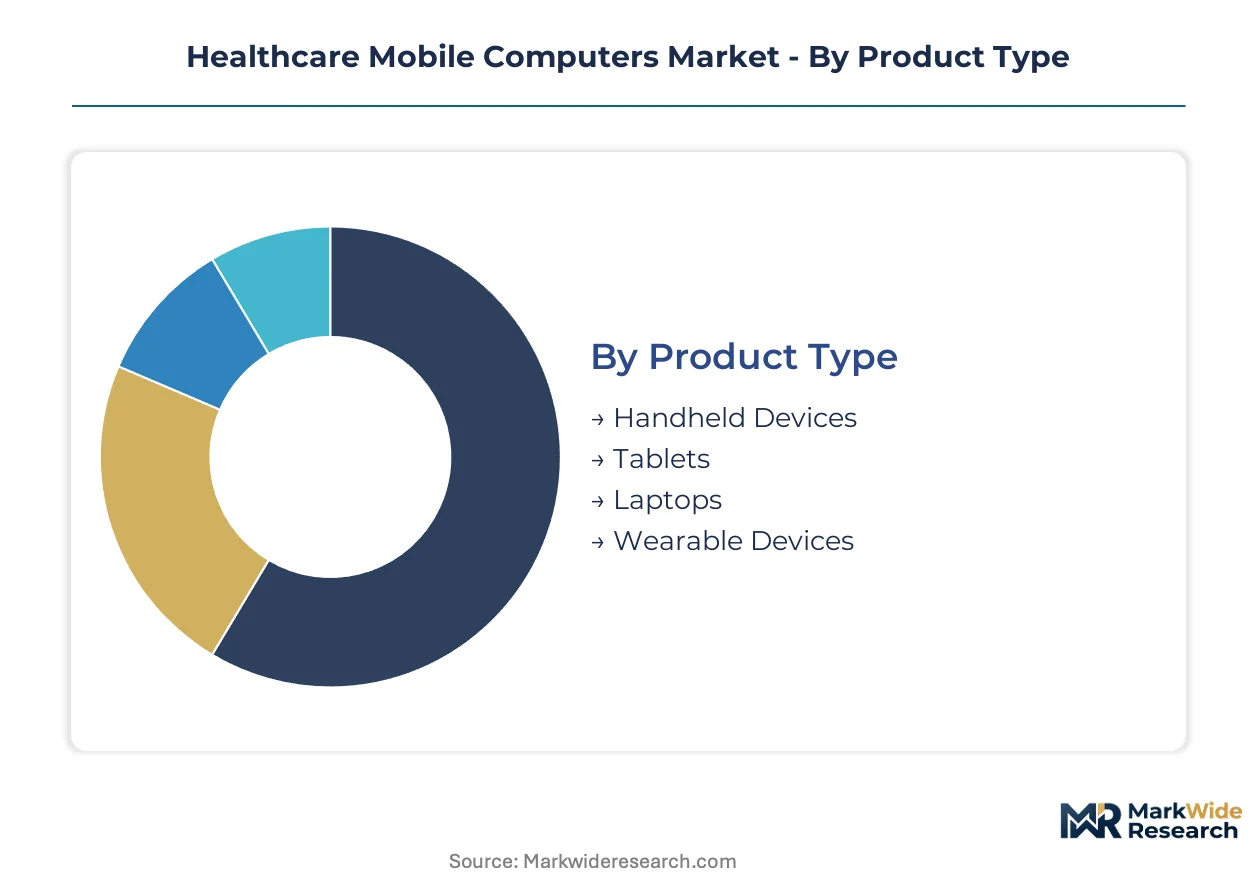
Healthcare mobile computers serve distinct workflow requirements across acute care, ambulatory, and post-acute settings. Segmentation reveals how form factor, connectivity protocol, and care environment dictate procurement specifications and vendor eligibility.
Product Type:
Form factor selection tracks the tension between screen real estate demands and mobility constraints across clinical workflows.
- Handheld Devices:Compact units with integrated barcode scanners and antimicrobial housings dominate nurse rounding and specimen collection workflows. United States acute care networks standardize these for medication administration at the point of care, driven by FDA 510(k) clearance requirements for patient safety applications.
- Tablets:Larger-screen devices with sealed, fanless enclosures support telemedicine consultations and bedside diagnostic imaging review. Demand concentrates in surgical suites and isolation wards where particulate contamination risks eliminate ventilated alternatives, with Germany's academic medical centers adopting these most aggressively.
- Laptops:Full-keyboard units with extended battery life serve clinical documentation and administrative workstations. Hospital IT departments in integrated delivery networks deploy these for back-office and non-patient-facing roles where IEC 60601-1 compliance is less critical.
- Wearable Devices:Wrist-worn and belt-clip sensors enable hands-free documentation and ambient monitoring in perioperative and long-term care settings.
Established volume favors handheld devices; emerging adoption favors wearable devices.
Application:
Clinical use cases determine hardware durability, connectivity, and regulatory certification requirements.
- Patient Monitoring:Continuous vital sign capture and alert generation demand devices with persistent wireless connectivity and IEC 60601-1 electrical safety compliance. Intensive care units in the United States deploy these for real-time telemetry integration, constrained by FDA device classification timelines.
- Telemedicine:Video consultation and remote diagnostic workflows require high-resolution cameras, larger displays, and HIPAA-compliant encryption modules. Post-pandemic reimbursement permanence in the United States has locked in procurement budgets for dedicated telemedicine tablets across rural health systems.
- Data Collection:Barcode scanning and electronic health record documentation drive the largest installed base of handheld units.
- Asset Tracking:Real-time location services for medical equipment and supplies leverage RFID and Bluetooth beacon technologies.
Procurement scale concentrates in patient monitoring; steepest expansion trajectory appears in telemedicine.
End User:
Care setting maturity determines infrastructure readiness and total cost of ownership calculations.
- Hospitals:Acute care networks with capital budgets for enterprise mobility architectures drive premium medical-grade hardware demand. United States integrated delivery networks consolidate vendor relationships through framework agreements spanning multiple facilities, displacing fragmented departmental purchasing.
- Nursing Homes:Long-term care facilities remain underpenetrated relative to acute care, with skilled nursing operators in the United States now digitizing medication administration and resident monitoring workflows.
- Clinics:Ambulatory settings prioritize cost-optimized hardware with sufficient durability for high-frequency sanitization cycles.
- Home Healthcare:Distributed care models require consumer-grade durability with clinical-grade security and connectivity.
Capital deployment depth favors hospitals; penetration runway favors nursing homes.
Technology:
Connectivity protocol selection shapes real-time capability, infrastructure investment, and cybersecurity architecture.
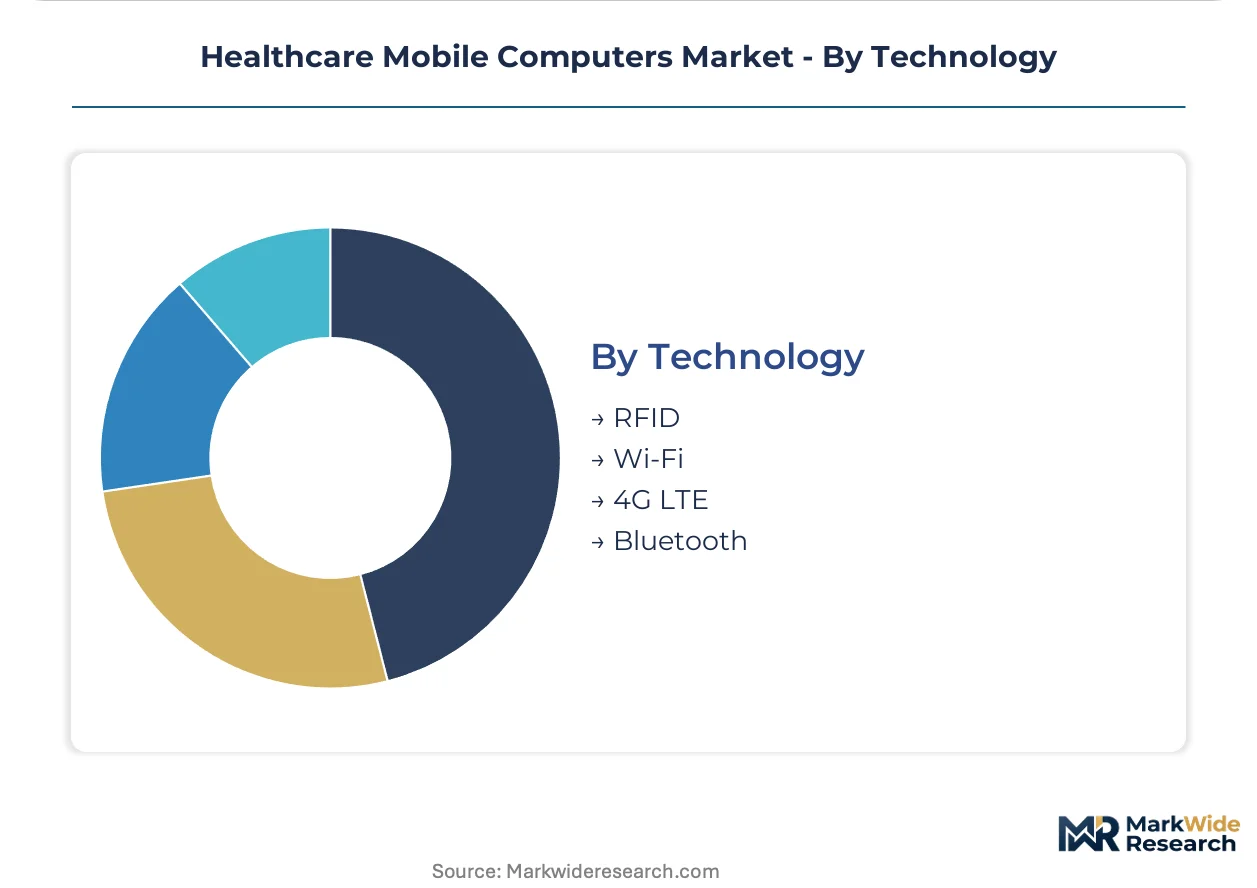
- Wi-Fi:Hospital-grade 6E implementations enable high-throughput diagnostic imaging transmission and eliminate workstation tethering in surgical suites. United States health systems prioritize Wi-Fi 6E for its spectrum separation from congested legacy bands, though infrastructure refresh cycles constrain deployment velocity.
- RFID:Passive and active radio-frequency identification supports asset tracking, patient identification, and medication verification without line-of-sight requirements. European hospital systems embed RFID alongside barcode workflows to satisfy EU MDR traceability mandates.
- 4G LTE:Cellular connectivity enables ambulatory and home healthcare applications beyond hospital network perimeters.
- Bluetooth:Low-energy protocols support wearable device pairing and proximity-based location services.
Installed base dominance sits with Wi-Fi; emerging protocol investment flows toward RFID.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classification requirements and HIPAA security rule updates anchor procurement acceleration in the United States, while EU MDR electromagnetic compatibility mandates reshape European vendor eligibility. Hospital systems across Germany, China, India, and Japan are deploying divergent connectivity architectures.
United States
Integrated delivery networks in the Midwest and Southeast are consolidating enterprise mobility architectures through framework agreements spanning multiple facilities. FDA 510(k) clearance pathways for barcode medication administration systems compress procurement cycles for hardened, encrypted hardware platforms. Academic medical centers in Boston and the Research Triangle are piloting private 5G networks for real-time diagnostic imaging transmission at bedside.
Germany
Academic medical centers are adopting fanless, sealed-enclosure tablets most aggressively to eliminate particulate contamination risks in surgical suites. EU MDR biocompatibility testing requirements for devices with prolonged skin contact are reshaping wearable device material selection across hospital systems. The Baden-Württemberg medical technology cluster around Stuttgart is concentrating supplier engineering resources for IEC 60601-1 electrical safety compliance.
China
Domestic manufacturers are expanding assembly capacity for medical-grade tablets and handheld scanners, fragmenting supply concentration. NMPA medical device registration requirements are extending product launch timelines for international vendors seeking market access. The Yangtze River Delta manufacturing corridor around Shanghai and Suzhou is capturing regional supply chain migration from East Asian chemical suppliers of antimicrobial housing materials.
India
Production-linked incentives under the PLI scheme for electronics manufacturing are attracting assembly capacity for medical-grade tablets, creating regional supply alternatives. CDSCO medical device rules are tightening quality management system requirements for imported hardware platforms. The Karnataka technology corridor around Bangalore is concentrating biomedical engineering talent for RF engineering and cybersecurity architecture development.
Japan
PMDA quality management system requirements are sustaining premium positioning for domestic medical-grade hardware manufacturers. METI standards for electromagnetic compatibility in clinical environments are determining which connectivity stacks become embedded in next-generation procurement specifications. The Kansai medical device cluster around Osaka is specializing in disinfectant-ready housing materials for repeated sanitization cycles.
Healthcare Mobile Computers Market Competitive Landscape
Enterprise mobility specialists and ruggedized hardware manufacturers split the market into distinct capability tiers. Hospital procurement consolidation around single-platform architectures favors vendors with certified key-management architectures across multiple regulatory jurisdictions simultaneously. Two strategic archetypes dominate: integrated workstation suppliers with printer-integrated lines, and sealed-enclosure specialists for sterile environments. Competitive moves concentrate on backward integration into antimicrobial material supply and geographic certification expansion.
Within the integrated workstation tier, Zebra Technologies and Honeywell International Inc. exemplify scale-driven positioning through enterprise mobility deployment depth. Panasonic Holdings Corporation anchors the sealed-enclosure specialist archetype for fanless clinical tablet supply. These three entities represent the concentration of certified medical-grade platform supply as HIPAA encryption mandates disqualify consumer-grade hardware from hospital procurement lists.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Getac Technology Corporation |
| Zebra Technologies |
| DT Research Inc. |
| Hewlett-Packard Enterprise (HPE) |
| Honeywell International Inc. |
| Panasonic Holdings Corporation |
| Xplore Technologies Corp. |
| Datalogic S.p.A. |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor's container cost volatility feeds directly into antimicrobial polymer pricing tiers, compressing margins for mid-tier manufacturers while amplifying differentiation power for certified medical-grade suppliers with captive material sourcing.
Pricing Analysis
Price spreads between United States and East Asian procurement markets exceed forty percent for equivalent IEC 60601-1 certified handheld units. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, volume scale, and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are expanding assembly capacity. Nursing homes and ambulatory clinics exhibit the highest price sensitivity; academic medical centers in Germany and the United States demonstrate the lowest.
Supply Chain Analysis
Extended payment terms from East Asian chemical suppliers now stretch to one hundred twenty days for ionic silver and copper-infused polymer procurement. Manufacturing concentrates in China, Taiwan, and South Korea for display panels and battery cells; Mexico and Vietnam are emerging as secondary assembly locations. The chain draws from concentrated East Asian sources for antimicrobial housing materials and semiconductor components. Single-source vulnerability in ionic silver supply creates exposure to input cost volatility. Distribution runs through integrated delivery network framework agreements and GPO contracts in the United States, direct hospital procurement in Germany, and regional distributor networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat structure where HIPAA encryption mandates and FDA 510(k) clearance pathways create entrenched switching costs that protect incumbent positions while raising barriers for unqualified entrants.
For Market Incumbents: Pre-empt domestic Chinese manufacturer expansion by accelerating backward integration into antimicrobial polymer supply and securing exclusive framework agreements with Midwest and Southeast integrated delivery networks before procurement consolidation completes. Threat vectors include NMPA-registered Chinese entrants offering equivalent IEC 60601-1 certification at compressed price points. Priority levers center on captive supply of ionic silver-infused housing materials and simultaneous FDA-EU MDR-CDSCO certification investment.
For New Entrants and Emerging Players: Establish a beachhead in United States skilled nursing facilities, where mobile point-of-care penetration lags acute care hospitals by substantial margins and procurement committees lack standardization mandates. The long-term care segment offers the most penetrable white space due to delayed digitization timelines and fragmented purchasing authority. Go-to-market execution should emphasize telemedicine-ready tablet bundles with simplified EHR middleware pre-configuration.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial ruggedized hardware parents seeking to divest non-core medical divisions lacking HIPAA-compliant encryption architectures. Long-term viability over the coming decade rests on regulatory certification breadth rather than unit cost position. Acquisition focus should center on mid-tier sealed-enclosure specialists with incomplete FDA submission pipelines. The signal to monitor is CDSCO quality management system enforcement tightening, which would disqualify import-dependent competitors and concentrate supply among certified domestic assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Barcode medication administration clearance compresses procurement cycles for acute care networks. |
| EU MDR CE Marking Pathway | Biocompatibility testing investment preserves European hospital system access against withdrawal risk. |
| Hospital System Partnership | Framework agreements with integrated delivery networks displace fragmented departmental purchasing. |
| Software Companion Development | Epic Systems and Oracle Health middleware integration reduces deployment timeline friction. |
| Reimbursement Strategy | Telemedicine tablet procurement locks in post-pandemic CMS reimbursement permanence. |
Research Methodology
The analysis maps handheld devices, tablets, wearables, and laptop form factors, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and clinical workflow specialists. Primary interviews with these stakeholders combined secondary validation through FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up unit deployment estimates triangulated against top-down healthcare IT capital expenditure aggregates.
Assumptions held fixed include HIPAA security rule enforcement intensity, FDA device classification pathway timelines, and Wi-Fi 6E infrastructure refresh velocity across United States health systems; variables included India PLI scheme subsidy uptake rates and EU MDR biocompatibility testing burden evolution. Segmentation dimensions modeled encompass product form factor, clinical application, care setting maturity, and connectivity protocol across the projection horizon. CAGR derivation anchored in historical procurement cycle analysis and vendor shipment disclosures, with forecast inputs incorporating EHR integration complexity indices and antimicrobial material cost trajectories.
Sensitivities concentrate around NMPA registration timeline acceleration for Chinese manufacturers, EU MDR electromagnetic compatibility requirement expansion, and private 5G network deployment velocity at academic medical centers. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure investment continuity. Macroeconomic contraction affecting hospital capital budgets, regulatory deviation in device classification pathways, or technological disruption in ambient clinical monitoring would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Donor Management Software Market