
 Breathing Exercise Devices Market | 2026-2036
Breathing Exercise Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Breathing Exercise Devices Market Analysis
Market Context with Strategic Players
Respiratory therapist workforce shortages in post-acute settings is rotating demand toward simpler, patient-operated devices that reduce clinical supervision hours. Teleflex Incorporated leverages its hospital supply chain relationships to sustain placement across integrated delivery networks. POWERbreathe International Limited specializes in electronic inspiratory muscle trainers that differentiate its portfolio from basic mechanical alternatives. Smiths Medical anchors its position through critical care channel control and long-term contracts with pulmonary rehabilitation centers.
Technical Definition and Structural Segments
Breathing exercise devices are instruments designed to strengthen respiratory muscles, improve lung capacity, or maintain airway patency through controlled airflow resistance or volume-guided inhalation, typically constructed from medical-grade plastics or silicone with flow-calibrated valves or electronic pressure sensors. These devices serve clinical rehabilitation, athletic performance conditioning, and anxiety management applications where voluntary breathing modulation produces measurable physiological outcomes. Handheld mechanical units dominate volume due to low unit cost and minimal training requirements, while electronic devices capture disproportionate margin pools through Bluetooth connectivity and app-based training protocols. The incentive spirometer segment remains mature in surgical recovery settings, whereas stress relief and relaxation use cases among fitness enthusiasts represent the fastest-growing demand category.
Regulatory Frame and Forward-Looking Close
The FDA's 510(k) clearance framework for Class II respiratory devices governs market entry in the United States, while the EU MDR and CE marking requirements shape conformity assessment for European distribution. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain design and manufacturing processes for electronic device variants. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classification as connected breathing trainers incorporate algorithmic coaching features.
Market Dynamics
Respiratory therapist workforce shortages in post-acute settings are rotating demand toward simpler, patient-operated devices that reduce clinical supervision hours. This structural force compresses training requirements while elevating the importance of intuitive device design and remote monitoring capabilities across rehabilitation protocols.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The Class II medical device framework accelerates market entry for electronic breathing trainers with Bluetooth connectivity, enabling faster product cycles than pharmaceutical alternatives.
- Home-Based Respiratory Therapy Programs:United States healthcare systems are scaling outpatient pulmonary rehabilitation, creating pull for portable incentive spirometers that patients operate without clinical supervision.
- Silicone Valve Manufacturing:Advances in medical-grade elastomer processing reduce per-unit production costs for mechanical flow-resistance devices, expanding addressable volume in price-sensitive segments.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Petroleum-derived silicone and specialized thermoplastics expose manufacturers to input price swings that compress margin pools on entry-level mechanical units.
- Supply Concentration in East Asian Electronics:Pressure sensor and Bluetooth module fabrication clusters in Shenzhen and Taipei create geographic vulnerability for electronic device variants.
- EU MDR Conformity Assessment Burden:The expanded clinical evidence requirements for Class IIa respiratory devices extend European launch timelines by 12-18 months versus pre-2017 CE marking processes.
Strategic Opportunities
- Underpenetrated Indian Pulmonary Rehabilitation:India's CDSCO regulatory streamlining under the 2017 Medical Device Rules creates whitespace for incentive spirometer adoption in tier-2 hospital networks.
- Algorithmic Coaching Convergence:Integration of respiratory pressure sensors with machine learning coaching protocols opens subscription revenue models distinct from hardware sales.
- Direct-to-Consumer Athletic Channels:Fitness e-commerce platforms and endurance sports specialty retailers represent underexploited distribution for inspiratory muscle trainers targeting cyclists and swimmers.
Industry Challenges
- Respiratory Therapist Talent Scarcity:Post-acute facilities face persistent hiring gaps for credentialed pulmonary specialists, forcing device manufacturers to absorb patient education responsibilities.
- ISO 13485 Certification Timeline:Quality management system audits for electronic device variants require 9-14 month preparation cycles that delay commercial launch schedules.
- Legacy EMR Integration Complexity:Bluetooth-enabled breathing trainers encounter interoperability friction with hospital electronic medical record systems, complicating remote monitoring deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathing Exercise Devices Market |
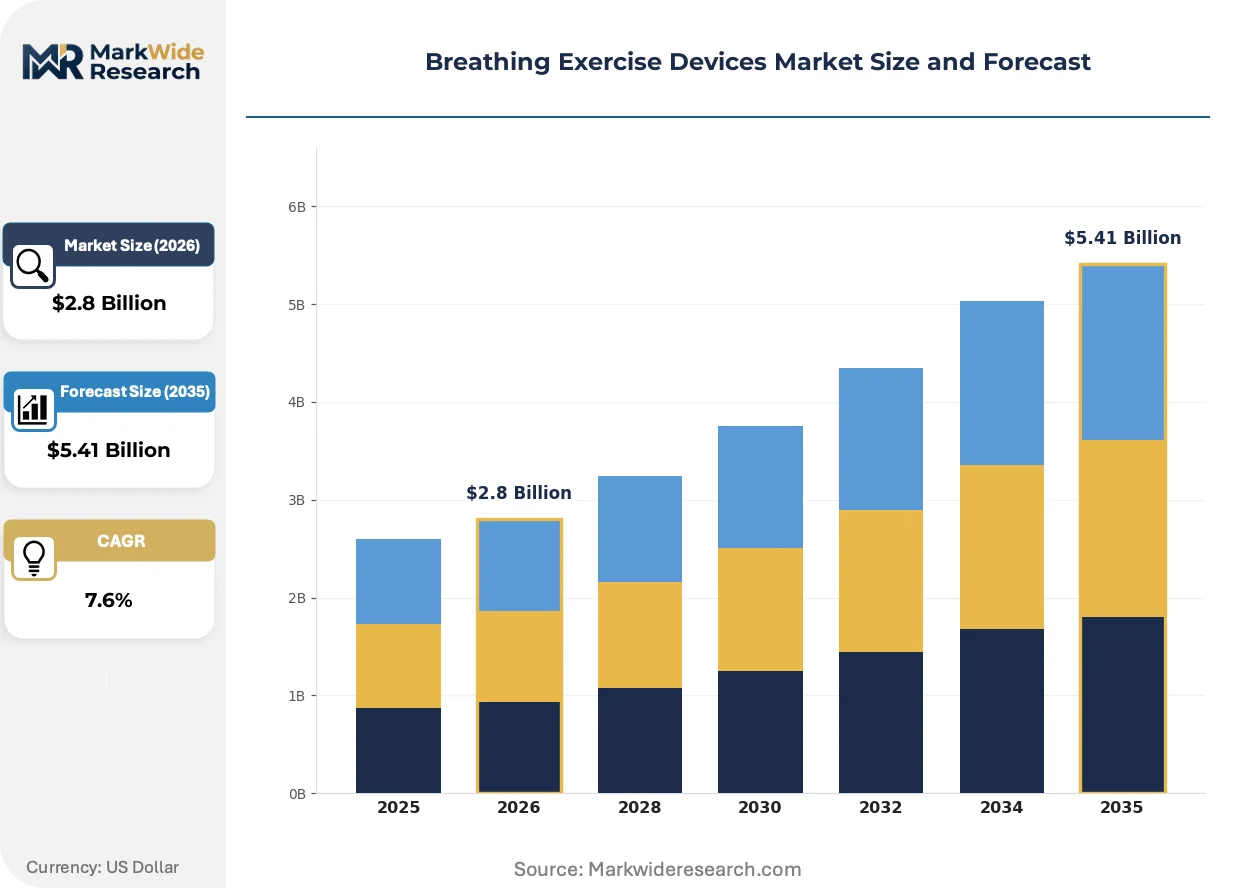
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Handheld, Electronic, Pursed Lip, Incentive Spirometer Target User: Athletes, Patients, Fitness Enthusiasts, Elderly Use Case: Rehabilitation, Exercise Training, Relaxation, Stress Relief Material: Plastic, Silicone, Metal, Glass |
| Companies Covered | Teleflex Incorporated, Nidek Medical India, Becton Dickinson, Boen Healthcare, Wintersweet Medical, Cardinal Health, POWERbreathe International Limited, Beijing Konted Medical Technology, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathing Exercise Devices Market Emerging Trajectories
Connected respiratory hardware is redefining competitive differentiation as manufacturers race to embed software capabilities that transform one-time device sales into recurring revenue relationships. This shift elevates firmware development and data security competencies alongside traditional mechanical engineering expertise.
Electronic pressure-sensing inspiratory trainers with real-time biofeedback displays are supplanting basic mechanical threshold-load devices in athletic conditioning programs. Collegiate sports medicine departments and professional cycling teams are adopting these units at accelerating rates. The technology is supplanting subjective breathing effort perception with quantifiable training load metrics that enable periodized respiratory muscle programming.
The EU MDR's intensified post-market surveillance requirements for Class IIa respiratory devices are forcing manufacturers to rebuild clinical evidence portfolios. Device companies must now maintain systematic literature reviews and vigilance reporting systems that exceed pre-2021 CE marking obligations. Electronic breathing trainer portfolios face the steepest compliance cost escalation due to their software-as-a-medical-device classification uncertainties.
Hospital procurement committees are consolidating vendor relationships for respiratory therapy equipment around integrated delivery networks that span multiple facilities. Group purchasing organizations are displacing individual hospital contracting for incentive spirometers and pulmonary rehabilitation systems. This concentration is most visible in United States integrated delivery networks where standardization across 10-50 facility footprints drives volume commitments to single-source suppliers.
Breathing Exercise Devices Market Segmentation
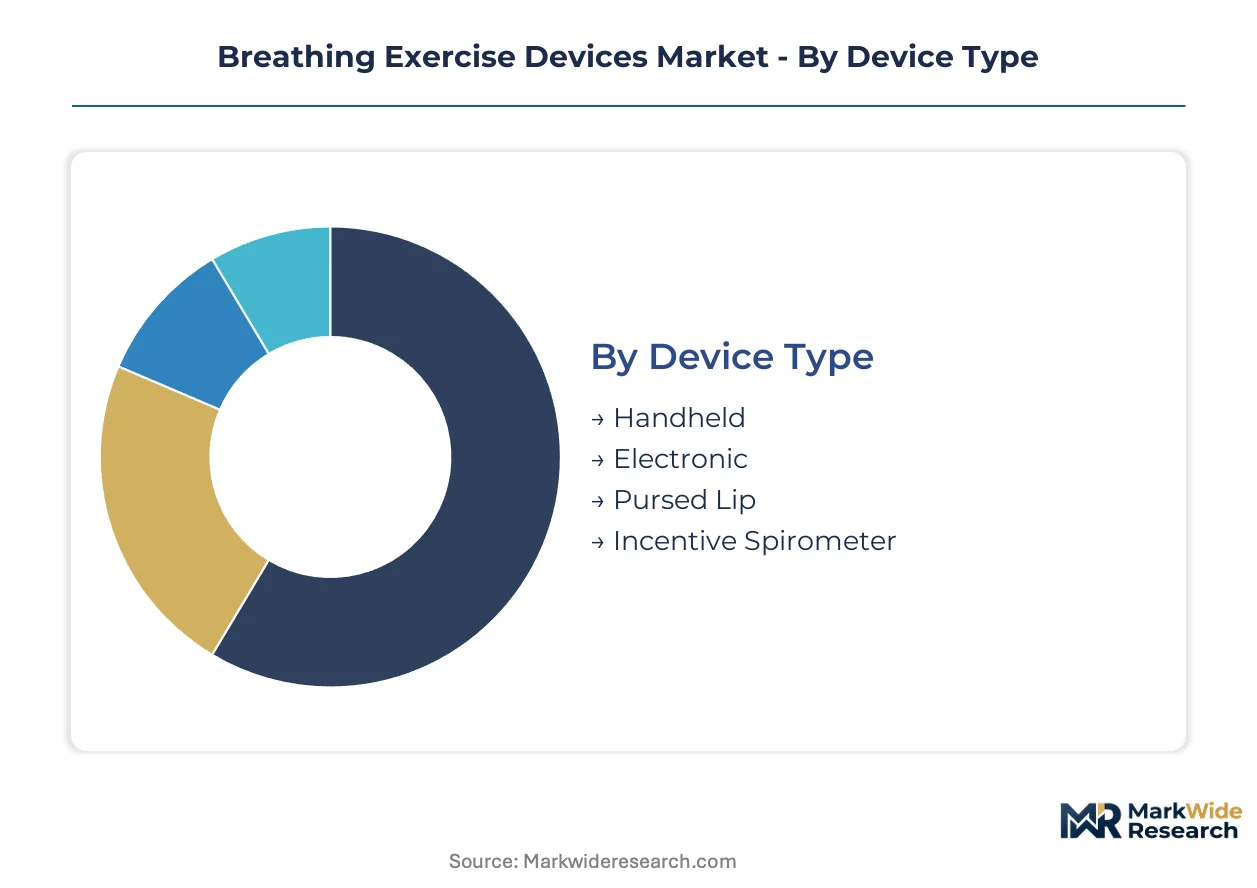
Channel strategy for breathing exercise devices diverges sharply between clinical procurement committees and direct-to-consumer platforms. Understanding which segments flow through hospital supply chains versus fitness e-commerce determines pricing architecture and regulatory investment priorities for manufacturers.
Device Type:
Hospital supply chains favor mechanical units with minimal training overhead, while athletic conditioning programs pull electronic variants through specialty retail and direct-to-consumer channels.
- Handheld:Constructed from injection-molded medical-grade plastics with fixed-orifice flow resistance mechanisms. Post-acute facilities in the United States rotate procurement toward these units as respiratory therapist shortages elevate self-operated device requirements.
- Electronic:Pressure-sensing inspiratory trainers with Bluetooth connectivity and algorithmic biofeedback displays. Collegiate sports medicine departments and professional cycling teams drive demand concentration as quantifiable respiratory muscle training displaces subjective effort perception.
- Pursed Lip:Simple flow-resistance devices requiring no calibration or power source. Home-based COPD management programs distribute these through durable medical equipment suppliers.
- Incentive Spirometer:Volume-guided inhalation trainers with calibrated chambers and one-way valves. Surgical recovery protocols in integrated delivery networks sustain placement through group purchasing organization contracts.
Handheld mechanical units dominate installed base across post-acute and home settings. Electronic pressure-sensing variants are where expansion concentrates as athletic conditioning and remote monitoring applications mature.
Target User:
Cost tier separation is pronounced: patients access devices through insurance-reimbursed clinical channels while fitness enthusiasts and athletes purchase at full retail through e-commerce and specialty sporting goods.
- Athletes:Inspiratory muscle trainers with periodized load progression capabilities. Triathlon and competitive swimming cohorts in the United States and Australia demonstrate highest willingness-to-pay for connected training protocols.
- Patients:Prescribed incentive spirometers and threshold-load devices for post-surgical pulmonary rehabilitation. Medicare reimbursement pathways in the United States shape product specification requirements for this segment.
- Fitness Enthusiasts:Stress relief and breathwork practitioners seeking portable relaxation tools. Wellness e-commerce platforms and meditation app partnerships drive discovery for this cohort.
- Elderly:Simplified mechanical devices with large-print instructions and minimal assembly. Home health agencies and geriatric care coordinators influence procurement decisions for this demographic.
Patient populations represent the deepest volume pool through reimbursed clinical channels. Athletic users are climbing the fastest as sports science validation expands addressable market beyond traditional medical indications.
Use Case:
Application maturity varies: rehabilitation carries established reimbursement codes while relaxation and stress relief operate in emerging wellness categories without comparable payer infrastructure.
- Rehabilitation:Post-surgical pulmonary recovery and COPD maintenance protocols with documented clinical outcomes requirements. United States integrated delivery networks standardize incentive spirometer selection across facility footprints.
- Exercise Training:Respiratory muscle conditioning for endurance performance with quantifiable training load metrics. Professional cycling teams and collegiate swimming programs validate technology adoption for this application.
- Relaxation:Breathwork and parasympathetic activation for anxiety management without clinical supervision. Corporate wellness programs and meditation platform integrations expand distribution for this use case.
- Stress Relief:Portable biofeedback devices for workplace and travel contexts. Direct-to-consumer marketing through fitness influencers drives awareness in this segment.
Rehabilitation commands the steepest volume concentration through hospital procurement. Relaxation applications are gaining share fastest as wellness expenditure displaces traditional healthcare spending patterns.
Material:
Supply concentration and cost tier alignment differ: petroleum-derived polymers expose manufacturers to input volatility while silicone and specialized elastomers command premium positioning.
- Plastic:ABS and polycarbonate injection-molded housings for entry-level mechanical devices. Price-sensitive volume segments in India and Southeast Asia favor these constructions.
- Silicone:Medical-grade elastomer valves and mouthpiece seals with biocompatibility certification. FDA 510(k) clearance pathways in the United States elevate material documentation requirements for this category.
- Metal:Stainless steel flow-control mechanisms in high-durability clinical settings. Long-term care facilities prioritize these constructions for multi-patient reuse protocols.
- Glass:Borosilicate chamber components in precision-calibrated incentive spirometers. European manufacturers under EU MDR conformity assessment favor these materials for post-market surveillance traceability.
Plastic constructions dominate unit economics at scale. Silicone elastomer components are where margin expansion concentrates as regulatory documentation becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes breathing exercise devices primarily through reimbursed clinical channels for post-surgical recovery, while Germany and Japan favor precision-engineered units for athletic conditioning, and India represents emerging volume through tier-2 hospital network expansion.
United States
Medicare reimbursement pathways for home-based pulmonary rehabilitation and respiratory therapist workforce shortages drive demand for patient-operated incentive spirometers. The FDA's 510(k) clearance framework governs Class II device market entry timelines. Integrated delivery networks in Texas and Florida standardize procurement across multi-facility footprints through group purchasing organization contracts.
Germany
Professional cycling teams and collegiate sports medicine departments pull electronic pressure-sensing trainers for quantifiable respiratory muscle programming. The EU MDR conformity assessment requirements extend launch timelines versus pre-2017 CE marking processes. Medical device engineering clusters in Baden-Württemberg concentrate precision manufacturing for silicone valve components.
Japan
Aging demographics and COPD prevalence sustain demand for simplified mechanical devices in home health settings. The PMDA medical device registration pathway shapes product specification requirements for domestic distribution. Tokyo-based rehabilitation equipment distributors anchor procurement relationships with long-term care facility networks.
India
Tier-2 hospital network expansion and pulmonary rehabilitation program scaling create whitespace for incentive spirometer adoption. The CDSCO regulatory streamlining under the 2017 Medical Device Rules reduces import clearance friction. Manufacturing cost advantages in Gujarat and Maharashtra attract contract production for entry-level plastic construction units.
China
Domestic production of medical-grade polymers and pressure sensor modules supports cost-competitive electronic device fabrication. The NMPA Class II medical device registration requirements align with international quality benchmarks. Shenzhen electronics clusters concentrate Bluetooth module and sensor fabrication for connected breathing trainer variants.
Breathing Exercise Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital supply chain incumbents controlling procurement relationships across integrated delivery networks while athletic-focused innovators capture premium positioning through connected training protocols. The competitive terrain separates into three archetypes: diversified medical device conglomerates with critical care channel control, dedicated respiratory specialists with electronic muscle training expertise, and regional fabricators serving price-sensitive volume segments. Dominant competitive moves include backward integration into silicone valve manufacturing and strategic partnerships with fitness e-commerce platforms for direct-to-consumer distribution.
Among diversified medical device conglomerates, Teleflex Incorporated and Smiths Medical exemplify the integrated leader archetype through hospital supply chain relationships and long-term pulmonary rehabilitation center contracts. POWERbreathe International Limited occupies a specialist position focused on electronic inspiratory muscle trainers. Beijing Konted Medical Technology represents the regional fabricator tier serving cost-optimized market segments.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Nidek Medical India |
| Becton Dickinson |
| Boen Healthcare |
| Wintersweet Medical |
| Cardinal Health |
| POWERbreathe International Limited |
| Beijing Konted Medical Technology |
| Smiths Medical |
| Others |
Supply Flow & Price Mechanics
Long-term group purchasing organization contracts with United States integrated delivery networks lock in multi-year pricing visibility for incentive spirometer suppliers while securing dedicated production capacity from silicone valve manufacturers in Baden-Württemberg and medical-grade polymer processors in Gujarat. These arrangements insulate established vendors from spot-market volatility in petroleum-derived inputs while compressing margin flexibility for new entrants seeking hospital procurement access.
Pricing Analysis
Contract-based long-term offtake dominates hospital procurement, with three-tier pricing structure across premium electronic trainers, standard mechanical units, and economy plastic constructions. Price differentiation hinges on FDA 510(k) clearance tier and Bluetooth connectivity certification. Cost compression in entry-level mechanical segments is intensifying because Indian contract manufacturers are expanding ABS injection-molding capacity. Fitness enthusiasts purchasing through direct-to-consumer channels demonstrate lowest price sensitivity, while tier-2 hospital networks in emerging markets drive hardest volume negotiations.
Supply Chain Analysis
Inventory buffers for pressure sensors and Bluetooth modules stretch to 16-22 weeks as fabrication clusters in Shenzhen and Taipei face capacity constraints. Component sourcing draws from China for electronics, Germany for precision silicone valves, and India for injection-molded housings. Single-source vulnerability concentrates in Taiwan semiconductor foundries supplying respiratory pressure transducers. Distribution runs through hospital supply chain incumbents for clinical segments and fitness e-commerce platforms for athletic conditioning applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) clearance and EU MDR conformity assessment creates formidable defensive moats for established players, as certification timelines and clinical evidence requirements deter rapid competitive replication. Switching costs for integrated delivery networks consolidating vendor relationships reinforce incumbent positioning.
For Market Incumbents: Consolidate procurement relationships across expanding United States integrated delivery network footprints before respiratory therapist workforce shortages accelerate vendor consolidation. Deepen backward integration into medical-grade silicone valve production to defend margin pools against Indian contract manufacturer price competition. Prioritize firmware development capabilities to capture recurring revenue from algorithmic coaching subscriptions.
For New Entrants and Emerging Players: Differentiate on connected training protocols for triathlon and competitive swimming cohorts where sports science validation commands premium positioning. Target India's tier-2 hospital networks as regulatory streamlining under CDSCO Medical Device Rules lowers import clearance friction. Pursue fitness e-commerce platform partnerships to bypass entrenched hospital supply chain gatekeepers.
For Investors and Strategic Acquirers: Electronic respiratory muscle training specialists with proprietary pressure-sensing algorithms and established athletic channel relationships represent priority acquisition targets for medical device conglomerates seeking premium positioning outside reimbursed clinical segments. Monitor FDA guidance evolution on software-as-a-medical-device classification as inflection indicator for connected trainer revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market entry for electronic breathing trainers with Bluetooth connectivity versus pharmaceutical alternatives. |
| CE Marking Pathway | EU MDR conformity assessment extends European launch timelines but creates regulatory differentiation against non-compliant competitors. |
| Hospital System Partnership | Group purchasing organization contracts with Texas and Florida integrated delivery networks lock in multi-facility volume commitments. |
| Software Companion Development | Algorithmic coaching integration transforms one-time device sales into recurring subscription revenue relationships. |
| Reimbursement Strategy | Medicare pathway alignment for home-based pulmonary rehabilitation shapes product specification requirements for patient segment. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Interviews with respiratory therapists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers informed demand-side dynamics. Trade data from Indian CDSCO import registrations and Chinese NMPA device approvals anchored supply-side validation. Bottom-up unit economics modeling and top-down macroeconomic trend analysis provided cross-verification.
Segmentation dimensions modeled include device type, target user archetype, use case application, and material construction across the projection horizon. CAGRs derive from regression analysis against respiratory therapist workforce trends, surgical procedure volumes, and athletic conditioning program adoption curves. Electronic pressure-sensing trainer penetration rates and silicone valve manufacturing cost trajectories served as category-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance velocity, EU MDR post-market surveillance stability, or petroleum-derived polymer cost regimes would require recalibration. Forecasts reflect documented assumptions regarding reimbursement pathway continuity and Bluetooth module supply chain resilience. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Medical Electronics Market
Medical Devices
Active Wheelchair Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Pharma Robots Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Wrist Fixator Procedure Kit Market