
 Global Surgical Kits Market | 2026-2036
Global Surgical Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Kits Market Foresight
Modular kit configurations is broadening buyer choice across acute care settings. Medtronic leverages its integrated device portfolio to anchor comprehensive cardiac procedure bundles. Cardinal Health competes through distribution scale and same-day replenishment networks in North America. Johnson & Johnson (Ethicon) differentiates via suture-integrated kits that reduce intraoperative instrument handling.
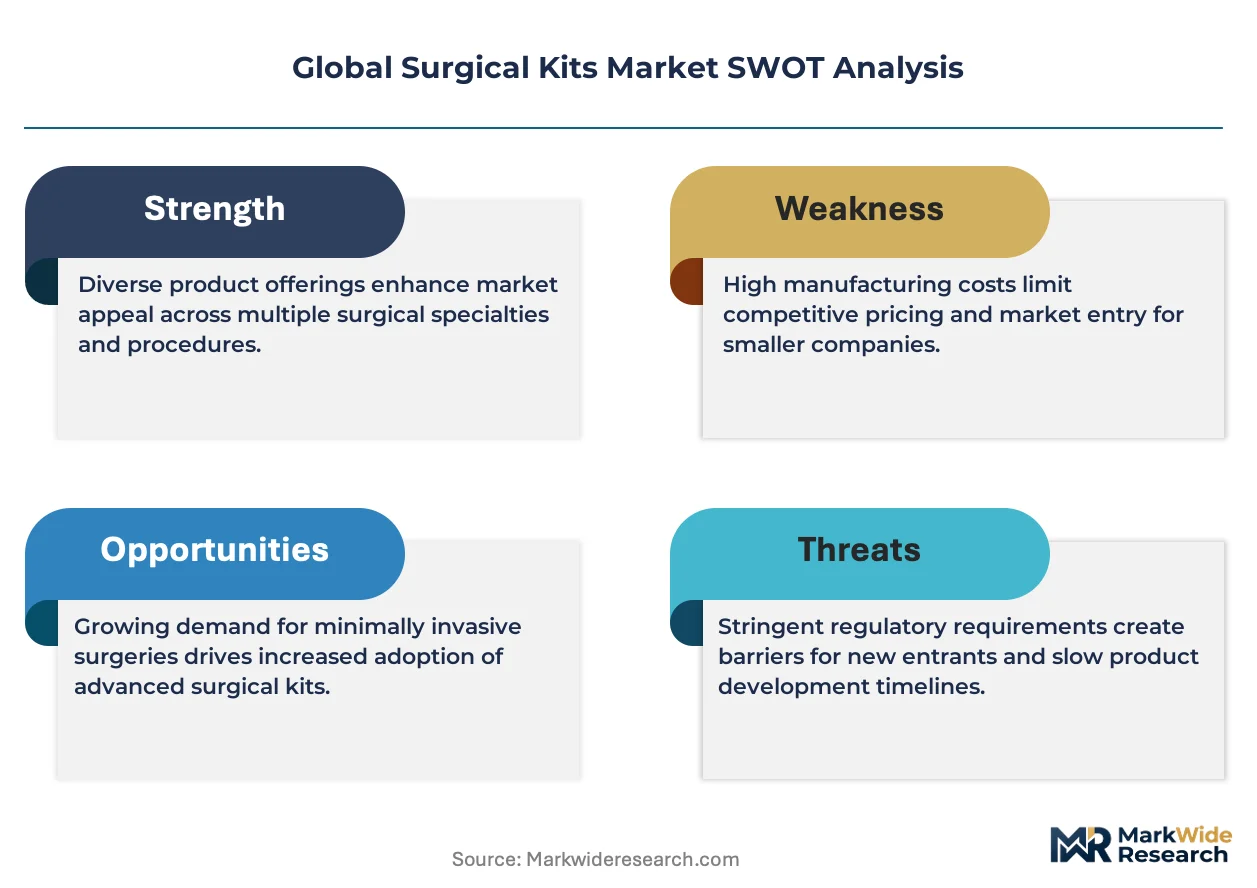
A surgical kit is a pre-assembled, sterile collection of instruments, drapes, and consumables packaged for a specific operative procedure, typically including items ranging from scalpels and forceps to suction tubing and wound closure materials, manufactured under ISO 13485 quality systems and validated for sterility assurance levels. Its primary purpose is to reduce preparation time, minimize surgical site infection risk, and standardize supply chain workflows in operating rooms. Specialty kits command premium positioning due to procedure-specific customization and higher barrier-to-entry manufacturing, while disposable kits represent the fastest-expanding product type as facilities prioritize infection control and eliminate reprocessing costs. Ambulatory surgical centers are emerging as a concentrated demand node where space constraints favor compact, single-use configurations over reusable alternatives.
The FDA enforces sterile barrier and biocompatibility standards under 21 CFR Part 820, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for kit classification and post-market surveillance. ISO 11607 governs packaging validation globally, creating compliance costs that favor manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving MDR transition timelines and FDA guidance on combination product kits to anticipate certification bottlenecks and reposition supply agreements accordingly.
Market Dynamics
Hospital consolidation and centralized procurement mandates are compressing vendor relationships into fewer, larger contracts that favor manufacturers with integrated supply chains and multi-site service capabilities.
Growth Catalysts
- EU MDR sterile barrier mandates:The Medical Device Regulation's updated packaging validation requirements are accelerating facility transitions from reusable to disposable kit formats.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are driving demand for compact, procedure-specific configurations that minimize storage footprint.
- RFID-enabled inventory tracking:Real-time consumption monitoring is converging with automated replenishment systems to reduce waste and stockout incidents.
Market Restraints
- Medical-grade polymer cost volatility:Specialized barrier films and Tyvek alternatives face input price swings tied to petrochemical feedstock markets.
- Single-source sterilization capacity:Gamma and ethylene oxide sterilization services concentrate among a limited number of contract providers in Germany and the United States.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies create multi-month delays for novel material introductions.
Strategic Opportunities
- India's hospital infrastructure buildout:Government-funded medical cities and tier-2 facility upgrades create first-mover advantages for standardized kit suppliers.
- Robotic surgery accessory bundling:Instrument sets tailored to da Vinci and competing platforms represent unpenetrated attach-rate potential.
- Japan's PMDA fast-track pathway:The Sakigake designation accelerates regulatory timelines for kits incorporating breakthrough sterilization technologies.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs are extending quality management system renewal cycles by four to six months.
- Legacy ERP integration with track-and-trace systems:Hospital materials management platforms require costly middleware development to interface with UDI-compliant kit databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Kits Market |
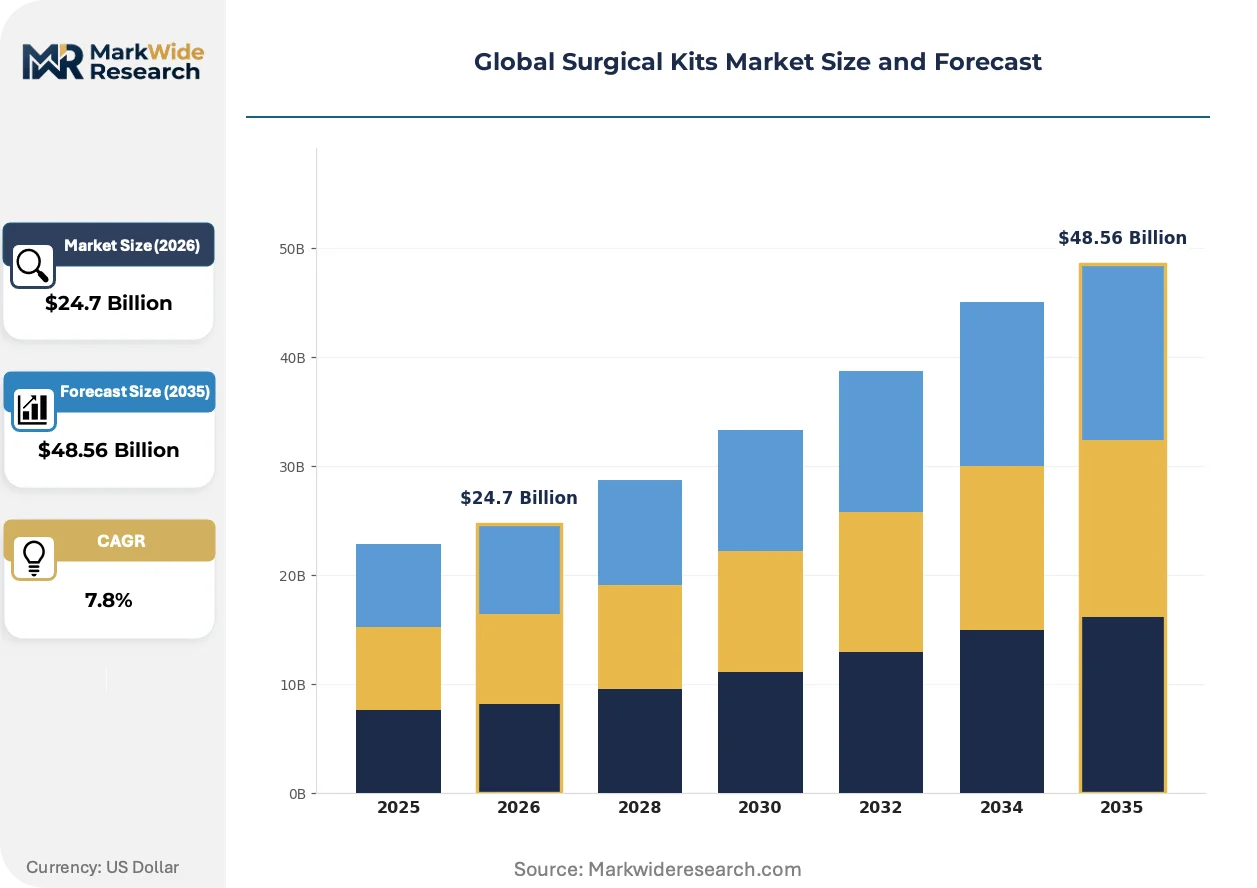
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $48.56 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Kits, Specialty Kits, Emergency Kits, Disposable Kits, Reusable Kits Application: Orthopedic Procedures, Cardiovascular Surgery, General Surgery, Neurosurgery, Plastic Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Trauma Centers, Outpatient Facilities Distribution Channel: Direct Sales, Medical Supply Distributors, Online Platforms, Retail Pharmacies, Group Purchasing Organizations |
| Companies Covered | Medline Industries, Medtronic, Johnson & Johnson (Ethicon), Cardinal Health, B. Braun Melsungen AG, Stryker, Boston Scientific Corporation, Smith & Nephew, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Kits Market Shifts & Advancements
Digital integration and sustainability pressures are redefining how surgical kits are specified, validated, and consumed across acute care networks. Three developments dominate the transformation trajectory.
Smart packaging embedded with temperature and humidity sensors is converging with blockchain-verified chain-of-custody records. Major hospital systems in Germany and the Netherlands are piloting these hybrid formats for high-value cardiac and orthopedic sets. This convergence is compressing liability exposure and enabling outcome-based supplier contracts that tie payment to sterile integrity documentation.
China's NMPA issued draft guidance in late 2024 tightening clinical evidence requirements for kits containing combination products. Domestic manufacturers must now submit procedure-specific usability studies alongside traditional biocompatibility data. Cardiovascular and neurosurgical kit categories face the steepest compliance ramps, with several provincial tenders already excluding products lacking the new documentation.
Group purchasing organizations are consolidating supplier panels and mandating kit standardization across member facilities. This behavioral shift displaces hospital-level customization in favor of regional contracts with limited SKU variability. The United Kingdom's NHS Supply Chain exemplifies this pattern, where four national frameworks now cover 80 percent of elective procedure volumes.
Global Surgical Kits Market Segmentation
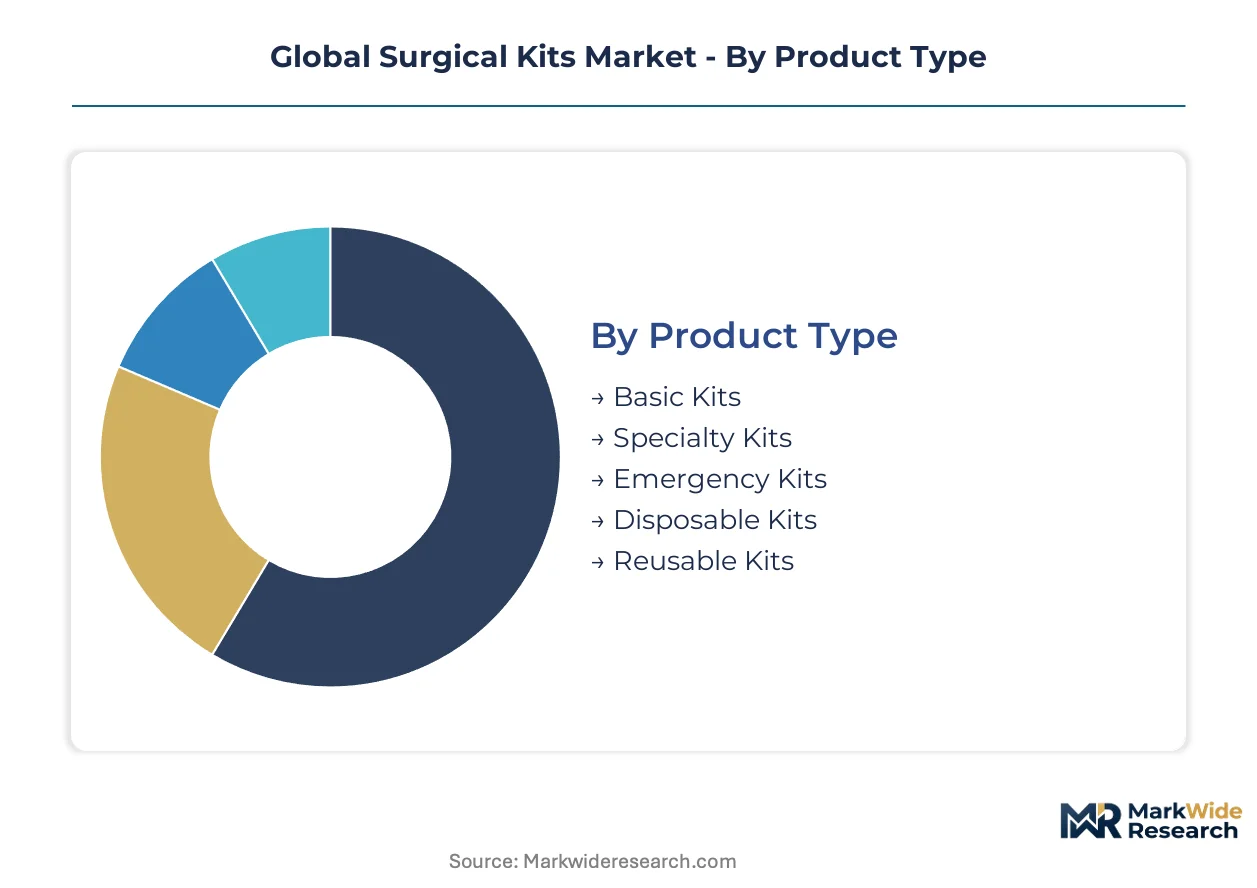
Surgical kit segmentation reveals divergent cost structures and regulatory burdens across product formats. Procedure complexity and sterility requirements create distinct margin profiles that reshape procurement priorities across acute care networks.
Product Type:
Volume concentration sits with standardized configurations, while premium positioning attaches to procedure-specific customization and validated barrier systems.
- Basic Kits:Standardized instrument assemblies for routine procedures including scalpels, forceps, drapes, and suction components. Demand clusters in India's tier-2 hospital upgrades and Vietnam's provincial health system expansions where procurement budgets prioritize cost containment over customization.
- Specialty Kits:Procedure-dedicated configurations engineered for cardiac, orthopedic, or neurosurgical workflows with instrument-matched layouts and validated sterile barriers. Germany's consolidated hospital networks and Japan's university medical centers concentrate procurement here, driven by ISO 11607 packaging mandates and outcome-based supplier contracts.
- Emergency Kits:Rapid-deployment sterile packs for trauma and resuscitation scenarios with abbreviated instrument counts.
- Disposable Kits:Single-use configurations eliminating reprocessing infrastructure and cross-contamination pathways.
- Reusable Kits:Stainless steel instrument sets requiring centralized sterilization capacity and quality management systems.
Today's leader: Specialty Kits. Tomorrow's challenger: Disposable Kits.
Application:
Procedure reimbursement rates and instrument complexity determine kit specification intensity across surgical disciplines.
- Orthopedic Procedures:Implant-accompanying instrument sets with torque drivers, reamers, and trial components matched to specific prosthesis geometries. ASCs in the United States and Germany's DRG-funded hospitals anchor demand, pressured by CMS and BfArM cost transparency mandates that bundle device and kit reimbursement.
- Cardiovascular Surgery:High-value configurations incorporating cannulae, needle holders, and vessel loops with temperature-stable packaging for bypass and valve procedures. Japan's PMDA Sakigake fast-track pathway and China's NMPA combination product guidance are accelerating regulatory differentiation for sterilization-innovative suppliers.
- General Surgery:Versatile laparotomy and appendectomy configurations with broad instrument applicability.
- Neurosurgery:Micro-instrument sets with bayonet forceps and fine dissectors requiring precision packaging.
- Plastic Surgery:Aesthetic and reconstructive kits with delicate tissue handling instruments.
Cardiovascular Surgery commands premium positioning. Orthopedic Procedures are climbing the fastest as ASC volume expands.
End User:
Facility scale and case throughput dictate inventory models and supplier relationship structures.
- Hospitals:High-volume purchasers with centralized materials management and multi-procedure standardization mandates. NHS Supply Chain frameworks in the United Kingdom and Germany's hospital consolidation wave are compressing vendor panels toward integrated suppliers with multi-site service capabilities.
- Ambulatory Surgical Centers:Space-constrained facilities favoring compact, single-use configurations with minimal storage footprint and rapid turnover protocols. United States freestanding ASCs are displacing reusable alternatives fastest, supported by CMS site-neutral payment policies.
- Clinics:Limited-procedure settings with sporadic surgical volume and distributor-dependent replenishment.
- Trauma Centers:24-hour readiness requirements driving emergency kit stockpiling and redundancy protocols.
- Outpatient Facilities:Same-day discharge settings with simplified instrument needs and direct-to-procedure logistics.
Hospitals retain procurement dominance. Ambulatory Surgical Centers are gaining share fastest on regulatory tailwinds.
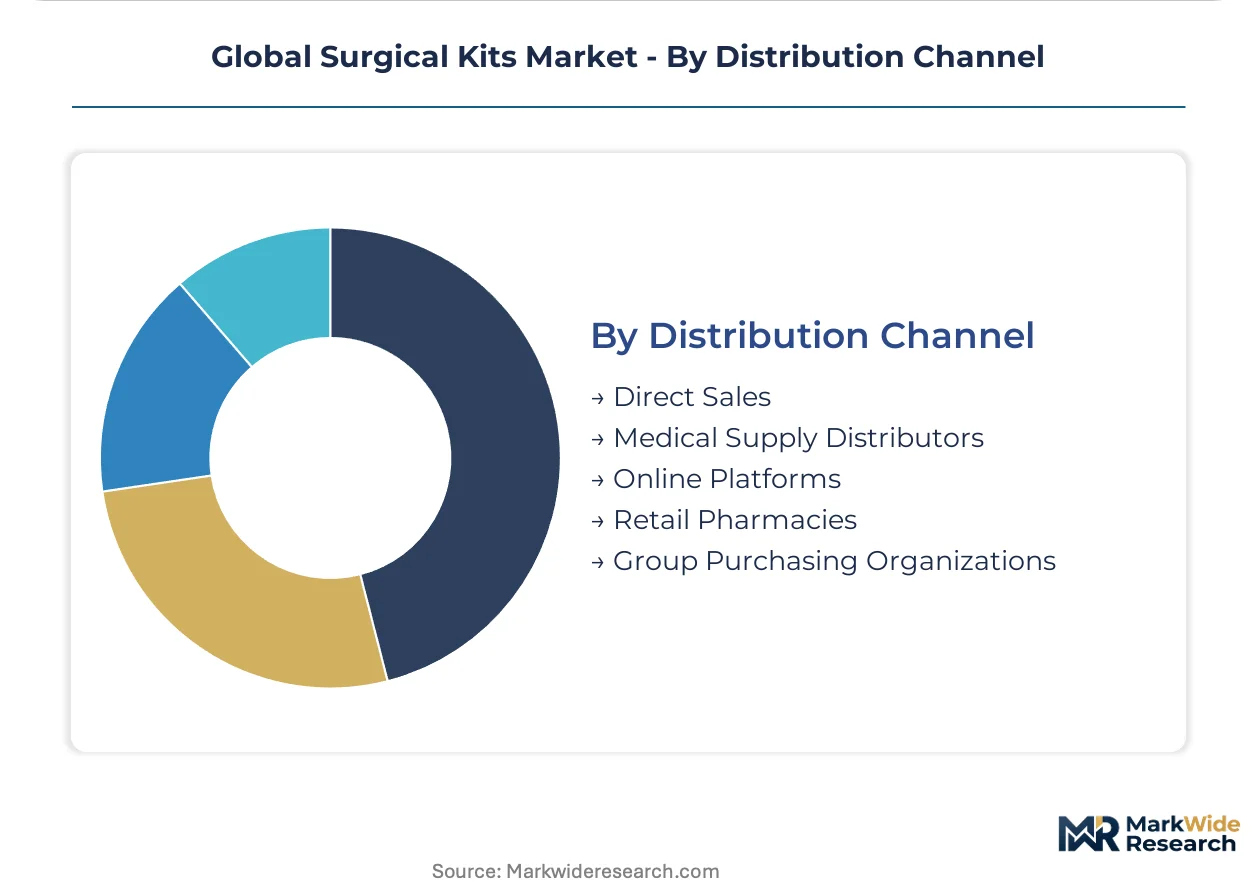
Distribution Channel:
Channel selection reflects buyer scale, geographic concentration, and integration with hospital ERP systems.
- Direct Sales:Manufacturer-to-facility relationships for high-volume accounts with dedicated field service and consignment inventory. Medtronic and Johnson & Johnson deploy this model for cardiac and suture-integrated kits across United States integrated delivery networks.
- Group Purchasing Organizations:Consolidated contracting vehicles standardizing specifications across member facilities. NHS Supply Chain national frameworks and Premier, Inc. panels in the United States now cover dominant elective procedure volumes.
- Medical Supply Distributors:Regional fulfillment networks with same-day replenishment capabilities.
- Online Platforms:Digital procurement portals for smaller facilities and emergency restocking.
- Retail Pharmacies:Limited surgical supply presence concentrated in wound care and minor procedure kits.
Group Purchasing Organizations are consolidating control. Direct Sales retains strategic accounts through service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical kit manufacturing originated in Germany and the United States during the post-war standardization of operating room protocols, with these markets retaining concentrated expertise in sterile barrier engineering and regulatory compliance infrastructure.
United States
Freestanding ambulatory surgical centers in Florida and Texas are displacing reusable kit formats fastest, driven by CMS site-neutral payment policies that compress reimbursement differentials between hospital and outpatient settings. The FDA enforces 21 CFR Part 820 quality system regulations with heightened scrutiny of ethylene oxide sterilization residuals. Cardinal Health operates same-day replenishment hubs from its distribution centers in Ohio and Arizona to serve integrated delivery networks.
Germany
Hospital consolidation in North Rhine-Westphalia and Bavaria is concentrating procurement through centralized purchasing cooperatives that mandate ISO 11607-validated packaging. The BfArM cost transparency initiative bundles device and kit reimbursement, pressuring suppliers toward outcome-based contracting. B. Braun Melsungen AG anchors specialty kit production from its manufacturing cluster in Hessen, supplying consolidated hospital networks across the Rhineland.
China
Provincial medical city construction in Sichuan and Jiangsu is creating first-mover opportunities for standardized disposable kits as tier-2 facilities upgrade from reusable instruments. The NMPA issued draft guidance in late 2024 tightening clinical evidence requirements for combination product kits, with cardiovascular and neurosurgical categories facing steepest compliance ramps. Domestic manufacturers in the Yangtze River Delta are retooling sterile barrier lines to meet the new documentation standards.
Japan
University medical centers in Tokyo and Osaka concentrate demand for premium cardiovascular and orthopedic kits with temperature-stable packaging validated for extended shelf life. The PMDA Sakigake fast-track designation accelerates regulatory timelines for kits incorporating breakthrough sterilization technologies, rewarding early filers with priority review. Johnson & Johnson leverages this pathway to anchor suture-integrated kit portfolios across Kanto region hospitals.
India
Government-funded medical cities in Gujarat and Karnataka are driving standardized kit procurement as tier-2 facility upgrades prioritize infection control over cost containment. The CDSCO harmonizes with ISO 13485 quality systems while state-level tenders increasingly specify disposable formats to eliminate reprocessing infrastructure gaps. Medline Industries has established distribution partnerships from Mumbai to serve emerging hospital clusters in Maharashtra and Telangana.
Global Surgical Kits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sterile barrier validation capability and integrated supply chain scale, with the market consolidating around three structural tiers. Integrated device manufacturers anchor the top tier through procedure-specific bundling, while distribution-scale operators compete on replenishment velocity and multi-site service coverage. Specialists in single-use configurations occupy a growing mid-tier as infection control priorities displace reusable alternatives. Dominant competitive moves include backward integration into sterilization capacity and strategic partnerships with group purchasing organizations to secure national framework positioning.
Within the integrated device manufacturer tier, Medtronic and Johnson & Johnson (Ethicon) exemplify archetypes that leverage proprietary instrument portfolios to anchor comprehensive procedure bundles. Cardinal Health represents the distribution-scale vector, competing through replenishment network density rather than manufacturing integration. Among European specialists, B. Braun Melsungen AG occupies a position bridging sterile barrier engineering expertise with hospital system consolidation tailwinds in its domestic market.
| Leading Market Players |
|---|
| Medline Industries |
| Medtronic |
| Johnson & Johnson (Ethicon) |
| Cardinal Health |
| B. Braun Melsungen AG |
| Stryker |
| Boston Scientific Corporation |
| Smith & Nephew |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 11607-validated specialty kits and commodity disposable formats manifests in both pricing power and supply chain architecture across Germany, the United States, and Japan. Premium-tier manufacturers capture margin through sterile barrier engineering expertise while standard-kit suppliers compete on polymer input costs and sterilization throughput efficiency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates surgical kit procurement, with ISO 13485 certification grade and barrier film performance specifications as primary differentiation drivers. Cost compression in standard disposable formats is intensifying because of medical-grade polymer feedstock volatility tied to petrochemical markets. Ambulatory surgical centers exhibit highest price sensitivity due to CMS site-neutral reimbursement constraints, while university medical centers in Japan and Germany show lowest sensitivity when temperature-stable packaging extends shelf life.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume integrated delivery network demand, while distributor networks serve fragmented clinic and outpatient facility procurement. Manufacturing concentrates in Germany, the United States, and China, with sterile barrier film production drawing from specialized polymer suppliers in the Rhine-Ruhr region and Yangtze River Delta. Gamma and ethylene oxide sterilization capacity concentrates among contract providers in Germany and the United States, creating single-source vulnerability for manufacturers without captive sterilization assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through disposable format conversion eliminating reprocessing infrastructure costs, while premium-tier positioning rewards sterile barrier innovation and regulatory fast-track navigation.
For Market Incumbents: Anticipate EU MDR packaging validation deadlines by accelerating ISO 11607 certification renewals and securing redundant sterilization capacity before auditor backlogs extend quality management system cycles. Consolidate GPO framework positioning through outcome-based contracting that ties payment to sterile integrity documentation, defending against distribution-scale competitors replenishing on velocity alone.
For New Entrants and Emerging Players: Launch via regional distributor partnerships targeting India's tier-2 hospital infrastructure buildout in Gujarat and Karnataka, where government-funded medical cities prioritize standardized disposable kits over reusable alternatives. Penetrate robotic surgery accessory bundling for da Vinci-compatible instrument sets, an unpenetrated attach-rate segment lacking established kit suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization capacity scarcity meets MDR compliance cost escalation, favoring acquisition of mid-tier manufacturers with validated barrier technologies and underutilized gamma processing lines. Target firms with PMDA Sakigake pathway experience in Japan, watching NMPA combination product guidance implementation in China as inflection indicator for regulatory-differentiated premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607 Packaging Validation | FDA and EU MDR sterile barrier mandates accelerate facility transitions to disposable formats. |
| Backward Integration into Sterilization | Captive gamma and ethylene oxide capacity insulates against single-source contract provider bottlenecks. |
| GPO Framework Partnership | NHS Supply Chain and Premier national contracts standardize specifications across member facilities. |
| RFID-Enabled Inventory Tracking | Real-time consumption monitoring converges with automated replenishment to reduce waste incidents. |
| PMDA Sakigake Fast-Track Filing | Priority review for breakthrough sterilization technologies rewards early regulatory investment in Japan. |
Research Methodology
Bottom-up hospital and ambulatory surgical center demand modeling reconciled against top-down sterile barrier manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterilization service operators combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare cost reports, and ISO 13485 certification registries. Triangulation across these sources anchors volume estimates in observable procurement patterns and regulatory compliance timelines.
Historical trendline analysis of procedure volume growth, kit penetration rates, and disposable format adoption curves informed projection frameworks across product type, application, end user, and distribution channel dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion constraints incorporate surgical procedure reimbursement trajectories, infection control policy shifts, and sterile barrier material cost indices as industry-specific forecast inputs throughout the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR transition timeline delays, ethylene oxide sterilization regulatory restrictions, or medical-grade polymer supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Cryoboxes Market