
 Middle East and North Africa Disposable Gloves Market | 2026-2036
Middle East and North Africa Disposable Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and North Africa Disposable Gloves Market Intelligence
Multi-source procurement is pivoting toward consolidated distributor partnerships across the Middle East and North Africa disposable gloves market. Top Glove Corporation Bhd anchors regional supply through its Malaysian manufacturing scale and established Gulf logistics networks. Hartalega Holdings Berhad differentiates via advanced nitrile formulation capabilities and thin-gauge production lines optimized for clinical sensitivity requirements. Gulf East Paper and Plastic Industries LLC competes on localized warehousing and rapid fulfillment across Saudi Arabia and the UAE.
The Middle East and North Africa disposable gloves category encompasses single-use hand protection manufactured from natural rubber latex, synthetic nitrile, vinyl, or polyethylene, with thickness ratings spanning thin to extra heavy grades and tensile strength parameters dictating barrier integrity against pathogens and chemicals. Nitrile gloves command expanding share due to latex allergy prevalence and superior puncture resistance in surgical and laboratory environments. Medical use applications generate the dominant revenue pool, while food handling segments show accelerated growth tied to hospitality sector hygiene mandates across Dubai and Riyadh. Thickness segmentation reveals heavy-grade industrial gloves carrying higher per-unit margins despite lower volumes.
SFDA in Saudi Arabia, MOHAP in the UAE, and Egypt's national pharmaceutical regulator enforce medical device registration and biocompatibility testing that shapes import eligibility and local distribution requirements. CE marking under the EU MDR influences Gulf procurement specifications even without direct European jurisdiction, as hospital groups benchmark to international standards. Stakeholders must monitor evolving national preference policies and domestic manufacturing incentives that could redirect sourcing patterns away from established Southeast Asian suppliers.
Market Dynamics
Healthcare procurement across Saudi Arabia and the UAE is consolidating from fragmented spot purchasing toward multi-year supply agreements, compressing distributor margins while favoring manufacturers with established Gulf logistics networks and medical-grade certification capabilities.
Growth Catalysts
- SFDA Medical Device Registration:Saudi Arabia's tightening biocompatibility testing requirements for imported gloves is filtering out substandard suppliers and elevating certified manufacturers with established regulatory dossiers.
- Nitrile Formulation Advances:Synthetic nitrile production lines optimized for thin-gauge clinical sensitivity are capturing share from natural rubber latex as Gulf hospital groups prioritize allergen-free alternatives in surgical environments.
- Hospital Infrastructure Expansion:Greenfield medical city developments in Riyadh and Dubai are generating concentrated demand for bulk glove supply contracts with multi-year visibility.
Market Restraints
- Petrochemical Feedstock Volatility:Nitrile butadiene rubber prices fluctuate with crude oil derivatives, compressing margin predictability for manufacturers without backward integration into acrylonitrile supply.
- Southeast Asian Supply Concentration:Malaysian and Thai producers control over 60% of global nitrile glove capacity, exposing Middle East buyers to shipping disruptions through the Strait of Malacca.
- MOHAP Import Documentation Complexity:UAE medical device registration timelines extending beyond 180 days delay market entry for new suppliers lacking established Gulf regulatory affairs teams.
Strategic Opportunities
- Egyptian Manufacturing Incentives:Domestic production subsidies under Egypt's industrial development framework could redirect sourcing from Asian imports toward localized assembly for North African distribution.
- Food Service Mandates:Hospitality sector hygiene regulations in Dubai and Riyadh are expanding glove consumption beyond healthcare into restaurant and catering supply chains.
- CE Marking Alignment:Gulf hospital groups benchmarking procurement specifications to EU MDR standards create pathways for European-certified suppliers to penetrate premium clinical segments without redundant testing.
Industry Challenges
- Regulatory Affairs Talent Scarcity:SFDA and MOHAP submission expertise concentrates in Jeddah and Dubai, creating bottlenecks for manufacturers seeking multi-country Gulf registration.
- Cold Chain Warehouse Requirements:Medical-grade glove storage specifications in Saudi Arabia's extreme heat demand capital-intensive climate-controlled distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and North Africa Disposable Gloves Market |
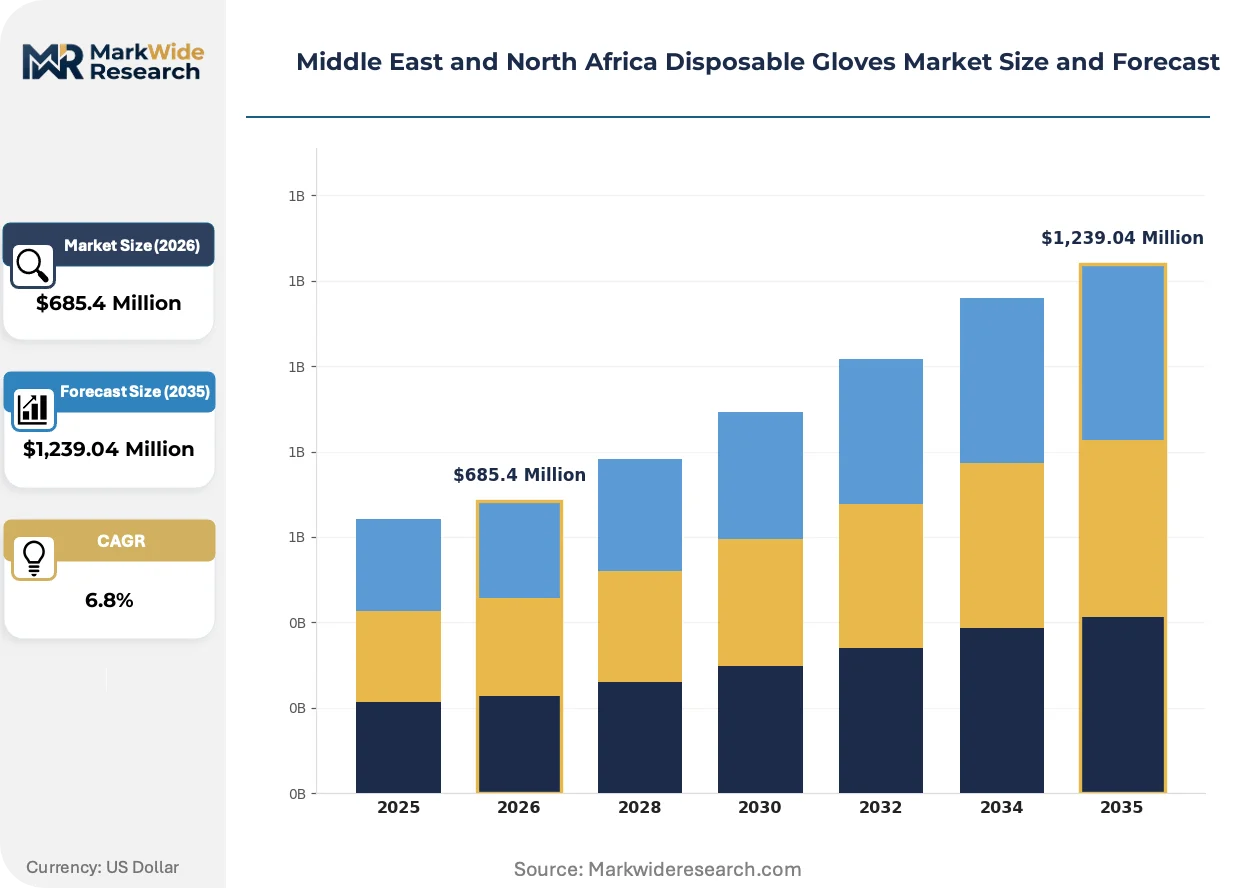
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex Gloves, Nitrile Gloves, Vinyl Gloves, Polyethylene Gloves Application: Medical Use, Industrial Use, Food Handling, Cleaning Applications Thickness: Thin, Medium, Heavy, Extra Heavy Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Kimberly-Clark Corporation, Gulf East Paper and Plastic Industries LLC, Top Glove Corporation Bhd, Hartalega Holdings Berhad, United Medical Industries Co. Ltd., Ansell Ltd., PAUL HARTMANN Middle East FZE, Kossan Rubber Industries Bhd, Cardinal Health, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and North Africa Disposable Gloves Market Strategic Shifts & Innovations
Material science advances and procurement digitization are restructuring competitive advantage in Middle East and North Africa glove supply, with regulatory compliance automation and sustainability metrics emerging as differentiation vectors.
Chlorinated nitrile surface treatment is unifying barrier performance with tactile sensitivity in examination-grade gloves. Saudi surgical centers are adopting these formulations for procedures previously requiring double-gloving. The technology is compressing SKU proliferation by replacing separate standard and high-sensitivity product lines with single versatile grades.
MOHAP's electronic medical device registration portal is accelerating approval timelines for digitized submission packages. UAE distributors are investing in regulatory technology platforms to automate documentation workflows. Smaller manufacturers lacking these capabilities face exclusion from government hospital tenders requiring rapid compliance turnaround.
Buyer consortiums among Dubai's private hospital networks are consolidating purchasing power through centralized procurement platforms. Traditional distributor relationships with individual facilities are yielding to direct manufacturer negotiations with aggregated volume commitments. This concentration is most visible in the UAE's northern emirates, where hospital groups are standardizing glove specifications across multi-site operations.
Middle East and North Africa Disposable Gloves Market Segmentation
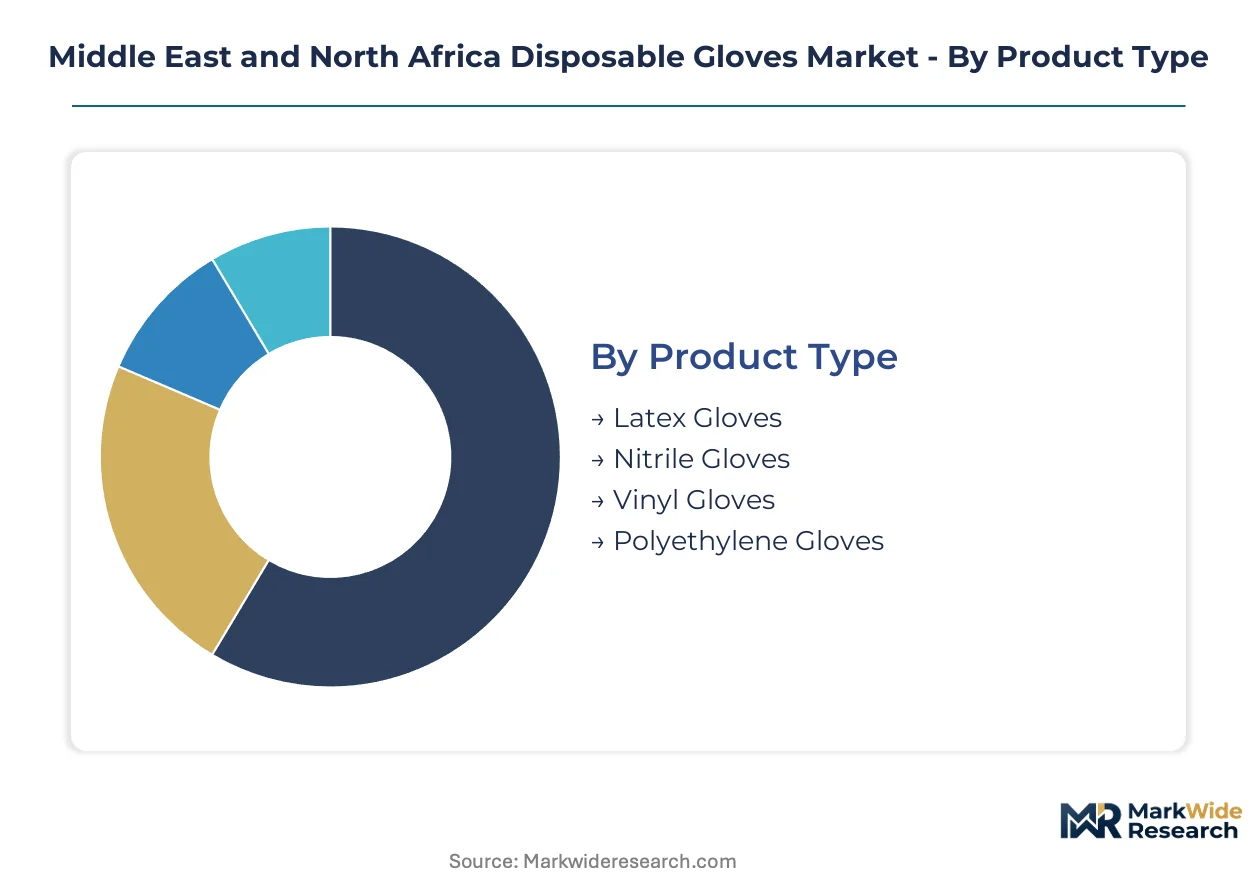
Segmentation in the Middle East and North Africa disposable gloves market reveals how procurement priorities diverge across regulatory environments, climate conditions, and end-use intensity. Buyers in Saudi Arabia and the UAE select specifications that balance SFDA compliance with total cost of ownership under extreme heat storage requirements.
Product Type:
Customization intensity varies sharply across this category, with formulation chemistry dictating both performance ceilings and regulatory pathway complexity.
- Nitrile Gloves:Synthetic acrylonitrile-butadiene formulations deliver superior puncture resistance and eliminate latex protein allergens. Demand concentrates in Saudi surgical centers where SFDA biocompatibility requirements favor nitrile's documented safety profile over natural rubber alternatives.
- Latex Gloves:Natural rubber formulations maintain cost advantages in high-volume examination settings despite declining share. UAE hospital groups are phasing out standard latex in favor of low-protein or synthetic alternatives to reduce occupational allergy incidence among nursing staff.
- Vinyl Gloves:Polyvinyl chloride compounds serve budget-sensitive food handling and light cleaning applications across North African markets where cost minimization outweighs durability requirements.
- Polyethylene Gloves:Cast polyethylene films target single-use food service with minimal barrier demands, prevalent in Dubai's hospitality sector quick-service operations.
Most installed capacity flows through Nitrile Gloves. Expansion is steepest in Nitrile Gloves as Gulf healthcare procurement shifts toward allergen-free synthetic alternatives.
Application:
Volume concentration versus margin capture splits this category, with medical procurement commanding premium pricing while food service generates scale through mandate-driven replacement cycles.
- Medical Use:Surgical and examination applications demand sterile packaging, lot traceability, and tensile strength certification. Riyadh's greenfield medical cities are consolidating procurement into multi-year agreements with manufacturers holding established SFDA dossiers.
- Food Handling:Hospitality sector hygiene mandates in Dubai and Riyadh are expanding glove consumption into restaurant supply chains. MOHAP food safety regulations now require barrier protection for direct food contact across hotel and catering operations.
- Industrial Use:Chemical resistance and cut protection specifications serve petrochemical and manufacturing operations concentrated in Saudi Arabia's Eastern Province industrial zones.
- Cleaning Applications:Janitorial and sanitation services utilize medium-grade disposable protection across commercial facilities, with procurement running through facility management contractors rather than direct hospital purchasing.
Medical Use captures the dominant revenue share. Food Handling is expanding most quickly as Gulf hospitality regulations extend hygiene mandates beyond healthcare.
Thickness:
Performance tiering aligns with risk exposure, where barrier integrity requirements scale with chemical concentration and puncture hazard intensity.
- Heavy:Extra-thick formulations deliver chemical splash protection and extended wear durability for industrial chemical handling. Saudi petrochemical facilities specify heavy-grade nitrile for maintenance operations involving solvent exposure.
- Medium:Standard examination thickness balances tactile sensitivity with adequate barrier protection for routine clinical procedures across UAE hospital networks.
- Thin:Reduced-gauge production lines optimize for surgical precision and extended wear comfort in procedures requiring fine motor control.
- Extra Heavy:Maximum thickness ratings target specialized industrial applications with extreme abrasion or extended immersion requirements, carrying the highest per-unit margins despite limited volume.
Medium thickness dominates unit volume across healthcare procurement. Heavy grade carries the steepest margin expansion trajectory as industrial safety standards tighten.
Distribution Channel:
Channel selection reflects buyer scale and regulatory complexity, with large healthcare systems bypassing intermediaries while fragmented buyers rely on distributor technical support.
- Direct Sales:Manufacturer-to-institution contracts serve Saudi Arabia's Ministry of Health and large UAE hospital groups with dedicated account management and regulatory documentation support. These arrangements compress distributor margins while ensuring lot traceability for SFDA compliance.
- Wholesalers:Regional distributors with climate-controlled warehousing across Jeddah and Dubai aggregate fragmented demand from smaller clinics and independent practices. Cold chain capabilities separate viable medical-grade suppliers from general trade competitors.
- Retail:Pharmacy and medical supply stores serve individual practitioners and small outpatient facilities with immediate availability but limited technical specification guidance.
- Online:E-commerce platforms are penetrating non-medical segments, with Dubai-based procurement platforms gaining traction among restaurant and hospitality buyers seeking standardized food-service grades.
Wholesalers handle the majority of current volume throughput. Direct Sales is gaining share fastest as Gulf healthcare procurement consolidates toward centralized tendering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Eastern Province petrochemical corridor anchors regional demand for heavy-grade industrial gloves, while Dubai's healthcare procurement platforms concentrate Gulf clinical supply negotiations.
Saudi Arabia
Riyadh's greenfield medical cities and Eastern Province industrial zones drive parallel demand streams for clinical and chemical-resistant gloves. SFDA medical device registration requirements filter import eligibility toward manufacturers with established biocompatibility dossiers. Jeddah's climate-controlled distribution hubs handle bulk warehousing for Ministry of Health supply contracts.
United Arab Emirates
Dubai's hospitality sector hygiene mandates and Abu Dhabi's hospital network consolidation expand food-service and clinical glove consumption simultaneously. MOHAP electronic registration portals accelerate approval timelines for digitized submission packages. Sharjah's logistics free zones aggregate Southeast Asian imports for re-export across the Gulf.
Egypt
Cairo's pharmaceutical manufacturing base and Alexandria's port infrastructure position the country for North African distribution hub status. Domestic production subsidies under industrial development frameworks redirect sourcing from Asian imports toward localized assembly. Suez Canal Economic Zone incentives attract glove converting operations for regional supply.
Qatar
Hamad Medical Corporation procurement centralization and FIFA-legacy hospitality infrastructure sustain dual demand channels for medical and food-service grades. National health system tendering favors suppliers with established Gulf regulatory affairs capabilities. Doha's warehousing investments address cold chain requirements for medical-grade storage.
Kuwait
Ministry of Health procurement reform shifts spot purchasing toward multi-year supply agreements with certified manufacturers. Healthcare infrastructure expansion in Ahmadi and Jahra governorates concentrates demand for bulk clinical glove contracts. Kuwait City's distributor networks link to Dubai and Jeddah logistics hubs for inventory replenishment.
Middle East and North Africa Disposable Gloves Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue localized warehousing and rapid fulfillment partnerships. Malaysian and Thai manufacturers anchor supply through scale advantages and established Strait of Malacca shipping lanes. Gulf-based distributors compete on climate-controlled logistics and MOHAP submission expertise. Consolidation pressures favor manufacturers with backward integration into nitrile butadiene rubber supply and multi-country Gulf registration capabilities.
Within the scale-driven tier, Top Glove Corporation Bhd and Hartalega Holdings Berhad represent Southeast Asian manufacturing concentration. Gulf East Paper and Plastic Industries LLC occupies a position among regional distributors with localized fulfillment infrastructure. These three entities exemplify the geographic split between Asian production gravity and Gulf logistics specialization that structures competitive positioning.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Gulf East Paper and Plastic Industries LLC |
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| United Medical Industries Co. Ltd. |
| Ansell Ltd. |
| PAUL HARTMANN Middle East FZE |
| Kossan Rubber Industries Bhd |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Multi-year procurement consolidation by Saudi Arabia's Ministry of Health and large UAE hospital groups is compressing spot-market premiums and forcing suppliers into volume-commitment contracts with thinner margins. This buyer-side concentration elevates manufacturers with backward integration into nitrile butadiene rubber feedstock and established SFDA dossiers, while fragmenting pricing power among distributor-dependent competitors.
Pricing Analysis
Acrylonitrile-butadiene rubber price volatility feeds directly into nitrile glove manufacturing costs, with petrochemical derivative swings compressing margin predictability for non-integrated producers. Pricing stratifies across medical-grade certified, food-service compliant, and industrial economy tiers, with SFDA biocompatibility certification commanding substantial premiums over uncertified alternatives. Cost compression in standard examination grades is intensifying as Malaysian capacity expansions flood Gulf markets with undifferentiated volume. Food-service buyers in Dubai's hospitality sector exhibit highest price sensitivity, while Saudi surgical centers prioritize barrier performance over unit economics.
Supply Chain Analysis
Nitrile butadiene rubber supply rests on Malaysian and Thai petrochemical complexes, with acrylonitrile monomer production concentrated in Northeast Asian refineries. Synthetic rubber formulations, packaging films, and sterilization equipment draw from Chinese, German, and Japanese specialty chemical producers. Single-source vulnerability through the Strait of Malacca exposes Middle East buyers to shipping disruptions from Southeast Asian manufacturing gravity. Distribution runs through Jeddah and Dubai climate-controlled hubs, with Sharjah free zones aggregating bulk imports for re-export across Gulf Cooperation Council states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and North Africa disposable gloves market reads as a late-cycle quality story, with procurement consolidation favoring manufacturers holding established regulatory dossiers over commodity volume players. Demand is tilting toward chlorinated nitrile formulations and thin-gauge surgical sensitivity grades that command sustained premium positioning.
For Market Incumbents: Anchor Gulf market position through captive nitrile butadiene rubber supply or long-term feedstock offtake agreements that insulate margins from petrochemical volatility. Deepen MOHAP and SFDA regulatory affairs capabilities in Dubai and Jeddah to accelerate tender response times against emerging entrants with documentation bottlenecks. Prioritize climate-controlled warehousing investments in Riyadh's extreme heat environment, as Ministry of Health contracts increasingly specify storage integrity guarantees that disqualify general-trade distributors. For New Entrants and Emerging Players: Capture Egyptian manufacturing incentives under Suez Canal Economic Zone frameworks to establish localized converting operations for North African distribution without competing directly against Malaysian scale in Gulf clinical segments. Target food-service mandates in Dubai and Riyadh hospitality supply chains, where MOHAP hygiene regulations are expanding glove consumption beyond healthcare procurement concentration. Pursue rapid fulfillment partnerships with restaurant procurement platforms rather than multi-year hospital tender cycles that favor incumbents with established dossiers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional distributors possessing climate-controlled logistics infrastructure and multi-country Gulf regulatory submission expertise. Long-term viability in this market hinges on backward integration into synthetic rubber supply or exclusive distribution partnerships with Southeast Asian manufacturers seeking Gulf market access. Watch for Egyptian domestic production subsidy announcements as an inflection signal that could redirect North African sourcing patterns and elevate localized assembly valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Butadiene Rubber | Captive acrylonitrile supply insulates margins from petrochemical volatility affecting Malaysian competitors. |
| SFDA Medical Device Registration Investment | Established biocompatibility dossiers unlock Saudi Ministry of Health multi-year supply contracts. |
| Climate-Controlled Warehousing Expansion | Jeddah and Riyadh cold chain infrastructure satisfies Ministry of Health storage specifications in extreme heat. |
| Egyptian Manufacturing Localization | Suez Canal Economic Zone incentives redirect North African sourcing from Asian import dependency. |
| Food-Service Distribution Partnership | Dubai hospitality procurement platforms extend glove consumption beyond healthcare market concentration. |
Research Approach
Coverage spans Saudi Arabia, UAE, Egypt, Qatar, and Kuwait, with primary inputs from each market's healthcare procurement ecosystem. The analysis combines structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation through SFDA registration databases, MOHAP medical device filings, customs import records, and Gulf hospital tender documentation. Bottom-up demand modeling across clinical, food-service, and industrial end-uses triangulates against top-down macroeconomic projections for healthcare infrastructure spending.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include material chemistry, thickness grade, application intensity, and distribution channel structure, with cross-tabs against regional regulatory clusters. CAGRs derive from fitted growth curves calibrated to hospital bed expansion timelines, hospitality sector hygiene mandate implementation schedules, and petrochemical feedstock cost trajectories. Nitrile formulation adoption rates and chlorinated surface treatment penetration serve as industry-specific demand drivers in the quantitative framework.
Feedstock price volatility, regulatory approval timeline extensions, and domestic manufacturing incentive announcements are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about continued Gulf healthcare infrastructure investment and sustained Malaysian supply concentration. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Cryotubes Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Europe Sharps Containers Market