
 Europe Coiled Tubing Market | 2026-2036
Europe Coiled Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coiled Tubing Market Analysis
Service company procurement channels across the North Sea are being redrawn as integrated rental-and-service bundling is reshaping how operators access coiled tubing strings. Schlumberger Limited leverages its integrated well intervention portfolio to anchor long-term contracts with major offshore operators. Baker Hughes competes through specialized high-pressure composite coiled tubing designs engineered for deepwater Norwegian fields. Halliburton sustains market presence by controlling regional maintenance and recertification infrastructure.
Coiled tubing consists of continuous, seam-welded steel or composite pipe manufactured in long, unbroken lengths typically ranging from 2,000 to 30,000 feet, designed to be spooled onto a reel for repeated deployment into oil and gas wells without threaded connections. Its primary industrial purpose centers on well intervention, completion, and drilling operations where rapid tripping speed and live-well capability reduce non-productive time. Well intervention services occupy the largest value share as operators prioritize production optimization over greenfield development in Europe's mature basins. Composite material grades represent the fastest-expanding segment, driven by corrosion resistance demands in high-CO2 North Sea reservoirs.
The EU Green Deal's methane emissions framework and REACH chemical compliance standards shape equipment specifications and material selection across European manufacturing. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority enforce well integrity regulations that mandate recertification cycles and traceability documentation for coiled tubing strings. Stakeholders must monitor how the EU AI Act's predictive maintenance requirements intersect with downhole sensor integration strategies.
Market Dynamics
The EU Green Deal's methane emissions framework is compressing equipment replacement cycles across North Sea operations, forcing operators to retire legacy steel coiled tubing strings ahead of schedule and adopt corrosion-resistant composite alternatives.
Growth Catalysts
- Norway's offshore cluster:Mature field revitalization campaigns in the North Sea basin require continuous coiled tubing deployment for well intervention services. Statoil-operated fields drive recurring demand for high-pressure rated strings.
- REACH chemical compliance standards:Equipment specifications across European manufacturing now mandate traceable material composition. This regulatory pull accelerates replacement of ungraded inventory with certified composite grades.
- Composite material migration:Corrosion resistance demands in high-CO2 reservoirs are displacing conventional steel strings. North Sea operators facing sour gas conditions prioritize polymer-matrix composites for extended service life.
Market Restraints
- Specialized alloy input costs:Nickel and chromium price volatility directly impacts high-grade coiled tubing production margins. European mills pass through raw material swings with 60-90 day lags, compressing fabricator profitability.
- Recertification infrastructure concentration:Maintenance and recertification capacity clusters in Aberdeen and Stavanger. Operators outside these hubs face extended downtime and transport costs for mandatory integrity verification.
- Steel string residual value:Existing steel inventory retains operational utility in low-corrosion applications. This functional substitute delays full composite conversion despite regulatory pressure.
Strategic Opportunities
- EU AI Act predictive maintenance mandates:Downhole sensor integration requirements create white space for smart coiled tubing strings with embedded fiber optic monitoring. First movers capture specification-setting advantage.
- Integrated rental-and-service bundling:Procurement channel innovation allows service companies to anchor long-term contracts through equipment-plus-technician packages. This model penetrates smaller independent operators previously served by spot rental.
- Decommissioning application expansion:Plug and abandonment campaigns in UK and Dutch sectors represent underpenetrated demand. Coiled tubing cement placement and perforation sealing displace conventional rig-based methods.
Industry Challenges
- Composite repair technician scarcity:Fiber-reinforced polymer damage assessment and field repair requires specialized certification. Training pipeline lag constrains deployment scale-up for next-generation strings.
- Dual certification timelines:Equipment must satisfy both Norway's Petroleum Safety Authority well integrity rules and UK North Sea Transition Authority documentation standards. Parallel approval processes extend time-to-revenue for new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coiled Tubing Market |
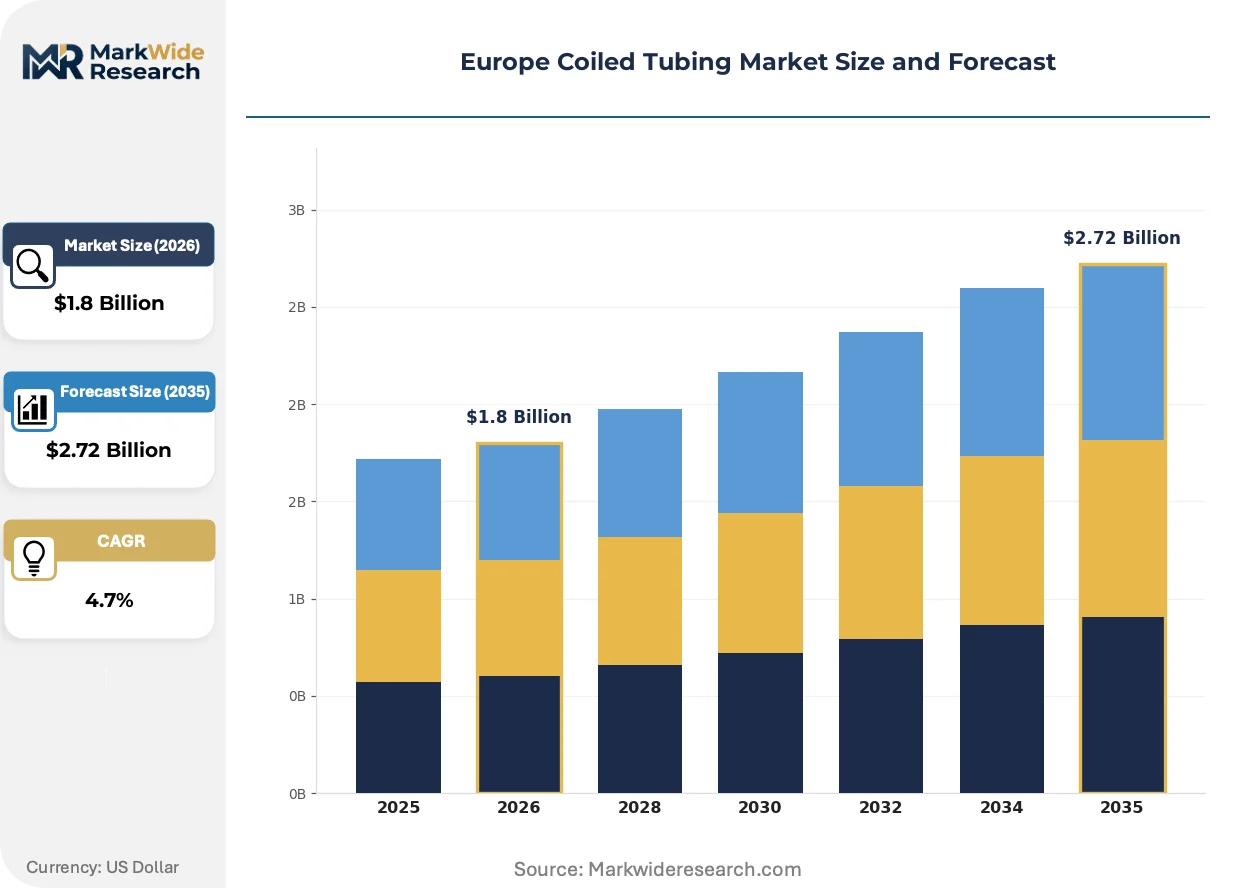
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Intervention, Well Completion, Drilling, Plugging Material: Steel, Composite, Alloy, Polymer Application: Onshore Operations, Offshore Operations, Enhanced Oil Recovery, Land Operations End User: Oil & Gas Companies, Service Providers, Contractors, Offshore Operators |
| Companies Covered | Schlumberger Limited, Baker Hughes, Halliburton, Weatherford, National Oilwell Varco, GOES GmbH, Stimline AS, Royal IHC, Tenaris, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coiled Tubing Market Emerging Trajectories
Material science advances and regulatory digitization mandates are converging to redefine coiled tubing specifications across European offshore operations. Equipment functionality now extends beyond mechanical delivery to encompass real-time downhole data transmission.
Carbon fiber-reinforced polymer composites are migrating from niche deepwater applications to standard well intervention inventory. Norwegian operators facing sour gas corrosion rates above 3mm annually are adopting these strings for 15,000 psi rated operations. The technology is migrating from premium-tier positioning to mid-market deployment as manufacturing scale reduces unit costs.
The EU AI Act's predictive maintenance requirements are mandating sensor integration in high-pressure equipment categories. Downhole pressure and temperature monitoring capabilities must now interface with operator digital twin platforms. Norwegian and UK regulators are aligning inspection protocols to accept continuous monitoring data in lieu of fixed-interval physical recertification.
Integrated service contracting is displacing standalone equipment rental across North Sea procurement desks. Major operators now bundle coiled tubing strings with dedicated crews and real-time engineering support. This pattern concentrates most visibly in Equinor's supplier frameworks, where multi-year integrated awards have replaced annual equipment-only tenders.
Europe Coiled Tubing Market Segmentation
Segmentation in the Europe Coiled Tubing Market reveals how equipment specifications diverge across pressure ratings, corrosion environments, and regulatory jurisdictions. Understanding these divisions exposes where procurement budgets concentrate and where technology substitution accelerates.
Service Type:
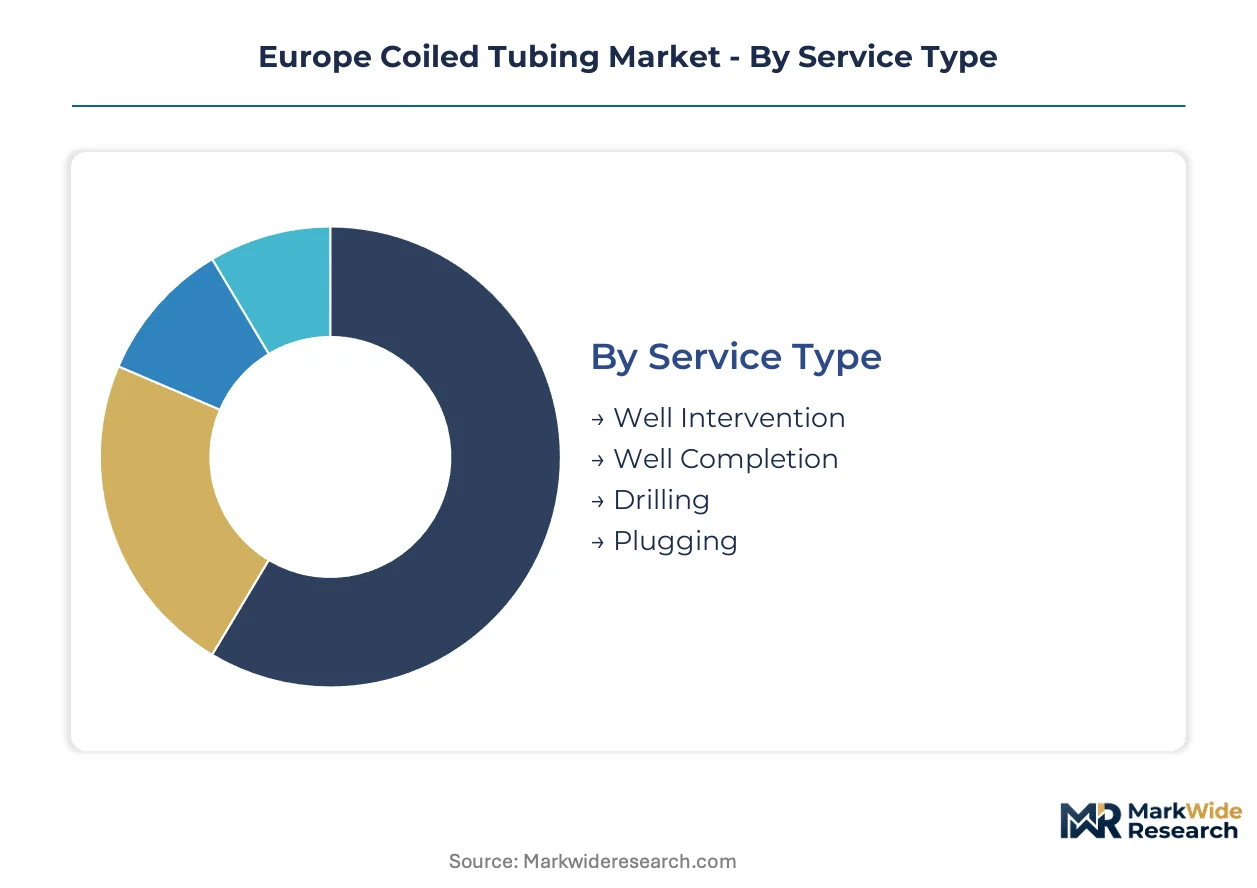
Service type segmentation tracks the use-case spectrum from routine maintenance through permanent abandonment, with each application demanding distinct pressure ratings, string diameters, and crew specializations.
- Well Intervention:Continuous pipe deployment for live-well workovers, stimulation, and production optimization dominates procurement volume across Norway's mature offshore clusters. North Sea operators facing declining reservoir pressure prioritize intervention campaigns over drilling new wells, anchoring recurring demand for 15,000 psi rated strings and integrated service crews.
- Well Completion:Final well preparation including perforation, gravel packing, and sand control installation requires precision-engineered strings with real-time downhole telemetry. UK North Sea Transition Authority well integrity rules mandate completion-grade traceability documentation, favoring suppliers with certified quality management systems.
- Drilling:Slim-hole and re-entry drilling applications utilize coiled tubing for directional work in tight-radius wellbores. Norwegian deepwater fields deploy specialized high-torque strings for underbalanced drilling in depleted zones.
- Plugging:Permanent well abandonment drives cement placement and mechanical plug setting for decommissioning campaigns. UK and Dutch sector plug-and-abandonment obligations are expanding this segment as mature fields reach end-of-life.
Established volume favors Well Intervention; emerging adoption favors Plugging.
Material:
Material selection pivots on cost tier versus corrosion resistance trade-offs, with regulatory pressure compressing the economic viability of conventional grades.
- Steel:Conventional carbon and low-alloy grades retain position in low-corrosion onshore applications and budget-constrained operations. Residual inventory across European rental fleets delays full phase-out despite EU Green Deal methane framework pressure.
- Composite:Carbon fiber-reinforced polymer matrices deliver corrosion immunity in high-CO2 North Sea reservoirs where sour gas attacks steel at rates exceeding 3mm annually. Norwegian operators now specify composite strings as standard for subsea well intervention, with manufacturing scale reducing unit costs toward mid-market positioning.
- Alloy:High-nickel chromium grades bridge performance between steel and full composite for intermediate corrosion conditions. REACH chemical compliance documentation requirements favor traceable alloy sourcing from European mills.
- Polymer:Specialized polymer liners and coatings extend steel string service life in moderate sour service. Dutch and German onshore operators deploy polymer-enhanced strings for cost-sensitive workover programs.
Steel commands current fleet share; composite claims the steepest expansion trajectory.
Application:
Application segmentation maps operational environment against technical complexity, with offshore specifications driving premium pricing and certification requirements.
- Onshore Operations:Lower-pressure well intervention and workover services across European conventional and unconventional onshore basins. German and Romanian onshore fields utilize standard steel strings with shorter recertification intervals.
- Offshore Operations:Subsea well intervention, completion, and abandonment services in the North Sea and Norwegian Sea. Norway's Petroleum Safety Authority mandates dual-pressure containment and emergency disconnect capability for floating rig operations.
- Enhanced Oil Recovery:CO2 and chemical injection programs for mature field revitalization. UK North Sea carbon capture utilization projects are piloting coiled tubing for CO2 placement in depleted reservoirs.
- Land Operations:Terrestrial drilling and intervention distinct from marine environments, encompassing Dutch Groningen field decommissioning and Polish shale workovers. Regulatory frameworks here follow national petroleum authorities rather than offshore-specific regimes.
Offshore Operations absorb the premium equipment investment; Enhanced Oil Recovery is gaining share fastest.
End User:
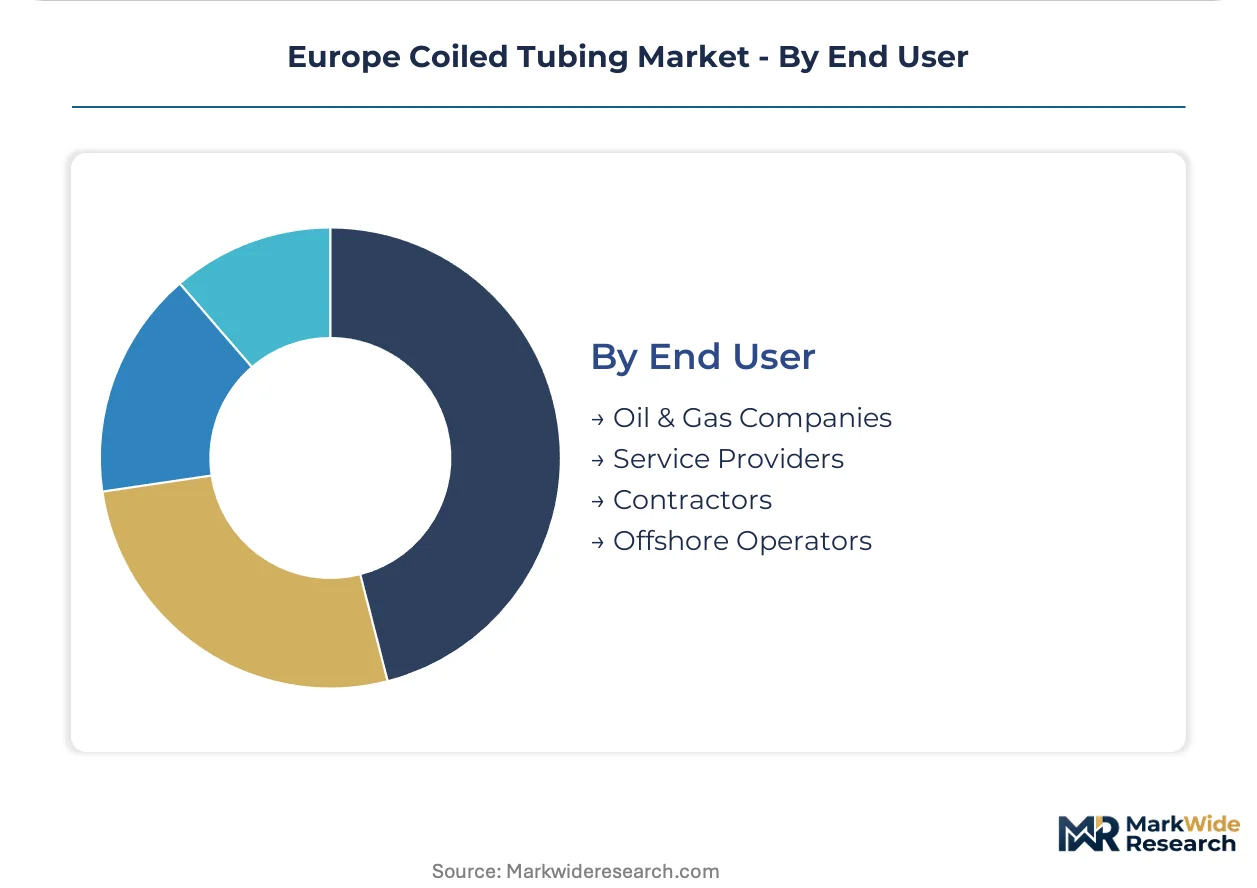
End user segmentation distinguishes between asset owners, service integrators, and execution specialists, with procurement authority shifting toward bundled service contracts.
- Oil & Gas Companies:Major operators including Equinor, Shell, and BP retain direct procurement for multi-year framework agreements. Integrated rental-and-service bundling now dominates their supplier selection criteria.
- Service Providers:Schlumberger, Baker Hughes, and Halliburton maintain owned coiled tubing fleets as core intervention assets. These firms control regional maintenance and recertification infrastructure in Aberdeen and Stavanger.
- Contractors:Specialist intervention contractors and regional service companies operate leased or second-tier equipment. EU AI Act predictive maintenance mandates are forcing technology upgrades among smaller fleet operators.
- Offshore Operators:Platform and floating production facility owners with captive intervention requirements. Norwegian offshore cluster operators increasingly specify smart strings with embedded fiber optic monitoring.
Service Providers consolidate fleet ownership; Offshore Operators are driving smart equipment specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norwegian Continental Shelf pipeline network and North Sea offshore infrastructure grid anchor European coiled tubing demand. These subsea corridors connect mature production clusters to onshore maintenance hubs, concentrating equipment deployment around Stavanger and Aberdeen.
Norway
Equinor-operated Johan Sverdrup and Troll field extensions drive continuous demand for 15,000 psi rated composite strings. The Petroleum Safety Authority mandates dual-pressure containment systems for floating rig operations. Stavanger hosts the densest concentration of recertification facilities, where Halliburton and Baker Hughes maintain captive maintenance infrastructure.
United Kingdom
North Sea decommissioning obligations and late-life field workovers sustain intervention spending across the UKCS. The North Sea Transition Authority enforces well integrity documentation standards that favor suppliers with certified quality management systems. Aberdeen functions as the primary service hub, where integrated rental-and-service contracts now dominate procurement patterns.
Netherlands
Groningen field decommissioning and offshore IJmuiden corridor operations create demand for plugging and abandonment services. REACH chemical compliance documentation requirements accelerate replacement of ungraded steel inventory. Rotterdam's port infrastructure supports composite string import logistics for Dutch North Sea campaigns.
Germany
Onshore conventional fields in Lower Saxony and shale workover programs utilize standard steel strings with shorter recertification cycles. ECHA oversees material composition traceability under REACH standards. Celle and Clausthal-Zellerfeld host regional service bases serving domestic operators with cost-sensitive equipment tiers.
Denmark
Tyra field redevelopment and Danish North Sea mature basin workovers require specialized high-pressure intervention strings. The Danish Energy Agency aligns well integrity rules with Norwegian and UK standards. Esbjerg's offshore service cluster supports jackup-based coiled tubing deployment for Maersk Oil and independent operators.
Europe Coiled Tubing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified strings and maintenance capacity. The European market exhibits consolidated service provision alongside fragmented equipment manufacturing. Three archetypes dominate: integrated oilfield service conglomerates with captive fleets, specialized composite fabricators with corrosion-resistant IP, and regional rental operators with spot-market flexibility. Competitive dynamics center on long-term contract anchoring through bundled crews and predictive maintenance integration.
Within the integrated service tier, Schlumberger Limited and Baker Hughes represent platform-scale archetypes with full intervention portfolios. Halliburton occupies a position emphasizing regional maintenance infrastructure control. GOES GmbH exemplifies the specialized fabricator archetype with European manufacturing footprint. Stimline AS and Royal IHC sit within the regional specialist tier, serving North Sea operators with targeted equipment and service configurations.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes |
| Halliburton |
| Weatherford |
| National Oilwell Varco |
| GOES GmbH |
| Stimline AS |
| Royal IHC |
| Tenaris |
| Others |
Supply Flow & Price Mechanics
Stavanger's composite string manufacturing cluster concentrates high-pressure coiled tubing capacity for Norwegian offshore operators, translating supply scarcity into pricing leverage for corrosion-resistant grades. Equipment buyers outside this hub absorb transport and recertification premiums that widen spreads between standard steel and certified composite strings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API-certified composite strings from traceable alloy grades and ungraded steel inventory. Price differentiation hinges on REACH chemical compliance documentation and dual-pressure containment certification for floating rig operations. Cost compression in the steel tier intensifies because residual fleet utility delays full phase-out despite EU Green Deal methane framework pressure. Independent contractors exhibit highest price sensitivity; Equinor-anchored integrated service contracts absorb premium tier pricing with least negotiation leverage.
Supply Chain Analysis
EU dual-use technology controls and carbon fiber export restrictions from US and Japanese suppliers constrain composite matrix flows into European fabrication facilities. Manufacturing concentrates in Germany, Norway, and the Netherlands for finished strings; carbon fiber pre-preg feeds from Japan, the United States, and South Korea. Nickel and chromium price volatility from South African and Indonesian ore markets constitutes the dominant raw material risk. Distribution runs through Aberdeen and Stavanger service hubs with captive maintenance infrastructure controlling downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's predictive maintenance mandates constitute a regulatory inflection that will displace conventional strings and restructure procurement authority toward sensor-integrated suppliers.
For Market Incumbents: Entrench position by deepening backward integration into fiber optic sensor supply and capturing recertification capacity in Aberdeen and Stavanger. Composite repair technician training pipelines represent the critical capability gap that Schlumberger, Baker Hughes, and Halliburton must close before independent contractors scale alternative maintenance networks. For New Entrants and Emerging Players: Establish a beachhead in UK and Dutch plug-and-abandonment campaigns where decommissioning obligations outstrip incumbent crew availability. The decommissioning application segment offers lowest certification barriers and shortest sales cycles for smart string technology. Partner with regional intervention contractors to bypass integrated service contract lock-in at major operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized composite fabricators with corrosion-resistant IP and European manufacturing footprint over steel-dependent rental operators. Long-term viability across the projection horizon rests on sensor integration capabilities and regulatory acceptance of continuous monitoring data. Watch for Norway's Petroleum Safety Authority alignment with UK North Sea Transition Authority on digital recertification protocols as the signal for accelerated smart string adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Scale-Up | Reduces unit costs toward mid-market positioning for carbon fiber-reinforced polymer strings. |
| Fiber Optic Sensor Integration | Satisfies EU AI Act predictive maintenance mandates and enables digital twin platform connectivity. |
| Recertification Infrastructure Expansion | Captures maintenance revenue streams outside concentrated Aberdeen-Stavanger hubs. |
| Integrated Service Contract Anchoring | Locks multi-year equipment-plus-crew awards with Equinor, Shell, and BP procurement desks. |
| Decommissioning Service Capability Buildout | Positions for UK and Dutch plug-and-abandonment obligations as mature fields reach end-of-life. |
Methodological Framework
Initial hypotheses were tested against primary input from well intervention engineers, offshore procurement managers, composite fabrication technical directors, and regulatory compliance officers at Norway's Petroleum Safety Authority and the UK North Sea Transition Authority, then refined through secondary validation. Sources included EU REACH chemical compliance filings, Petroleum Safety Authority well integrity audit reports, North Sea Transition Authority decommissioning obligation databases, and customs trade records for carbon fiber and specialty alloy inputs. Bottom-up equipment fleet analysis and top-down operator spending triangulation anchored volume estimates.
Demand-supply-balance modeling tracked intervention campaign schedules against certified string manufacturing capacity across the analysis window. Segmentation dimensions covered service type, material grade, application environment, and end-user procurement authority. CAGRs derived from operator capital commitment pipelines and regulatory compliance deadline clustering. Forecast inputs incorporated EU AI Act implementation timelines and composite string manufacturing scale curves.
Sensitivities concentrate around EU AI Act enforcement pacing, nickel price volatility, and dual-certification timeline convergence between Norwegian and UK regulators. Cross-checking against North Sea operator disclosed intervention spending and Petroleum Safety Authority equipment registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Casing Centralizer Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Global Completion Equipment and Services Market