
 Europe Hydraulic Fracturing Fluids Market | 2026-2036
Europe Hydraulic Fracturing Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydraulic Fracturing Fluids Market Foresight
CE marking under the EU Pressure Equipment Directive is bifurcating the supplier landscape into qualified and non-qualified tiers. Halliburton Company leverages its integrated service model across North Sea operations. Baker Hughes Company anchors its position through specialized high-pressure pumping technologies. Schlumberger Limited differentiates via digital fluid monitoring systems deployed in Norwegian concessions.
Hydraulic fracturing fluids are engineered suspensions of water, proppants, and functional additives injected at pressures exceeding 10,000 psi to create and maintain fracture conductivity in low-permeability formations. Their primary purpose is to maximize hydrocarbon or geothermal heat extraction from formations where natural permeability is insufficient. Water-based formulations occupy the largest volume share due to lower base-fluid costs and simpler waste handling, while friction reducer additives represent the fastest-expanding category as operators push injection rates higher in extended-reach laterals. Oil-based systems retain premium positioning in water-sensitive clay formations where formation damage risks dominate economics.
REACH registration requirements govern biocide and surfactant chemistries permitted in European formulations, while the EU Green Deal's methane intensity benchmarks constrain venting practices during flowback operations. The F-Gas Regulation indirectly shapes foam-based fluid viability through fluorinated surfactant restrictions. Operators and chemical suppliers must monitor how the EU AI Act's predictive maintenance mandates will integrate with real-time fracturing fluid performance optimization systems.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's methane intensity thresholds are compressing formulation choice sets, forcing operators to retire legacy biocide chemistries and requalify entire additive portfolios under stricter toxicity profiles.
Growth Catalysts
- Offshore shale concessions:Norway's North Sea licensing rounds are expanding addressable reservoir volume for high-pressure fluid systems. State regulator NPD has accelerated permitting timelines for extended-reach laterals requiring specialized friction reducer packages.
- REACH registration tailwinds:Biocide reauthorization under ECHA's 2024 review cycle is clearing market space for quaternary ammonium alternatives with lower aquatic toxicity. Formulators holding early registrations capture share from delayed competitors.
- Geothermal co-production:Poland's Baltic Basin operators are repurposing hydraulic fracturing fleets for deep geothermal heat extraction, extending fluid demand beyond hydrocarbon applications. Dual-use equipment spreads fixed costs across energy transition projects.
Market Restraints
- Guar gum supply volatility:Friction reducer feedstock prices swing with Indian monsoon patterns and export restrictions. European blenders lack backward integration into seed processing, exposing margin compression during supply shocks.
- Water sourcing constraints:Onshore Poland and Germany face seasonal groundwater withdrawal limits under national environmental agency rulings. Trucking water from distant sources adds 15-20% to base fluid costs.
- Cross-linked gel substitution:Viscoelastic surfactant systems are displacing boron-crosslinked guar in low-temperature formations. Legacy polymer investments face stranded asset risk as operator specifications tighten.
Strategic Opportunities
- Romania's Moesian Platform:Black Sea shale remains underpenetrated due to past exploration moratoriums. Recent parliamentary reversals on hydraulic fracturing bans open acreage requiring full fluid system deployment.
- Real-time optimization convergence:Integration of fiber-optic distributed temperature sensing with automated additive injection enables dynamic proppant concentration adjustment. Norwegian operators pilot closed-loop control reducing fluid overdesign by 12-18%.
- EU Innovation Fund eligibility:Green Deal-aligned methane detection and reduction projects qualify for non-dilutive capital. Fluid suppliers embedding leak-detection chemistry into formulations access subsidized pilot budgets.
Industry Challenges
- Specialized pressure-pumping labor:Extended-reach offshore operations require crews certified to 15,000 psi operational standards. Training pipelines lag fleet expansion timelines in the North Sea.
- CE marking timeline compression:EU Pressure Equipment Directive recertification cycles for high-pressure pumping units now overlap with REACH additive requalification. Dual-track compliance strains technical documentation resources.
- Flowback treatment integration:Produced fluid recycling mandates require compatibility between fracturing chemistry and wastewater treatment biology. Bioaugmentation failures in Polish central treatment facilities force batch segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydraulic Fracturing Fluids Market |
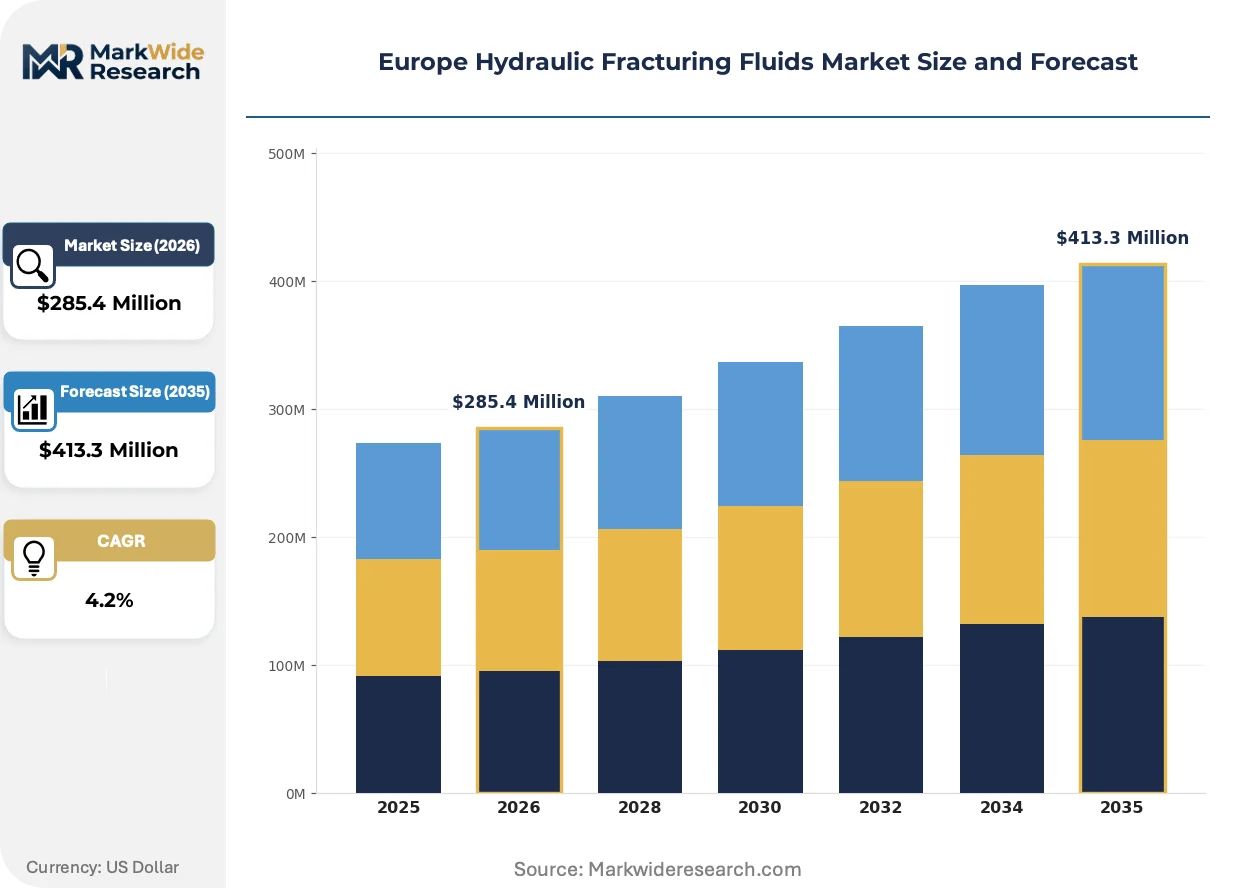
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $413.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Water-Based, Oil-Based, Foam-Based, Hybrid Additive Type: Friction Reducers, Biocides, Surfactants, Gelling Agents Application: Natural Gas, Oil Recovery, Geothermal Energy, Enhanced Oil Recovery End User: Exploration Companies, Service Providers, Government Agencies, Research Institutions |
| Companies Covered | Halliburton Company, Baker Hughes Company, Schlumberger Limited, Cuadrilla Resources Ltd, PJSC Rosneft Oil Company, PJSC Gazprom, IGas Energy PLC, PAO NOVATEK, Equinor ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydraulic Fracturing Fluids Market Shifts & Advancements
Digital fluid monitoring systems and low-toxicity additive platforms are converging to reshape how operators design, execute, and verify fracture treatments across European unconventional plays.
Microseismic sensor arrays embedded in treatment strings are miniaturizing fracture mapping from surface-based geophone networks to downhole distributed acoustic sensing. Norwegian offshore operators deploy these systems on every third well to validate fracture geometry models against actual propagation patterns. Real-time geometry feedback is compressing the iteration cycle between diagnostic pumping and full-rate execution, reducing non-productive time.
ECHA's 2024 biocide reauthorization framework is forcing formulators to abandon isothiazolinone-based preservation systems in favor of peracetic acid and glutaraldehyde alternatives with faster environmental degradation profiles. The industrial consequence is a complete reformulation of water-based fluid packages, with compatibility testing against reservoir mineralogy now extending qualification timelines by 4-6 months. Polish onshore operators are most affected, as their lower-temperature formations previously relied on cost-optimized isothiazolinone chemistries.
Integrated service contracting is displacing discrete chemical procurement across North Sea operations. Operators now bundle fluid design, pumping execution, and flowback handling under single-provider accountability, transferring technical risk from their balance sheets to service company warranties. This consolidation is most visible in Norway, where Equinor's framework agreements require full-chain methane intensity guarantees that fragmented suppliers cannot underwrite.
Europe Hydraulic Fracturing Fluids Market Segmentation
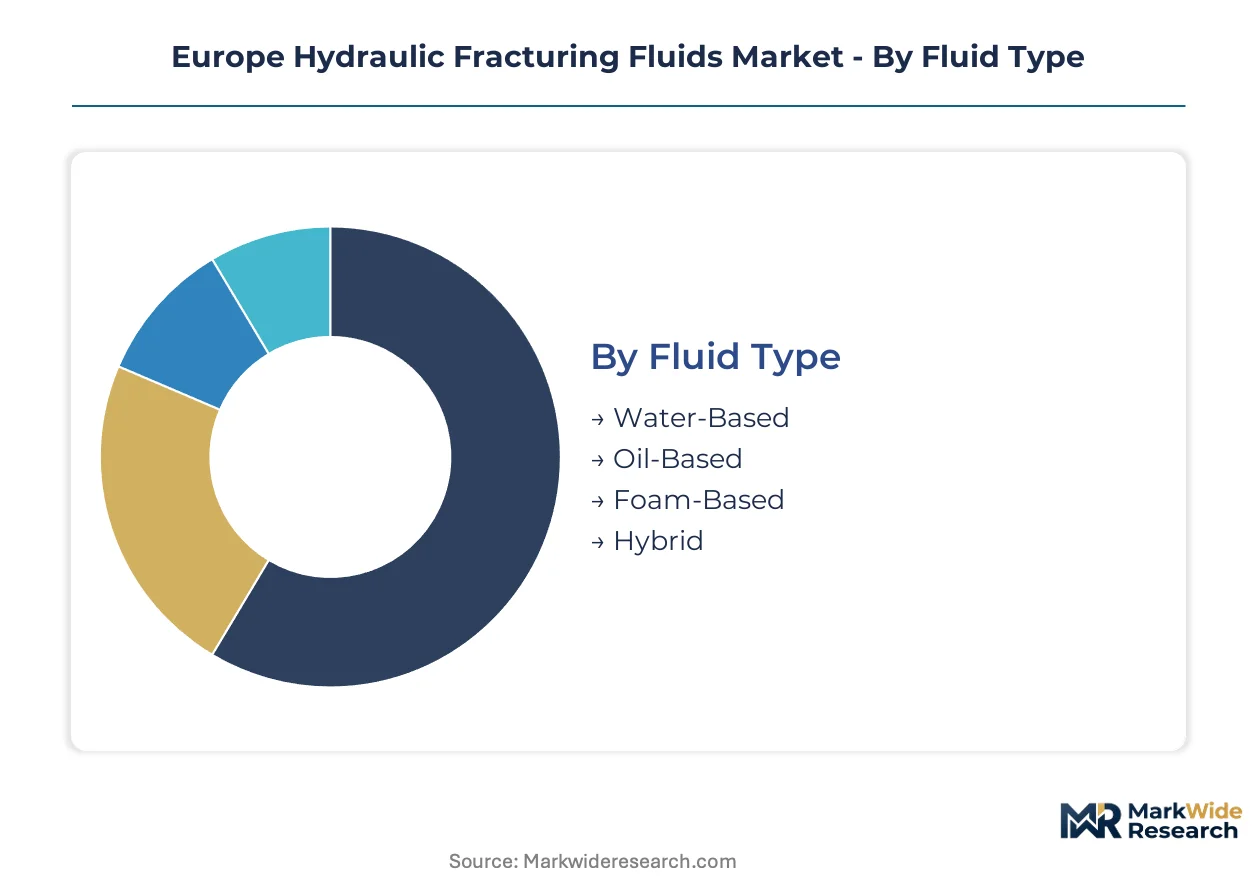
Fluid formulation choices in European unconventional extraction are hardening around regulatory compliance and reservoir-specific performance requirements. Segmentation reveals where substitution threats from viscoelastic surfactants and geothermal repurposing are reshaping procurement priorities.
Fluid Type:
Substitution pressure concentrates most intensely on oil-based systems as REACH toxicity thresholds and water-based performance improvements converge.
- Water-Based:Suspensions of water, proppants, and functional additives dominate European volume due to lower base-fluid costs and simpler waste handling under national environmental agency rulings. Norwegian North Sea operators specify these systems for extended-reach laterals where friction reducer packages enable higher injection rates.
- Oil-Based:Hydrocarbon-base formulations retain premium positioning in water-sensitive clay formations where formation damage risks dominate economics. Poland's Baltic Basin projects deploy these selectively in high-clay lithologies, though REACH registration costs for aromatic solvents are compressing margins.
- Foam-Based:Nitrogen or carbon dioxide energized systems face viability constraints from the F-Gas Regulation's fluorinated surfactant restrictions. Limited deployment concentrates in low-pressure zones.
- Hybrid:Dual-base formulations blending water and synthetic hydrocarbon phases address intermediate compatibility challenges. Emerging interest tracks geothermal co-production applications.
Water-Based retains volume leadership; Friction Reducer packages within this category hold the steepest expansion curve as extended-reach laterals proliferate.
Additive Type:
Cost tier stratification separates commodity biocides from premium friction reducer chemistries with patent-protected molecular architectures.
- Friction Reducers:High-molecular-weight polyacrylamide and guar-derivative polymers enable elevated pump rates with reduced horsepower requirements. Norwegian offshore concessions specify these for 15,000 psi operations where mechanical efficiency gains justify premium pricing.
- Biocides:Preservation systems prevent microbial degradation of organic polymers during storage and injection. ECHA's 2024 reauthorization framework is forcing wholesale transition from isothiazolinones to peracetic acid and glutaraldehyde alternatives with faster environmental degradation profiles.
- Surfactants:Interfacial tension modifiers enhance proppant transport and flowback cleanup. REACH registration governs permissible chemistries.
- Gelling Agents:Boron-crosslinked guar and synthetic polymer systems build viscosity for proppant suspension. Viscoelastic surfactant substitution threatens legacy polymer investments in low-temperature Polish formations.
Friction Reducers command the highest margin tier; Biocides face the most severe reformulation disruption from regulatory reauthorization cycles.
Application:
Application segmentation tracks how geothermal energy repurposing is extending fluid demand beyond hydrocarbon extraction.
- Natural Gas:Primary demand driver concentrates in Norway's North Sea shale concessions and Poland's Baltic Basin tight gas formations. State regulator NPD's accelerated permitting timelines expand addressable reservoir volume.
- Oil Recovery:Conventional tight oil applications face margin compression from volatile crude benchmarks. Romanian Moesian Platform prospects remain contingent on parliamentary regulatory stability.
- Geothermal Energy:Deep heat extraction repurposes existing hydraulic fracturing fleets in Poland's Baltic Basin. Dual-use equipment spreads fixed costs across energy transition projects.
- Enhanced Oil Recovery:Tertiary recovery applications remain limited in European unconventional plays due to unfavorable viscosity ratios and waterflood alternatives.
Natural Gas anchors current procurement volumes; Geothermal Energy applications are climbing fastest as operators diversify revenue streams.
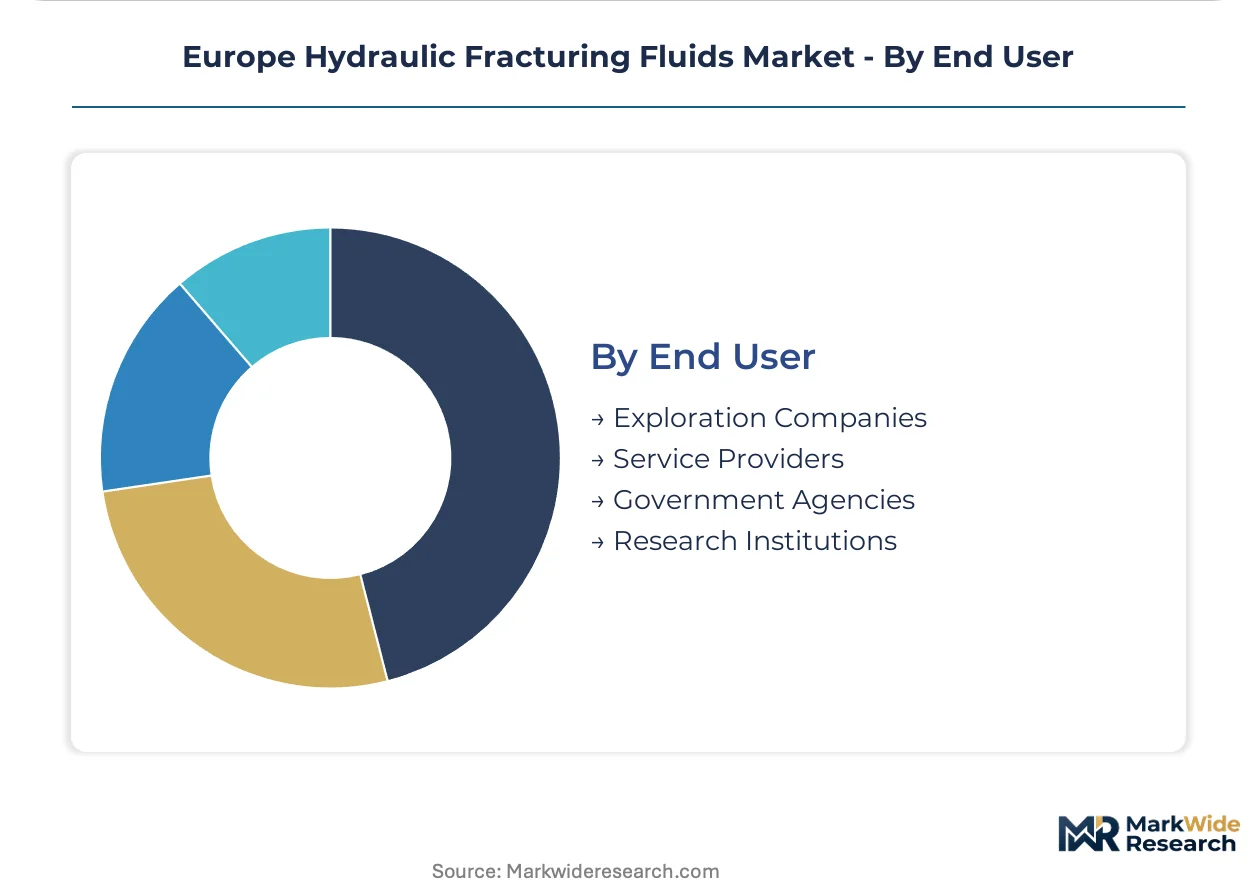
End User:
Customer type segmentation reveals consolidation toward integrated service contracting that transfers technical risk from operators to vendors.
- Exploration Companies:National oil companies and independent operators specify fluid performance criteria and methane intensity guarantees. Equinor's framework agreements require full-chain accountability that fragments suppliers cannot underwrite.
- Service Providers:Halliburton, Baker Hughes, and Schlumberger bundle fluid design, pumping execution, and flowback handling under single-provider warranties. CE marking under the EU Pressure Equipment Directive qualifies this tier for high-pressure offshore deployment.
- Government Agencies:State regulators including Norway's NPD and Poland's environmental agencies set permitting conditions and groundwater withdrawal limits that constrain formulation choice.
- Research Institutions:Universities and national laboratories pilot alternative chemistries including bio-based friction reducers and encapsulated biocide delivery systems.
Service Providers concentrate procurement decision authority; Government Agencies exercise expanding influence through REACH compliance deadlines and methane emission thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal methane intensity benchmarks and REACH compliance deadlines are redirecting capital toward North Sea and Baltic Basin unconventional plays. National regulators in Norway and Poland have compressed permitting timelines for extended-reach laterals requiring specialized fluid systems.
Norway
State regulator NPD accelerated offshore shale licensing rounds for the North Sea basin. Equinor's framework agreements mandate full-chain methane intensity guarantees that fragmented suppliers cannot underwrite. Stavanger anchors the regional service hub where Halliburton and Schlumberger deploy integrated fluid-pumping-flowback bundles.
Poland
Polish environmental agencies relaxed groundwater withdrawal limits for Baltic Basin tight gas projects following 2023 parliamentary reviews. ECHA's 2024 biocide reauthorization forced wholesale transition from isothiazolinones to peracetic acid alternatives. Warsaw-based operators now repurpose hydraulic fracturing fleets for deep geothermal co-production.
Romania
Parliamentary reversals on hydraulic fracturing moratoriums opened the Moesian Platform to unconventional exploration. National environmental agency rulings still constrain water sourcing from the Danube delta region. Black Sea port infrastructure at Constanța is expanding storage capacity for friction reducer polymer imports.
United Kingdom
Cuadrilla Resources and IGas Energy hold dormant Lancashire and Weald Basin licenses awaiting regulatory signal clarity. The North Sea Transition Authority maintains decommissioning liability frameworks that complicate new offshore shale economics. Aberdeen service clusters remain oriented toward conventional North Sea workover rather than unconventional fracturing.
Germany
Federal environmental agency groundwater rulings impose seasonal withdrawal limits on prospective Lower Saxony shale plays. The F-Gas Regulation's fluorinated surfactant restrictions block foam-based fluid deployment in low-pressure zones. Berlin-headquartered chemical blenders lack backward integration into guar seed processing, exposing margin compression during Indian supply shocks.
Europe Hydraulic Fracturing Fluids Market Competitive Landscape
Player mix skews toward integrated service conglomerates with CE marking qualifications under the EU Pressure Equipment Directive. Market structure concentrates procurement decision authority within three global oilfield service providers holding Norwegian offshore framework agreements. Strategic archetypes include full-chain integrators, high-pressure pumping specialists, and digital fluid monitoring developers. Competitive moves center on integrated service contracting transfers and REACH-compliant additive portfolio requalification.
Within the full-chain integrator tier, Halliburton Company, Baker Hughes Company, and Schlumberger Limited anchor the qualified supplier landscape for high-pressure offshore deployment. These US-incorporated entities exemplify the service provider archetype that bundles fluid design, pumping execution, and flowback handling under single-provider warranties. Their positioning reflects the consolidation pressure from Equinor's methane intensity guarantee requirements that fragmented chemical suppliers cannot underwrite.
| Leading Market Players |
|---|
| Halliburton Company |
| Baker Hughes Company |
| Schlumberger Limited |
| Cuadrilla Resources Ltd |
| PJSC Rosneft Oil Company |
| PJSC Gazprom |
| IGas Energy PLC |
| PAO NOVATEK |
| Equinor ASA |
| Others |
Supply & Pricing Matrix
Capacity utilization at Norwegian North Sea pumping service hubs creates scale economies that compress per-unit fluid costs while elevating price floors for non-integrated blenders. Halliburton and Schlumberger leverage captive additive manufacturing to undercut fragmented competitors on extended-reach lateral packages, transferring margin pressure downstream to independent chemical suppliers lacking backward integration into guar seed processing.
Pricing Analysis
CE marking tier under the EU Pressure Equipment Directive creates the primary spread between qualified and non-qualified supplier pricing. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels segments buyer access to Norwegian offshore frameworks. Cost compression in the economy tier intensifies because REACH reauthorization timelines strain working capital for delayed registrants. Exploration companies holding Equinor framework agreements demonstrate lowest price sensitivity, while independent Polish onshore operators exhibit highest sensitivity to friction reducer feedstock swings.
Supply Chain Analysis
Just-in-time additive delivery dominates Norwegian offshore operations where platform storage constraints limit inventory, while Polish onshore blenders maintain strategic stockpiles of biocide alternatives ahead of ECHA reauthorization deadlines. Manufacturing concentration in Germany, Norway, and the United Kingdom shapes regional supply availability, with friction reducer polymer production drawing from Indian guar gum and German synthetic polyacrylamide feedstocks. Single-source vulnerability in Indian monsoon-dependent seed harvests threatens formulation continuity. Distribution runs through Stavanger and Aberdeen service hubs for offshore deployment, with Warsaw and Berlin anchoring onshore blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated service contracting is transforming this market into a platform-economics structure where methane intensity data interoperability between operators and regulators creates winner-take-most dynamics. Equinor's framework agreements exemplify how full-chain accountability requirements consolidate procurement authority within qualified service conglomerates.
For Market Incumbents: Fortify additive portfolio requalification timelines by accelerating ECHA biocide registrations ahead of competitor delays. Secure captive supply of guar gum through backward integration into seed processing or long-term offtake agreements with Indian processors, insulating margin compression from monsoon volatility. Viscoelastic surfactant substitution in Polish low-temperature formations threatens legacy polymer investments; preemptive R&D allocation toward hybrid gel systems defends market position. For New Entrants and Emerging Players: CE marking fast-track through specialized high-pressure pumping unit certification opens Norwegian offshore access currently blocked to unqualified competitors. Target Romania's Moesian Platform as the most penetrable geography following parliamentary reversal of fracturing moratoriums. Geothermal co-production in Poland's Baltic Basin offers white-space entry where dual-use equipment spreads fixed costs across energy transition projects. Partner with established service providers on flowback handling integration to bypass full-chain warranty requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers holding multi-year framework agreements with methane intensity guarantees. Long-term viability across the analysis window favors acquisition targets with REACH-registered additive portfolios and CE marking qualifications under the EU Pressure Equipment Directive. Watch ECHA biocide reauthorization completion rates as the inflection indicator for competitive repositioning; delayed registrants face stranded inventory risk that creates distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Additive Requalification | ECHA biocide registrations determine market access for water-based fluid formulations across European unconventional plays. |
| Integrated Service Contracting | Equinor framework agreements transfer technical risk from operators to vendors through full-chain methane intensity guarantees. |
| Geothermal Fleet Repurposing | Polish Baltic Basin operators extend hydraulic fracturing equipment utilization into deep heat extraction projects. |
| Real-Time Fluid Optimization | Norwegian closed-loop control pilots reduce fluid overdesign through fiber-optic distributed temperature sensing integration. |
| Romanian Market Entry | Moesian Platform acreage requires complete fluid system deployment following parliamentary reversal of exploration bans. |
Research Methodology
A standing panel of hydraulic fracturing service engineers, ECHA regulatory affairs specialists, North Sea drilling contractors, and Polish environmental agency permitting officers provided ongoing calibration across primary data collection. Secondary validation drew from NPD licensing round disclosures, ECHA biocide registration databases, EU Green Deal methane intensity benchmarks, and SEC filings of listed oilfield service providers. Bottom-up fluid volume modeling triangulated against top-down energy demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation by fluid type, additive category, application, and end user, with additional dimensioning by CE marking qualification status and REACH registration completion. CAGRs derived from logistic growth curve fitting to patent filing trajectories and permitting velocity indicators. Forecast inputs incorporated NPD accelerated timeline announcements and ECHA reauthorization cycle impacts on formulation availability.
Underlying assumptions cover regulatory stability in Norway and Poland, REACH compliance deadline adherence, and guar gum supply continuity from Indian processing, with deviation risk concentrated in Romanian parliamentary reversals and ECHA biocide authorization delays. Revision becomes warranted when methane intensity guarantee thresholds in framework agreements cross enforceability thresholds or when geothermal co-production economics shift project prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Frac Tree Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market