
 Integrated Gas System Market | 2026-2036
Integrated Gas System Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Gas System Market Foresight
Ultra-high-purity gas specification tiers is collapsing the gap between semiconductor-grade and industrial-grade integrated gas systems, forcing upgrade cycles across downstream fabs. Linde plc leverages its cryogenic engineering heritage to dominate helium and hydrogen distribution architectures. Air Liquide sustains margin pools through backward integration into on-site gas generation. Siemens Energy AG differentiates via electrolyzer-gas handling hybrids that bridge power-to-gas workflows.
An integrated gas system encompasses the engineered assembly of storage vessels, compression trains, distribution piping, and processing skids designed to deliver gases at specified pressure, purity, and flow rates to industrial or energy consumers. These systems typically operate at pressures ranging from 150 bar in CNG infrastructure to cryogenic conditions below minus 160 degrees Celsius for LNG, with materials selected for hydrogen embrittlement resistance or sour gas compatibility. Gas storage and processing units command the deepest margin pools due to long asset lives and captive aftermarket service contracts, while modular installation types are expanding fastest as brownfield sites seek minimized shutdown windows. LNG technology leads absolute spending within the technology dimension, though renewable gas segments are attracting disproportionate capital allocation from utility providers under decarbonization mandates.
The EPA enforces methane performance standards that shape compressor seal specifications and leak detection protocols for US onshore facilities. EMA's F-Gas Regulation and the EU AI Act's emerging industrial monitoring requirements are tightening product compliance burdens across European gas infrastructure. China's MEE dual carbon goals and GB standards on hydrogen purity are redirecting procurement specifications for new integrated gas investments. Stakeholders must monitor how regulatory divergence on hydrogen blending ratios reshapes equipment interoperability across border-linked gas corridors.
Market Dynamics
Europe's F-Gas Regulation and the EU Green Deal are compressing methane emission tolerances and redirecting capital flows toward low-carbon gas infrastructure retrofits across industrial corridors.
Growth Catalysts
- LNG infrastructure scale-up:Utility providers are accelerating LNG adoption as the dominant end-use channel, driving demand for cryogenic storage and vaporization skids.
- Rhine corridor hydrogen blending:Industrial clusters in Germany are retrofitting integrated gas networks to accommodate hydrogen admixture ratios mandated under national hydrogen strategy frameworks.
- Ultra-high-purity specification tiers:Collapsing grade distinctions between semiconductor and industrial gas systems are forcing upgrade cycles across downstream fabrication facilities.
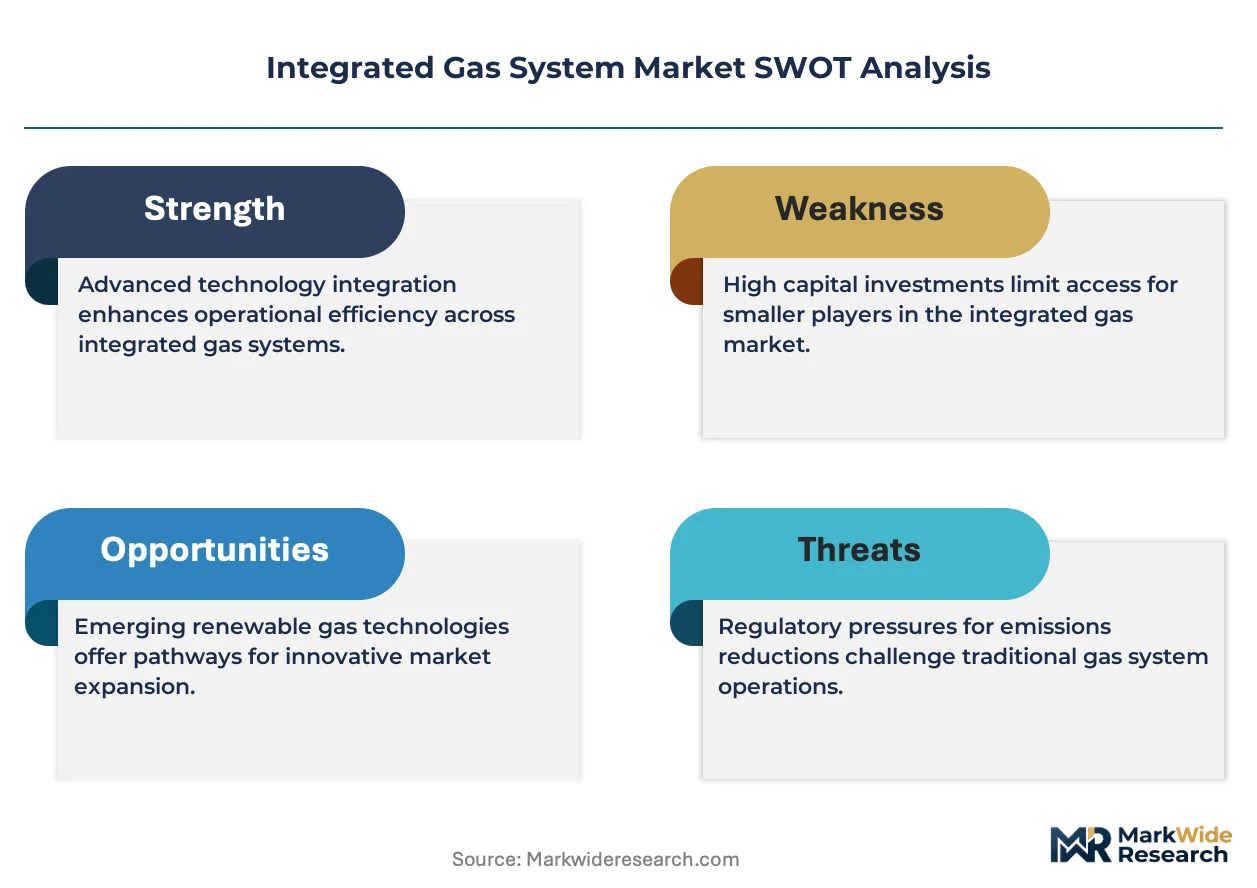
Market Restraints
- Nickel alloy input cost volatility:Cryogenic vessel fabrication depends on specialized nickel-based alloys subject to supply concentration from limited smelter capacity.
- Hydrogen embrittlement material constraints:Existing carbon steel distribution networks face technical limitations for hydrogen service without comprehensive pipeline replacement.
- F-Gas compliance friction:The EU's tightening fluorinated gas phase-down schedules create regulatory uncertainty for refrigeration-integrated gas processing units.
Strategic Opportunities
- Power-to-gas electrolyzer convergence:Electrolyzer-gas handling hybrids are opening white space for vendors bridging renewable electricity to chemical energy storage.
- On-site generation backward integration:Captive air separation and hydrogen production units allow margin capture from industrial consumers seeking supply security.
- Modular brownfield installation:Pre-fabricated skids minimize shutdown windows at operating facilities, creating channel differentiation against field-erected systems.
Industry Challenges
- Cryogenic welding certification timelines:Qualified technicians for LNG and hydrogen service face extended training and qualification periods under pressure equipment directives.
- Legacy SCADA integration complexity:Digital retrofitting of existing gas distribution networks requires harmonization with decades-old control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Gas System Market |
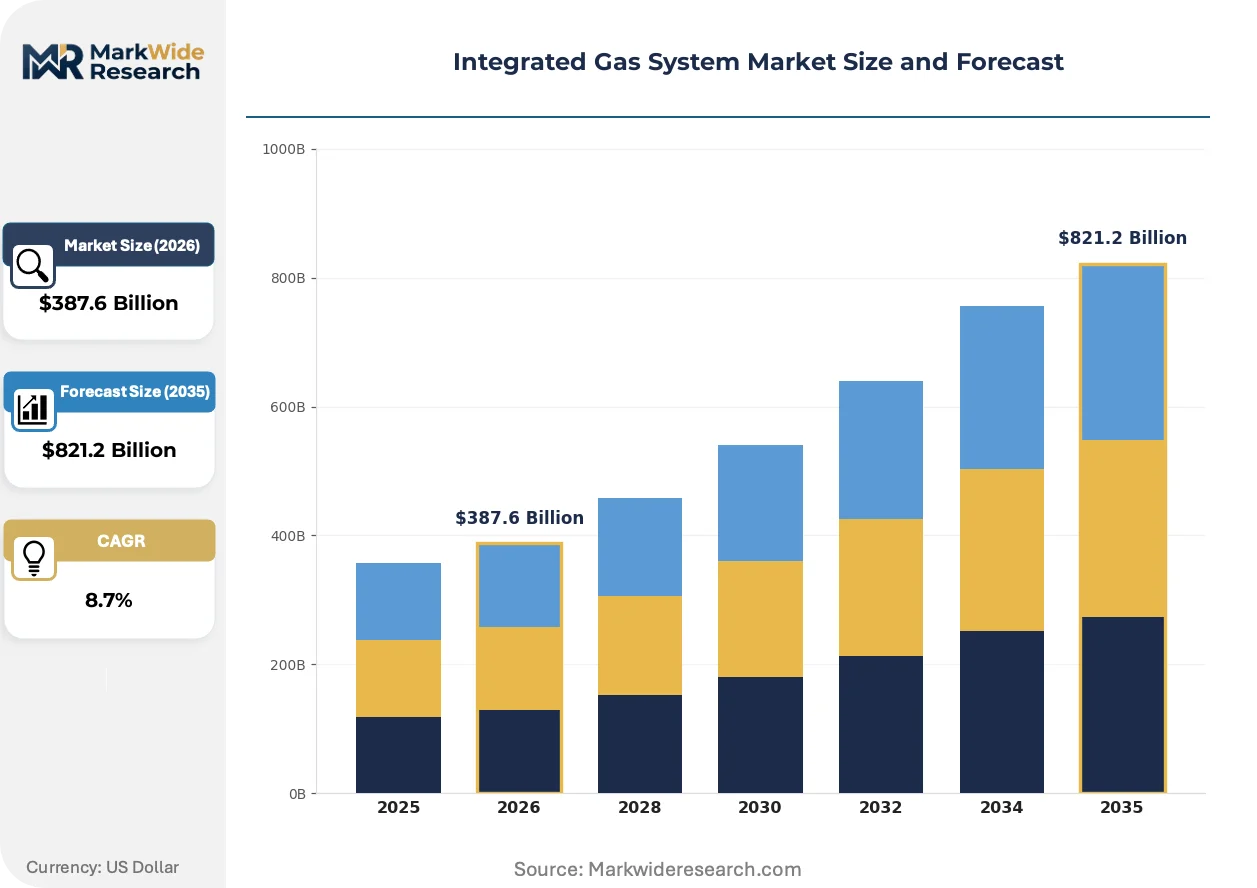
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Storage, Compression Systems, Distribution Networks, Processing Units Installation Type: Onshore Facilities, Offshore Platforms, Hybrid Systems, Modular Units End User: Utility Providers, Industrial Manufacturers, Transportation Sector, Power Generation Technology: CNG, LNG, Biogas, Renewable Gas |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals Inc., Honeywell International Inc., Emerson, Yokogawa, TechnipFMC plc, General Electric Company, Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Gas System Market Shifts & Advancements
Membrane separation architectures and AI-driven predictive maintenance are compressing operational expenditure structures while regulatory pressure on methane intensity accelerates equipment refresh cycles.
Polymeric membrane separation for nitrogen and hydrogen recovery is supplanting cryogenic distillation in mid-scale applications. Food processing and electronics manufacturing facilities are adopting these systems for on-site generation. This technology is supplanting energy-intensive refrigeration cycles, reducing power draw by half in suitable pressure-ratio conditions.
The EPA's methane performance standards are tightening compressor seal specifications and mandating continuous leak detection protocols. US onshore gas processing facilities must retrofit or replace rod packing systems and implement optical gas imaging surveys. This regulatory pressure concentrates capex allocation among midstream operators in the Permian and Appalachian basins.
Aftermarket service contracts are unbundling from initial equipment procurement as buyers seek operational expenditure predictability. Industrial gas consumers in chemicals and refining are separating maintenance agreements from capital purchases, favoring performance-guaranteed service providers. This pattern is most visible in Germany's chemical triangle and the US Gulf Coast petrochemical corridor.
Integrated Gas System Market Segmentation
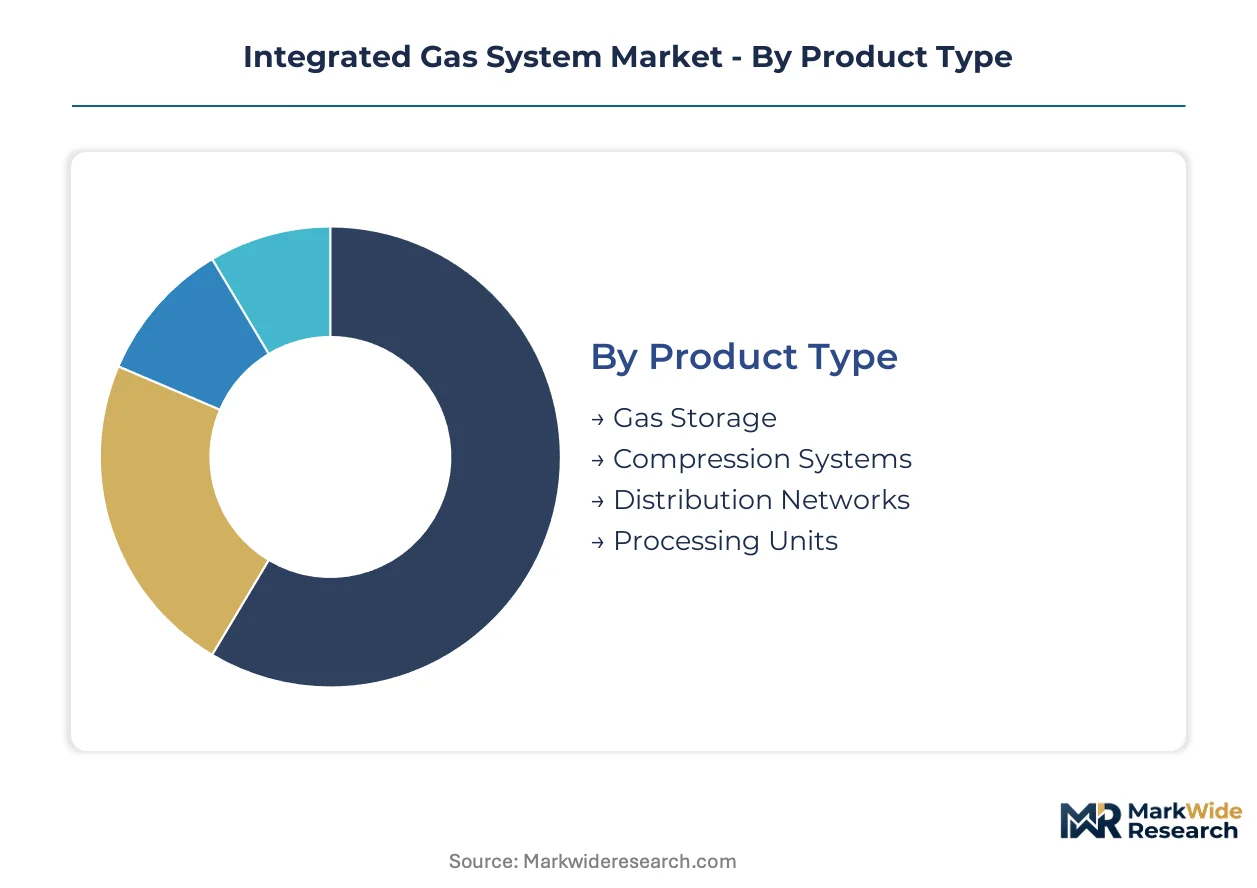
Segmentation reveals where capital allocation concentrates across the integrated gas system value chain. Technology choices determine equipment specifications, while installation methods shape project economics and delivery timelines.
Product Type:
Gas storage and processing units command the deepest margin pools due to long asset lives and captive aftermarket service contracts.
- Gas Storage:Cryogenic and pressurized vessel systems maintain inventory buffers for demand fluctuations. Rhine corridor industrial clusters in Germany are retrofitting hydrogen-compatible storage as blending mandates tighten.
- Compression Systems:Multi-stage compression trains elevate gas pressure for pipeline transport or CNG dispensing. EPA methane performance standards are forcing seal upgrades across Permian basin midstream operators.
- Distribution Networks:Pipeline architectures and valve stations route gases to end-use points. Hydrogen embrittlement constraints limit carbon steel reuse for high-purity hydrogen service.
- Processing Units:Filtration, dehydration, and separation skids condition raw gas streams. Modular processing packages minimize field construction at brownfield chemical facilities.
The dominant share belongs to Gas Storage, while Processing Units is closing the gap fastest.
Installation Type:
Project delivery models diverge sharply between greenfield construction and operational site constraints.
- Onshore Facilities:Field-erected systems dominate large-scale LNG terminals and pipeline compressor stations. German industrial clusters along the Rhine favor onshore hydrogen blending retrofits over greenfield builds.
- Modular Units:Pre-fabricated skids reduce shutdown windows at operating refineries and chemical plants. Fabrication yards in the US Gulf Coast and Rotterdam corridor specialize in cryogenic module assembly.
- Offshore Platforms:Space-constrained topside installations require compact, weight-optimized equipment packages. North Sea operators face decommissioning timelines that compress replacement cycles.
- Hybrid Systems:Combinations of fixed and mobile infrastructure serve fluctuating demand profiles. Remote mining and drilling camps deploy hybrid configurations for supply flexibility.
Onshore Facilities retains the largest installed base, though Modular Units is expanding most quickly as brownfield constraints intensify.
End User:
Customer archetypes determine purity specifications, contract structures, and service intensity.
- Utility Providers:Grid-connected gas distributors manage seasonal demand peaks and supply security obligations. European utilities under EU Green Deal mandates are redirecting capital toward low-carbon gas infrastructure.
- Industrial Manufacturers:Chemical, refining, and metals producers consume process gases at massive scale. Germany's chemical triangle unbundles maintenance contracts from equipment procurement for opex predictability.
- Transportation Sector:CNG and LNG fuelling networks serve heavy trucking and marine vessels. Port authorities in Rotterdam and Singapore specify bunkering infrastructure with dual-fuel compatibility.
- Power Generation:Gas turbine operators require precise fuel conditioning for combustion stability. Peaker plant dispatch patterns stress rapid-start compression systems.
Utility Providers hold the dominant position, while Industrial Manufacturers is gaining share fastest on hydrogen corridor investments.
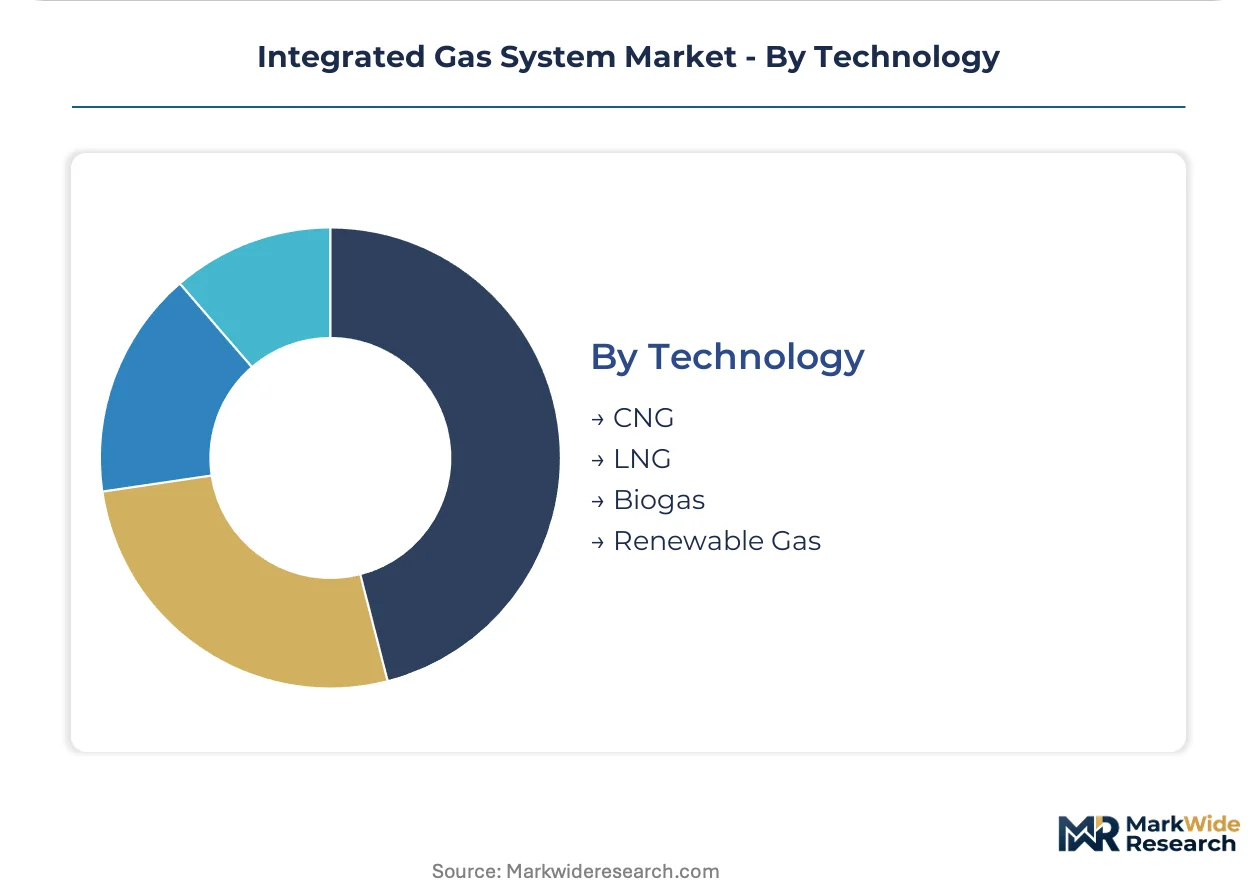
Technology:
Technology selection locks in thermodynamic pathways and regulatory compliance trajectories for decades.
- LNG:Cryogenic liquefaction, storage, and vaporization systems enable intercontinental gas trade. Utility providers are accelerating LNG adoption as the dominant end-use channel for supply diversification.
- CNG:High-pressure compression and cascade storage serve vehicle fuelling and pipeline injection. Urban transit fleets in India and China drive demand for fast-fill station architectures.
- Biogas:Upgrading systems purify anaerobic digester output to pipeline-quality biomethane. Agricultural clusters in Denmark and the Netherlands integrate biogas processing with district heating networks.
- Renewable Gas:Power-to-gas electrolyzer hybrids convert renewable electricity to hydrogen or synthetic methane. Germany's national hydrogen strategy mandates renewable gas quotas for industrial offtake contracts.
LNG maintains the largest technology footprint, though Renewable Gas is climbing the fastest on decarbonization capital flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nickel alloy smelters concentrate in Germany, China, and the United States, creating chokepoints for cryogenic vessel fabrication. Equipment procurement patterns diverge sharply across regulatory jurisdictions.
Germany
Industrial clusters along the Rhine corridor are retrofitting integrated gas networks for hydrogen blending under national hydrogen strategy mandates. The F-Gas Regulation tightens fluorinated gas phase-down schedules for refrigeration-integrated processing units. BASF and Bayer facilities in Ludwigshafen and Leverkusen unbundle maintenance contracts from capital purchases for operational expenditure predictability.
United States
Midstream operators in the Permian and Appalachian basins face EPA methane performance standards forcing compressor seal upgrades and optical gas imaging surveys. FERC oversees interstate pipeline safety protocols that shape distribution network specifications. Gulf Coast petrochemical corridors specialize in cryogenic module assembly for brownfield chemical facilities.
China
MEE dual carbon goals and GB standards on hydrogen purity redirect procurement specifications for new integrated gas investments. Urban transit fleets in Beijing and Shanghai drive demand for fast-fill CNG station architectures. Yangtze River Delta fabrication yards export modular processing skids to Southeast Asian markets.
Japan
METI oversees hydrogen supply chain development targeting industrial decarbonization in steel and chemical sectors. Kansai region refineries adopt membrane separation architectures for nitrogen recovery from process streams. Osaka-based engineering groups specialize in compact, weight-optimized equipment packages for space-constrained installations.
Netherlands
Port authorities in Rotterdam specify bunkering infrastructure with dual-fuel LNG compatibility for marine vessels. Agricultural clusters in Groningen integrate biogas upgrading with district heating networks under EU Green Deal mandates. Rotterdam corridor fabrication yards compete with US Gulf Coast suppliers for modular cryogenic assembly contracts.
Integrated Gas System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Industrial gas majors leverage backward integration into on-site generation to sustain margin pools, while engineering conglomerates differentiate through electrolyzer-gas handling hybrids. Three archetypes dominate: cryogenic engineering specialists, integrated gas generation providers, and power-to-gas workflow bridgers. Consolidation concentrates among European and North American headquarters, with strategic partnerships and geographic expansion as dominant competitive moves.
Within the cryogenic engineering tier, Linde plc and Air Liquide exemplify divergent strategic positions. Linde plc anchors helium and hydrogen distribution architectures through heritage cryogenic capabilities. Air Liquide occupies a position emphasizing captive supply of on-site generation units for industrial consumers seeking supply security. Siemens Energy AG sits within the power-to-gas convergence space, representing the electrolyzer-gas handling hybrid archetype that bridges renewable electricity to chemical energy storage workflows.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals Inc. |
| Honeywell International Inc. |
| Emerson |
| Yokogawa |
| TechnipFMC plc |
| General Electric Company |
| Siemens Energy AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with take-or-pay clauses lock in supply access for cryogenic vessel fabricators while anchoring price visibility across nickel alloy procurement cycles. Industrial gas consumers in Germany's Rhine corridor and US Gulf Coast petrochemical facilities favor these structures to hedge against nickel price volatility under EPA methane compliance timelines.
Pricing Analysis
The EU's F-Gas Regulation dictates the pricing tier structure across refrigeration-integrated gas processing units, compressing margins on fluorinated gas-dependent equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade purity systems from industrial-grade configurations, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard tiers is intensifying because nickel alloy input volatility feeds through to cryogenic vessel fabrication quotes. Utility providers demonstrate highest price sensitivity due to regulated return frameworks, while semiconductor fabs accept premium positioning for ultra-high-purity specifications.
Supply Chain Analysis
Strategic stockpiling of nickel-based alloys dominates inventory strategy among cryogenic vessel fabricators, insulating against smelter concentration risk in Germany, China, and the United States. Raw material procurement draws from specialized nickel alloy feedstock, high-pressure valve castings, and polymeric membrane substrates. Single-source vulnerability concentrates in qualified cryogenic welding technician pools under extended certification timelines. Distribution runs through EPC contractor networks and direct OEM channels to utility providers and industrial manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts unbundling from initial equipment procurement represent the fastest-expanding recurring-revenue layer, outpacing hardware sales growth as industrial consumers prioritize operational expenditure predictability.
For Market Incumbents: Shield installed base positions through captive aftermarket service agreements that extend beyond standard warranty periods. Deepen backward integration into on-site hydrogen generation to capture margin pools from supply-security-seeking chemical producers. Counter modular specialist entrants by embedding predictive maintenance software into legacy SCADA architectures.
For New Entrants and Emerging Players: Anchor in modular brownfield installation services where shutdown window minimization commands premium positioning against field-erected incumbents. Target hydrogen blending retrofit contracts across Germany's Rhine corridor industrial clusters, where national hydrogen strategy mandates accelerate equipment replacement cycles. Lead with electrolyzer-gas handling hybrid configurations that bridge power-to-gas workflows for utility providers under EU Green Deal capital reallocation.
For Investors and Strategic Acquirers: Capital is best deployed toward cryogenic engineering specialists with qualified technician pipelines and heritage helium distribution capabilities. Long-term viability across the analysis window favors vendors with electrolyzer integration competencies and captive aftermarket contract books. Watch hydrogen embrittlement-resistant materials certification progress as the inflection signal for pipeline retrofit demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into On-Site Generation | Captive hydrogen and air separation units capture margin from supply-security-focused chemical producers in Germany's chemical triangle. |
| Modular Brownfield Installation Expansion | Pre-fabricated skids minimize shutdown windows at operating refineries, differentiating against field-erected systems in the US Gulf Coast. |
| Electrolyzer-Gas Handling Hybrid Development | Power-to-gas convergence bridges renewable electricity to chemical storage for utility providers under EU Green Deal mandates. |
| Aftermarket Service Contract Unbundling | Performance-guaranteed maintenance agreements separate from capital purchases, addressing industrial manufacturer opex predictability demands. |
| Hydrogen Embrittlement-Resistant Materials R&D | Pipeline-compatible alloys unlock retrofit opportunities across carbon steel distribution networks facing hydrogen service limitations. |
Research Methodology
Initial hypotheses were tested against primary input from EPC contractors, utility planning officers, cryogenic vessel procurement leads, and aftermarket service directors, then refined through secondary validation. Bottom-up triangulation combined trade customs data on nickel alloy shipments, FERC pipeline safety filings, EPA methane performance standard compliance disclosures, and industrial gas consumer procurement databases. Top-down cross-checks drew from EU Green Deal capital flow tracking and national hydrogen strategy implementation timelines across member states.
Variance decomposition across the projection horizon isolates technology segment contributions, installation type delivery models, and end-user contract structures. Segmentation dimensions modeled include gas storage versus processing unit product types, onshore versus modular installation approaches, and LNG versus renewable gas technology pathways. CAGRs were derived from installed base evolution and replacement cycle acceleration under regulatory compliance deadlines, with hydrogen blending ratio mandates and F-Gas phase-down schedules as key forecast inputs.
Underlying assumptions cover nickel alloy price stability, qualified technician certification throughput, and regulatory harmonization on hydrogen interoperability standards, with deviation risk concentrated in supply concentration for specialized smelter capacity. Revision becomes warranted when hydrogen embrittlement material certification timelines extend beyond equipment replacement windows or when F-Gas compliance friction triggers technology substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Oilfield Services Market