
 United States Oil and Gas Downstream Market | 2026-2036
United States Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Downstream Market Analytics
Midstream pipeline access to coastal export terminals is tilting competitive advantage toward Gulf Coast refiners with deepwater dock capacity. Marathon Petroleum Corp. leverages its integrated logistics network spanning Midwest refineries and retail distribution. Valero Energy Corporation dominates the export-oriented refining segment with substantial capacity positioned along the Texas and Louisiana coastlines.
United States oil and gas downstream operations encompass crude oil refining, product upgrading, and the distribution of finished fuels and petrochemical feedstocks through a network of refineries, terminals, and retail channels. Catalytic reforming and hydrocracking units process heavy sour crudes into higher-value gasoline and diesel fractions meeting stringent sulfur specifications. Gasoline retains the largest share of refined product output, while jet fuel demand recovers fastest from cyclical lows in aviation activity. Logistics and storage infrastructure captures expanding margin pools as crude quality differentials and regional supply imbalances persist.
EPA Tier 3 vehicle emission standards, California Air Resources Board LCFS requirements, and OSHA Process Safety Management rules collectively constrain refinery operations and mandate continuous capital deployment for compliance upgrades. These frameworks elevate operating costs for aging facilities while advantaging newer complexes with lower baseline emissions profiles. Stakeholders must weigh retrofit economics against greenfield alternatives as product specifications tighten and carbon intensity metrics penetrate procurement criteria.
Market Dynamics
Refinery configuration economics are tilting toward integrated petrochemical complexes as Gulf Coast feedstock demand outpaces traditional fuel markets. Marathon Petroleum and Valero Energy have repositioned capital toward chemical-ready units capable of processing Permian light sweet crudes into higher-margin propylene and aromatics streams.
Growth Catalysts
- EPA Tier 3 sulfur standards:Mandates for 10 parts-per-million gasoline sulfur limits force capacity upgrades that favor large integrated refiners with capital deployment flexibility. Smaller merchant facilities face stranded asset risk.
- Petrochemical feedstock pull:Gulf Coast ethylene crackers and derivative plants consume expanding volumes of naphtha and natural gas liquids, redirecting refinery output from transportation fuels to chemical precursors.
- Midwest pipeline network density:Bakken and Permian crude access via Enbridge and Energy Transfer systems lowers delivered feedstock costs for Illinois and Ohio refining clusters.
Market Restraints
- California LCFS carbon intensity scoring:The state's Low Carbon Fuel Standard assigns penalties to conventionally refined products, compressing margins on gasoline and diesel shipped to West Coast markets.
- Renewable diesel feedstock competition:Soybean oil and used cooking grease procurement battles between refiners and biodiesel producers inflate renewable feedstock costs for conventional hydroprocessing units.
- Specialized welder and process operator scarcity:OSHA Process Safety Management compliance requires certified craft labor that the Gulf Coast industrial corridor cannot source at scale.
Strategic Opportunities
- Texas and Louisiana carbon capture hubs:EPA permitting frameworks for Class VI injection wells enable refinery CO2 sequestration projects qualifying for Inflation Reduction Act tax credits.
- Hydrogen blending into existing pipeline infrastructure:Gulf Coast hydrogen network development allows refiners to supply low-carbon fuel to California and Pacific Northwest industrial buyers.
- Renewable diesel retrofit at stranded fluid catalytic cracking units:California demand for renewable diesel creates offtake certainty for Gulf Coast refiners converting FCC capacity to hydrotreating vegetable oils.
Industry Challenges
- OSHA PSM audit preparation and mechanical integrity documentation:Aging pressure vessel inspection backlogs and relief valve testing schedules consume engineering resources at facilities built before 1990.
- Control system cybersecurity hardening:TSA pipeline security directives mandate network segmentation and access logging upgrades for operational technology environments running legacy distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Downstream Market |
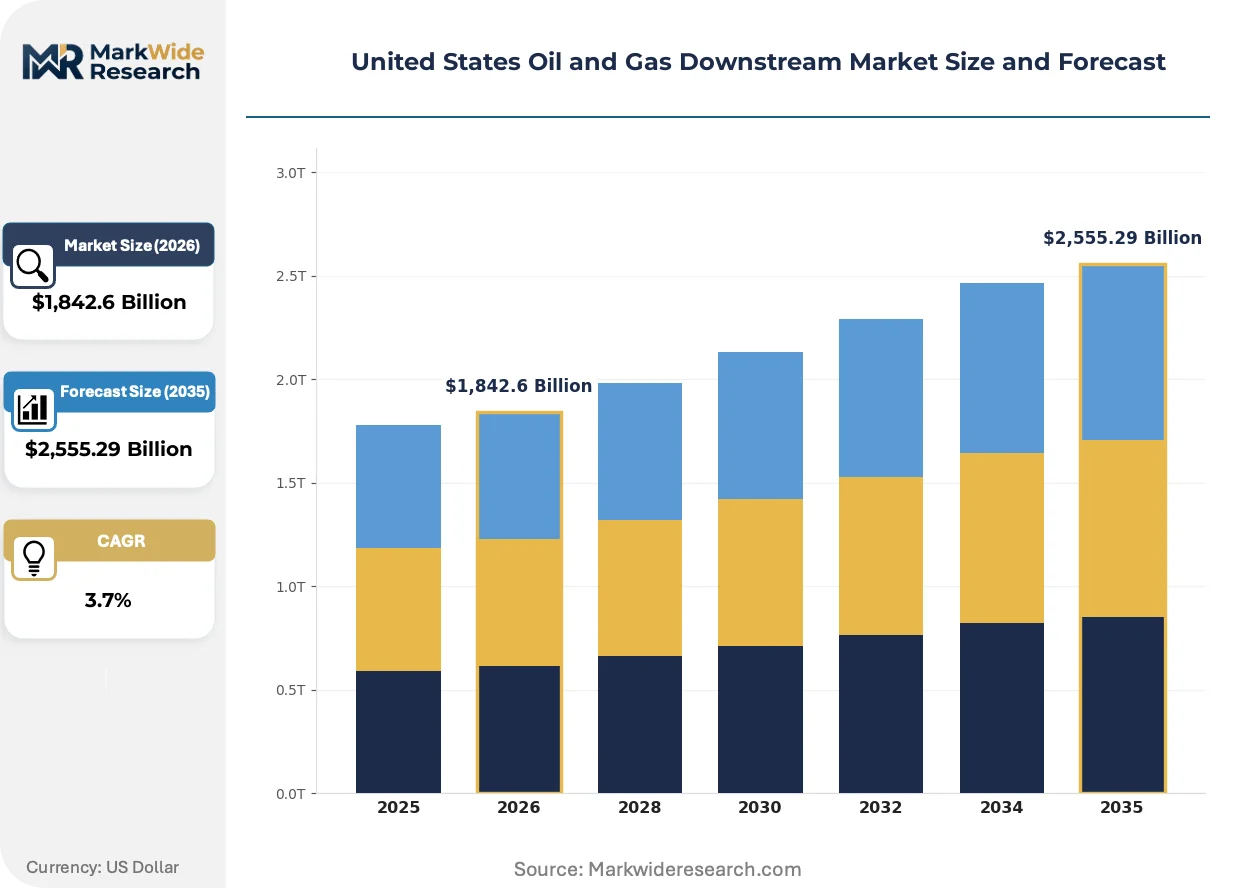
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $2,555.29 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Heating Oil Service Type: Refining, Logistics, Distribution, Storage End User: Transportation, Industrial, Residential, Commercial Technology: Hydrocracking, Catalytic Reforming, Distillation, Gas-to-Liquid |
| Companies Covered | Marathon Petroleum Corp., Chevron Corporation, Phillips 66, Valero Energy Corporation, Exxon Mobil Corporation, HF Sinclair Corp., PBF Energy Inc., CVR Energy Inc., Delek US Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Downstream Market Evolving Landscape
Digital twin deployment and advanced process control systems are compressing the optimization cycle for refinery yield structures. Real-time crude assay integration allows operators to switch feedstock slates within hours rather than days.
Electrified steam methane reforming for hydrogen production is rendering obsolete conventional fired-heater units at Gulf Coast refineries. Phillips 66 and LyondellBasell are piloting 100-megawatt electrolyzer installations to supply hydrocracker hydrogen demand. The technology is compressing Scope 1 emissions profiles while raising electricity procurement as a new operational cost center.
OSHA Process Safety Management enforcement memoranda issued in 2023 intensified scrutiny of Management of Change procedures and near-miss reporting systems. Refiners now deploy predictive analytics on pressure relief events to preempt regulatory citations. The Gulf Coast petrochemical corridor bears the highest inspection density, with facilities in Texas and Louisiana receiving targeted emphasis programs.
California fleet operators and municipal procurement offices now mandate renewable diesel certification for contract fuel supply. Bulk distributors serving Los Angeles and San Francisco ports have reconfigured terminal blending infrastructure to segregate conventional and renewable product streams. The shift is most visible in marine fuel bunkering, where CARB verification requirements displace uncertified distillate.
United States Oil and Gas Downstream Market Segmentation
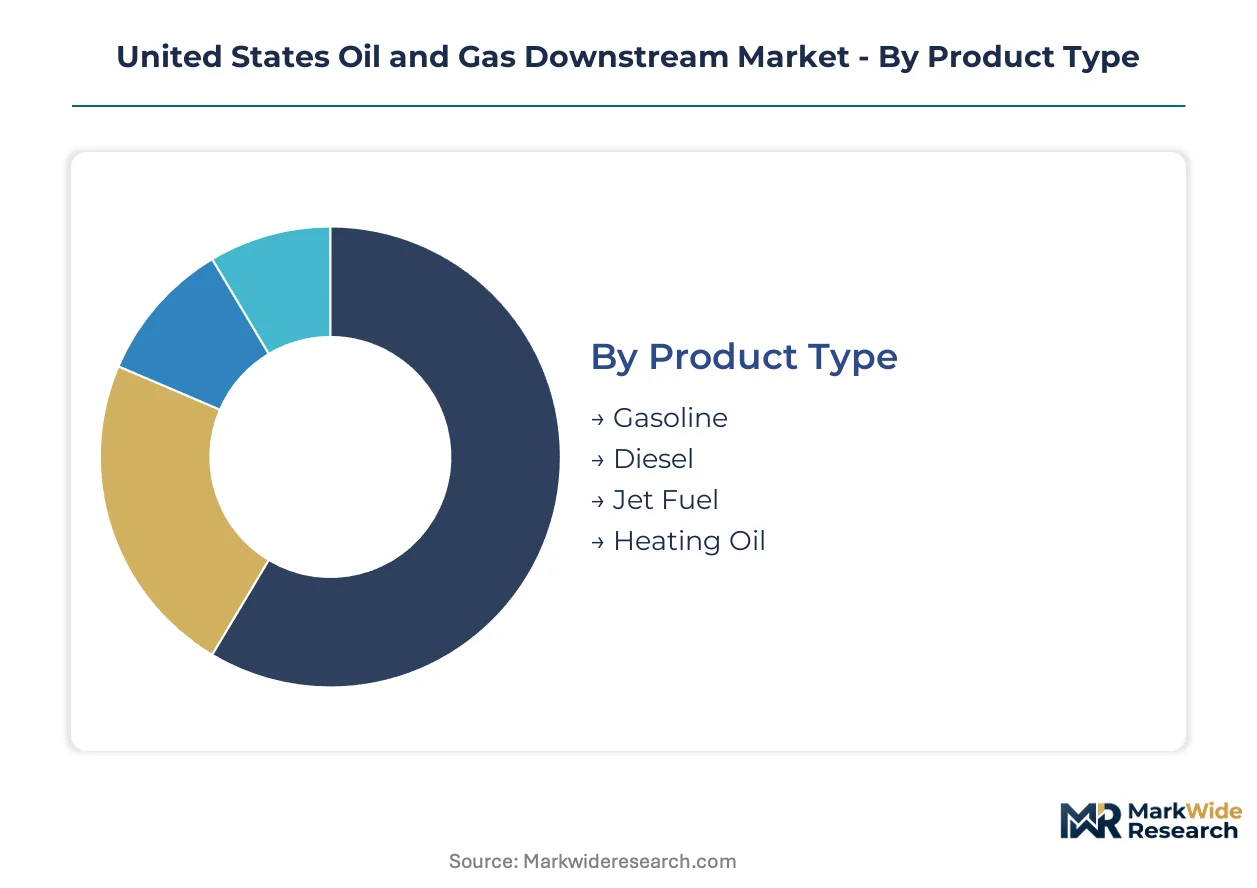
Segmentation in the United States downstream oil and gas sector exposes how regulatory pressure, feedstock quality shifts, and end-use electrification timelines redistribute margin capture across refining configurations and service layers. Understanding these divisions clarifies where capital deployment yields durable returns versus stranded asset exposure.
Product Type:
Cost tier differentiation across refined products reflects sulfur content specifications, octane requirements, and carbon intensity scoring that varies by destination state.
- Gasoline:The largest volume refined product output, formulated to EPA Tier 3 10-ppm sulfur limits and seasonal Reid Vapor Pressure adjustments. Midwest refineries along Enbridge pipeline networks supply Chicago, Detroit, and Ohio demand centers where gasoline dominates transportation fuel consumption.
- Diesel:Ultralow-sulfur distillate meeting 15-ppm standards for on-road use and 500-ppm for non-road applications. Gulf Coast refiners with deepwater export terminals capture premium pricing from Latin American offtake agreements constrained by local refining shortfalls.
- Jet Fuel:Kerosene-based turbine fuel governed by ASTM D1655 specifications for freeze point and thermal stability. Aviation sector recovery post-pandemic drives demand concentration at Atlanta, Dallas-Fort Worth, and Los Angeles airport fueling hubs.
- Heating Oil:Residual fuel oil and distillate grades serving residential and commercial heating in New England and Mid-Atlantic markets. Demand compresses as heat pump electrification accelerates in Massachusetts and New York building codes.
Gasoline commands the established base. The steepest expansion runs through jet fuel as aviation activity normalizes.
Service Type:
Application focus determines margin stability, with asset-heavy refining exposed to crack spread volatility while logistics and storage capture fee-based revenue insulated from commodity cycles.
- Refining:Crude processing through atmospheric distillation, conversion, and upgrading units to produce specification products. Integrated Gulf Coast complexes with petrochemical co-production capabilities achieve superior netbacks versus standalone fuel refiners facing California LCFS carbon intensity penalties.
- Logistics:Pipeline transportation, marine terminaling, and railcar movements connecting production basins to demand centers. Energy Transfer and Enbridge systems dominate Permian and Bakken crude gathering, with tariff structures regulated by FERC rate-of-return methodologies.
- Distribution:Wholesale and retail product delivery through branded and unbranded channels. Marathon Petroleum's integrated network spans Midwest refineries through terminal ownership to company-operated retail locations.
- Storage:Tankage and cavern facilities providing inventory management, blending, and strategic reserve capacity. Cushing, Oklahoma serves as the WTI pricing hub with 90 million barrels of working storage concentrated in a 20-mile radius.
Refining absorbs the capital intensity. Logistics and storage deliver the most stable fee structures across the cycle.
End User:
Volume concentration varies sharply, with transportation consuming the majority of refined product output while industrial demand shifts toward petrochemical feedstocks.
- Transportation:Light-duty vehicles, heavy trucking, aviation, and marine vessels consuming gasoline, diesel, and jet fuel. California fleet electrification mandates and EPA vehicle emission standards compress long-term gasoline demand in coastal markets while diesel persists in long-haul freight corridors.
- Industrial:Petrochemical crackers, asphalt manufacturers, and process heat users requiring naphtha, propane, and residual fuel streams. Gulf Coast ethylene producers pull naphtha away from gasoline blending, redirecting refinery yield structures toward chemical precursors.
- Residential:Home heating, backup power generation, and cooking applications concentrated in rural and Northeastern markets. Heating oil demand erodes as state weatherization programs and building electrification codes advance in Connecticut and Vermont.
- Commercial:Retail fueling stations, construction equipment, and distributed generation serving businesses and municipalities. Fleet operators in Los Angeles and San Francisco ports now mandate renewable diesel certification, reconfiguring terminal infrastructure.
Transportation anchors volume throughput. Industrial offtake is climbing fastest as chemical capacity expands along the Texas and Louisiana corridor.
Technology:
Margin capture depends on conversion depth, with complex units processing heavier, cheaper crudes into higher-value product slates.
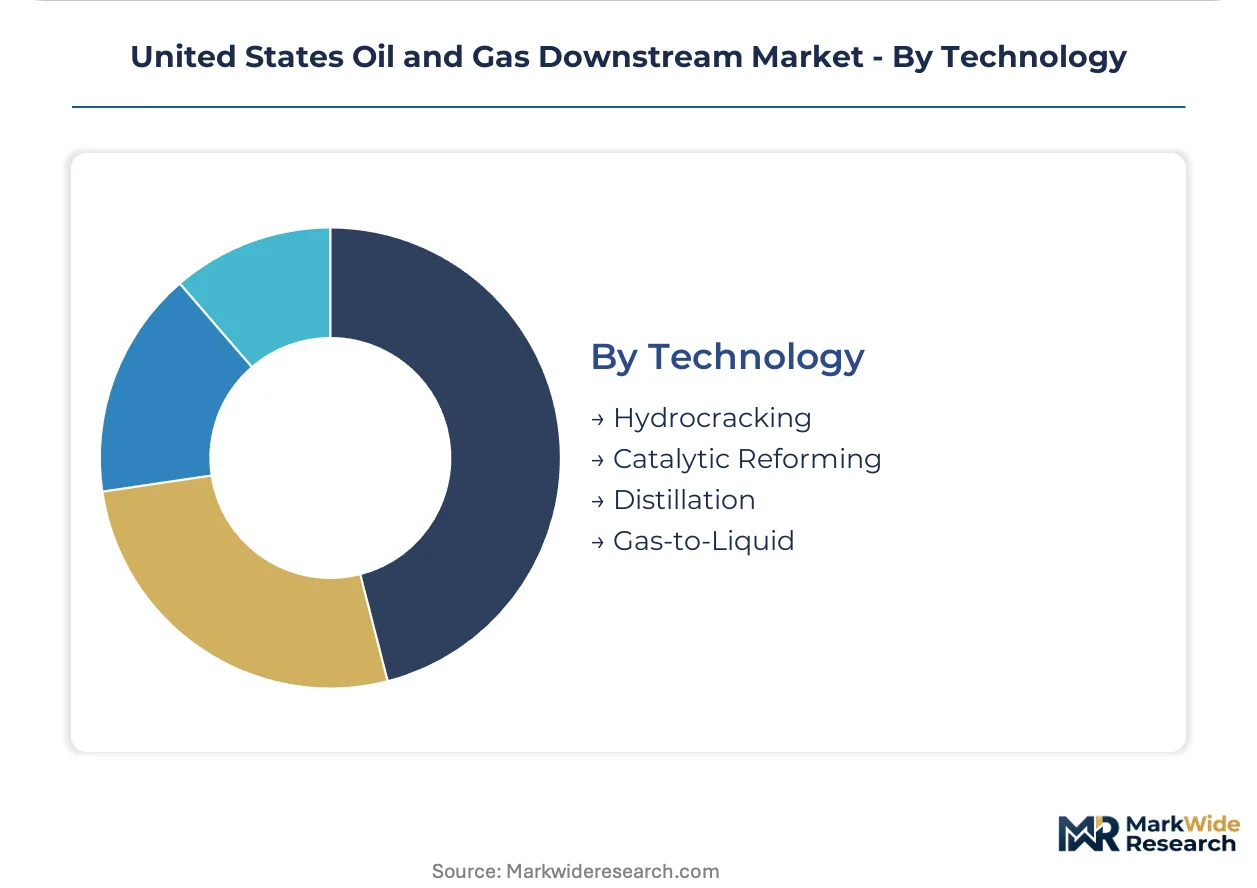
- Hydrocracking:Catalytic hydrogen addition cracking heavy vacuum gas oil into diesel and jet fuel fractions. Gulf Coast refiners with hydrocracker capacity achieve superior yields on discounted heavy sour crude imports while meeting ultralow-sulfur distillate specifications.
- Catalytic Reforming:Naphtha upgrading to high-octane reformate for gasoline blending and aromatics extraction for petrochemical feedstock. Continuous catalyst regeneration designs dominate new installations for hydrogen efficiency and yield optimization.
- Distillation:Atmospheric and vacuum separation of crude into component fractions without molecular transformation. Simple topping refineries face margin compression as light sweet crude premiums erode the value of basic fuel oil production.
- Gas-to-Liquid:Fischer-Tropsch synthesis converting natural gas into synthetic diesel and lubricant base stocks. Small-scale deployment in the United States remains limited by shale oil economics, though pilot projects target stranded gas monetization in the Permian.
Distillation provides the foundational capacity. Hydrocracking and catalytic reforming deliver the deepest margin expansion on complex crude slates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts sharply toward Gulf Coast refiners with deepwater dock capacity, while Midwest operators capture margin through pipeline-fed feedstock cost advantages. California's LCFS program compresses returns on conventional products shipped to West Coast markets, creating a three-zone arbitrage map.
Gulf Coast
Texas and Louisiana host the densest concentration of integrated refining-petrochemical complexes, with Port Arthur and Lake Charles serving as export hubs for Latin American offtake. EPA Class VI permitting frameworks for carbon sequestration enable refinery CO2 capture projects qualifying for Inflation Reduction Act tax credits. The Houston Ship Channel corridor concentrates hydrogen network development and renewable diesel retrofit activity.
Midwest
Illinois and Ohio refining clusters leverage Enbridge and Energy Transfer pipeline networks connecting Bakken and Permian crude supplies to Chicago and Detroit demand centers. EPA Tier 3 sulfur standards favor large integrated refiners with capital deployment flexibility for gasoline hydrotreater upgrades. The Toledo and Detroit refining belts concentrate catalytic reforming capacity serving octane demand in the Great Lakes automotive corridor.
California
Los Angeles and San Francisco Bay Area terminals face margin compression from CARB LCFS carbon intensity scoring that penalizes conventionally refined gasoline and diesel. The state's Low Carbon Fuel Standard mandates renewable diesel certification for fleet procurement contracts, reconfiguring marine fuel bunkering infrastructure at Long Beach and Oakland ports. West Coast refiners redirect yield structures toward renewable feedstock hydrotreating to avoid LCFS deficit obligations.
Pacific Northwest
Washington State refineries at Anacortes and Ferndale supply jet fuel to Seattle-Tacoma and Portland international airports as aviation demand normalizes post-pandemic. Oregon's clean fuels program extends carbon intensity requirements north of California, creating a contiguous regulatory block. The region's hydroelectric grid supports electrified hydrogen production pilot projects targeting hydrocracker feedstock supply.
United States Oil and Gas Downstream Market Competitive Landscape
Integrated majors and independent refiners split the market between petrochemical-integrated complexes and export-oriented fuel specialists. The structure concentrates margin capture among operators with Gulf Coast dock access and Midwest pipeline networks. Three archetypes dominate: integrated oil majors with chemical co-production, independent pure-play refiners with logistics ownership, and merchant refiners dependent on third-party crude supply. Competitive moves center on renewable diesel retrofit commitments and carbon capture hub partnerships.
Within the integrated major tier, Marathon Petroleum Corp., Valero Energy Corporation, and Phillips 66 exemplify divergent strategic positioning. Marathon anchors Midwest refining through integrated logistics spanning Enbridge pipeline access to retail distribution networks. Valero occupies the export-specialist position with substantial capacity concentrated along Texas and Louisiana coastlines. Phillips 66 represents the technology-forward archetype through pilot electrified hydrogen production installations targeting hydrocracker demand.
| Leading Market Players |
|---|
| Marathon Petroleum Corp. |
| Chevron Corporation |
| Phillips 66 |
| Valero Energy Corporation |
| Exxon Mobil Corporation |
| HF Sinclair Corp. |
| PBF Energy Inc. |
| CVR Energy Inc. |
| Delek US Holdings |
| Others |
Value Network & Pricing Analysis
EPA Tier 3 sulfur standard compliance costs determine both the premium spread for specification-grade gasoline and the geographic concentration of viable refinery capacity. This regulatory chokepoint compresses margins at aging Midwest facilities while rewarding Gulf Coast complexes with integrated hydrotreater investments.
Pricing Analysis
Configured-to-order pricing for California LCFS-compliant renewable diesel commands a substantial premium over standard Gulf Coast gasoline spot pricing. Price differentiation hinges on carbon intensity scoring tier and pipeline delivery cost to West Coast terminals. Pricing pressure stems from renewable feedstock procurement battles between conventional refiners and biodiesel producers. Fleet operators in Los Angeles ports exhibit the highest price sensitivity, while export offtake buyers in Latin America absorb premium tiers for specification certainty.
Supply Chain Analysis
Tariff exposure between Canada and the United States on heavy sour crude imports dominates supply chain risk calculus for Midwest refiners. Feedstock sourcing draws from Canada, Mexico, and domestic Permian and Bakken basins. Key inputs include Permian light sweet crude, Canadian heavy sour bitumen, and natural gas liquids for petrochemical integration. Single-source vulnerability concentrates in Enbridge pipeline corridors serving Chicago and Detroit demand centers. Distribution runs through FERC-regulated pipeline networks, marine terminals at Houston and Corpus Christi, and railcar movements to East Coast markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against electrification-driven demand compression in California and Northeast transportation fuel markets. Battery electric vehicle adoption timelines threaten gasoline volume throughput at legacy refining configurations.
For Market Incumbents: Insulate margin capture by accelerating renewable diesel retrofit commitments at stranded fluid catalytic cracking units and securing Class VI carbon sequestration permits for Texas and Louisiana hub participation. EPA Tier 3 compliance cost escalation threatens smaller merchant refiners, creating consolidation opportunities for operators with capital deployment flexibility.
For New Entrants and Emerging Players: Midwest hydrogen blending infrastructure for California-bound pipeline supply represents the most penetrable entry point for low-carbon fuel specialists. Renewable diesel terminaling at Oakland and Long Beach ports offers second-mover advantage as CARB enforcement intensifies. A go-to-market angle anchored in fleet procurement contract certification bypasses established refiner channel control.
For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors integrated petrochemical complexes with deepwater dock access over standalone fuel refiners. Long-term viability rests on chemical feedstock pivot capacity and carbon capture hub positioning. Watch for OSHA PSM enforcement memoranda triggering distressed asset availability in the Gulf Coast corridor.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Retrofit | Converts stranded FCC capacity to capture California LCFS premium pricing and offtake certainty. |
| Carbon Capture Hub Partnership | Secures EPA Class VI permitting for IRA tax credit qualification and Scope 1 emissions reduction. |
| Petrochemical Integration Expansion | Redirects refinery yield from transportation fuels to Gulf Coast ethylene cracker feedstock demand. |
| Hydrogen Network Infrastructure | Supplies low-carbon hydrocracker feedstock to Pacific Northwest industrial buyers via pipeline blending. |
| Pipeline Logistics Ownership | Captures fee-based revenue insulated from crack spread volatility through FERC-regulated tariff structures. |
Research Methodology
A spread of perspectives from refinery operations managers, crude procurement leads at integrated majors, pipeline logistics executives, and EPA regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation against EIA refinery capacity surveys, FERC tariff filings, EPA enforcement databases, and SEC 10-K disclosures. Bottom-up unit economics and top-down sector sizing underwent cross-referencing for triangulation.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included product type tier, service layer, end-use sector, and conversion technology depth. CAGRs emerged from iterative reconciliation of capacity utilization trends, regulatory compliance cost trajectories, and feedstock quality shift assumptions. Crack spread volatility and carbon intensity scoring penetration served as industry-specific forecast inputs.
Practitioners should monitor California LCFS credit price movements and EPA PSM enforcement intensity for early signals of margin compression or asset stranding. Forecasts reflect documented assumptions about electrification timelines and petrochemical demand elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Planned LNG Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Injection Well Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Indonesia Oil and Gas Market