
 Libya Oil and Gas Midstream Market | 2026-2036
Libya Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Libya Oil and Gas Midstream Market Foresight
A capital-intensity divergence between integrated majors and state-backed operators is rotating investment priorities across Libya's midstream landscape. National Oil Corporation leverages its pipeline monopoly and terminal control to dominate onshore crude evacuation routes. Eni S.P.A. sustains deepwater tieback infrastructure at the Bouri and Bahr Essalam fields, competing on offshore gas processing reliability. TotalEnergies anchors downstream connectivity through Mellitah Oil & Gas, the joint venture that operates the 24-inch Greenstream subsea pipeline to Sicily.
Libya Oil and Gas Midstream encompasses the transportation, processing, and storage infrastructure bridging upstream extraction with downstream refining and export, typically involving crude oil pipelines rated for sour service conditions, pressurized natural gas compression stations, and floating storage offloading vessels with dynamic positioning systems. The primary purpose is to maintain continuous hydrocarbon flow from desert and offshore production zones to Mediterranean export terminals and domestic refineries. Pipeline infrastructure leads by deployed asset value given the 4,000-kilometer network spanning the Sirte and Murzuq basins, while offshore facility investment is growing fastest as deepwater gas development resumes at structures like the NC-41 field. Storage facility margins concentrate at Ras Lanuf and Es Sider terminals where tank farm capacity determines export scheduling flexibility for blended crude grades.
Libya's hydrocarbon sector operates under oversight from the National Oil Corporation's regulatory arm and must comply with environmental assessments administered by the country's energy ministry, while international operators face dual jurisdiction from EU REACH obligations on chemical handling at Mediterranean transshipment points and domestic safety standards for pressure vessel integrity. These frameworks shape capital allocation toward leak detection systems and corrosion-resistant pipeline coatings. Stakeholders must monitor whether unified governance emerges from ongoing political settlement efforts, as institutional clarity will determine the pace of trunk line modernization and third-party access terms for independent producers.
Market Dynamics
Pipeline integrity management has become the decisive structural force in Libya's midstream sector, with National Oil Corporation's rehabilitation mandates forcing operators to redirect capital toward corrosion monitoring and leak detection systems rather than greenfield expansion.
Growth Catalysts
- European energy security realignment:Mediterranean refiners are diversifying crude sourcing away from Russian Urals, expanding offtake contracts at Libyan terminals. This demand pull concentrates at Ras Lanuf and Es Sider export facilities.
- Domestic environmental protocol tightening:Libya's energy ministry has imposed stricter spill response and pipeline coating standards. Operators must deploy cathodic protection systems and real-time pressure monitoring to maintain evacuation licenses.
- Deepwater gas development resumption:Subsea tieback infrastructure at structures like NC-41 and Bahr Essalam is accelerating offshore compression station investment. Mellitah Oil & Gas is expanding wet gas handling capacity at the Greenstream landing point in Sicily.
Market Restraints
- Specialized alloy supply concentration:Sour service pipeline steel and corrosion-resistant coatings are sourced through a limited supplier base concentrated in German and Italian manufacturing clusters. Input cost volatility tracks European energy prices.
- Political settlement uncertainty:Institutional fragmentation between competing governance claims in Tripoli and Benghazi delays trunk line modernization tender approvals. Third-party access terms for independent producers remain unresolved.
- Technical limitation in subsea repair:Libya lacks indigenous saturation diving capacity and dynamic positioning vessel fleets. Offshore pipeline maintenance depends on contracted Mediterranean marine service providers with extended mobilization timelines.
Strategic Opportunities
- Sirte Basin corridor rehabilitation:The 800-kilometer network connecting Amal and Nafoora fields to Marsa el Brega terminal offers brownfield efficiency gains. Automated pigging systems and fiber-optic leak detection can extend asset life without full replacement.
- Carbon capture integration at gas processing:Associated gas streams from Mellitah complex operations present early-mover potential for CO2 separation and reinjection. EU Carbon Border Adjustment Mechanism exposure creates incentive alignment with European offtakers.
- Floating storage and offloading vessel deployment:FSO units with dynamic positioning can bypass congestated onshore tank farms at Es Sider. This channel innovation enables direct loading to very large crude carriers without intermediate storage bottlenecks.
Industry Challenges
- Pipeline welding certification backlog:API 1104-qualified welders and ASME-certified inspectors are in acute shortage. Training programs at Libyan technical institutes cannot match rehabilitation schedule demands.
- Legacy SCADA integration complexity:New digital twin and predictive maintenance platforms must interface with 1980s-era control systems at compression stations. Protocol translation and cybersecurity hardening extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Libya Oil and Gas Midstream Market |
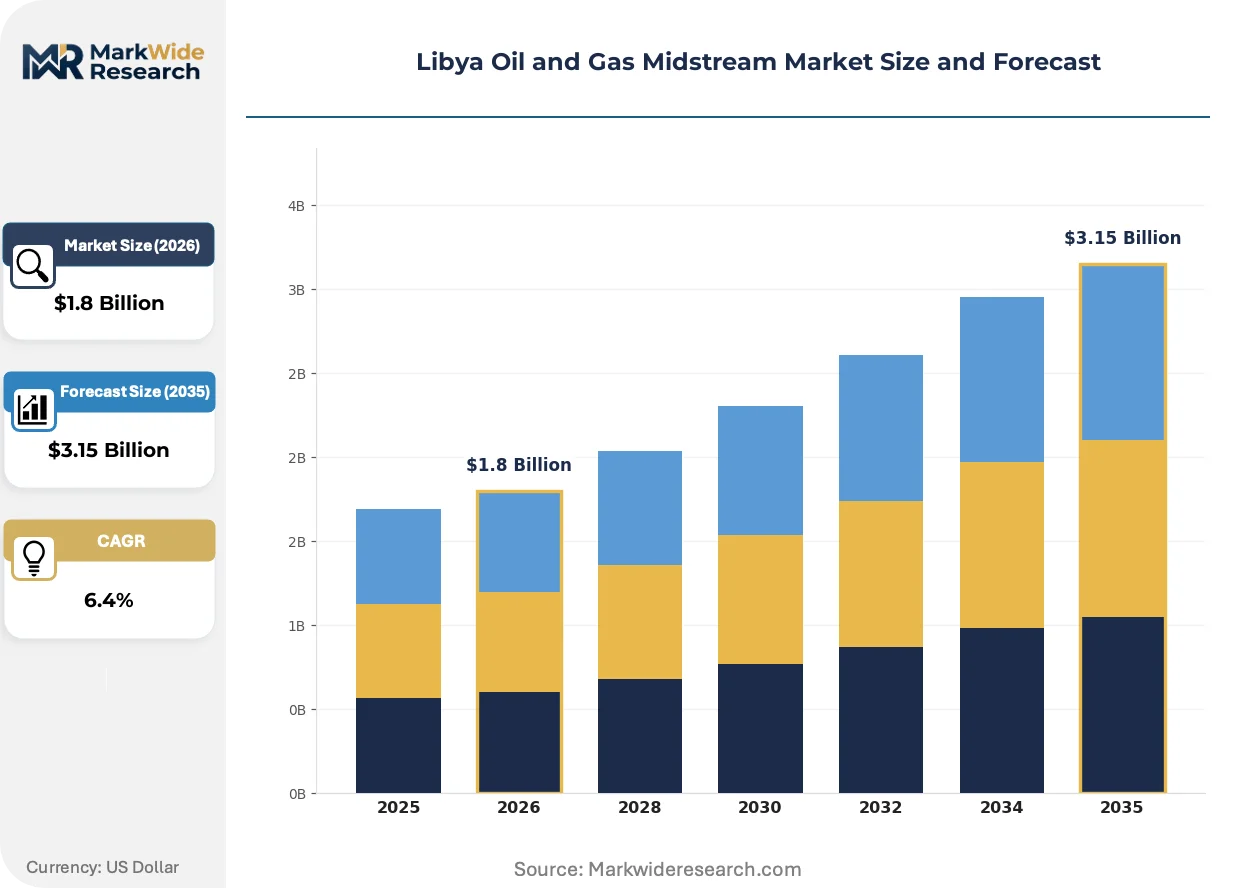
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Pipeline, Storage Facility, Compression Station, Offshore Facility Service Type: Transportation, Processing, Storage, Refining Technology: Automation, Monitoring, Safety Systems, Communication End User: Oil Producers, Gas Distributors, Government Agencies, Enterprises |
| Companies Covered | National Oil Corporation, Eni S.P.A., ConocoPhillips Corporation, TotalEnergies, Chevron, Repsol, Suncor Energy, Arabian Gulf Oil Company, Mellitah Oil & Gas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Libya Oil and Gas Midstream Market Shifts & Advancements
Digital instrumentation and subsea processing architectures are actively reshaping Libya's midstream investment profile, compressing the operational frontier between onshore terminal automation and offshore gas handling sophistication.
Intelligent pigging systems equipped with magnetic flux leakage and ultrasonic testing sensors are fragmenting traditional maintenance scheduling across Libya's trunk line network. National Oil Corporation is deploying these tools on quarterly rather than annual cycles at high-pressure sour service segments. The structural consequence is fragmenting capex allocation between predictive analytics platforms and conventional mechanical inspection contracts.
REACH obligations on chemical handling at Mediterranean transshipment points are tightening solvent and coating disclosure requirements for operators loading at Libyan terminals. Industrial consequence includes mandatory substitution of legacy corrosion inhibitors with biodegradable alternatives. Blended crude export scheduling at Ras Lanuf is most affected, with terminal operators reformulating tank cleaning protocols to maintain EU port access.
Buyer concentration among European refiners is compressing contract negotiation cycles and unbundling traditional long-term offtake structures. Spot market participation at Es Sider and Zawiya terminals is displacing annual term agreements for certain crude grades. This pattern is most visible among Italian and Spanish refiners optimizing Mediterranean sourcing flexibility against Carbon Border Adjustment Mechanism exposure.
Libya Oil and Gas Midstream Market Segmentation
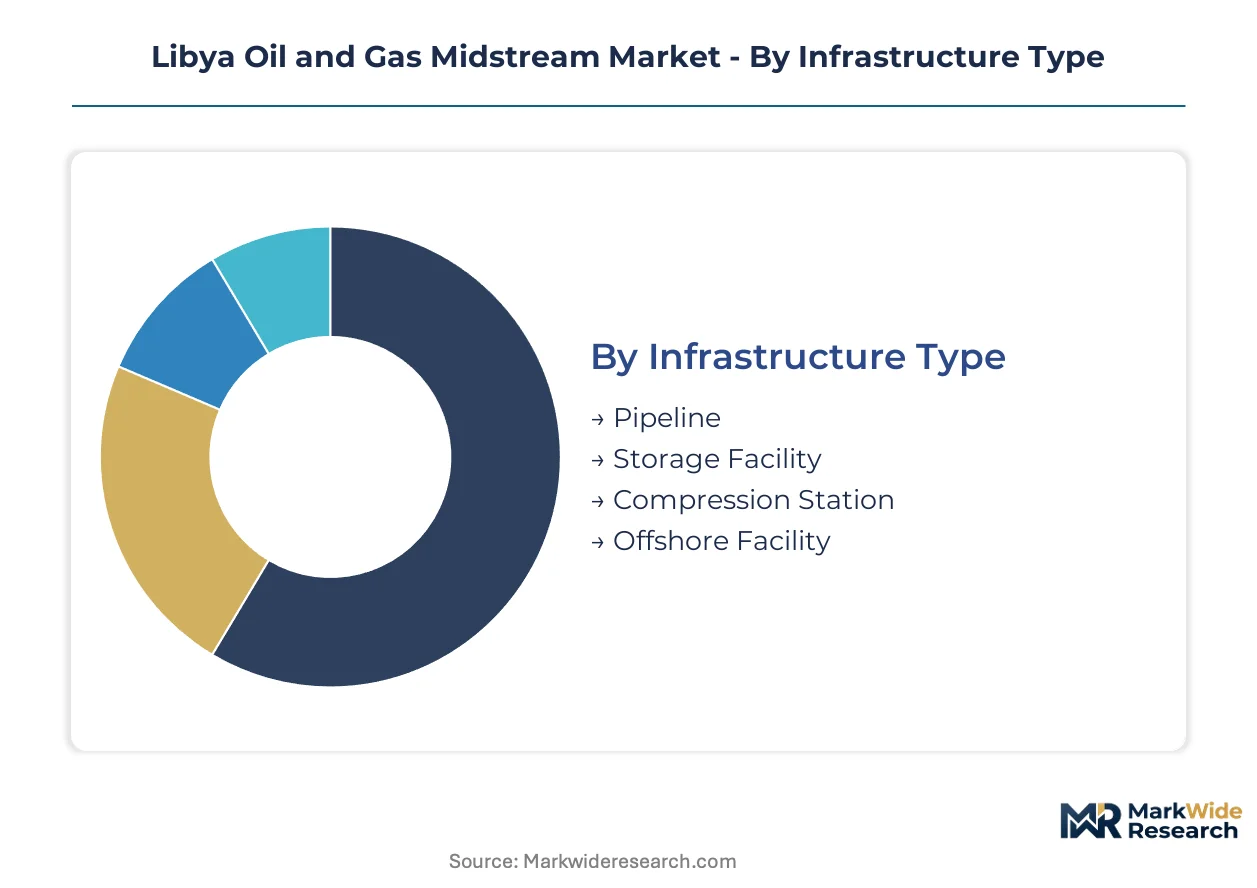
Segmentation in Libya's midstream sector reveals how capital allocation splits between rehabilitation-heavy onshore corridors and technology-intensive offshore gas infrastructure. Each dimension exposes different pressure points: infrastructure type determines asset life extension priorities, while service type shapes revenue stability under volatile export demand.
Infrastructure Type:
Pipeline infrastructure channels the majority of hydrocarbon evacuation volume from Sirte Basin production fields to Mediterranean export terminals, while offshore facilities command premium investment rates for deepwater tieback development.
- Pipeline:Steel trunk lines rated for sour service conditions span roughly 4,000 kilometers across desert basins. Demand concentrates in the Sirte Basin corridor where National Oil Corporation mandates cathodic protection upgrades and automated pigging systems to extend asset life under stricter domestic environmental protocols.
- Storage Facility:Tank farms at Ras Lanuf and Es Sider terminals provide crude blending and export scheduling flexibility. Investment is accelerating at Es Sider where floating storage alternatives are being evaluated to bypass congestion bottlenecks for very large crude carrier loading.
- Compression Station:Pressurized natural gas facilities maintain flow assurance across gathering networks and processing trains.
- Offshore Facility:Subsea tieback infrastructure at Bahr Essalam and NC-41 fields requires dynamic positioning vessel support and wet gas handling capacity.
Pipeline dominates installed base. Offshore facility is where expansion concentrates.
Service Type:
Service specialization determines margin stability: transportation and storage generate fee-based revenue under take-or-pay structures, while processing and refining expose operators to commodity price spreads and quality differentials.
- Transportation:Crude and natural gas evacuation services move production from wellhead to terminal through pipeline networks and marine loading systems. Oil Producers in the Murzuq Basin depend on trunk line availability to reach Zawiya export facilities, with scheduling priority disputes emerging during maintenance windows.
- Processing:Gas separation, dehydration, and conditioning prepare hydrocarbon streams for pipeline specification or LNG feedstock. Associated gas from Mellitah complex operations presents carbon capture integration potential as EU Carbon Border Adjustment Mechanism exposure reshapes offtaker requirements.
- Storage:Tank farm operations and floating storage offloading vessel deployment enable inventory management and blending operations.
- Refining:Domestic refining connectivity at Marsa el Brega and Zawiya processes crude for local product supply.
Transportation commands the largest revenue share. Processing is climbing the fastest as deepwater gas development resumes.
Technology:
Technology deployment splits between legacy system hardening and new digital architecture, with automation and monitoring absorbing capital as operators confront SCADA integration complexity.
- Automation:Digital control systems and predictive maintenance platforms interface with 1980s-era infrastructure at compression stations. Government Agencies mandate protocol translation and cybersecurity hardening as conditions for evacuation license renewal.
- Monitoring:Intelligent pigging with magnetic flux leakage sensors and fiber-optic leak detection systems enable quarterly inspection cycles. National Oil Corporation deploys these tools at high-pressure sour service segments to satisfy pipeline integrity management mandates.
- Safety Systems:Pressure relief, emergency shutdown, and fire suppression equipment protect personnel and assets.
- Communication:SCADA network upgrades and field telemetry infrastructure support remote operations.
Monitoring holds the largest installed technology base. Automation is gaining share fastest as predictive analytics platforms fragment traditional mechanical inspection contracts.
End User:
End user concentration shapes contract structures: Oil Producers and Gas Distributors negotiate throughput agreements, while Government Agencies set regulatory terms and Enterprises consume refined products.
- Oil Producers:Upstream operators require continuous evacuation capacity from desert and offshore production zones. Independent producers in the Sirte Basin seek third-party access terms to trunk line networks, with political settlement uncertainty delaying framework resolution.
- Gas Distributors:Mellitah Oil & Gas and similar entities manage subsea pipeline corridors to European markets. Greenstream subsea pipeline operations to Sicily anchor their infrastructure investment priorities as Mediterranean energy security realignment expands offtake demand.
- Government Agencies:National Oil Corporation and energy ministry entities regulate licensing and environmental compliance.
- Enterprises:Domestic industrial and power generation consumers purchase refined products from local refineries.
Oil Producers dominate throughput volume. Gas Distributors represent the steepest expansion trajectory as European refiners diversify crude sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Libya commands pricing leverage over Mediterranean refiners through Ras Lanuf and Es Sider terminal access, while Italian and Spanish buyers extract volume flexibility through spot market participation. This asymmetry shapes contract structures across the basin.
Tripoli
Central governance functions and National Oil Corporation headquarters concentrate administrative control over export licensing. The energy ministry enforces pipeline integrity mandates through cathodic protection requirements. Zawiya refinery connectivity and coastal tank farms anchor crude scheduling operations for western production basins.
Benghazi
Eastern administrative claims compete for regulatory authority over Sirte Basin trunk lines. Political settlement uncertainty delays third-party access framework approvals for independent producers. Marsa el Brega terminal and associated compression stations handle the bulk of domestic refining throughput.
Sirte Basin Corridor
Amal and Nafoora field evacuation routes depend on 800-kilometer pipeline networks requiring automated pigging upgrades. National Oil Corporation mandates quarterly intelligent inspection cycles using magnetic flux leakage sensors. Brownfield rehabilitation concentrates contractor resources on fiber-optic leak detection deployment.
Mellitah Complex
Greenstream subsea pipeline landing operations in Sicily anchor European gas export capacity. Wet gas handling expansion responds to Carbon Border Adjustment Mechanism pressure from EU offtakers. Associated gas streams present carbon capture integration potential for early-mover positioning.
Offshore Deepwater Blocks
NC-41 and Bahr Essalam structures drive subsea tieback infrastructure investment. Dynamic positioning vessel dependence creates maintenance bottlenecks given limited indigenous marine service capacity. Compression station commissioning tracks resumption timelines for suspended field developments.
Libya Oil and Gas Midstream Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Libya's midstream sector. National Oil Corporation dominates onshore pipeline networks through statutory monopoly and terminal control, while integrated majors compete on offshore gas processing sophistication. The structure splits between state-backed operators with evacuation license authority and international partners with subsea engineering capabilities. Competitive moves concentrate on brownfield asset rehabilitation partnerships and carbon capture integration positioning for EU market access.
Within the state-dominated tier, National Oil Corporation exemplifies pipeline monopoly archetype control over crude evacuation routes. Among international integrated majors, Eni S.P.A. and TotalEnergies occupy positions anchored by deepwater field equity and subsea infrastructure joint ventures. Mellitah Oil & Gas represents the bilateral venture model linking Libyan state interests with European operator technical capacity.
| Leading Market Players |
|---|
| National Oil Corporation |
| Eni S.P.A. |
| ConocoPhillips Corporation |
| TotalEnergies |
| Chevron |
| Repsol |
| Suncor Energy |
| Arabian Gulf Oil Company |
| Mellitah Oil & Gas |
| Others |
Supply & Pricing Matrix
Biodegradable corrosion inhibitor substitution for legacy solvent-based coatings simultaneously redraws procurement geography toward German and Italian specialty chemical clusters and compresses margin structures at Ras Lanuf terminal operations. This input transition forces terminal operators to absorb REACH compliance costs while negotiating offtake terms with European refiners.
Pricing Analysis
The customization-premium spread between standard trunk line rehabilitation contracts and configured-to-order subsea tieback projects widens as offshore gas development resumes. Contract-based long-term offtake structures dominate pipeline services, while spot market participation at Es Sider and Zawiya terminals accelerates for certain crude grades. Price differentiation rests on certification tier alignment with EU environmental protocols and volume scale commitments from Mediterranean refiners. Cost compression in standard pipeline maintenance is intensifying because cathodic protection system deployment has become commoditized, while integrated majors with offshore gas equity show least price sensitivity given strategic positioning requirements.
Supply Chain Analysis
Inventory lead times for sour service pipeline steel and ASME-certified pressure vessel components extend to 18-24 months, constraining rehabilitation scheduling flexibility. Supply concentrates in German and Italian manufacturing clusters for corrosion-resistant coatings and specialized alloys, while dynamic positioning vessel fleets for offshore maintenance draw from Mediterranean marine service providers in Italy, Spain, and Greece. Raw material dependencies center on nickel-alloy steel, high-performance epoxy coatings, and subsea umbilical assemblies. Single-source vulnerability in saturation diving capacity creates maintenance bottlenecks for Bahr Essalam and NC-41 field infrastructure. Distribution runs through National Oil Corporation's terminal control network and Mellitah Oil & Gas joint venture channels to European offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Libya Oil and Gas Midstream Market sits in early-cycle recovery as European energy security realignment pulls Mediterranean crude demand toward Libyan terminals. Capital deployment timing favors brownfield rehabilitation over greenfield expansion.
For Market Incumbents: Fortify pipeline integrity management capabilities through automated pigging system deployment and fiber-optic leak detection integration at Sirte Basin corridors. Deepen vertical integration into cathodic protection services to defend margin position against specialized alloy cost volatility from German and Italian supplier concentration. Accelerate carbon capture feasibility studies at Mellitah complex operations to preempt EU Carbon Border Adjustment Mechanism exposure.
For New Entrants and Emerging Players: Differentiate on subsea repair and dynamic positioning vessel contracting capabilities, where indigenous Libyan capacity gaps create service bottlenecks. Target floating storage and offloading vessel deployment at Es Sider terminal congestion points, the most penetrable infrastructure segment given tank farm capacity constraints. Pursue partnership structures with National Oil Corporation for third-party trunk line access once political settlement clarifies regulatory frameworks.
For Investors and Strategic Acquirers: The market sits at a rehabilitation-heavy phase that favors technical service specialists with pipeline integrity platform expertise. Long-term viability over the coming decade hinges on institutional governance consolidation and sustained European offtake diversification from Russian supply sources. Acquisition target archetypes include Mediterranean marine service providers with saturation diving assets and predictive analytics platforms for SCADA integration. Watch political settlement progress between Tripoli and Benghazi governance claims as the critical inflection signal for trunk line modernization tender acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Integrity Management Platform Deployment | National Oil Corporation mandates accelerate intelligent pigging adoption across 4,000-kilometer network. |
| Subsea Tieback Infrastructure Expansion | NC-41 and Bahr Essalam field resumption drives wet gas handling investment at Mellitah complex. |
| Carbon Capture Integration Feasibility | EU Carbon Border Adjustment Mechanism exposure creates incentive alignment with Italian and Spanish refiners. |
| Floating Storage and Offloading Vessel Deployment | FSO units with dynamic positioning bypass Es Sider tank farm congestion for very large crude carrier loading. |
| REACH Compliance Chemical Substitution | Biodegradable corrosion inhibitor reformulation maintains EU port access for blended crude exports. |
Research Methodology
A spread of perspectives from pipeline operations managers, subsea engineering contractors, European refinery procurement leads, and National Oil Corporation regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with compression station maintenance directors and terminal scheduling officers alongside secondary validation through customs data on specialized alloy imports, EU REACH compliance filings, and Mediterranean marine service fleet registries. Bottom-up capacity modeling and top-down demand aggregation from European refinery intake data were triangulated against project development timelines.
Segmentation dimensions modeled span infrastructure type, service specialization, technology deployment, and end-user concentration across the projection horizon. The analytical framework derived CAGRs from historical capital expenditure patterns and announced rehabilitation schedules, with growth trajectories stress-tested against political settlement scenarios and European offtake contract renewal rates. Industry-specific forecast inputs include pipeline integrity management mandate compliance timelines and subsea field development resumption announcements.
The analysis sits within stated boundaries; outcomes outside sustained European demand diversification or unified Libyan governance emergence would require recalibration. Forecasts reflect documented assumptions on rehabilitation schedule execution and offshore gas field commissioning timelines. Political fragmentation, specialized alloy supply disruption, and subsea repair capacity constraints represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Shale Shakers Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Kuwait Oilfield Services Market