
 Coiled Tubing Services Market | 2026-2036
Coiled Tubing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Coiled Tubing Services Market Analysis
The capital-intensity divergence between integrated service conglomerates and regional specialists is rotating competitive advantage toward asset-heavy operators with captive manufacturing. Halliburton Company leverages its vertical fabrication network to control alloy sourcing for high-pressure applications. Baker Hughes Company sustains technology leadership through proprietary continuous-monitoring systems. Superior Energy Services, Inc. anchors its position in Gulf of Mexico offshore interventions where mobilization logistics favor established fleet operators.
Coiled tubing services deploy continuous-length steel or composite pipe spooled on large drums to perform well intervention, drilling, and stimulation without interrupting production flow. Typical units handle tubing diameters from one to three and one-half inches at working pressures exceeding ten thousand psi, with reel capacities reaching thirty thousand feet for extended-reach operations. Well intervention commands the largest revenue share as mature fields require escalating workover frequency to maintain output. Automated systems represent the fastest-expanding technology segment as operators deploy remote-actuated stripper assemblies and real-time fatigue tracking to reduce personnel exposure and non-productive time. Onshore deployment dominates volume, though offshore applications generate premium pricing due to marine logistics complexity and equipment redundancy requirements.
API 5ST standards govern tubing material grades and fatigue-life calculations across North American operations, while BSEE regulations in the US Gulf mandate blowout preventer redundancy for subsea interventions. The EPA's methane emissions rules are accelerating demand for live-well intervention techniques that eliminate flaring during completion work. Stakeholders must monitor how carbon-intensity disclosure requirements reshape contractor qualification criteria and capital allocation toward lower-emission service technologies.
Market Dynamics
API 5ST specification revisions are forcing capital reallocation toward fatigue-rated alloy grades as operators extend lateral reach beyond fifteen thousand feet in unconventional basins. Equipment certification cycles now determine fleet deployment velocity more than raw capacity.
Growth Catalysts
- Extended-reach well architecture:Permian Basin operators deploy coiled tubing units for laterals exceeding twelve thousand feet, requiring continuous-length pipe with enhanced fatigue resistance. Reel capacity expansion drives replacement demand across North American onshore fleets.
- EPA methane emissions rules:Live-well intervention techniques eliminate flaring during completion work, accelerating contractor qualification for zero-vent operations. Regulatory compliance creates technology pull for closed-loop circulation systems.
- Real-time fatigue monitoring:Embedded sensor arrays track pipe stress cycles during intervention, enabling predictive retirement and reducing downhole failures. Adoption concentrates among supermajors with proprietary well databases.
Market Restraints
- Specialized alloy supply concentration:High-strength chromium-molybdenum steel sourcing concentrates among integrated mills in Germany and Japan, exposing service companies to billet allocation constraints and extended lead times.
- Deepwater BSEE redundancy mandates:US Gulf subsea interventions require dual blowout preventer stacks, doubling mobilization cost and compressing contractor margins on fixed-price contracts.
- Composite pipe substitution:Carbon fiber-reinforced thermoplastic lines achieve weight reductions exceeding sixty percent for certain intervention applications, displacing steel in corrosion-sensitive offshore environments.
Strategic Opportunities
- Argentina Vaca Muerta development:Neuquén Basin shale expansion lacks indigenous coiled tubing capacity, creating fleet deployment openings for operators with modular equipment and local partnership structures.
- EU Green Deal methane intensity disclosure:CSRD-aligned carbon reporting requirements favor service providers with certified low-emission intervention technologies, differentiating European contractors in qualification rounds.
- Remote-actuated stripper assemblies:Integration of automated wellhead sealing with real-time pressure telemetry reduces personnel exposure and enables continuous operations in high-H2S environments.
Industry Challenges
- Experienced coil operator scarcity:Fatigue-life calculation expertise and downhole dynamics modeling skills concentrate among aging specialists, constraining fleet expansion velocity for regional entrants.
- API 5ST certification timeline compression:Revised material grade testing protocols extend qualification cycles for new alloy formulations, delaying commercial deployment of next-generation high-pressure strings.
- Legacy SCADA integration friction:Real-time monitoring systems require retrofitting analog-era reel control architectures, generating downtime and compatibility failures during initial deployment phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coiled Tubing Services Market |
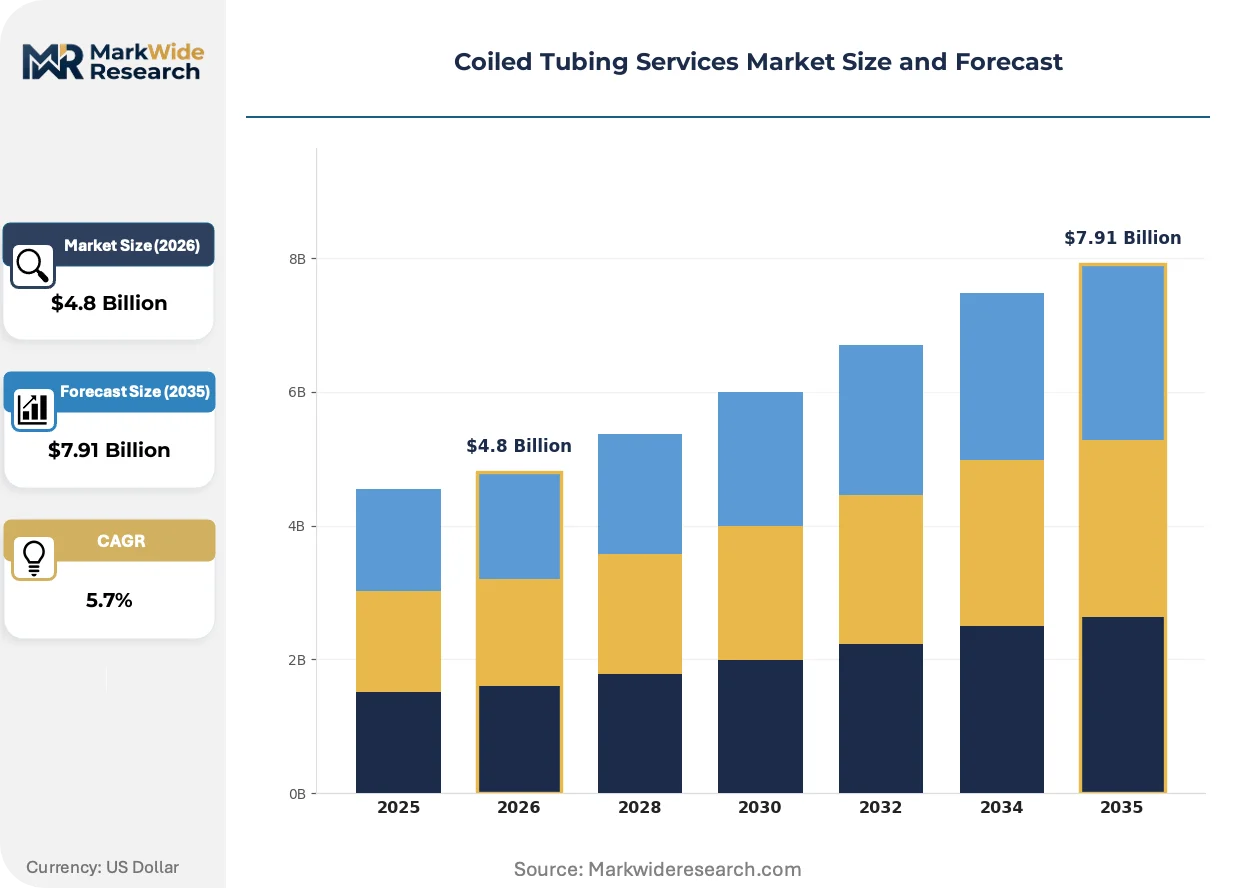
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Intervention, Drilling, Cementing, Stimulation End User: Oil Companies, Gas Producers, Service Providers, Contractors Deployment: Onshore, Offshore, Land-Based, Integrated Technology: Automated Systems, Pressure Control, Monitoring Solutions, Data Acquisition |
| Companies Covered | Weatherford International plc, Superior Energy Services, Inc., Schlumberger Limited, Trican Well Service Ltd., Calfrac Well Services Ltd., Halliburton Company, Nabors Industries Ltd, National-Oilwell Varco Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coiled Tubing Services Market Emerging Trajectories
Digital thread technologies are compressing the feedback loop between downhole measurement and surface equipment control, enabling closed-loop intervention automation that reduces non-productive time.
Composite-reinforced coiled tubing is bifurcating the intervention market into weight-critical offshore applications and cost-sensitive onshore operations. North Sea operators adopt hybrid carbon-steel strings for platform crane limitations, while Permian contractors retain conventional steel for abrasion tolerance in proppant-laden flowback. The technology is bifurcating vendor specialization between marine-certified fabricators and land-focused volume producers.
REACH substance restrictions on chromium VI compounds are accelerating plasma coating adoption for corrosion protection in European offshore operations. The industrial consequence eliminates hexavalent chromium surface treatments from supply chains serving North Sea platforms. Norwegian contractors now qualify alternative metallization processes through DNV certification frameworks.
Integrated service contracting is consolidating procurement decisions among supermajor engineering teams, compressing vendor lists to operators with captive manufacturing and real-time data platforms. Independent regional specialists face exclusion from long-term frame agreements. This concentration is most visible in US unconventional basins where drilling and completion budgets consolidate under integrated project management structures.
Coiled Tubing Services Market Segmentation
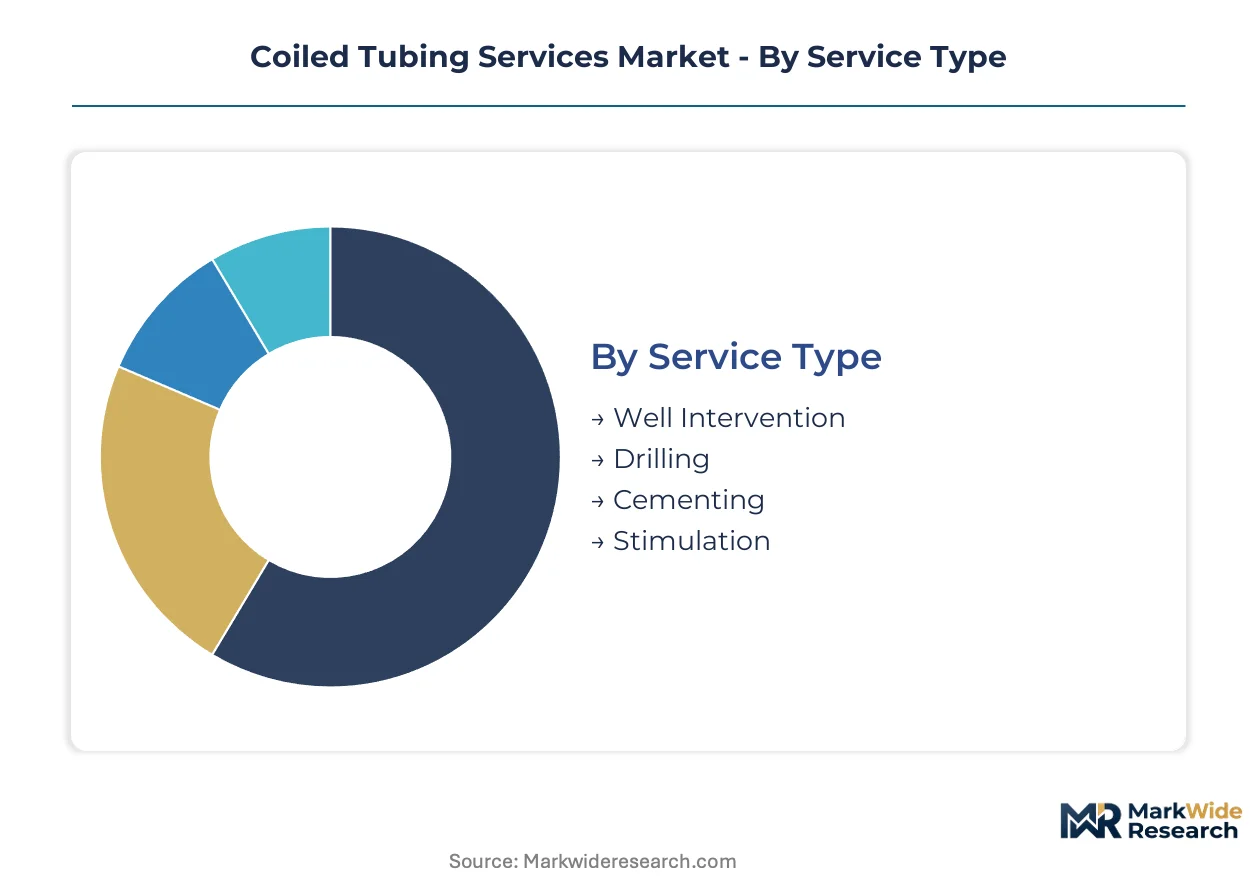
Coiled tubing services fragment across four critical dimensions that determine equipment specification, pricing power, and channel strategy. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape contractor qualification requirements.
Service Type:
Channel mix varies sharply by intervention complexity, with integrated service providers dominating bundled offerings while independent specialists capture discrete well intervention contracts.
- Well Intervention:Workover operations deploy continuous-length pipe for cleanouts, acidizing, and mechanical repairs without killing the well. Permian Basin operators drive demand for extended-reach interventions beyond twelve thousand feet, where fatigue-rated strings command premium day rates. By volume, well intervention leads. By growth pace, stimulation is ahead.
- Stimulation:Hydraulic fracturing support via coiled tubing delivers precise fluid placement in multi-stage completions. Neuquén Basin Vaca Muerta development lacks indigenous capacity, creating deployment openings for modular fleet operators with local partnership structures.
- Drilling:Slim-hole re-entry applications reduce rig time for marginal field redevelopment.
- Cementing:Remedial squeeze operations seal annular gas migration in aging wellbores.
Stimulation services expand most quickly as unconventional completion intensity rises, while well intervention retains the largest revenue base.
End User:
Cost tier stratification separates supermajor engineering teams with integrated procurement from independent operators purchasing discrete services.
- Oil Companies:Integrated majors consolidate spending under long-term frame agreements that favor vendors with captive manufacturing and real-time data platforms. US unconventional basins concentrate this procurement power among five operators controlling sixty percent of drilling and completion budgets.
- Gas Producers:Dry gas developers in Alberta's Montney formation prioritize live-well intervention techniques to eliminate flaring during completion work, accelerating contractor qualification for zero-vent operations under EPA methane rules.
- Service Providers:Subcontracting specialists fill fleet gaps during demand spikes.
- Contractors:Regional independents compete on mobilization speed for single-well campaigns.
Oil companies dominate contract value, though gas producers are gaining share fastest as LNG export capacity expands.
Deployment:
Application environment dictates equipment redundancy requirements and margin structure, with marine logistics compressing contractor economics despite premium pricing.
- Onshore:Land-based operations handle the majority of coiled tubing footage, with Permian and Montney basins concentrating fleet utilization. Reel capacity expansion to thirty thousand feet drives replacement demand as laterals extend.
- Offshore:Platform and subsea interventions require dual blowout preventer stacks under BSEE mandates, doubling mobilization cost. North Sea operators adopt hybrid carbon-steel strings to address crane weight limitations.
- Land-Based:Conventional desert and arctic deployments use standard fleet configurations.
- Integrated:Multi-service packages combine coiled tubing with pumping and wireline units.
Onshore deployment leads by unit count, while offshore commands the steepest pricing premium.
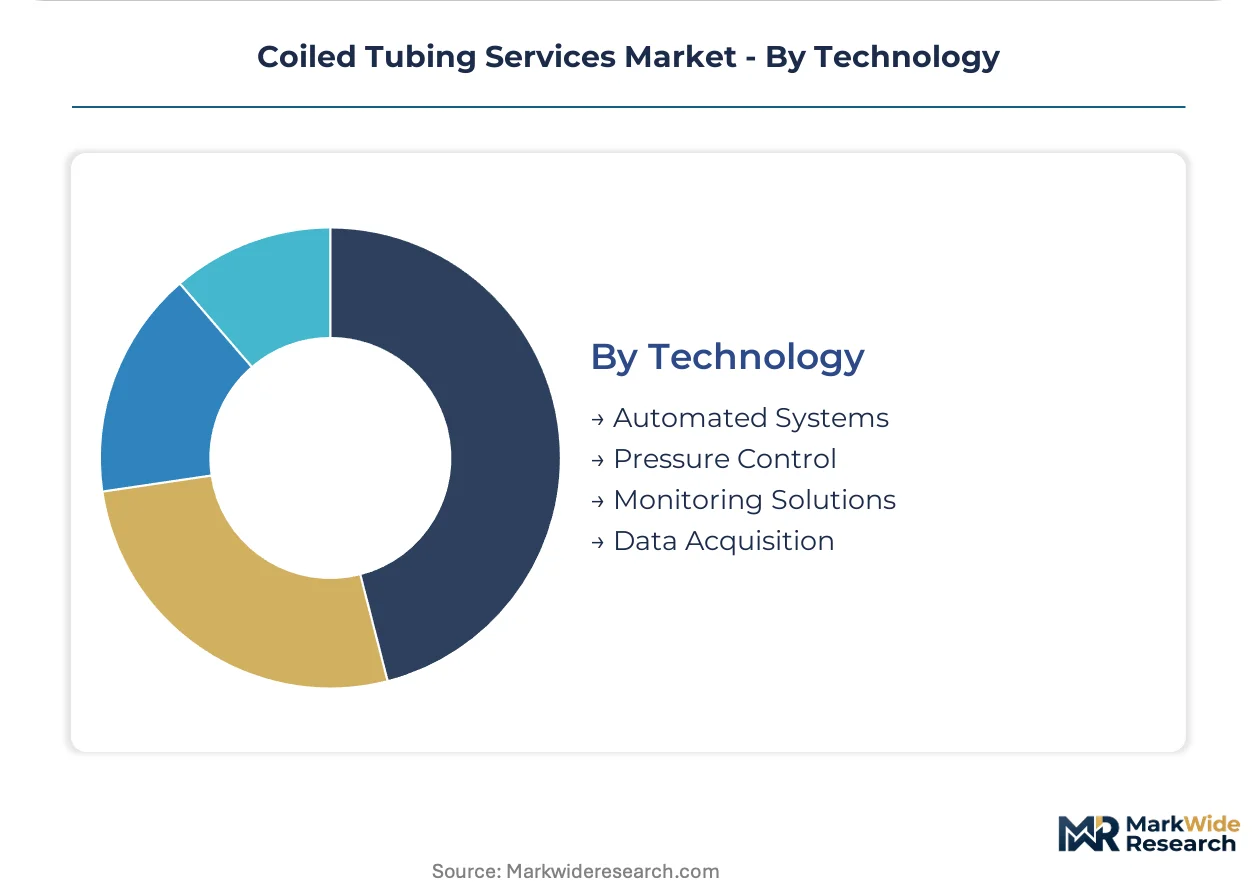
Technology:
Customer type bifurcates between supermajors deploying proprietary monitoring systems and regional operators purchasing standardized equipment.
- Automated Systems:Remote-actuated stripper assemblies integrate with real-time pressure telemetry to reduce personnel exposure in high-H2S environments. Adoption concentrates among operators with proprietary well databases that enable predictive fatigue retirement algorithms.
- Monitoring Solutions:Embedded sensor arrays track pipe stress cycles during intervention, enabling continuous operations and reducing non-productive time.
- Pressure Control:Advanced wellhead sealing systems maintain integrity across extended-reach laterals.
- Data Acquisition:Digital thread technologies compress feedback loops between downhole measurement and surface control.
Automated systems claim the fastest adoption trajectory, while pressure control equipment retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor service providers with captive manufacturing in Germany and Japan, while import-dependent basins in Argentina and Australia create fleet deployment openings for mobile operators. Trade flows concentrate high-strength alloy supply among integrated steel mills, constraining regional fleet expansion timelines.
United States
Permian Basin operators deploy coiled tubing units for laterals exceeding twelve thousand feet, requiring enhanced fatigue resistance. EPA methane emissions rules accelerate contractor qualification for zero-vent live-well interventions. Midland-Odessa concentrates fleet utilization as reel capacity expansion drives replacement demand across Texas and New Mexico operations.
Canada
Alberta's Montney formation gas producers prioritize closed-loop circulation systems to eliminate flaring during completion work. Health Canada environmental guidelines align with provincial methane reduction targets for unconventional development. Calgary anchors service provider headquarters, while Grande Prairie functions as the primary mobilization hub for northern Alberta and British Columbia shale plays.
Germany
Integrated steel mills supply high-strength chromium-molybdenum billet to global service companies, creating supply concentration for fatigue-rated alloy grades. REACH substance restrictions on chromium VI compounds accelerate plasma coating adoption for corrosion protection. Düsseldorf-Ruhr industrial corridor hosts metallurgical research facilities certifying alternative surface treatments for North Sea platform applications.
Argentina
Neuquén Basin Vaca Muerta shale expansion lacks indigenous coiled tubing capacity, creating deployment openings for modular fleet operators. National hydrocarbon regulator frameworks govern contractor qualification for unconventional well interventions. Neuquén city functions as the operational coordination center, with equipment mobilized through Bahía Blanca port logistics.
United Arab Emirates
Offshore field redevelopment in the Arabian Gulf generates demand for dual blowout preventer configurations under marine safety mandates. ADNOC procurement standards favor contractors with real-time monitoring capabilities and DNV-certified equipment. Abu Dhabi concentrates regional headquarters, while Dubai Jebel Ali serves as the primary equipment staging and maintenance hub.
Coiled Tubing Services Market Vendor Landscape
Concentration sits with integrated service conglomerates controlling captive alloy sourcing and proprietary monitoring platforms. The vendor base stratifies into three tiers: asset-heavy operators with vertical fabrication networks, technology-focused specialists with continuous-monitoring systems, and regional mobilization providers serving single-well campaigns. Dominant competitive moves include strategic partnerships for modular fleet deployment and portfolio diversification into automated wellhead sealing systems.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify archetypes combining manufacturing control with technology platforms. Superior Energy Services, Inc. occupies a position among Gulf of Mexico-focused operators where mobilization logistics favor established fleet scale. Weatherford International plc and Schlumberger Limited represent the scale-driven end with global deployment capabilities spanning onshore and offshore applications.
| Leading Market Players |
|---|
| Weatherford International plc |
| Superior Energy Services, Inc. |
| Schlumberger Limited |
| Trican Well Service Ltd. |
| Calfrac Well Services Ltd. |
| Halliburton Company |
| Nabors Industries Ltd |
| National-Oilwell Varco Inc. |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Ninety-day billet lead times from German and Japanese integrated mills compress fleet expansion timelines for regional specialists while amplifying pricing power for asset-heavy operators with captive alloy sourcing. This supply concentration forces procurement decisions toward long-term offtake agreements that lock in material grades before API 5ST certification cycles complete, embedding inventory carrying costs into day-rate structures.
Pricing Analysis
The customization-premium spread separates fatigue-rated strings for extended-reach laterals from standard-grade inventory, with configured-to-order pricing commanding substantial premiums over catalog offerings. Project-based contracting dominates, where day rates bifurcate based on reel capacity tier and real-time monitoring integration. Price differentiation rests on certification grade and geographic delivery cost, with Permian Basin mobilization absorbing logistics premiums. Cost compression in standard-grade segments is intensifying because of fleet overcapacity in mature North American basins. Independent regional operators exhibit highest price sensitivity, while supermajor engineering teams prioritize performance guarantees over rate negotiation.
Supply Chain Analysis
Strait of Hormuz transit underwrites alloy flow security for Arabian Gulf offshore deployments, though alternative routing adds cost layers. High-strength chromium-molybdenum billet concentrates in Germany, Japan, and South Korea, drawing from integrated steel mills with metallurgical research capabilities. Raw material dependencies center on nickel, molybdenum, and specialized welding consumables. Single-source vulnerability persists in fatigue-testing equipment where DNV-certified apparatus suppliers number fewer than five globally. Distribution runs through port-centric staging hubs in Houston, Aberdeen, and Singapore that coordinate equipment mobilization to basin-specific demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-reach well architecture in unconventional basins is driving early-cycle expansion as lateral lengths push equipment capabilities beyond legacy fleet specifications. Live-well intervention adoption under EPA methane rules accelerates contractor qualification demand faster than indigenous capacity can respond.
For Market Incumbents: Secure backward integration into high-strength alloy supply through captive mill relationships or long-term billet offtake agreements to defend against allocation constraints. Expand reel capacity certification programs ahead of API 5ST timeline compression to capture replacement demand from Permian operators extending laterals beyond fifteen thousand feet.
For New Entrants and Emerging Players: Differentiate on modular fleet architecture that enables rapid deployment to supply-constrained basins like Argentina's Neuquén formation. Target Vaca Muerta development where indigenous coiled tubing capacity gaps create white-space openings for operators with local partnership structures and DNV-certified equipment packages.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement power concentrates among integrated service providers with manufacturing control and real-time data platforms. Acquisition candidates with proprietary fatigue-monitoring algorithms and established Gulf of Mexico offshore credentials offer defensive positioning against composite pipe substitution. Watch for inflection when BSEE mandates extend blowout preventer redundancy requirements to additional offshore jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Alloy Sourcing Agreement | Backward integration into German or Japanese mill capacity secures billet allocation ahead of regional competitors. |
| Real-Time Monitoring Platform Deployment | Embedded sensor arrays differentiate contractors in supermajor qualification rounds requiring predictive fatigue retirement. |
| Modular Fleet Expansion | Containerized equipment packages enable rapid mobilization to supply-constrained basins like Vaca Muerta. |
| Plasma Coating Certification | REACH-compliant surface treatment qualification opens North Sea platform work as hexavalent chromium exits supply chains. |
| Remote-Actuated Stripper Integration | Automated wellhead sealing reduces personnel exposure in high-H2S environments while enabling continuous operations. |
Methodological Framework
Initial hypotheses were tested against primary input from coiled tubing fleet managers, drilling engineering leads at unconventional operators, procurement directors at supermajor engineering teams, and aftermarket service heads, then refined through secondary validation. Primary intelligence combined structured interviews with channel checks across Permian and Montney basin operations. Secondary sources included API specification documentation, BSEE regulatory filings, EPA methane rule dockets, customs trade data for alloy billet flows, and SEC filings from integrated service providers. Bottom-up equipment deployment counts were triangulated against top-down basin-level spending estimates.
Variance-decomposition framing isolated volume drivers from price-mix effects across the projection horizon. The analytical framework modeled service type, deployment environment, technology tier, and end-user procurement structure as segmentation dimensions. CAGRs were derived from equipment replacement cycles tied to lateral length extension trends and regulatory compliance timelines. Forecast inputs incorporated reel capacity expansion trajectories and API 5ST certification pipeline visibility.
The analysis sits within stated boundaries; outcomes outside sustained unconventional drilling intensity or accelerated composite pipe substitution would require recalibration. Forecasts reflect assumptions regarding alloy supply continuity and regulatory enforcement consistency. Practitioners should keep alternative scenarios live as BSEE mandate expansion and REACH substance restriction timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Mud Balance Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Wellhead Equipment Market