
 Asia-Pacific AI in Oil and Gas Market | 2026-2036
Asia-Pacific AI in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AI in Oil and Gas Market Analytics
Direct sales channels between AI vendors and national oil companies is narrowing as consortium-based procurement gains ground across Southeast Asian basins. Siemens leverages its industrial automation heritage to anchor digital twin deployments in Australian offshore projects. C3.AI competes through enterprise-scale machine learning platforms tailored to reservoir simulation workflows. ENERZAi specializes in edge-computing inference for subsea pipeline monitoring, occupying a niche between hyperscaler clouds and legacy SCADA integrators.
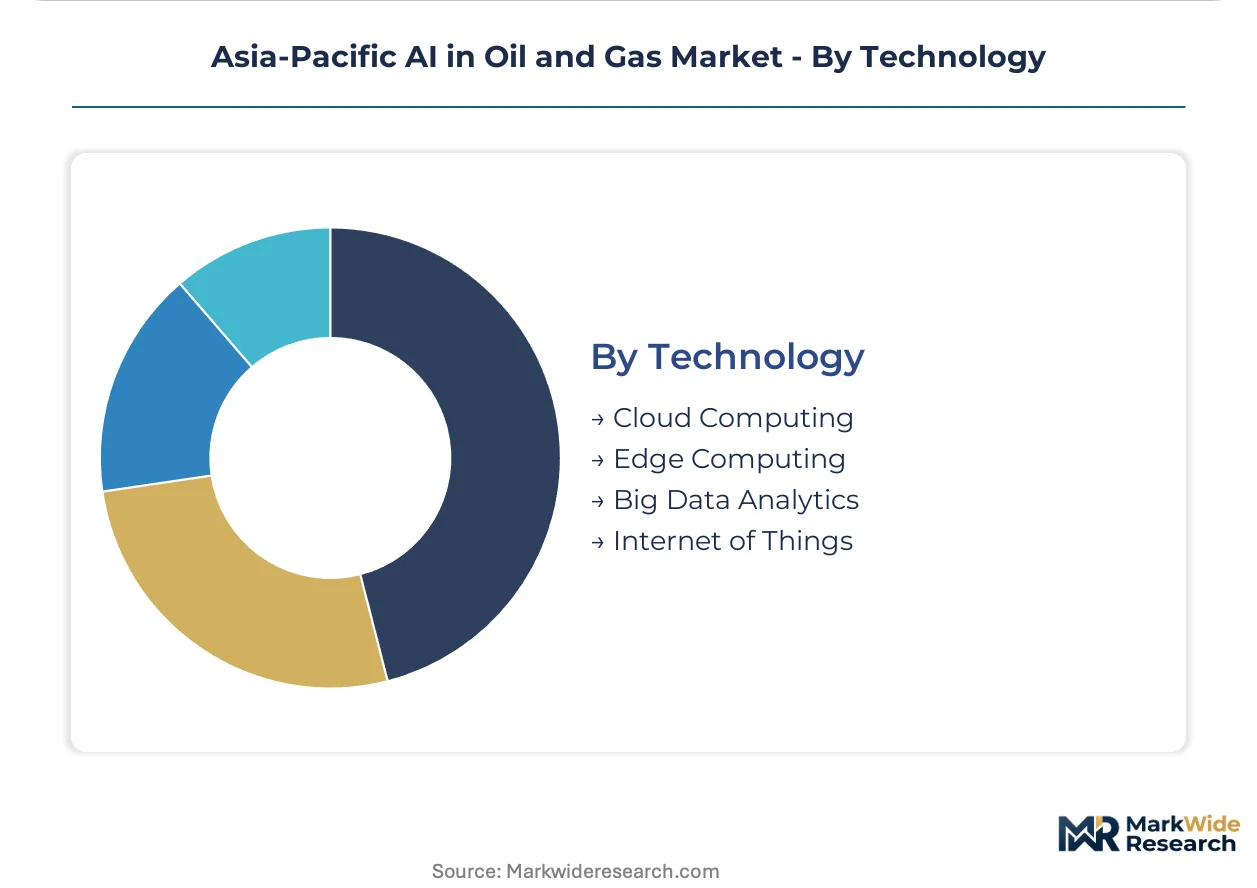
Asia-Pacific AI in Oil and Gas encompasses software systems that apply statistical learning algorithms, sensor fusion architectures, and real-time data pipelines to hydrocarbon exploration, extraction, and logistics operations. These platforms typically process seismic datasets exceeding petabyte scale, execute predictive models with sub-second latency requirements, and integrate with distributed control systems via OPC-UA or proprietary protocols to optimize recovery rates and minimize unplanned downtime. Machine Learning commands the largest revenue share among product types, as subsurface characterization and production forecasting algorithms require continuous retraining on proprietary field data. Edge Computing within the technology dimension represents the fastest-expanding segment, driven by latency constraints in remote wellpad environments where satellite bandwidth remains costly and intermittent.
MIIT cybersecurity certification requirements and China's GB standards for industrial data interfaces shape vendor qualification protocols across state-backed procurement cycles. Australia's Critical Infrastructure Protection Act and Japan's METI guidelines for operational technology security create parallel compliance layers for foreign platform providers seeking market access. Stakeholders must evaluate sovereign data residency mandates against the technical overhead of localized edge deployments before committing to multi-country rollout architectures.
Market Dynamics
China's MIIT data governance mandates and dual carbon goals are compressing deployment timelines for AI-driven emissions monitoring across state-owned energy groups. This regulatory pressure cascades through procurement cycles, forcing vendors to localize edge infrastructure and achieve sovereign data residency certification before contract award.
Growth Catalysts
- MIIT Cybersecurity Certification:Mandatory vendor qualification protocols for industrial AI platforms accelerate replacement of legacy SCADA systems in Chinese upstream operations.
- Subsea Pipeline Integrity:Edge-computing inference architectures address latency constraints in remote wellpad environments where satellite bandwidth remains intermittent and costly.
- Australian LNG Export Corridor:Integrated producers pilot computer vision systems for flare stack inspection, creating reference deployments across Southeast Asian basins.
Market Restraints
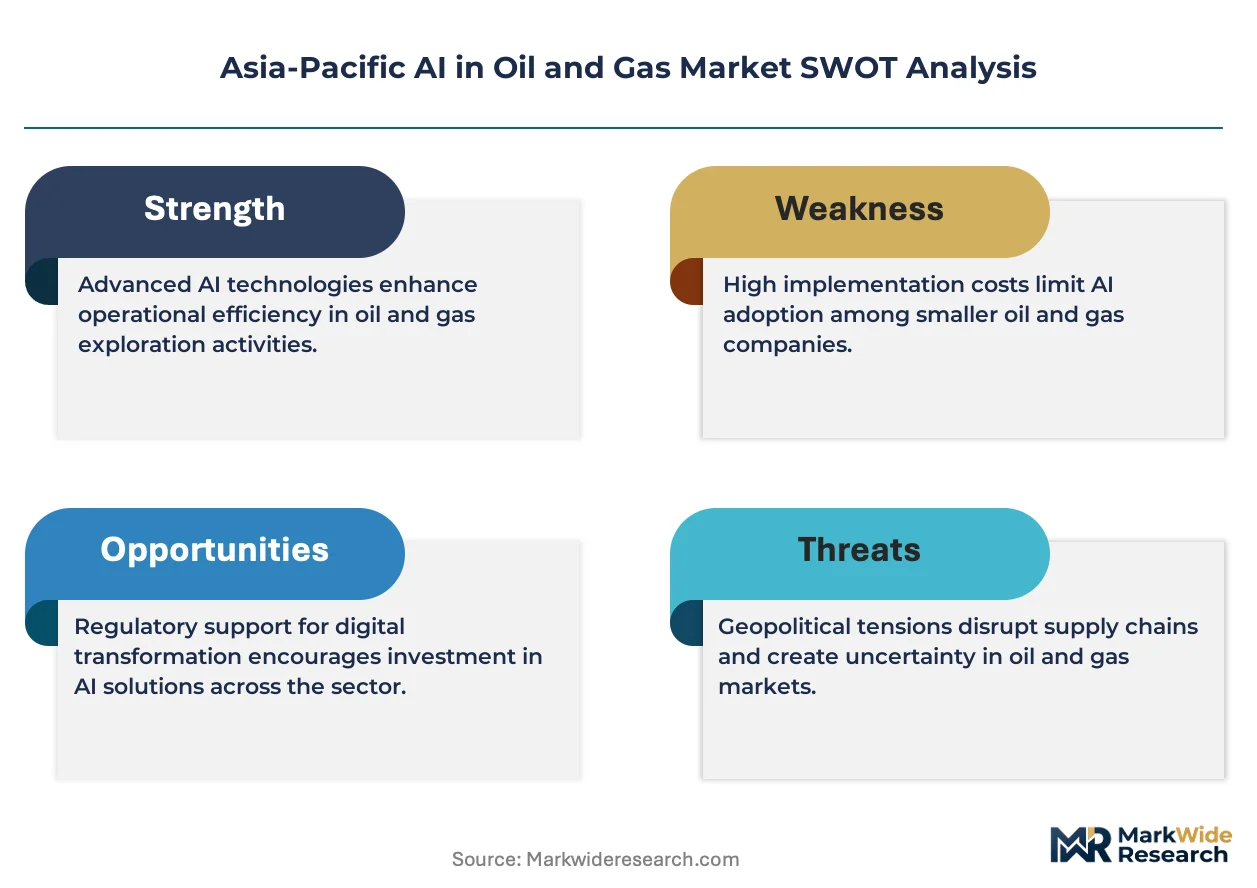
- Input Cost Volatility:Specialized GPU clusters for seismic processing face supply concentration risk from Taiwan-based foundry capacity allocation.
- Regulatory Friction:Australia's Critical Infrastructure Protection Act imposes parallel compliance layers that extend foreign platform provider qualification timelines.
- Technical Limitation:Petabyte-scale seismic dataset training requires proprietary field data that remains siloed within national oil company firewalls.
Strategic Opportunities
- Indonesian Deepwater Basins:Underpenetrated offshore fields present white space for predictive maintenance platforms targeting floating production facilities.
- Japan METI Operational Technology Guidelines:Security certification requirements create regulatory tailwind for vendors offering localized edge deployments with JIS-compliant data interfaces.
- Digital Twin Convergence:Integration of reservoir simulation workflows with real-time sensor fusion architectures enables closed-loop optimization of recovery rates.
Industry Challenges
- Geophysicist-Data Scientist Gap:Subsurface characterization algorithms require domain expertise that remains scarce across Asia-Pacific energy labor markets.
- Legacy DCS Integration Complexity:OPC-UA protocol translation and proprietary control system interfacing consume 40-60% of deployment engineering hours.
- IP Licensing Fragmentation:Machine learning model ownership disputes between AI vendors and national oil companies delay production deployment sign-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AI in Oil and Gas Market |
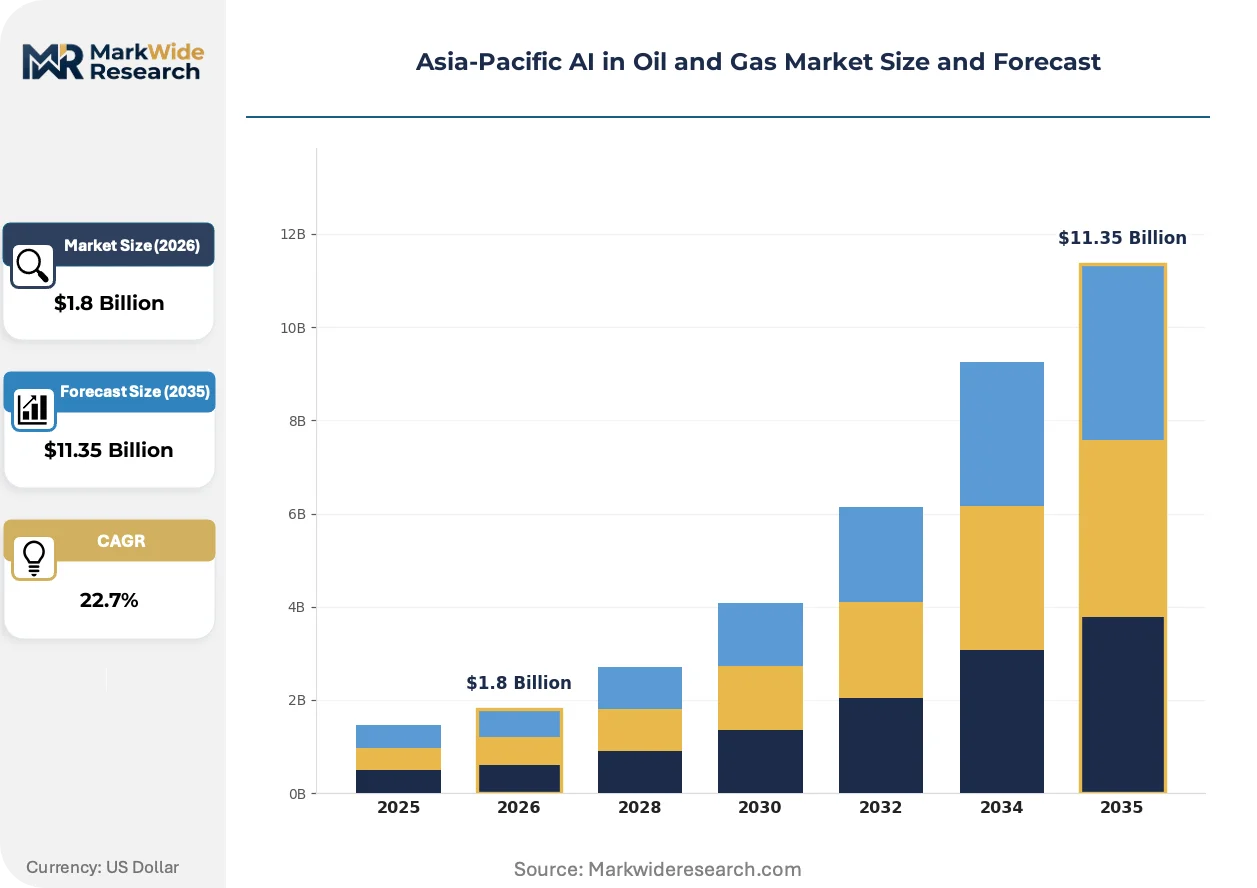
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Language Processing, Machine Learning, Predictive Analytics, Computer Vision Application: Exploration, Production Optimization, Equipment Monitoring, Supply Chain Management End User: Oil Producers, Service Companies, Regulatory Bodies, Energy Traders Technology: Cloud Computing, Edge Computing, Big Data Analytics, Internet of Things |
| Companies Covered | Siemens, Shell, Chevron, ExxonMobil, China Petrochemical Corporation, BP, Cisco Systems, C3.AI, ENERZAi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AI in Oil and Gas Market Evolving Landscape
Sensor fusion architectures are compressing the latency window between subsurface data acquisition and operational decision-making. This acceleration is reshaping competitive positioning around real-time inference capability rather than historical batch analytics.
Computer vision systems for flare stack and subsea infrastructure inspection are digitizing manual survey workflows across Australian and Southeast Asian offshore assets. Integrated LNG producers deploy these platforms at pilot scale with sub-second anomaly detection requirements. The technology is digitizing maintenance scheduling from calendar-based intervals to condition-driven triggers, compressing unplanned downtime exposure.
China's GB standards for industrial data interfaces and MIIT cybersecurity certification requirements are mandating localized edge deployment architectures. Foreign platform providers must establish sovereign data residency and achieve state-backed qualification before contract participation. Australian and Japanese national oil companies are observing these protocols as potential templates for their own Critical Infrastructure Protection Act and METI guideline implementations.
Consortium-based procurement between Southeast Asian national oil companies is displacing direct vendor relationships. Shared pilot programs for predictive maintenance platforms distribute capital risk and accelerate reference deployment accumulation. This model concentrates most visibly in Indonesia and Malaysia, where joint venture structures already govern production sharing agreements and extend naturally into digital transformation spend.
Asia-Pacific AI in Oil and Gas Market Segmentation
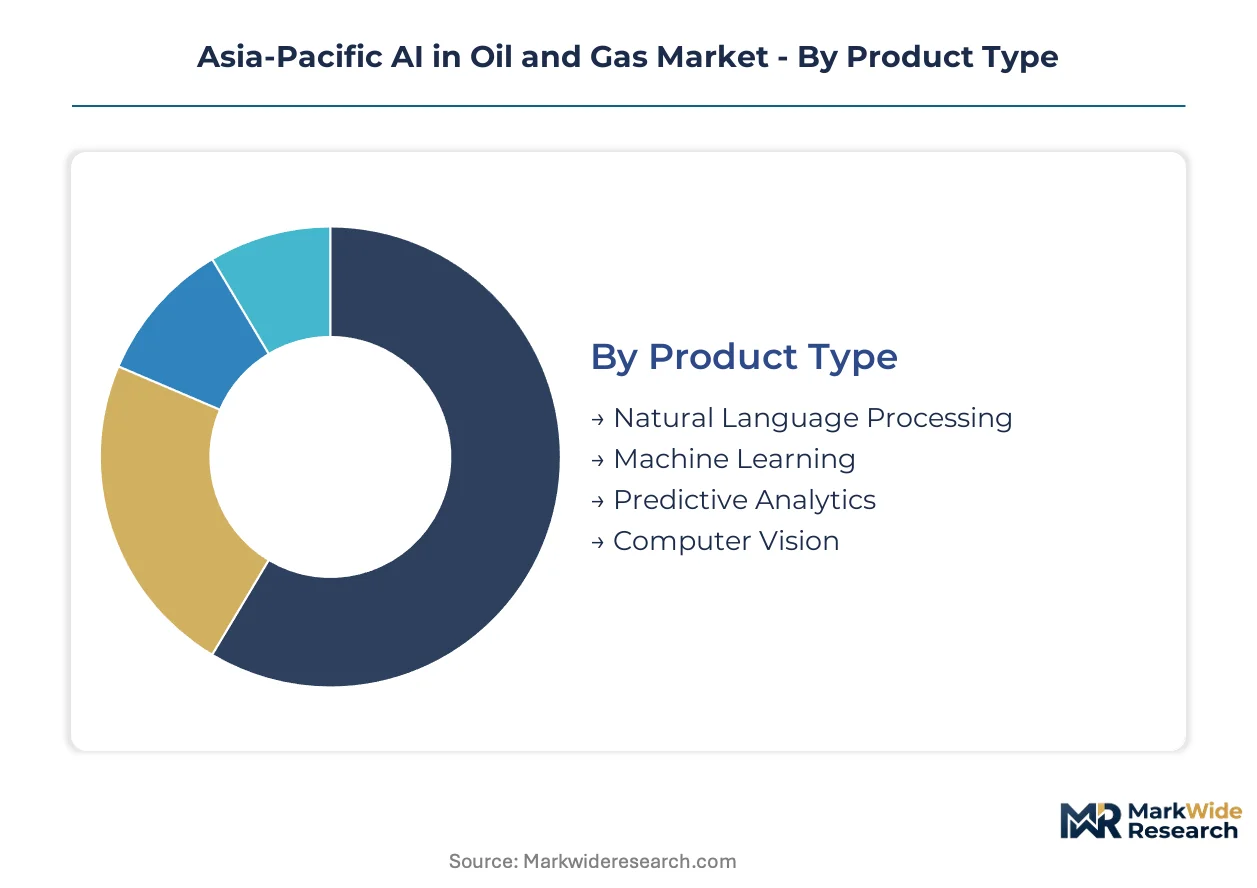
Segmentation reveals distinct deployment patterns across Asia-Pacific hydrocarbon operations. Product architecture choices determine integration complexity with legacy SCADA infrastructure. Application focus areas align with basin maturity and regulatory pressure intensity across Southeast Asian and Australian assets.
Product Type:
After-sales service intensity varies sharply across AI product categories, with continuous model retraining and edge infrastructure maintenance driving recurring revenue attachment.
- Machine Learning:Statistical learning algorithms process proprietary seismic datasets and production forecasting models. Chinese state-owned energy groups deploy these platforms under MIIT cybersecurity certification mandates for reservoir simulation workflows. Subsurface characterization algorithms require continuous retraining on field-specific data, creating sustained vendor engagement.
- Computer Vision:Image recognition systems execute flare stack inspection and subsea infrastructure monitoring with sub-second anomaly detection latency. Australian LNG integrated producers pilot these deployments across offshore assets, digitizing manual survey workflows into condition-driven maintenance triggers.
- Predictive Analytics:Time-series forecasting platforms target equipment failure prediction in remote wellpad environments where satellite bandwidth constraints favor localized inference.
- Natural Language Processing:Document intelligence systems automate regulatory filing and contract analysis for procurement cycles across consortium-based national oil company structures.
By volume, Machine Learning leads. By growth pace, Computer Vision is ahead.
Application:
Cost tier differentiation separates exploration-focused deployments from production optimization spend, with the latter commanding premium pricing due to operational criticality.
- Production Optimization:Real-time sensor fusion architectures integrate with distributed control systems via OPC-UA protocols to maximize recovery rates. Australian offshore projects anchor digital twin deployments that close the loop between reservoir simulation and surface facility control.
- Equipment Monitoring:Predictive maintenance platforms target floating production facilities in Indonesian deepwater basins, addressing unplanned downtime exposure through vibration analysis and thermal anomaly detection.
- Exploration:Seismic processing workflows apply machine learning to petabyte-scale datasets, though proprietary field data silos within national oil company firewalls constrain algorithm training.
- Supply Chain Management:Demand forecasting and logistics optimization systems serve energy traders and procurement consortia across Southeast Asian joint venture structures.
Production Optimization captures the largest deployment value. Equipment Monitoring shows the steepest expansion trajectory as offshore asset integrity demands intensify.
End User:
Customer type determines procurement channel structure, with direct vendor relationships giving way to consortium-based models among certain buyer categories.
- Oil Producers:National oil companies and integrated majors drive platform specification, with China's dual carbon goals compelling AI-driven emissions monitoring adoption across upstream operations.
- Service Companies:Drilling contractors and subsea specialists deploy edge-computing inference for pipeline integrity monitoring, occupying technical niches between hyperscaler clouds and legacy integrators.
- Regulatory Bodies:Environmental and safety agencies mandate data transparency standards that shape vendor qualification protocols under Australia's Critical Infrastructure Protection Act and Japan's METI guidelines.
- Energy Traders:Commodity trading desks apply predictive analytics to demand forecasting and arbitrage optimization across Asia-Pacific LNG export corridors.
Oil Producers dominate contract value. Service Companies are gaining share fastest as specialized edge deployment expertise becomes scarce.
Technology:
Supply concentration in GPU cluster manufacturing from Taiwan-based foundries creates input cost volatility for certain technology categories.
- Edge Computing:Localized inference architectures address latency constraints in remote wellpad environments where satellite bandwidth remains intermittent and costly. MIIT data governance mandates and China's GB standards for industrial data interfaces compel sovereign data residency certification.
- Cloud Computing:Hyperscaler platforms host seismic processing and enterprise-scale machine learning training, though foreign providers face localization requirements under state-backed procurement cycles.
- Big Data Analytics:Pipeline architectures process real-time sensor streams from subsea and surface facilities, integrating with proprietary control system protocols.
- Internet of Things:Sensor fusion deployments compress the latency window between subsurface data acquisition and operational decision-making across Southeast Asian basins.
Cloud Computing leads by installed base. Edge Computing is climbing the fastest as regulatory data residency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australian LNG export corridors while Chinese state-backed procurement compresses vendor margins through localization mandates. This asymmetry reshapes deployment economics across Southeast Asian joint ventures and offshore basins.
China
State-owned energy groups deploy AI-driven emissions monitoring under MIIT cybersecurity certification and dual carbon goals. GB standards for industrial data interfaces mandate sovereign data residency for foreign platform providers. Sinopec anchors digital twin pilots in the Bohai Bay basin, where reservoir simulation workflows integrate with localized edge infrastructure.
Australia
Integrated LNG producers pilot computer vision systems for flare stack inspection across the Northwest Shelf and Queensland Curtis Island. The Critical Infrastructure Protection Act imposes parallel compliance layers that extend foreign vendor qualification timelines. Perth-based engineering consortia distribute capital risk through shared predictive maintenance programs targeting floating production facilities.
Japan
Upstream operators align edge deployment architectures with METI operational technology security guidelines and JIS-compliant data interfaces. The country's national oil company observes Chinese localization protocols as potential templates for domestic procurement cycles. Chubu and Kansai industrial corridors host pilot sensor fusion deployments compressing latency between subsurface acquisition and surface facility control.
Indonesia
Deepwater basins including the Makassar Strait and Natuna Sea present white space for predictive maintenance platforms targeting floating production facilities. Consortium-based procurement between Pertamina and international joint venture partners distributes capital risk across digital transformation spend. Jakarta-based engineering clusters coordinate reference deployments that cascade through Malaysian and Vietnamese offshore assets.
South Korea
Shipyards and subsea specialists supply edge-computing inference hardware for pipeline integrity monitoring across Asia-Pacific offshore corridors. The country's industrial technology regulator shapes vendor qualification protocols through operational technology security guidelines. Busan-Ulsan manufacturing clusters produce GPU-intensive seismic processing equipment facing Taiwan foundry supply concentration risk.
Asia-Pacific AI in Oil and Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying inference hardware and protocol translation layers. The vendor base organizes around three strategic archetypes: industrial automation heritage players anchoring digital twin deployments, enterprise-scale machine learning platforms, and edge-computing inference specialists occupying niches between hyperscaler clouds and legacy SCADA integrators. Competitive moves concentrate on consortium-based procurement partnerships and sovereign data residency certification achievement.
Within the industrial automation tier, Siemens leverages its heritage to anchor offshore deployments. C3.AI and ENERZAi occupy distinct positions—one through enterprise-scale platforms, the other through edge-computing specialization for subsea monitoring. These three exemplify how vendor positioning stratifies around latency requirements, data governance mandates, and integration complexity with legacy control systems.
| Leading Market Players |
|---|
| Siemens |
| Shell |
| Chevron |
| ExxonMobil |
| China Petrochemical Corporation |
| BP |
| Cisco Systems |
| C3.AI |
| ENERZAi |
| Others |
Value Network & Pricing Analysis
Overcapacity in Taiwan-based GPU foundry allocation is compressing hardware procurement timelines for seismic processing clusters while simultaneously elevating price premiums for sovereign-certified edge deployments in Chinese upstream operations. This utilization asymmetry bifurcates vendor economics: hyperscaler cloud providers absorb volume discounts at the infrastructure layer while national oil companies extract localization concessions through MIIT-mandated data residency requirements.
Pricing Analysis
The customization-premium spread between standard SaaS-tiered subscriptions and configured-to-order edge deployments spans three distinct pricing architectures. Subscription models dominate exploratory seismic processing, while project-based contracting governs digital twin integrations with OPC-UA protocol translation requirements. Price differentiation hinges on MIIT cybersecurity certification tier and after-sales service bundling for continuous model retraining. Cost compression in standard cloud tiers is intensifying because hyperscaler competition for enterprise accounts, while premium pricing for localized edge infrastructure remains resilient due to regulatory compliance scarcity. National oil companies exhibit lowest price sensitivity given sovereign procurement mandates; independent service companies face acute margin pressure from satellite bandwidth cost volatility.
Supply Chain Analysis
Upstream feedstock dependencies for AI inference hardware concentrate in Taiwan, South Korea, and the United States for advanced GPU cluster manufacturing. Specialized edge-computing chipsets draw from Japanese foundry capacity for JIS-compliant industrial interfaces, while subsea sensor fusion components rest on German precision manufacturing for pressure-rated enclosures. Single-source vulnerability pervades Taiwan-based foundry allocation for seismic processing accelerators, with regulatory restrictions on semiconductor export controls amplifying supply uncertainty. Distribution runs through systems integrators with industrial automation heritage, who anchor consortium-based procurement cycles across Southeast Asian national oil company joint ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as consortium-based procurement displaces direct vendor relationships, creating specialized niches for edge-computing inference specialists between hyperscaler clouds and legacy SCADA integrators. Regulatory data residency mandates across Chinese, Australian, and Japanese procurement cycles multiply entry points for certified local deployment partners.
For Market Incumbents: Pre-empt margin erosion in enterprise-scale machine learning platforms by anchoring digital twin deployments with sovereign data residency certification ahead of Australian Critical Infrastructure Protection Act implementations. Consolidate channel control through consortium partnerships with Indonesian and Malaysian national oil companies, locking out emerging edge-specialist competitors from reference deployment accumulation in deepwater basins. Prioritize backward integration into GPU cluster supply through long-term offtake agreements with Taiwan-based foundries, mitigating input cost volatility that threatens project-based pricing power. For New Entrants and Emerging Players: Establish a beachhead in Indonesian deepwater floating production facility monitoring, where predictive maintenance platform penetration remains underdeveloped and consortium procurement distributes capital risk across joint venture partners. Target Japanese METI operational technology guideline compliance as a differentiated entry credential, leveraging JIS-standard data interfaces to bypass hyperscaler cloud competition. Pursue service company channel partnerships rather than direct national oil company sales, occupying technical niches in subsea pipeline integrity where specialized edge inference commands premium pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-hosted seismic processing as hyperscaler competition commoditizes training infrastructure, while edge deployment specialization maintains upward intensity due to sovereign certification requirements. Long-term viability favors acquisition targets with MIIT cybersecurity certification and established consortium relationships in Southeast Asian basins, rather than pure-play algorithm vendors lacking operational technology integration heritage. Monitor Taiwan foundry utilization rates as the critical inflection signal for hardware cost compression timelines and corresponding margin pressure on infrastructure-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Partnership Formation | Pertamina and Malaysian joint venture structures distribute capital risk across shared predictive maintenance pilots. |
| Sovereign Data Residency Certification | MIIT compliance unlocks Chinese state-backed procurement cycles for foreign platform providers. |
| Edge Computing Hardware Backward Integration | Captive supply of GPU clusters mitigates Taiwan foundry allocation volatility for seismic processing. |
| Digital Twin Platform Integration | Siemens anchors Australian offshore deployments through OPC-UA protocol translation with reservoir simulation workflows. |
| Computer Vision Product Launch | Australian LNG producers pilot flare stack inspection systems with sub-second anomaly detection requirements. |
Research Methodology
Desk research of MIIT cybersecurity certification protocols, Australian Critical Infrastructure Protection Act implementation guidelines, and Japanese METI operational technology security standards preceded structured interviews with upstream digital transformation officers, subsea engineering directors, and industrial automation procurement leads. Secondary validation drew from customs records of GPU cluster imports, national oil company annual procurement disclosures, and hyperscaler capex allocation filings for Asia-Pacific energy verticals. Bottom-up deployment counts across Indonesian, Malaysian, and Australian offshore assets were triangulated against top-down market sizing from energy sector IT spending surveys.
Assumptions regarding MIIT data governance mandate enforcement timelines, Taiwan foundry capacity allocation stability, and satellite bandwidth cost trajectories were held fixed across base-case scenarios while edge computing adoption elasticity and consortium procurement diffusion rates were varied in sensitivity testing. Segmentation modeling incorporated product architecture, application criticality, end-user procurement channel structure, and technology deployment topology. CAGRs were derived from deployment velocity analysis across reference pilot programs and subsequent production rollout scaling patterns, with input from subsea infrastructure integrity spending forecasts and LNG export corridor automation investment cycles.
Stress conditions across regulatory certification timeline delays, GPU supply chain disruption severity, and national oil company firewall data access restrictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledgment that sovereign data residency mandate expansion or foundry geopolitical restrictions could materially revise trajectory. Cross-checking against IEA digital energy investment benchmarks and Asia-Pacific EPC contractor automation order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Wellhead System Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Oil Hose Market