
 Dry Natural Gas Market | 2026-2036
Dry Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Natural Gas Market Foresight
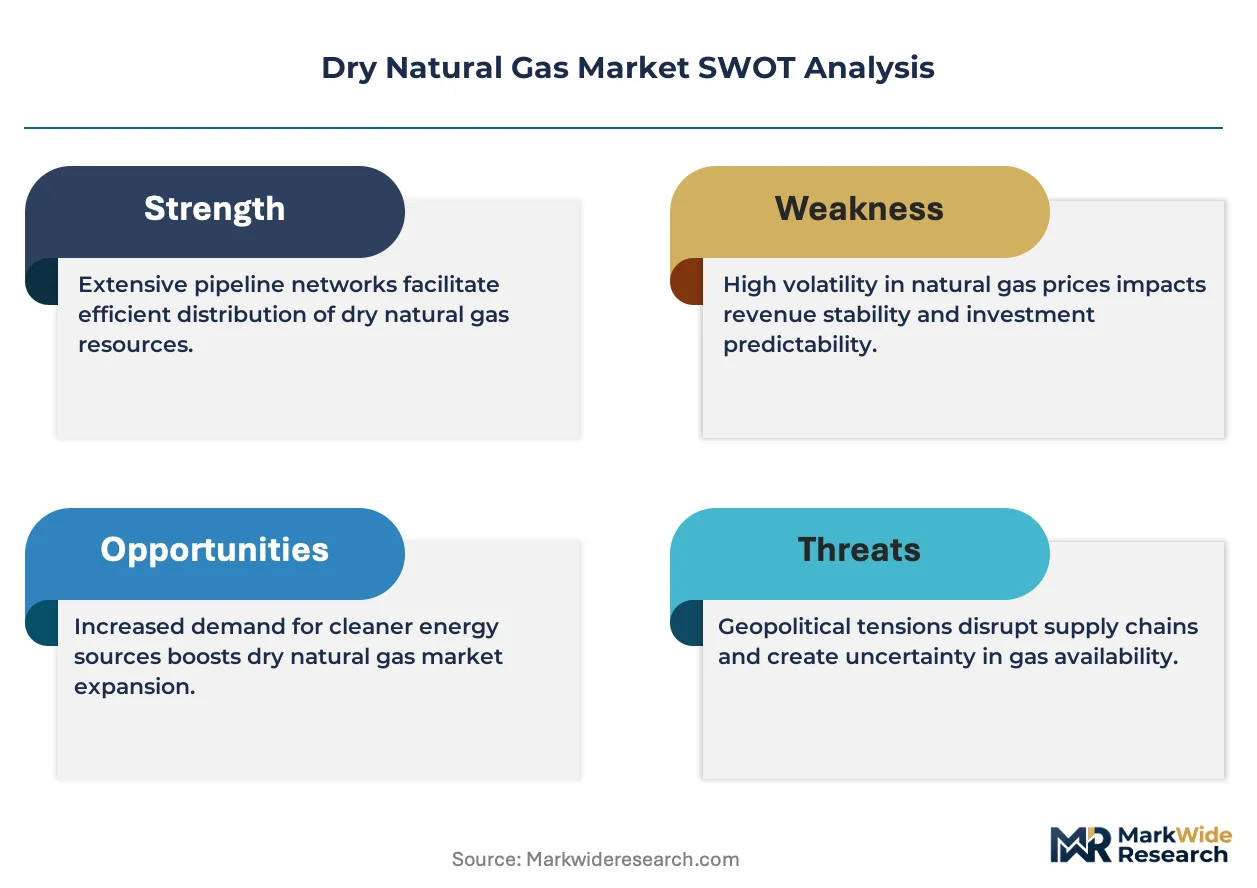
Asset-light leasing structures for pipeline and storage infrastructure are reshaping competitive entry in dry natural gas. Coterra Energy leverages vertical integration across the Permian and Marcellus to control wellhead-to-hub economics. EQT Corporation anchors the Appalachian basin with scaled shale production and midstream access. ExxonMobil extends its advantage through integrated LNG export positioning.
Dry natural gas is methane-dominant hydrocarbon processed to remove water vapor, heavier hydrocarbons, and non-combustible impurities, yielding a product with heating value typically above 1,000 Btu per standard cubic foot for pipeline delivery. Its primary purpose is combustion for heat and power generation, or conversion to hydrogen and petrochemical feedstocks. Shale gas dominates volume supply due to hydraulic fracturing economics, while LNG terminals capture expanding margin pools as interbasin arbitrage grows. Power generation remains the largest end user segment, though chemical feedstock applications are gaining share as cracker operators seek lower-carbon inputs.
The US EPA enforces methane performance standards under the Clean Air Act that raise compliance costs for upstream operators. China's MEE implements dual carbon targets that redirect industrial coal boilers toward gas alternatives. The EU F-Gas Regulation and methane strategy impose import standards affecting LNG cargo acceptance. Stakeholders must monitor regulatory divergence between Atlantic and Pacific basin standards when committing to long-term supply contracts.
Market Dynamics
The US EPA methane performance standards under the Clean Air Act are tightening extraction economics while China's industrial coal-to-gas conversion accelerates offtake concentration. These dual pressures are compressing wellhead margins in legacy basins while rewarding integrated operators with LNG export access.
Growth Catalysts
- Power generation baseload expansion:Utilities in the United States and Germany are contracting long-term pipeline supply to displace coal-fired capacity under carbon reduction mandates.
- China's MEE dual carbon targets:Provincial industrial boilers in Shandong and Jiangsu provinces face mandatory fuel switching deadlines that redirect demand toward pipeline gas and LNG.
- Hydrogen cracking feedstock pivot:Petrochemical operators in the Netherlands and Singapore are retrofitting steam crackers to accept methane as lower-carbon ethylene precursor.
Market Restraints
- Permian-Mountain West supply concentration:Pipeline takeaway constraints from the Delaware and Midland sub-basins create price volatility at Waha hub during maintenance cycles.
- EU F-Gas Regulation import standards:Methane intensity certification requirements for LNG cargo acceptance are raising compliance costs for non-integrated exporters.
- Renewable power substitution:Utility-scale solar and battery storage in Texas and California are capturing peak demand hours that previously supported gas-fired capacity payments.
Strategic Opportunities
- Vietnam industrial zone gasification:The country's Ministry of Industry and Trade is licensing combined-cycle power projects that require long-term LNG offtake contracts.
- Carbon capture and storage integration:Blue hydrogen production facilities in Norway and the United Arab Emirates are contracting certified low-methane supply for export to German chemical buyers.
- Small-scale LNG distribution:Bunkering infrastructure at the Port of Rotterdam and Singapore's Jurong Island is creating new demand channels for containerized cargo.
Industry Challenges
- Reservoir engineering talent scarcity:Shale operators in the Appalachian basin report difficulty recruiting geoscientists with hydraulic fracturing optimization expertise.
- Pipeline integrity capex cycles:PHMSA safety mandates are forcing operators to accelerate replacement of vintage gathering lines in the Marcellus and Utica formations.
- LNG offtake contract renegotiation:Destination-clause disputes between Japanese utilities and Qatari suppliers are creating arbitration backlogs that delay final investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Natural Gas Market |
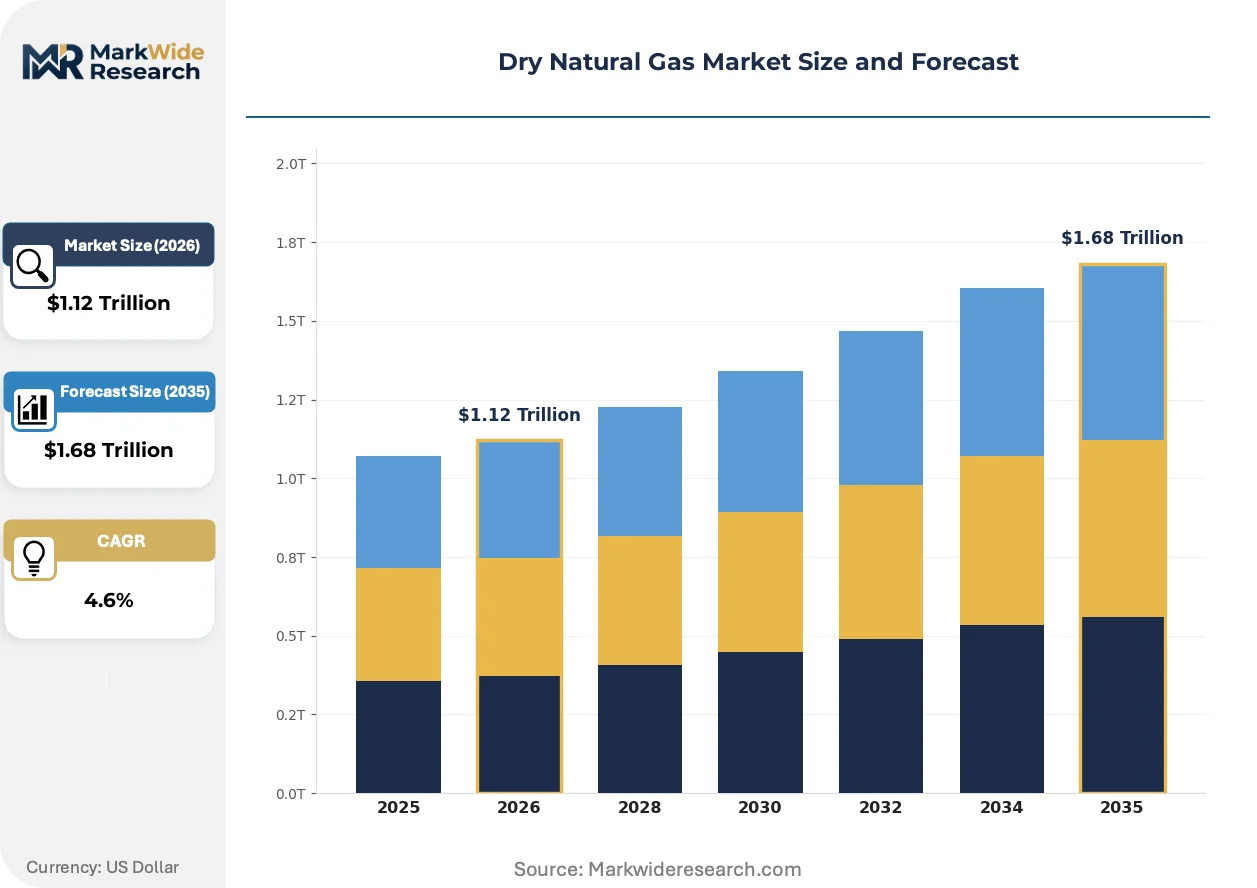
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.68 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
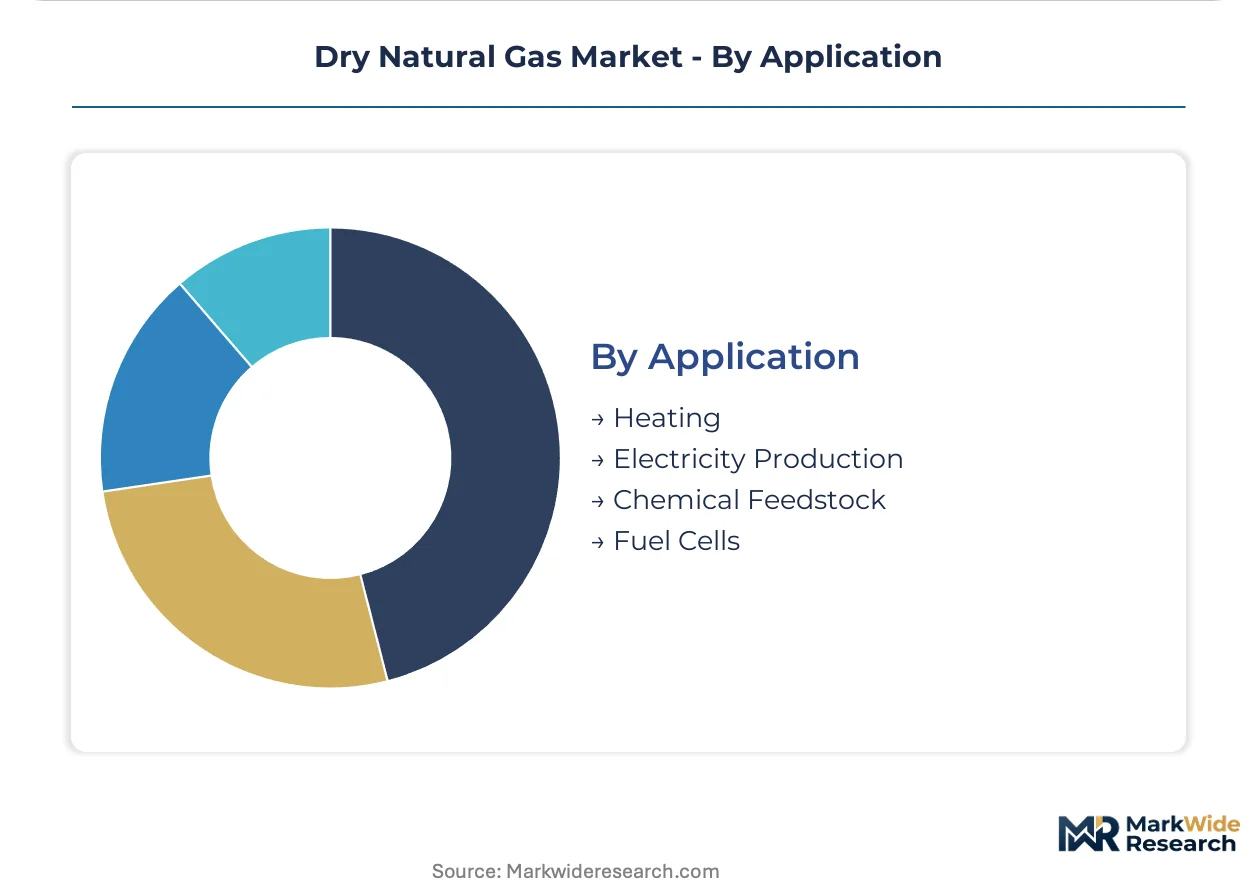
| Segmentation | Type: Shale Gas, Conventional Gas, Coalbed Methane, Biogas End User: Power Generation, Residential, Industrial, Transportation Distribution Channel: Pipelines, LNG Terminals, Trucking, Rail Transport Application: Heating, Electricity Production, Chemical Feedstock, Fuel Cells |
| Companies Covered | Coterra Energy, EQT Corporation, ExxonMobil, Chevron, Shell, Southwestern Energy, China National Petroleum Corporation, ConocoPhillips, Chesapeake Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Natural Gas Market Shifts & Advancements
Digital twin deployment and automated methane detection are compressing operational response times while regulatory frameworks fragment across Atlantic and Pacific basin standards. These forces are favoring capital-rich integrated operators over pure-play upstream independents.
Continuous methane monitoring via satellite and aerial LiDAR is collapsing the detection-to-repair cycle from quarterly surveys to real-time alerts. Supermajors with Permian and DJ basin positions are deploying this infrastructure to preempt EPA enforcement actions. The technology is collapsing the cost advantage previously held by smaller operators with manual inspection regimes.
The EU F-Gas Regulation and methane strategy are imposing import certification standards that require cargo-specific methane intensity documentation. LNG terminals in Belgium and Spain are rejecting cargoes that exceed 0.2% lifecycle leakage thresholds. European chemical buyers are now contracting only with suppliers who can demonstrate certified low-leakage production.
Industrial procurement in China is consolidating around state-backed energy trading houses that negotiate multi-year supply agreements with Qatar and Australia. Provincial distributors in Guangdong and Zhejiang are losing direct import licenses as the National Energy Administration centralizes purchasing authority. This consolidation is compressing margin pools for independent traders who previously captured arbitrage between spot and term pricing.
Dry Natural Gas Market Segmentation
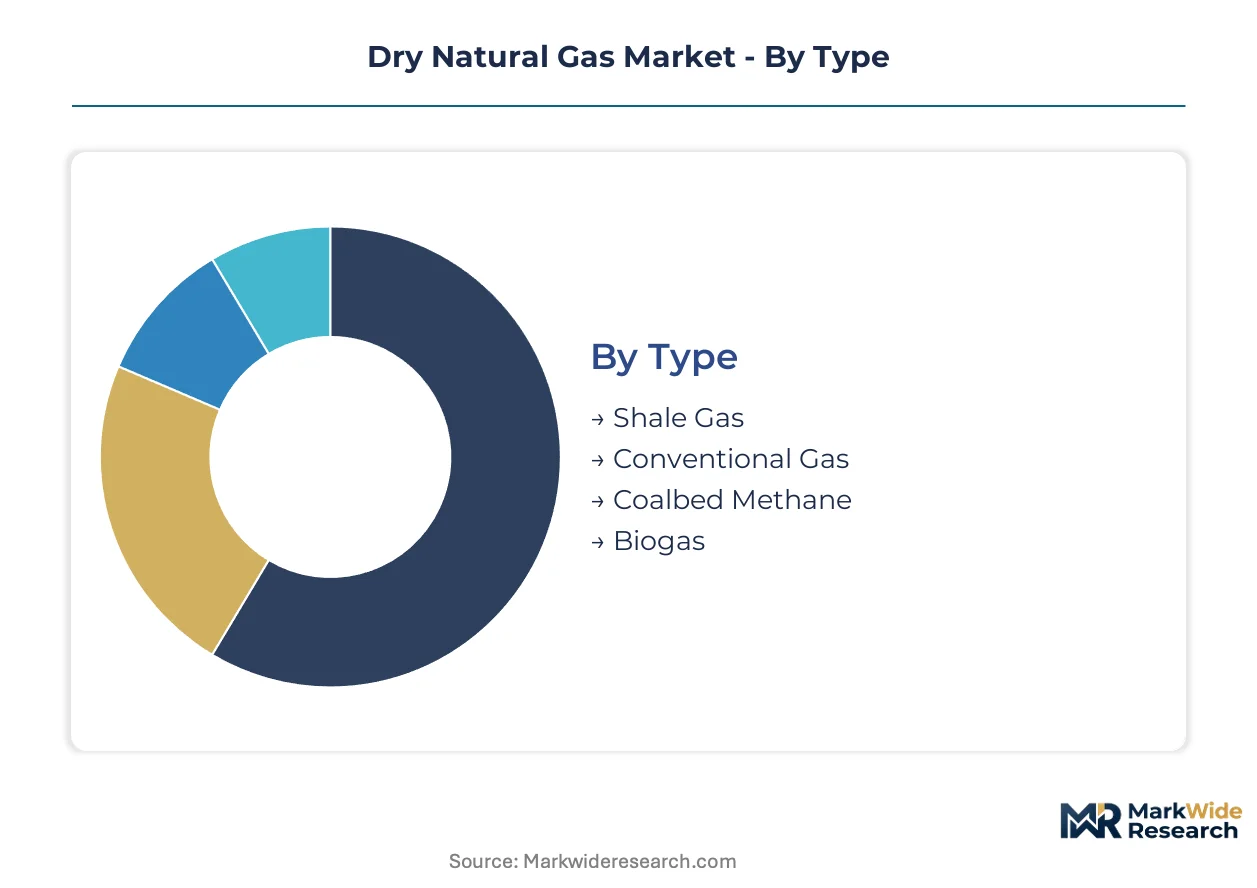
Dry natural gas market segmentation reveals how supply source, end-use intensity, and delivery infrastructure create divergent margin structures. Understanding these divisions exposes where capital deployment captures the highest risk-adjusted returns.
Type:
Cost tier determines extraction economics and regulatory exposure across production categories.
- Shale Gas:Hydraulically fractured formations in the Permian and Marcellus basins yield high initial decline rates with low breakeven costs. US EPA methane performance standards are compressing margins for operators lacking continuous monitoring infrastructure.
- Conventional Gas:Reservoirs with natural pressure drive require minimal artificial lift and deliver stable decline curves. Mature fields in the Gulf of Mexico and North Sea face accelerating decommissioning liabilities that redirect investment toward shale alternatives.
- Coalbed Methane:Adsorbed methane in coal seams releases through pressure reduction and dewatering. Australia's Bowen Basin and US Powder River Basin operations struggle with water disposal economics.
- Biogas:Anaerobic digestion of organic waste produces methane with carbon-negative credentials under EU certification schemes. Agricultural clusters in Denmark and California are scaling capacity to capture landfill diversion mandates.
Shale gas commands the established base. The steepest expansion runs through biogas.
End User:
Application intensity varies dramatically across customer categories, dictating contract duration and price volatility exposure.
- Power Generation:Combined-cycle turbines consume pipeline gas under baseload and peaking duty cycles. German utilities are contracting long-term supply to displace coal capacity under national carbon reduction timelines.
- Residential:Seasonal heating demand concentrates in northeastern US states and European markets with limited district heating penetration. China's MEE dual carbon targets are accelerating urban gasification in Shandong and Jiangsu provinces.
- Industrial:Process heat and feedstock applications in petrochemical crackers and ammonia synthesis require high-volume, interruptible contracts. Rotterdam and Singapore steam cracker operators are retrofitting for methane feedstock acceptance.
- Transportation:Compressed natural gas and LNG fueling for heavy trucking and marine bunkering creates distributed demand nodes. The Port of Rotterdam and Singapore's Jurong Island are licensing dedicated bunkering infrastructure.
Power generation anchors contract volumes. Industrial offtake is climbing the fastest as chemical feedstock pivots accelerate.
Distribution Channel:
Supply concentration dictates infrastructure access and margin capture across delivery modes.
- Pipelines:High-pressure transmission systems move dry gas from producing basins to demand centers with minimal handling losses. Permian-Mountain West takeaway constraints at the Waha hub create price volatility during maintenance cycles.
- LNG Terminals:Liquefaction facilities capture interbasin arbitrage by converting pipeline gas to liquid for marine transport. Qatar and Australian export terminals are consolidating offtake under Chinese state trading house procurement.
- Trucking:Compressed natural gas tube trailers and small-scale LNG tankers serve off-grid industrial and transportation demand. Vietnam's industrial zones are licensing distributed LNG receiving infrastructure.
- Rail Transport:Cryogenic tank cars extend pipeline reach to stranded demand in regions lacking transmission infrastructure. North Dakota Bakken production relies on rail to reach Midwest markets.
Pipelines retain the volume base. LNG terminals are gaining share fastest as Pacific basin demand concentrates.
Application:
Functional use case determines heating value specifications and processing requirements.
- Heating:Space conditioning and water heating applications prioritize consistent Btu delivery and odorant addition for safety. Northeastern US residential markets maintain seasonal storage injections to manage winter demand peaks.
- Electricity Production:Gas turbine combustion requires moisture removal and contaminant control to prevent blade fouling. Texas and California utility-scale solar and battery storage are displacing gas-fired capacity payments during peak hours.
- Chemical Feedstock:Steam cracker and ammonia synthesis operations demand high-purity methane with specified inert content. Blue hydrogen production in Norway and the UAE is contracting certified low-methane supply for German chemical buyers.
- Fuel Cells:Solid oxide and proton exchange membrane systems require ultra-low sulfur content to prevent catalyst poisoning. Distributed generation installations in Japan and South Korea are scaling behind commercial and industrial meters.
Electricity production dominates current throughput. Chemical feedstock applications show the steepest expansion trajectory as hydrogen economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon reduction mandates and industrial fuel-switching programs are redrawing demand geography. Pipeline infrastructure constraints and LNG terminal access determine where supply captures premium pricing.
United States
Power generators in Texas and California are displacing coal capacity with combined-cycle gas turbines under state renewable portfolio standards. The US EPA enforces methane performance standards that raise compliance costs for Permian and Appalachian operators. The Delaware Basin sub-region faces Waha hub price volatility during pipeline maintenance cycles.
China
Provincial industrial boilers in Shandong and Jiangsu provinces face mandatory coal-to-gas conversion deadlines under MEE dual carbon targets. The National Energy Administration centralizes LNG procurement authority through state-backed trading houses. Guangdong and Zhejiang distributors are losing direct import licenses as purchasing consolidates.
Germany
Utilities contract long-term pipeline supply to displace remaining coal-fired baseload under national carbon reduction timelines. The EU F-Gas Regulation imposes methane intensity certification requirements for LNG cargo acceptance. Rotterdam-connected industrial clusters in the Rhine-Ruhr region are retrofitting steam crackers for methane feedstock.
Qatar
North Field expansion projects anchor Pacific basin LNG supply commitments to Japanese and South Korean utilities. Destination-clause disputes with Japanese buyers are creating arbitration backlogs that delay final investment decisions. Ras Laffan Industrial City liquefaction terminals capture interbasin arbitrage as Chinese procurement concentrates.
Australia
East coast LNG export terminals face domestic gas reservation policy pressure from the federal government. The country's national energy regulator enforces pipeline access codes that constrain producer market power. Gladstone and Karratha industrial zones are scaling carbon capture integration for blue hydrogen export to German chemical buyers.
Dry Natural Gas Market Competitive Landscape
On the supply side, the industry is consolidating around integrated operators with captive midstream infrastructure and LNG export positioning. Pure-play upstream independents face margin compression from methane compliance costs and takeaway constraints. Two archetypes dominate: supermajors with global LNG portfolios and shale specialists with basin-scale production. Competitive moves center on pipeline capacity commitments and carbon intensity certification partnerships.
Within the integrated supermajor tier, ExxonMobil and Shell occupy positions defined by liquefaction terminal access and interbasin trading capability. Among North American shale specialists, Coterra Energy exemplifies the vertically integrated model with Permian and Marcellus basin control. EQT Corporation anchors the Appalachian pure-play archetype with scaled production and midstream access. These three represent the strategic divergence between global LNG arbitrage and domestic pipeline supply concentration.
| Leading Market Players |
|---|
| Coterra Energy |
| EQT Corporation |
| ExxonMobil |
| Chevron |
| Shell |
| Southwestern Energy |
| China National Petroleum Corporation |
| ConocoPhillips |
| Chesapeake Energy |
| Others |
Supply & Pricing Matrix
Permian-Mountain West takeaway constraints at the Waha hub signal persistent undercapacity that compresses wellhead margins while amplifying price volatility during maintenance cycles. This utilization squeeze forces producers toward long-term contract commitments and integrated LNG export positioning to escape spot market exposure.
Pricing Analysis
Certification level under the EU F-Gas Regulation and EPA methane performance standards creates the primary spread between premium and standard supply tiers. Three-tier pricing structure across certified low-methane, conventional pipeline-grade, and spot market delivery separates integrated exporters from basin-bound independents. Pricing pressure stems from Chinese state trading house procurement consolidation that compresses term premiums for non-integrated suppliers. Industrial chemical buyers in Germany and Singapore exhibit the least price sensitivity due to feedstock switching costs, while provincial distributors in China face margin erosion as import licenses centralize.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities are becoming standard for Appalachian and Permian producers facing PHMSA-mandated pipeline integrity capex cycles. Production concentrates in the United States, Qatar, and Australia, with feedstock drawn from hydraulic fracturing operations, conventional reservoir depletion, and North Field expansion projects. Raw material dependencies center on proppant supply from Wisconsin and Texas mines, steel for pipeline construction, and specialized liquefaction equipment from Japanese and Korean fabricators. Single-source vulnerability runs through Qatari liquefaction capacity committed to Pacific basin offtake. Distribution runs through high-pressure interstate pipelines, LNG terminals capturing interbasin arbitrage, and small-scale trucking for stranded industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry natural gas markets are recovering from cyclical lows as power generation baseload expansion and industrial coal-to-gas conversion in China tighten supply-demand balances. This cyclical upturn rewards operators with captive midstream infrastructure and certified low-methane production.
For Market Incumbents: Pre-empt margin compression from EPA methane enforcement by deploying continuous monitoring infrastructure across Permian and Marcellus positions. Secure pipeline capacity commitments and liquefaction terminal slots before Chinese procurement consolidation locks up Pacific basin supply. Deepen backward integration into carbon capture partnerships for blue hydrogen export certification.
For New Entrants and Emerging Players: Pursue Vietnam industrial zone gasification projects requiring distributed LNG receiving infrastructure that incumbents have underdeveloped. Target biogas production clusters in Denmark and California where landfill diversion mandates create protected margin pools. Lead with carbon-negative credentials under EU certification schemes to bypass commodity pricing pressure.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated shale specialists with basin-scale production and midstream control rather than pure-play upstream independents facing methane compliance cost inflation. Watch for inflection signals in Japanese utility offtake contract renegotiations with Qatari suppliers, as arbitration resolutions will clarify long-term pricing benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | North Field expansion projects anchor Pacific basin LNG supply commitments to Chinese state trading houses. |
| Long-term Supply Agreement | German utilities contract pipeline gas to displace coal capacity under national carbon reduction timelines. |
| Green Certification Program | EU F-Gas Regulation methane intensity certification determines LNG cargo acceptance at Belgian and Spanish terminals. |
| Vertical Integration into Storage | Coterra Energy controls wellhead-to-hub economics across Permian and Marcellus basins. |
| Technology Licensing | Automated methane detection systems collapse detection-to-repair cycles for EPA compliance advantage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA production data, IEA demand forecasts, FERC pipeline filings, and project development databases. Interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists informed supply-side and demand-side assumptions. Bottom-up triangulation across basin-level production economics and top-down validation against national energy balances anchored volume estimates.
Forecast inputs include fuel source segmentation, generation capacity tiers, project scale categories, regulatory framework clusters, and regional grid types across the analysis window. CAGRs derive from modeled supply-demand balances incorporating shale decline curves, LNG liquefaction capacity additions, and industrial fuel-switching trajectories. Specific inputs include EPA methane enforcement timelines and Chinese MEE dual carbon target implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Qatar and Australian exporters to redirect supply from Pacific to Atlantic basins would shift outcomes. Macroeconomic deviation, regulatory acceleration, or breakthrough renewable storage cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Global Oil and Gas Analytics Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Seismic Survey Equipment Market