
 Connected Oil and Gas Market | 2026-2036
Connected Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Oil and Gas Market Insights
Midstream logistics operators is reorganizing procurement priorities around real-time pipeline integrity monitoring, pulling investment away from legacy SCADA-only deployments. Schlumberger leverages its subsurface digital platform to anchor deepwater contract wins across the Gulf of Mexico. Honeywell International sustains manufacturing scale in ruggedized edge devices for hazardous environments. Baker Hughes differentiates through turbomachinery diagnostics married to cloud analytics.
Connected oil and gas denotes the integration of industrial IoT sensors, edge computing nodes, and machine learning algorithms across exploration, production, and distribution infrastructure to enable predictive maintenance, emissions tracking, and automated reservoir management. These systems typically operate on IEC 61508-certified hardware with sub-50ms latency requirements for safety-critical control loops. IoT and machine learning deployments are expanding fastest in offshore asset management, where margin pools concentrate around predictive failure models for subsea equipment. Production optimization applications remain mature onshore but are accelerating in remote Arctic and deepwater fields where labor access is constrained.
The US EPA enforces methane monitoring mandates under Clean Air Act protocols, while the EU F-Gas Regulation phases down fluorinated greenhouse gas use in refrigeration and cooling systems tied to gas processing. Brazil's national petroleum regulator imposes real-time production reporting requirements that force upstream operators to upgrade telemetry infrastructure. Stakeholders must decide whether to build proprietary data lakes or subscribe to vendor-agnostic cloud architectures as interoperability standards solidify.
Market Dynamics
Upstream operators face a structural squeeze between EPA methane monitoring mandates and the capital intensity of retrofitting legacy wellhead infrastructure with IEC 61508-certified edge devices. This tension compresses project timelines and forces parallel technology tracks.
Growth Catalysts
- EPA Clean Air Act enforcement:Methane emissions rules mandate continuous monitoring at compressor stations and well pads, forcing hardware refresh cycles across the Permian Basin.
- Subsea predictive analytics:Offshore Brazil operators deploy machine learning models for blowout preventer failure prediction, cutting unplanned downtime in deepwater fields.
- EU F-Gas phase-down:Refrigeration-dependent gas processing facilities must retrofit cooling systems, triggering sensor upgrades for leak detection and compliance logging.
Market Restraints
- Semiconductor supply concentration:Ruggedized edge devices depend on TSMC-fabricated chips, exposing lead times to Taiwan Strait logistics volatility.
- Legacy SCADA interoperability:Proprietary protocols from 1990s-era systems block seamless API integration with cloud-native analytics platforms.
- Arctic deployment costs:Hardened hardware rated for minus 40°C operations carries 3x material cost premiums versus standard industrial IoT gear.
Strategic Opportunities
- Saudi offshore expansion:Aramco's Marjan and Zuluf developments lack installed telemetry base, creating greenfield digital twin deployment potential.
- Carbon accounting convergence:Satellite methane detection fused with ground sensor networks enables verified emissions credits for EU ETS participation.
- Vendor-agnostic data lakes:OPC UA over TSN standardization lets operators avoid Schlumberger-Honeywell-Baker Hughes platform lock-in.
Industry Challenges
- IEC 61508 certification timelines:Safety integrity level validation for new edge devices stretches 18-24 months, delaying field deployment.
- Subsea fiber optic repair:Umbilical cable faults in 1,500-meter depths require specialized vessels with 45-day mobilization windows.
- OT-IT security segmentation:Purdue model compliance demands air-gapped networks that conflict with cloud analytics latency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Oil and Gas Market |
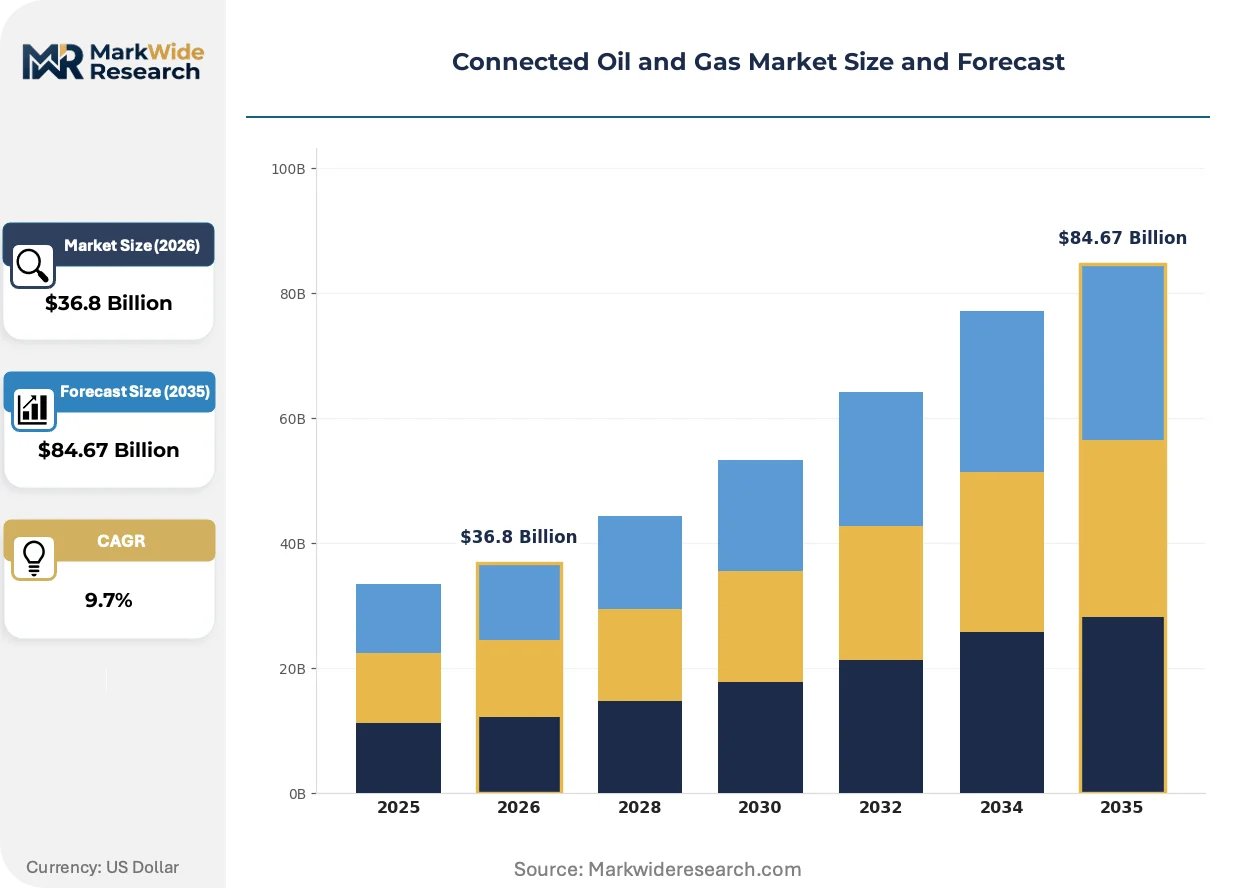
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $84.67 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Cloud Computing, Big Data Analytics, Machine Learning Application: Enhanced Oil Recovery, Production Optimization, Asset Management, Environmental Monitoring End User: Exploration Companies, Production Firms, Service Providers, Refining Organizations Deployment: Onshore, Offshore, Hybrid, Remote |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Emerson Electric, Honeywell International, ABB, Siemens, General Electric, Weatherford International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Oil and Gas Market Trends and Innovations
Digital thread architectures are collapsing the traditional separation between reservoir simulation, production operations, and midstream logistics. This integration demands new data governance models and compresses vendor specialization.
Time-sensitive networking over 5G private cellular is supplanting hardwired fieldbus protocols in offshore platforms. Shell and Equinor pilot installations in the North Sea demonstrate sub-10ms latency for emergency shutdown loops. The technology is compressing platform modification costs by eliminating 40% of legacy copper cabling runs.
The EU F-Gas Regulation's phasedown schedule tightens refrigerant leakage thresholds at LNG liquefaction plants. Operators must install continuous infrared sensors and automated reporting pipelines to national environmental agencies. German and Dutch terminals face 2027 compliance deadlines that accelerate procurement of Honeywell and Siemens monitoring packages.
Integrated service contracts now bundle hardware, edge software, and reservoir engineering analytics under single-vendor accountability. This displaces the prior model of separate SCADA, cloud, and consultancy procurement. The shift concentrates in Gulf of Mexico deepwater projects where operator staff reductions limit vendor management bandwidth.
Connected Oil and Gas Market Segmentation
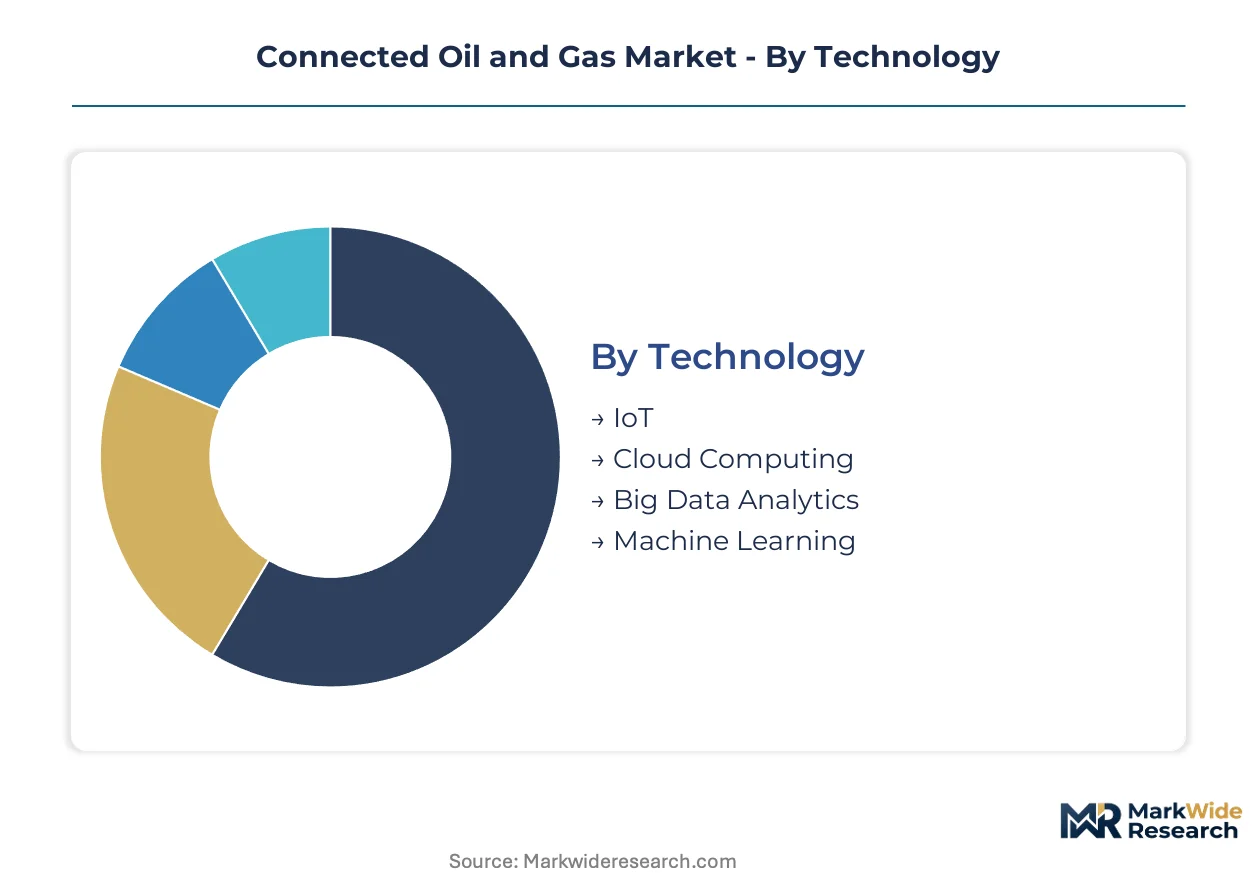
Technology stack choices determine capital allocation cycles and vendor lock-in exposure across upstream, midstream, and downstream operators. Deployment mode selection drives hardware specifications, connectivity costs, and regulatory compliance architecture. Application focus shapes whether procurement prioritizes production uplift or emissions accountability.
Technology:
Margin pools concentrate in edge-to-cloud integration layers where proprietary algorithms command recurring service fees.
- IoT:Industrial sensor networks operating on IEC 61508-certified hardware capture real-time wellhead pressure, flow rate, and equipment vibration data. Permian Basin operators deploy these at scale to satisfy EPA methane monitoring mandates while compressing manual inspection labor.
- Machine Learning:Predictive models trained on historical failure patterns forecast subsea equipment degradation before functional failure. Offshore Brazil deepwater fields represent the most concentrated demand for blowout preventer failure prediction, cutting unplanned downtime.
- Cloud Computing:Vendor-agnostic architectures store petabyte-scale production datasets with API accessibility for third-party analytics tools.
- Big Data Analytics:Reservoir simulation platforms fuse seismic, drilling, and production logs into unified digital twins.
IoT holds installed capacity. Machine Learning is rotating up the share rankings.
Application:
Application selection tracks whether operators prioritize barrel recovery economics or regulatory risk mitigation.
- Production Optimization:Real-time reservoir management systems adjust artificial lift parameters and choke settings to maximize flow rates within facility constraints. North Sea mature fields deploy these platforms to extend plateau production without capital-intensive infill drilling.
- Environmental Monitoring:Continuous emissions detection networks fuse satellite methane detection with ground sensor arrays for verified reporting to EU ETS registries. German and Dutch LNG terminals face tightening F-Gas Regulation thresholds that accelerate procurement.
- Asset Management:Integrated platforms track equipment health across drilling rigs, pipelines, and processing facilities.
- Enhanced Oil Recovery:Surveillance systems monitor CO2 flood front propagation and chemical injection conformance.
Production Optimization commands legacy spend. Environmental Monitoring is climbing the fastest as compliance deadlines tighten.
End User:
Procurement authority shifts based on whether technology spend flows through capital projects or operating budgets.
- Production Firms:Upstream operators with retained ownership of producing assets fund multi-year digital twin deployments as opex rather than capex. Gulf of Mexico independents concentrate spending here to offset declining technical staff.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle connected hardware with reservoir engineering expertise under integrated service contracts.
- Exploration Companies:Venture-backed wildcatters prioritize low-cost seismic processing over permanent infrastructure monitoring.
- Refining Organizations:Downstream processors apply predictive maintenance to fluid catalytic crackers and hydrocracker units.
Production Firms anchor contract value. Service Providers are gaining share through bundled accountability structures.
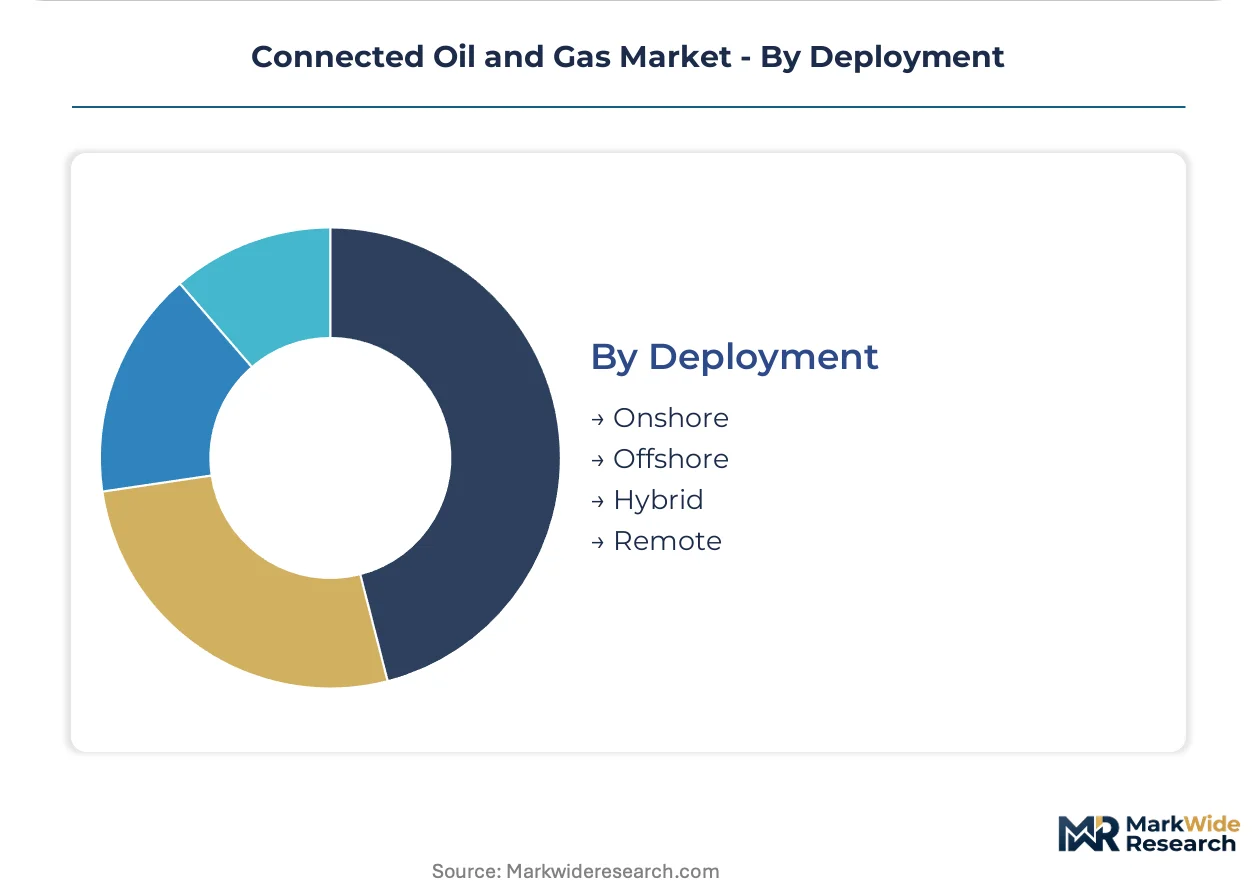
Deployment:
Deployment mode dictates connectivity cost structures and hardware environmental ratings.
- Offshore:Subsea fiber optic and acoustic telemetry networks operating at 1,500-meter depths require specialized umbilical cables and ROV-deployable sensors. Aramco's Marjan and Zuluf developments represent greenfield deployment potential without legacy infrastructure displacement.
- Remote:Arctic and deepwater fields with constrained labor access depend on satellite backhaul and hardened edge devices rated for minus 40°C operations, carrying material cost premiums.
- Onshore:Permian Basin and other conventional plays leverage cellular and licensed radio networks with established tower infrastructure.
- Hybrid:Mixed architectures combine local edge processing with intermittent cloud synchronization for bandwidth-constrained locations.
Onshore carries cumulative installed base. Offshore is expanding most quickly as pre-salt and deepwater projects advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream digital infrastructure investment clusters around five national markets where regulatory enforcement and reserve economics intersect. Brazil, the United States, Norway, Saudi Arabia, and the United Kingdom concentrate procurement authority for connected oil and gas platforms.
United States
Permian Basin operators deploy IEC 61508-certified edge devices at well pads to satisfy EPA methane monitoring mandates under Clean Air Act protocols. The EPA enforces continuous emissions surveillance at compressor stations, forcing hardware refresh cycles across Texas and New Mexico. Houston anchors vendor engineering support for Gulf of Mexico deepwater digital twin deployments.
Brazil
Pre-salt deepwater fields drive demand for subsea predictive analytics and blowout preventer failure models. The national petroleum regulator imposes real-time production reporting requirements that compel telemetry infrastructure upgrades. Santos Basin operators source integrated service contracts bundling hardware, edge software, and reservoir engineering analytics.
Norway
North Sea mature fields deploy production optimization platforms to extend plateau production without capital-intensive infill drilling. The Norwegian Petroleum Directorate mandates digital readiness standards for offshore facility modifications. Stavanger concentrates vendor engineering resources for subsea fiber optic and acoustic telemetry networks.
Saudi Arabia
Aramco's Marjan and Zuluf offshore developments represent greenfield digital twin deployment potential without legacy infrastructure displacement. The national regulator requires real-time reservoir surveillance for major field developments. Eastern Province fabrication yards integrate connected hardware into newbuild platform specifications.
United Kingdom
North Sea decommissioning timelines accelerate investment in remote monitoring to reduce offshore staffing levels. The North Sea Transition Authority ties license renewals to emissions reduction commitments verified through sensor networks. Aberdeen maintains specialist engineering capacity for 5G private cellular pilot installations.
Connected Oil and Gas Market Competitive Landscape
Concentration sits with integrated oilfield service conglomerates that bundle hardware, edge software, and reservoir engineering under single-vendor accountability. Three archetypes dominate: full-service digital platform providers, ruggedized edge device manufacturers, and turbomachinery diagnostics specialists. Competitive dynamics revolve around integrated service contract capture and interoperability standard-setting through OPC UA over TSN adoption.
Within the full-service digital platform tier, Schlumberger leverages subsurface digital platforms to anchor deepwater contract positions, while Halliburton and Baker Hughes occupy integrated service bundling roles across Gulf of Mexico and Brazilian pre-salt developments. These three exemplify the shift from separate SCADA, cloud, and consultancy procurement toward unified vendor accountability structures.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Emerson Electric |
| Honeywell International |
| ABB |
| Siemens |
| General Electric |
| Weatherford International |
| Others |
Pricing and Supply Chain Analysis
TSMC's 90% share of advanced semiconductor fabrication for ruggedized edge devices concentrates pricing power among a handful of foundry customers, compressing margins for downstream hardware vendors while elevating cost floors for IEC 61508-certified safety systems. This scale dynamic forces tiered procurement structures where volume commitments determine unit economics across the Permian Basin and North Sea deployment clusters.
Pricing Analysis
Volume-discount tiering structures dominate hardware procurement, with three-tier pricing separating SIL-4 certified devices from SIL-2 and non-safety-rated alternatives. Price differentiation rests on certification grade and after-sales telemetry bundling rather than raw component costs. Pricing pressure stems from Aramco's greenfield Marjan and Zuluf developments demanding vendor-agnostic OPC UA architectures that erode platform lock-in premiums. National oil companies exhibit lowest price sensitivity due to sovereign balance sheet backing, while Permian Basin independents negotiate aggressively on per-wellhead unit economics.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes 18-24 month IEC 61508 certification timelines to geopolitical disruption, forcing operators to pre-position inventory across Houston, Stavanger, and Singapore distribution hubs. Ruggedized edge hardware draws from TSMC-fabricated chips, subsea fiber optic umbilicals manufactured in Norway and Japan, and Arctic-hardened enclosures sourced from Finnish and Canadian specialty metalworkers. Single-source vulnerability concentrates in deepwater blowout preventer telemetry where proprietary acoustic protocols resist second-sourcing. Distribution runs through integrated service contractors who bundle hardware, edge software, and reservoir engineering under unified vendor accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected oil and gas market represents a service-attach opportunity where predictive analytics subscriptions and emissions compliance-as-a-service layers expand faster than hardware replacement cycles, compressing capital intensity for operators while elevating recurring revenue capture for platform vendors.
For Market Incumbents: Compound platform stickiness by embedding IEC 61508 certification services into hardware sales, creating switching costs that resist OPC UA standardization threats. Deepen backward integration into subsea fiber optic manufacturing to offset Norwegian and Japanese supplier concentration. Prioritize Saudi offshore greenfield capture at Marjan and Zuluf before competitor telemetry base establishes. For New Entrants and Emerging Players: IEC 61508 fast-track certification partnerships with TÜV Rheinland or Exida accelerate market entry against 18-24 month incumbent validation cycles. Target Permian Basin methane monitoring retrofit demand where EPA enforcement compresses procurement timelines and favors agile responders. Lead with satellite-ground sensor fusion for EU ETS carbon accounting verification, bypassing integrated service contract bundling that blocks pure-play hardware vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-to-cloud integration specialists with recurring service revenue exceeding 40% of contract value. Five-to-ten year viability hinges on vendor-agnostic data lake architectures displacing Schlumberger-Honeywell-Baker Hughes platform lock-in. Watch OPC UA over TSN adoption rates as inflection signal—acceleration indicates commoditization pressure on proprietary protocols, while stagnation preserves incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Bundling | Unifies hardware, edge software, and reservoir analytics under single-vendor accountability for Gulf of Mexico deepwater projects. |
| OPC UA over TSN Standardization | Enables vendor-agnostic interoperability that threatens proprietary platform lock-in across Schlumberger and Honeywell architectures. |
| Subsea Fiber Optic Backward Integration | Captures umbilical cable supply chain concentrated in Norway and Japan to compress 45-day ROV mobilization windows. |
| Satellite-Ground Sensor Fusion | Fuses methane detection networks for verified EU ETS emissions credits at German and Dutch LNG terminals. |
| Arctic Hardened Edge Manufacturing | Addresses 3x material cost premiums for minus 40°C rated devices in remote labor-constrained fields. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, EU ETS transaction registries, and Norwegian Petroleum Directorate digital readiness filings. Interviews with upstream production engineers, subsea telemetry specialists, integrated service contract procurement leads, and IEC 61508 certification auditors combined with customs records for ruggedized edge device imports and Aramco contractor prequalification disclosures. Bottom-up wellhead deployment counts and top-down platform vendor revenue triangulation validate market sizing across the analysis window.
Segmentation dimensions modeled span technology stack (IoT, machine learning, cloud computing, big data analytics), deployment mode (offshore, remote, onshore, hybrid), application focus (production optimization, environmental monitoring, asset management, enhanced oil recovery), and end-user procurement authority (production firms, service providers, exploration companies, refining organizations). CAGRs derive from regression against historical digital twin adoption curves and regulatory enforcement intensity indices, with specific weighting for EPA methane rule implementation pace and EU F-Gas Regulation phasedown deadlines.
Underlying assumptions cover semiconductor supply normalization, IEC 61508 certification timeline stability, and subsea vessel day-rate trajectories, with deviation risk concentrated in Taiwan Strait logistics disruption and 5G private cellular latency performance in North Sea pilot installations. Practitioners should keep alternative scenarios live as OPC UA standardization adoption and vendor-agnostic cloud architecture penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Well Cementing Market
Oil & Gas
Well Testing Services Market