
 Wellhead and Christmas Tree Special Parts Market | 2026-2036
Wellhead and Christmas Tree Special Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Wellhead and Christmas Tree Special Parts Market Insights
Modular wellhead assembly bundling is pivoting buyer preference away from discrete component sourcing toward integrated Christmas tree packages. Schlumberger leverages its integrated project delivery model to anchor long-term service contracts across deepwater basins. Baker Hughes differentiates through in-house alloy metallurgy capabilities that sustain premium positioning in high-pressure high-temperature applications. TechnipFMC competes by controlling subsea system architecture from wellhead through flowline connection.
Wellhead and Christmas Tree Special Parts comprise pressure-containing and flow-control components—gate valves, choke valves, tubing heads, and adapters—fabricated to API 6A pressure ratings up to 20,000 psi and designed to seal annular spaces between casing strings while managing hydrocarbon flow from reservoir to surface facilities. Carbon steel and stainless steel material grades dominate volume production for standard onshore duty, while duplex steel and Alloy 625 command margin pools in corrosive subsea and enhanced recovery environments where chloride cracking resistance determines field life. Choke valves for high-erosion deepwater service represent the fastest-growing product configuration as operators push into pre-salt and Lower Tertiary formations.
API 6A and NACE MR0175/ISO 15156 standards govern material selection and pressure integrity testing, with the US FAA and Coast Guard imposing additional structural requirements on offshore platform-mounted systems through marine safety regulations. The EPA enforces emissions containment protocols that drive demand for metal-to-metal sealing technology in wellhead connectors. Stakeholders must monitor evolving sour-service definitions and hydrogen sulfide partial-pressure thresholds as drilling frontiers encounter more aggressive reservoir chemistries.
Market Dynamics
Deepwater exploration economics are compressing wellhead procurement cycles as operators demand pre-integrated subsea assemblies that slash rig-time exposure and eliminate offshore welding operations. This structural pull toward modular, factory-tested packages is reconfiguring supplier relationships across the value chain.
Growth Catalysts
- Pre-salt formation access:Brazil's Santos Basin and West Africa's Lower Tertiary plays require 15,000+ psi rated Christmas trees, driving specification upgrades across fabrication yards in Houston and Singapore.
- EPA methane containment rules:Metal-to-metal sealing mandates for wellhead connectors are accelerating replacement cycles in mature US onshore basins where legacy elastomer seals face compliance deadlines.
- Duplex steel adoption:Chloride-resistant alloys for sour-service duty are penetrating North Sea and Gulf of Mexico installations where reservoir H2S partial pressures exceed NACE MR0175 thresholds.
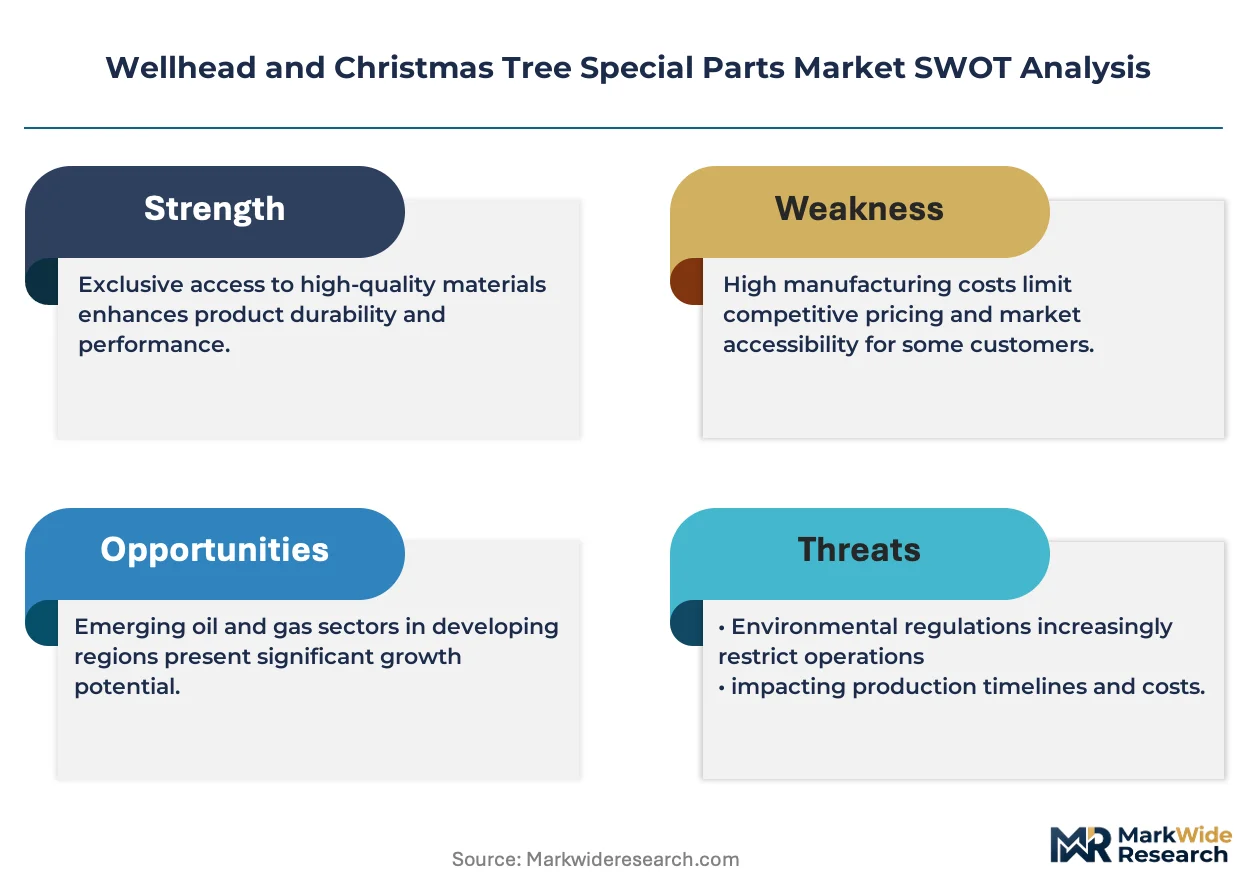
Market Restraints
- Nickel and molybdenum price volatility:Alloy 625 and super-duplex feedstock costs swing with stainless steel commodity indices, compressing margins on subsea wellhead contracts with fixed-price terms.
- Fabrication corridor concentration:US Gulf Coast yard capacity bottlenecks during hurricane season create delivery backlogs for integrated Christmas tree packages.
- API 6A certification timelines:Third-party witness testing for 20,000 psi ratings extends lead times 8-14 weeks beyond standard 10,000 psi qualifications.
Strategic Opportunities
- Decommissioning retrofit demand:UK North Sea plug-and-abandonment campaigns require specialized tubing head adapters that interface with legacy platform infrastructure.
- Digital twin integration:Sensor-embedded wellhead systems converging with subsea IoT architectures enable predictive maintenance contracts for floating production operators.
- India KG Basin expansion:Reliance-BP deepwater developments are qualifying new local fabrication partners for high-pressure high-temperature wellhead supply.
Industry Challenges
- Weld procedure qualification scarcity:ASME Section IX certified welders for super-duplex overlay work command premium wages and limit throughput at specialist machine shops.
- Legacy platform interface mismatch:New compact wellhead designs require custom adapter spools to mate with 1980s-vintage platform conductors, complicating project engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellhead and Christmas Tree Special Parts Market |
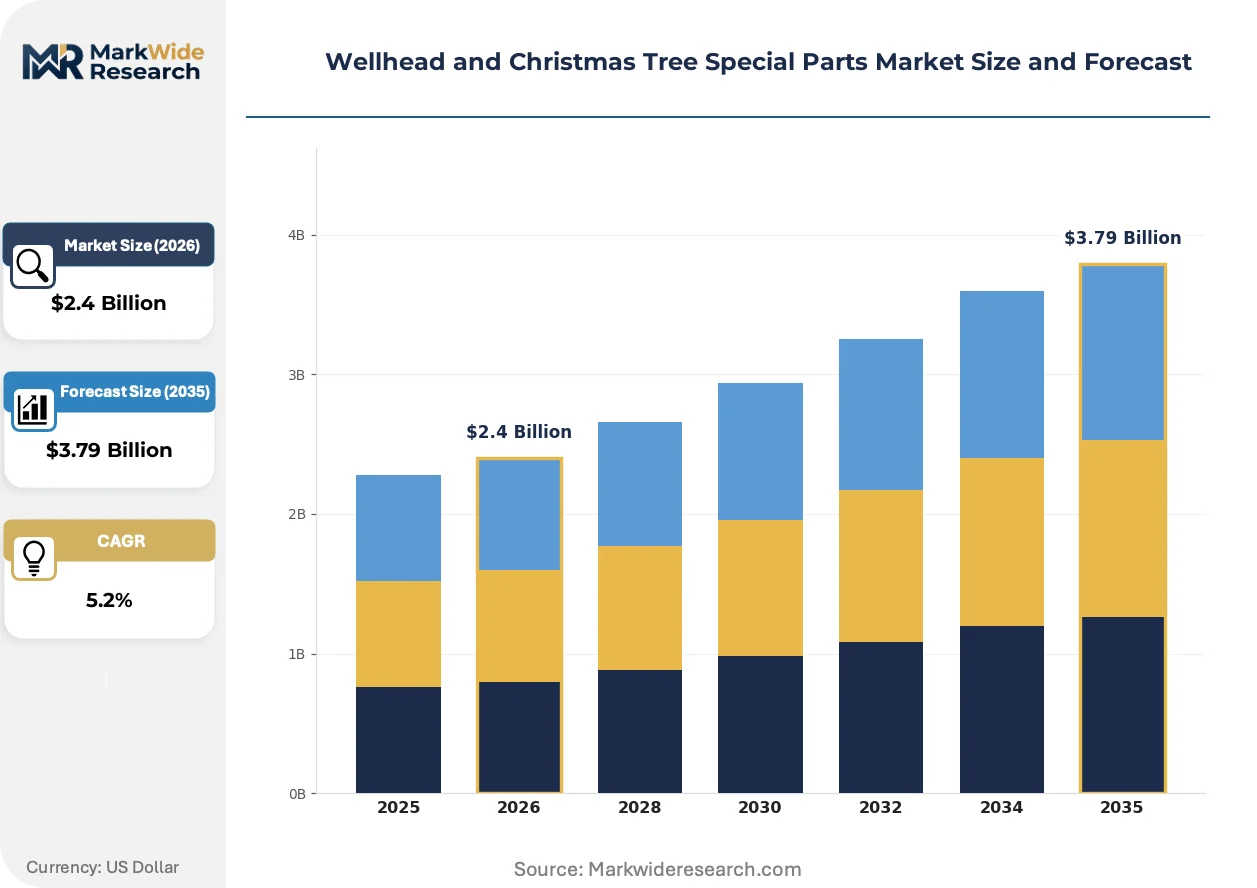
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valves, Choke Valves, Packers, Adapters, Flanges, Tubing Heads Material: Carbon Steel, Stainless Steel, Duplex Steel, Inconel, Monel, Alloy 625 Application: Onshore Extraction, Offshore Drilling, Deepwater Production, Subsea Completion, Enhanced Recovery, Directional Drilling End User: Oil & Gas Operators, Drilling Contractors, E&P Service Providers, Well Completion Firms |
| Companies Covered | Aker Solutions, Diamond Group Corporation, Schlumberger, FMC Technologies, VetcoGray, Baker Hughes, Cameron, Diwell, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellhead and Christmas Tree Special Parts Market Trends and Innovations
Subsea system architecture is converging toward horizontal Christmas trees and satellite wellhead configurations that eliminate surface platform footprints. This structural shift demands new metallurgical and sealing competencies across the supply base.
Hydraulic fracturing-rated wellhead systems rated to 20,000 psi working pressure are expanding into Permian Basin and DJ Basin pad drilling operations where zipper-frac intensity degrades conventional choke manifold life. E&P procurement teams now specify hardened trim packages and extended-life gate valves as standard. This specification escalation is compressing the addressable market for standard-pressure onshore wellheads and forcing fabricators to retool for premium-tier production.
The EPA's New Source Performance Standards for greenhouse gas emissions are tightening flange-sealing requirements on wellhead connectors used in federal waters. Operators must document fugitive methane testing protocols during commissioning. Gulf of Mexico deepwater projects now specify API 6A Appendix F PR2-level validation as baseline, with additional third-party witness testing for metal-to-metal seal integrity.
Integrated service contracting is displacing discrete component purchasing as ExxonMobil, Shell, and BP consolidate wellhead procurement under long-term alliance frameworks with system integrators. These agreements bundle engineering, fabrication, installation, and aftermarket support into single-source accountability. The model is most visible in US Gulf of Mexico and Brazilian pre-salt developments where operator staff reductions have eliminated in-house wellhead engineering capacity.
Wellhead and Christmas Tree Special Parts Market Segmentation
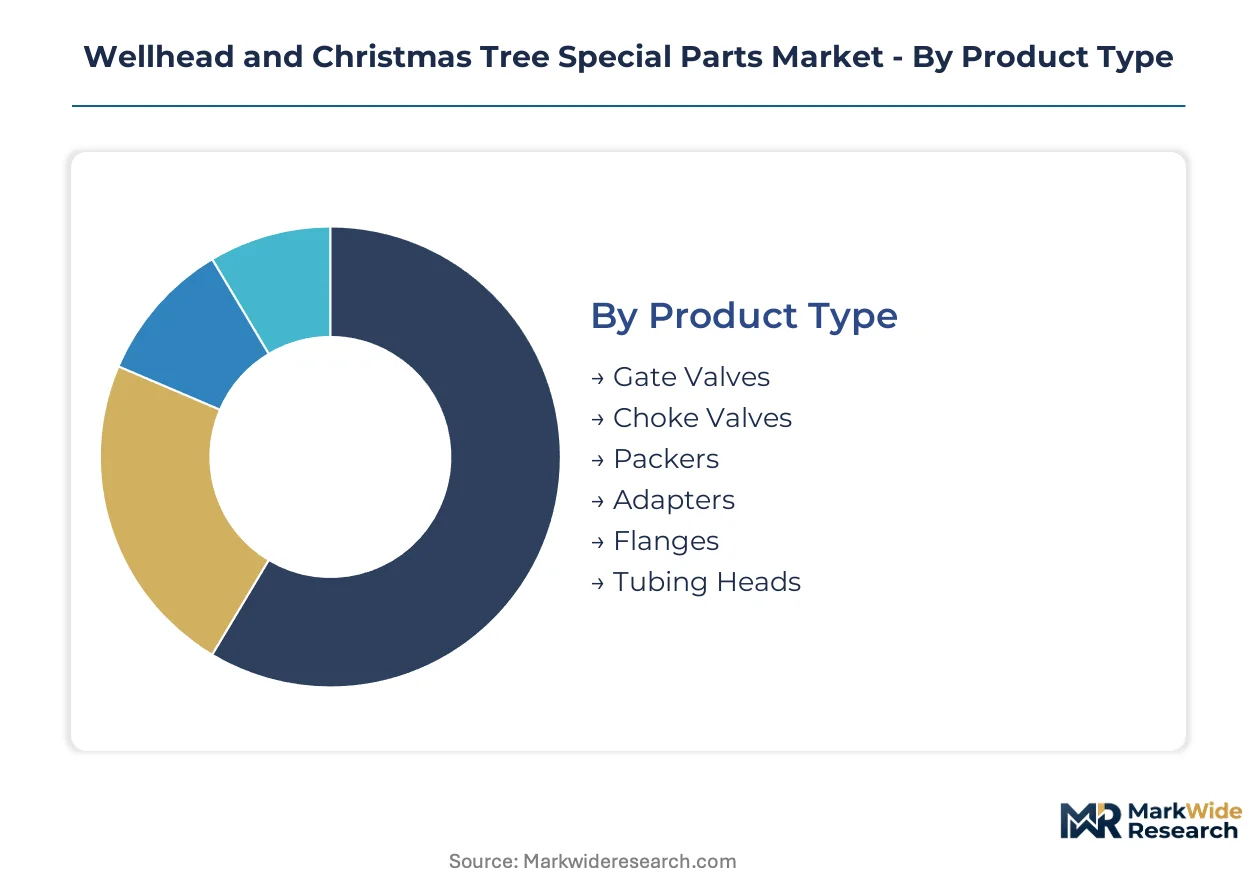
Wellhead and Christmas Tree Special Parts procurement decisions cluster around pressure ratings, metallurgical performance, and integration depth. Specification mismatches between reservoir chemistry and material selection drive field failures and replacement cycles. Understanding segment boundaries clarifies where fabrication margins concentrate versus where commoditization pressures dominate.
Product Type:
Capital intensity escalates sharply with pressure containment complexity and actuation mechanism sophistication.
- Gate Valves:Full-bore through-conduit designs with metal-to-metal sealing surfaces handle 10,000-20,000 psi working pressures. Permian Basin zipper-frac operations specify hardened trim packages from Houston fabricators to withstand sand erosion. API 6A PR2 validation timelines extend procurement cycles for super-premium ratings.
- Choke Valves:Adjustable flow-control trim with tungsten carbide or Stellite facing manages erosive multiphase flow from high-drawdown wells. Pre-salt developments in Brazil's Santos Basin require 15,000+ psi rated units with erosion-resistant cage designs. Deepwater operators specify these as the critical life-limiting component in Christmas tree assemblies.
- Packers:Annular sealing elements isolate production zones and protect casing integrity.
- Adapters:Transition spools connect mismatched casing programs and legacy platform interfaces.
- Flanges:API 6A bolted connections seal wellhead assemblies against pressure and environmental loads.
- Tubing Heads:Suspension points for production tubing strings incorporate back-pressure valves and test ports.
Most installed capacity flows through Gate Valves. Expansion is steepest in Choke Valves.
Material:
Raw material selection dictates corrosion resistance, weldability, and final assembly cost structure.
- Alloy 625:Nickel-chromium-molybdenum superalloy delivers exceptional chloride stress-corrosion cracking resistance in sour-service subsea environments. Gulf of Mexico Lower Tertiary completions specify this grade where H2S partial pressures exceed NACE MR0175 thresholds. Nickel price volatility compresses margins on fixed-price contracts.
- Duplex Steel:Ferritic-austenitic microstructure balances strength and pitting resistance for seawater-exposed subsea wellheads. North Sea operators specify 25Cr super-duplex for tieback connectors and mudline suspension systems. Fabrication requires ASME Section IX qualified welders for root pass overlay work.
- Carbon Steel:Standard API 5CT grades dominate onshore conventional production.
- Stainless Steel:13Cr and 17-4PH grades serve moderate sour-service onshore duty.
- Inconel:High-nickel alloys seal high-temperature thermal recovery wellheads.
- Monel:Copper-nickel alloys resist marine atmospheric corrosion on platform-mounted equipment.
Volume concentrates in Carbon Steel. Value capture is climbing fastest in Alloy 625.
Application:
Operating environment determines regulatory exposure, metallurgical specification, and service intensity.
- Deepwater Production:Subsea-rated Christmas trees and wellheads deployed in 1,000+ meter water depths require horizontal tree architectures and satellite tieback configurations. Brazil's pre-salt and West Africa's Lower Tertiary basins anchor demand for 15,000-20,000 psi rated assemblies. Factory acceptance testing extends lead times 8-14 weeks beyond standard qualifications.
- Subsea Completion:Seabed-installed wellheads with remote hydraulic and electric actuation eliminate surface platform footprints. TechnipFMC and Baker Hughes compete on integrated system architecture from wellhead through flowline connection. EPA methane containment rules mandate metal-to-metal sealing validation for federal waters.
- Onshore Extraction:Conventional land-based drilling uses standard-pressure wellhead configurations.
- Offshore Drilling:Platform-mounted surface wellheads support jackup and semisubmersible operations.
- Enhanced Recovery:Thermal and chemical injection wellheads handle corrosive flood fluids.
- Directional Drilling:Pad-drilling configurations demand compact wellhead spacing and zipper-frac compatibility.
Deployment volume peaks in Onshore Extraction. Specification escalation is most pronounced in Deepwater Production.
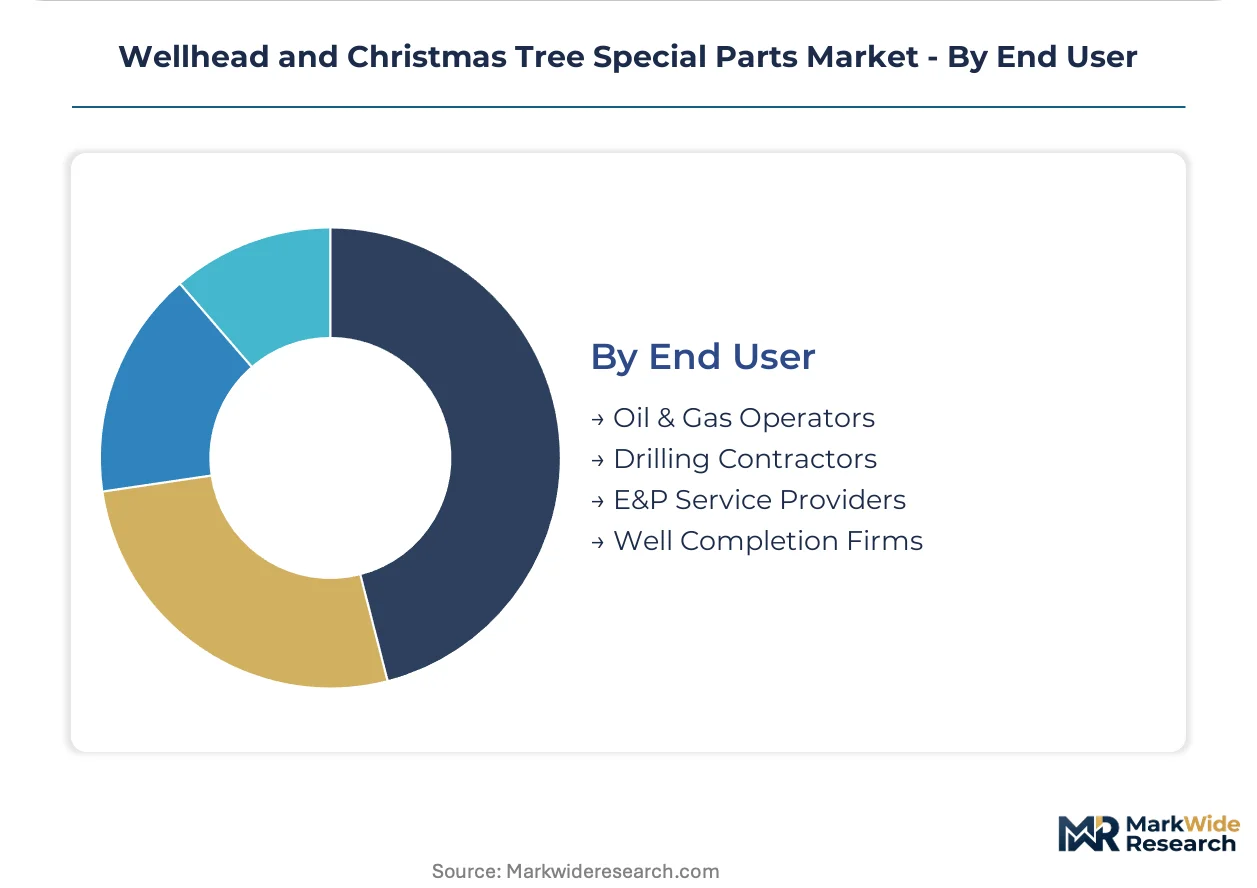
End User:
Procurement authority and technical capability vary sharply across buyer categories.
- Oil & Gas Operators:Supermajors and national oil companies consolidate wellhead procurement under long-term alliance frameworks bundling engineering, fabrication, and aftermarket support. ExxonMobil, Shell, and BP have eliminated in-house wellhead engineering capacity in the US Gulf of Mexico and Brazil. Single-source accountability shifts risk to system integrators.
- Drilling Contractors:Rig owners specify wellhead compatibility with BOP stacks and riser systems. Transocean and Seadrill demand pre-integrated subsea assemblies that minimize rig-time exposure and eliminate offshore welding. Procurement cycles compress as exploration economics tighten.
- E&P Service Providers:Schlumberger and Halliburton anchor integrated project delivery with captive wellhead supply.
- Well Completion Firms:Specialists in frac stack and flowback equipment interface with wellhead pressure ratings.
Contract volume flows predominantly through Oil & Gas Operators. Technical specification influence is expanding fastest among Drilling Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wellhead and Christmas tree special parts industry traces its modern fabrication lineage to the Gulf Coast petrochemical corridor, where Houston-area machine shops first scaled API-certified production for offshore drilling expansion in the 1970s.
United States
EPA methane containment rules and Bureau of Safety and Environmental Enforcement offshore safety mandates drive specification upgrades across the Gulf of Mexico. The Houston Ship Channel fabrication cluster hosts integrated Christmas tree assembly yards where TechnipFMC and Baker Hughes anchor subsea system production for deepwater operators.
Brazil
Pre-salt formation development in the Santos Basin demands 15,000-20,000 psi rated subsea assemblies that exceed legacy equipment capabilities. ANP local content requirements mandate domestic fabrication partnerships for Petrobras-led developments. The Rio de Janeiro metropolitan area concentrates subsea engineering talent and integration facilities serving Campos and Santos basin projects.
Norway
North Sea decommissioning campaigns and remaining field life extensions sustain demand for sour-service qualified adapters and tubing heads. Petroleum Safety Authority regulations enforce metal-to-metal sealing validation for subsea wellhead connectors in harsh environment deployments. Stavanger and Bergen host specialist machine shops qualified to NORSOK M-650 material traceability standards.
Singapore
Jurong Island fabrication yards serve as the Asia-Pacific hub for subsea Christmas tree integration, supplying West African and Southeast Asian deepwater projects. The Maritime and Port Authority coordinates heavy-lift logistics for 500-ton tree assemblies bound for pre-salt and Lower Tertiary developments. Local yards compete on delivery timelines during Gulf of Mexico hurricane season bottlenecks.
United Kingdom
North Sea plug-and-abandonment obligations and marginal field tiebacks sustain procurement of legacy-compatible tubing head adapters. The Health and Safety Executive enforces well integrity management system requirements that accelerate replacement of elastomer-sealed connectors. Aberdeen maintains subsea engineering concentration despite operator staff reductions, with fabrication increasingly outsourced to specialist machine shops.
Wellhead and Christmas Tree Special Parts Market Competitive Landscape
Premium-margin players sit above commodity-margin players across metallurgical certification tiers, with Alloy 625 and super-duplex qualified fabricators commanding 40-60% price premiums over carbon steel specialists. The supplier base clusters around three archetypes: integrated system architects controlling full subsea architecture, metallurgy-focused specialists capturing high-pressure high-temperature niches, and regional fabricators competing on delivery speed for standard-pressure onshore duty. Dominant competitive moves include backward integration into alloy feedstock supply and strategic partnerships with drilling contractors seeking pre-integrated assembly bundles.
Among integrated system architects, Schlumberger, Baker Hughes, and TechnipFMC exemplify the premium-tier positioning that bundles engineering, fabrication, and aftermarket accountability into single-source contracts. These companies anchor long-term alliance frameworks with supermajors in the US Gulf of Mexico and Brazil, occupying positions where operator engineering staff reductions have eliminated in-house wellhead specification capability. Their scale and certification breadth represent the structural barrier that mid-tier fabricators face when bidding for deepwater pre-salt or Lower Tertiary developments.
| Leading Market Players |
|---|
| Aker Solutions |
| Diamond Group Corporation |
| Schlumberger |
| FMC Technologies |
| VetcoGray |
| Baker Hughes |
| Cameron |
| Diwell |
| TechnipFMC |
| Others |
Pricing and Supply Chain Analysis
Alloy 625 nickel-chromium-molybdenum feedstock costs cascade through three distinct pricing tiers as material moves from Rotterdam commodity exchanges to subsea Christmas tree fabricators in Houston and Singapore. Nickel price volatility on the London Metal Exchange compresses margins on fixed-price contracts for deepwater operators, forcing fabricators to hedge or pass through exposure to procurement teams at supermajors and drilling contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API 6A Appendix F PR2-qualified super-duplex assemblies from carbon steel onshore configurations. Price differentiation hinges on NACE MR0175 certification grade and factory acceptance testing depth, with Alloy 625 subsea connectors commanding substantial premiums over 13Cr stainless alternatives. Cost compression in standard-pressure onshore tiers is intensifying because Permian Basin zipper-frac operators are consolidating procurement under integrated service contracts. Drilling contractors prove least price-sensitive, prioritizing rig-time reduction over unit cost, while independent onshore operators exhibit acute sensitivity to gate valve replacement cycles.
Supply Chain Analysis
Direct-to-operator channels anchor high-value subsea assembly procurement, with integrated project delivery models displacing discrete component purchasing at ExxonMobil, Shell, and BP. Geographic supply concentration clusters in the United States, Brazil, and Singapore, where Houston Ship Channel yards, Rio de Janeiro integration facilities, and Jurong Island fabricators handle 15,000-20,000 psi rated production. Raw material dependencies draw from nickel ore processing in Indonesia, molybdenum concentrate from Chile, and super-duplex plate mills in Sweden. Single-source vulnerability around ASME Section IX certified welders for super-duplex overlay work limits throughput at specialist machine shops during demand surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as reservoir chemistries turn sour and deepwater specifications escalate toward 20,000 psi ratings. The shift toward pre-integrated subsea assemblies rewards fabricators with captive metallurgy capabilities and long-term operator alliances.
For Market Incumbents: To counter nickel price volatility and fixed-price contract margin erosion, backward integration into alloy feedstock supply through offtake agreements with Indonesian nickel processors secures cost visibility. Capacity addition in Singapore during Gulf of Mexico hurricane season bottlenecks captures demand spillover from Houston yard constraints. API 6A Appendix F PR2 certification investment at Brazilian fabrication partnerships defends positioning against ANP local content requirements. For New Entrants and Emerging Players: Enter via decommissioning retrofit demand in the UK North Sea, where plug-and-abandonment campaigns require legacy-compatible tubing head adapters that interface with 1980s platform infrastructure. White-space concentration sits in digital twin integration, where sensor-embedded wellhead systems converging with subsea IoT architectures enable predictive maintenance contracts. A go-to-market angle anchored through drilling contractor partnerships for pre-integrated assembly bundles bypasses operator engineering staff reductions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier carbon steel fabricators face specification escalation toward premium-tier production without captive alloy metallurgy capabilities. Long-term viability favors Alloy 625 and super-duplex qualified specialists with NORSOK M-650 traceability and deepwater project reference lists. The signal to watch is EPA methane containment rule enforcement timelines, which accelerate replacement cycles for elastomer-sealed legacy connectors and expand the addressable market for metal-to-metal sealing validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Ofhtake agreements with Indonesian nickel processors hedge LME price exposure for fixed-price subsea contracts. |
| API 6A Appendix F PR2 Certification Investment | Third-party witness testing for 20,000 psi ratings unlocks Brazilian pre-salt and West Africa Lower Tertiary developments. |
| Digital Twin Platform Development | Sensor-embedded wellhead architectures enable predictive maintenance contracts with floating production operators. |
| Singapore Capacity Expansion | Jurong Island fabrication yards capture demand spillover during US Gulf Coast hurricane season bottlenecks. |
| Decommissioning Retrofit Specialization | Legacy platform interface adapters for UK North Sea plug-and-abandonment campaigns sustain aftermarket revenue. |
Research Methodology
Direct dialogue with subsea project engineers, drilling contractor procurement leads, API certification auditors, and alloy metallurgy specialists grounded qualitative assessment in operational realities. Secondary validation drew from Bureau of Safety and Environmental Enforcement incident reports, EPA methane emissions databases, ANP local content filings, and NORSOK M-650 material traceability standards. Bottom-up and top-down triangulation cross-checked fabrication yard capacity utilization against operator capital expenditure disclosures.
Bottom-up modeling built from individual product segments—gate valves, choke valves, tubing heads, adapters—aggregated through pressure rating tiers and metallurgical grades. Segmentation dimensions spanned product type, material specification, application environment, and end-user procurement authority. CAGRs were derived from trend extrapolation of specification escalation patterns and replacement cycle compression, with inputs from deepwater project sanctioning timelines and pre-salt development schedules.
Inputs from operator engineering staff and drilling contractor technical specifications were available through the study window; gaps in real-time alloy commodity pricing and confidential contract terms introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding EPA enforcement continuity, ANP local content stability, and nickel supply chain resilience. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Desalter Market
Oil & Gas
Drilling Services Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Well Cementing Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Wellhead System Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market