
 Wind Power Composite Market | 2026-2036
Wind Power Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Composite Market Insights
The EU Green Deal is expanding procurement criteria for wind energy infrastructure across European member states. LM Wind Power leverages its integrated blade manufacturing network to sustain long-term supply agreements with major European OEMs. Siemens Gamesa Renewable Energy anchors its competitive position through advanced resin transfer molding capabilities that reduce blade weight.
Wind power composites encompass fiber-reinforced polymer materials engineered for structural components in utility-scale turbines, typically incorporating glass or carbon fibers within epoxy or thermoplastic matrices to achieve specific strength-to-weight ratios exceeding 200 MPa per density unit. These materials primarily serve to extend rotor diameters beyond 120 meters while maintaining fatigue resistance across 25-year operational lifespans. Glass fiber formulations dominate current blade production due to cost efficiency, though carbon fiber segments command premium positioning in offshore applications where load-bearing demands intensify. Thermoplastic resins represent the fastest-growing material category as recyclability mandates from European regulators reshape end-of-life obligations for blade manufacturers.
The European Commission's F-Gas Regulation and REACH framework restrict fluorinated compounds and hazardous substances in composite manufacturing processes, compelling reformulation of resin systems across the supply chain. China's GB standards and MIIT directives establish domestic content thresholds that influence material sourcing decisions for turbines deployed within its territory. Stakeholders must monitor evolving extended producer responsibility legislation across multiple jurisdictions as blade decommissioning volumes accumulate.
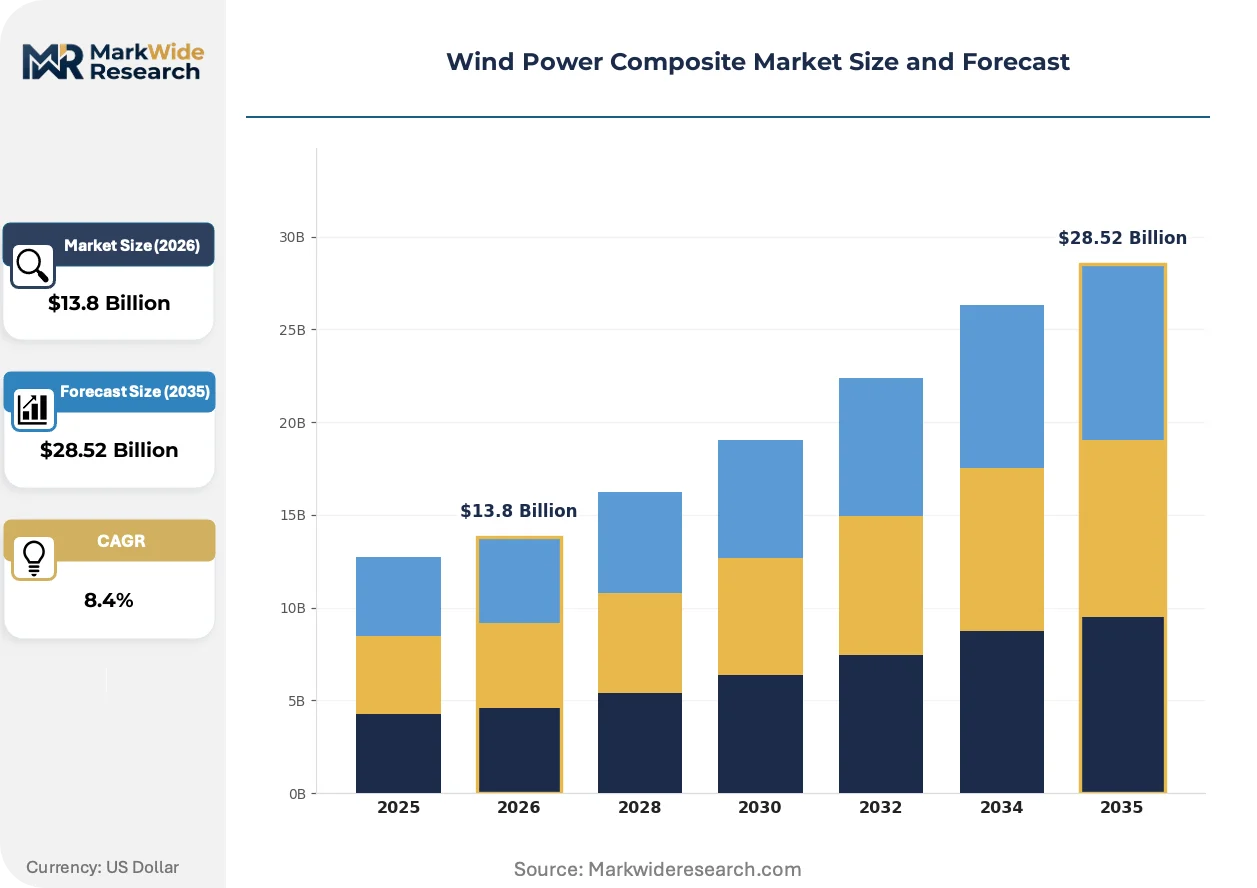
Market Dynamics
Offshore wind farm developers are scaling orders for larger turbine blades, forcing composite manufacturers to retool production lines for components exceeding 120 meters in length. This dimensional escalation is concentrating procurement among suppliers capable of integrated design-to-manufacture workflows.
Growth Catalysts
- EU Green Deal domestic content mandates:Member states are tightening local sourcing requirements for renewable energy infrastructure, creating captive demand for European-based blade manufacturing capacity.
- Carbon fiber adoption in offshore towers:Load-bearing demands in marine environments are accelerating substitution of glass fiber with carbon fiber reinforced polymers for enhanced fatigue resistance.
- China's state-backed installation surge:Central procurement schedules under MIIT directives are concentrating composite demand within domestic supply chains serving utility-scale wind parks.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations are compressing margins for blade manufacturers locked into fixed-price supply agreements.
- European supply concentration:Three integrated OEMs control over 70% of blade molding capacity in Western Europe, creating bottleneck risk for independent turbine assemblers.
- Thermoplastic recycling infrastructure gaps:End-of-life blade volumes are accumulating faster than pyrolysis or mechanical recycling capacity can absorb, exposing producers to extended producer liability.
Strategic Opportunities
- India's coastal wind zones:Untapped offshore sites along Gujarat and Tamil Nadu coastlines offer first-mover positioning for composite suppliers establishing local molding facilities.
- Recyclability-as-a-service models:Blade decommissioning mandates under evolving EU waste directives are creating revenue streams for composite processors offering closed-loop material recovery.
- Automated fiber placement convergence:Robotics integration with thermoplastic tape laying is enabling high-throughput production of complex aerodynamic profiles previously requiring manual layup.
Industry Challenges
- Non-destructive testing technician scarcity:Ultrasonic and thermographic inspection expertise for 25-year fatigue certification is concentrated among aging specialists with limited training pipeline replacement.
- Tooling amortization compression:Blade mold sets requiring 18-month capital recovery cycles face stranded asset risk as design iterations accelerate beyond 24-month product lifecycles.
- REACH compliance documentation burden:ECHA substance registration requirements for novel resin formulations are extending qualification timelines by 8-14 months versus legacy epoxy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Composite Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blades, Towers, Nacelles, Composites End User: Utilities, Independent Power Producers, OEMs, Project Developers Material: Glass Fiber, Carbon Fiber, Resin, Thermoplastics Technology: Horizontal Axis, Vertical Axis, Direct Drive, Gearbox |
| Companies Covered | TPI Composites, LM Wind Power, Siemens Gamesa Renewable Energy, Vestas Wind Systems, Hexcel Corporation, Toray Industries, Gurit Holding, Suzlon Energy, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Composite Market Trends and Innovations
Material science advances and manufacturing automation are converging to reshape blade economics. Three developments are restructuring competitive positioning across the value chain.
Thermoplastic resin systems are integrating carbon fiber reinforcements to enable welded blade joints that eliminate adhesive curing cycles. Offshore developers in the North Sea are specifying these materials for 15 MW+ turbine platforms. The technology is integrating in-house recycling loops that reduce end-of-life disposal costs by enabling material reprocessing at manufacturing sites.
REACH and the EU F-Gas Regulation are restricting fluorinated compounds in mold release agents and surface treatments. Composite manufacturers are reformulating resin systems to eliminate per- and polyfluoroalkyl substances from blade finishing processes. European blade producers are absorbing compliance costs through process reengineering while Asian exporters face market access barriers for non-conforming product lines.
Buyers are consolidating procurement through multi-year framework agreements that bundle blade supply with predictive maintenance services. Independent turbine operators are displacing spot-market purchasing with integrated supplier partnerships covering 20-year operational lifespans. This concentration is most visible in China's state-owned utility sector, where central procurement platforms are aggregating demand across provincial wind farm portfolios.
Wind Power Composite Market Segmentation
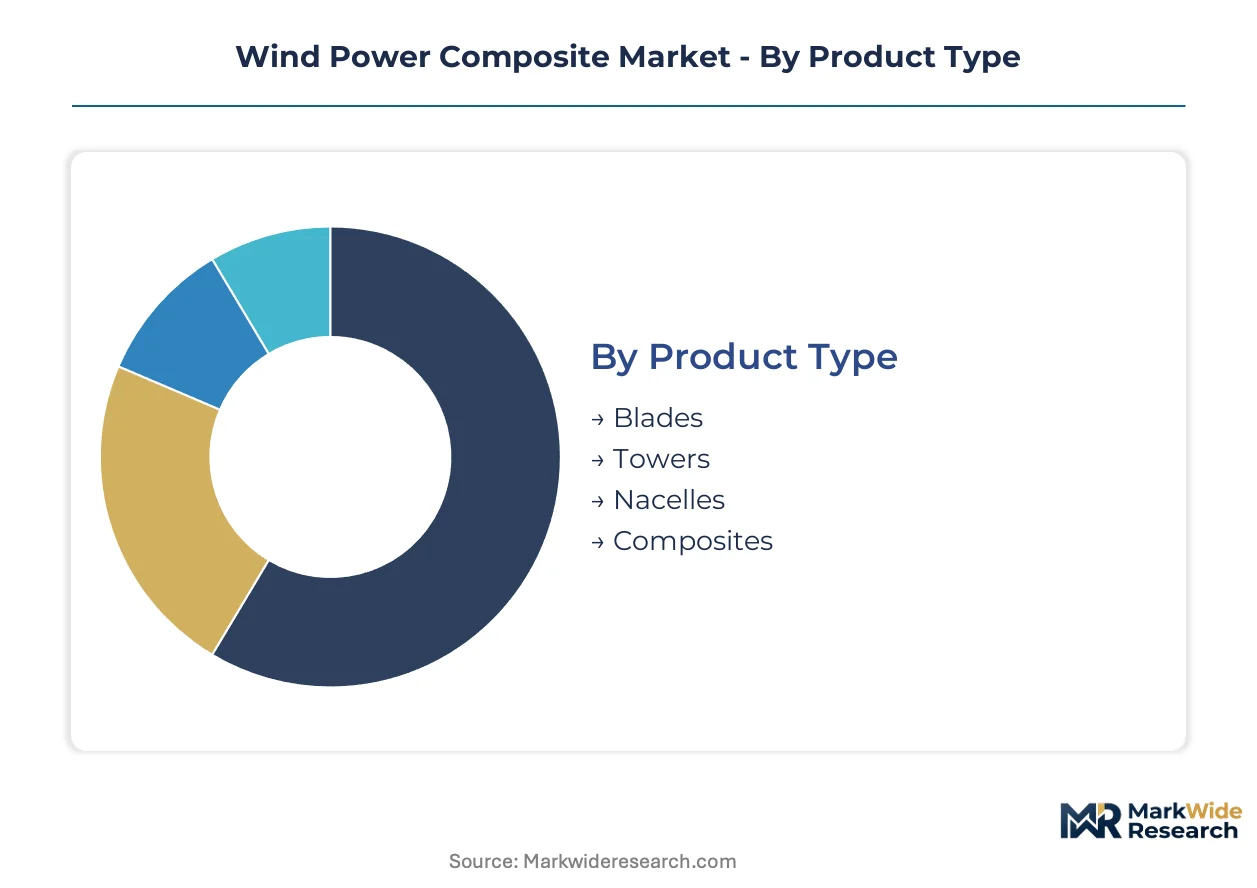
Wind power composite buyers diverge sharply by procurement scale, technical risk tolerance, and regulatory exposure. Segment-level strategies must align material selection with turbine scale, offshore versus onshore siting, and end-of-life compliance obligations across jurisdictions.
Product Type:
Buyers differentiate by component criticality, with blade investments dominating capital allocation and towers commanding extended lead times for marine-grade specifications.
- Blades:Fiber-reinforced polymer shells exceeding 120 meters incorporate glass or carbon fiber within epoxy or thermoplastic matrices to achieve strength-to-weight ratios above 200 MPa per density unit. Offshore developers in the North Sea and China's coastal provinces are scaling orders for 15 MW+ platforms, forcing retooling for integrated design-to-manufacture workflows.
- Towers:Tubular steel-concrete hybrid structures with composite access platforms and lightning protection systems. Load-bearing demands in marine environments are accelerating substitution with carbon fiber reinforced polymers for enhanced fatigue resistance across 25-year operational lifespans.
- Nacelles:Housing assemblies for drivetrain components, generators, and control systems with composite weatherproofing enclosures.
- Composites:Auxiliary structural elements including spinners, hub covers, and platform gratings serving secondary load-bearing functions.
Blades lead volumes today; towers are gaining share fastest as offshore installations proliferate.
End User:
Procurement concentration varies by balance sheet capacity, with state-backed entities aggregating demand across portfolios and independent operators seeking supply security through long-term partnerships.
- Utilities:Vertically integrated power generators with captive procurement platforms spanning provincial wind farm portfolios. China's state-owned utilities under MIIT directives dominate composite demand through central procurement schedules serving utility-scale installations.
- Independent Power Producers:Non-utility developers financing projects through power purchase agreements. European IPPs are displacing spot-market purchasing with integrated supplier partnerships covering 20-year operational lifespans to secure blade supply with predictive maintenance services.
- OEMs:Turbine manufacturers with in-house blade molding capacity or captive supply agreements. Three integrated OEMs control over 70% of blade molding capacity in Western Europe, creating bottleneck risk for independent turbine assemblers.
- Project Developers:Early-stage entities securing permits and financing prior to construction handoff.
Utilities anchor current procurement volumes; independent power producers are expanding their share most rapidly through bundled service contracts.
Material:
Cost-performance tradeoffs and recyclability mandates are restructuring material selection hierarchies across the value chain.
- Glass Fiber:E-glass and S-glass formulations dominate current blade production due to cost efficiency in onshore applications. Domestic content thresholds under China's GB standards and MIIT directives influence sourcing decisions for turbines deployed within its territory.
- Carbon Fiber:High-modulus reinforcements commanding premium positioning in offshore applications where load-bearing demands intensify. The EU Green Deal's domestic content mandates are tightening local sourcing requirements, creating captive demand for European-based carbon fiber processing capacity.
- Resin:Epoxy systems currently standard for blade infusion processes, though petrochemical feedstock fluctuations compress margins for manufacturers locked into fixed-price supply agreements.
- Thermoplastics:Polyamide and polypropylene matrices enabling welded joints and in-house recycling loops. REACH and the EU F-Gas Regulation are restricting fluorinated compounds, compelling reformulation of resin systems across the supply chain.
Glass fiber retains volume leadership; thermoplastics are climbing the fastest as recyclability mandates reshape end-of-life obligations.
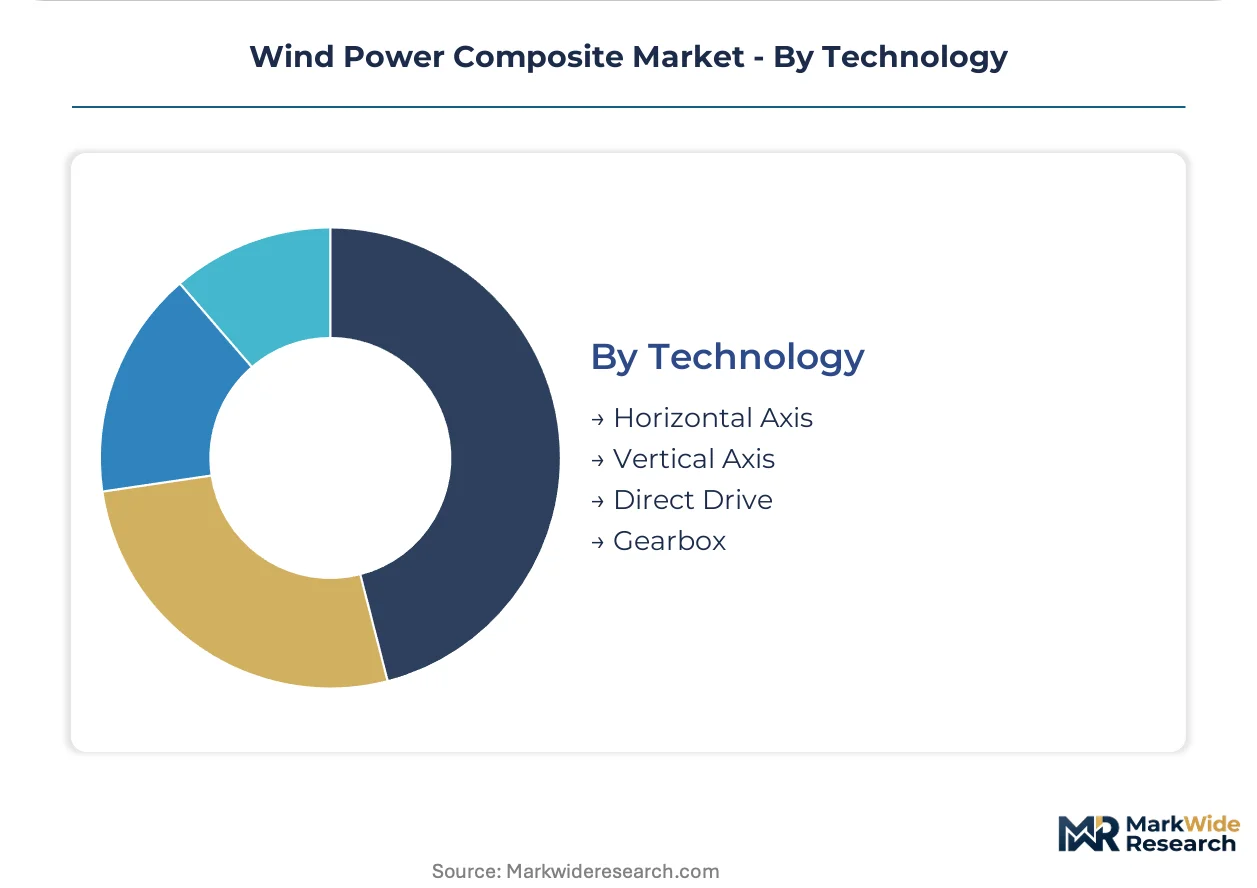
Technology:
Turbine architecture selection determines composite stress profiles, drivetrain complexity, and maintenance access requirements.
- Horizontal Axis:Upwind and downwind rotor configurations representing the dominant utility-scale design. Automated fiber placement convergence with thermoplastic tape laying is enabling high-throughput production of complex aerodynamic profiles previously requiring manual layup.
- Vertical Axis:Darrieus and Savonius designs for distributed generation and urban installations. India's coastal wind zones along Gujarat and Tamil Nadu offer first-mover positioning for composite suppliers establishing local molding facilities serving smaller-scale vertical axis deployments.
- Direct Drive:Permanent magnet generators eliminating gearbox components, increasing nacelle mass and composite housing requirements.
- Gearbox:Conventional drivetrain architectures with higher rotational speeds and reduced torque loading on composite structures.
Horizontal axis configurations dominate installed capacity; vertical axis designs are expanding most quickly in distributed generation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized blade molding technicians cluster in Denmark and northern Germany where decades of offshore wind development created concentrated expertise pools. These workforce concentrations anchor composite supply chains serving European and Asian turbine OEMs.
China
State-backed utility procurement under MIIT directives drives blade demand across coastal provinces. GB standards enforce domestic content thresholds that reshape material sourcing for turbines deployed within national territory. Jiangsu and Guangdong manufacturing corridors host integrated molding facilities supplying 15 MW+ offshore platforms.
Germany
REACH compliance documentation extends resin qualification timelines, compressing product development cycles for blade manufacturers. The EU Green Deal tightens local sourcing mandates, creating captive demand for carbon fiber processing capacity in northern industrial zones. Bremen and Hamburg harbor clusters anchor North Sea offshore supply chains.
United States
IRA production tax credits accelerate utility-scale wind farm development across Great Plains states. FERC interconnection queue reforms aim to reduce project completion delays affecting blade procurement schedules. Iowa and Texas manufacturing hubs retool for 120-meter+ blade production serving domestic and export markets.
India
CEA coastal wind zone notifications unlock Gujarat and Tamil Nadu sites for first offshore installations. BIS certification requirements influence composite material specifications for turbines deployed in cyclone-prone regions. Mundra and Chennai industrial corridors attract blade molding investments from European and Asian suppliers.
Denmark
EU F-Gas Regulation restricts fluorinated compounds in mold release agents used at legacy blade facilities. Advanced resin transfer molding expertise concentrates in Aarhus and Odense industrial clusters. These technical centers export process engineering to emerging wind markets in Poland and the Baltic states.
Wind Power Composite Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the wind power composite value chain. Integrated turbine OEMs with captive blade molding capacity control dominant share of European supply, while independent fabricators serve spot-market demand in Asia-Pacific growth corridors. Three strategic archetypes define competitive positioning: vertically integrated turbine manufacturers, specialized blade engineering houses, and materials-focused compounders supplying resin and fiber systems. Dominant competitive moves include capacity expansion for 120-meter+ blade formats and strategic partnerships bundling blade supply with predictive maintenance services.
Among Denmark-based engineering specialists, LM Wind Power and Vestas Wind Systems occupy positions within the integrated OEM tier, leveraging decades of North Sea offshore deployment experience. TPI Composites exemplifies the independent fabricator archetype, serving multiple turbine OEMs through distributed manufacturing networks. These three anchors illustrate how geographic proximity to major offshore wind zones shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| TPI Composites |
| LM Wind Power |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| Hexcel Corporation |
| Toray Industries |
| Gurit Holding |
| Suzlon Energy |
| Teijin Limited |
| Others |
Pricing and Supply Chain Analysis
State-owned utility procurement platforms in China aggregate blade demand across provincial wind farm portfolios, anchoring contract-based long-term offtake pricing that locks in composite supply years ahead of installation. This buyer concentration forces independent fabricators into fixed-price agreements that compress margins when epoxy resin feedstock costs fluctuate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates offshore carbon fiber blades from onshore glass fiber units from auxiliary nacelle components. Price differentiation rests on certification grade for 25-year fatigue resistance and volume scale across utility-scale procurement schedules. Cost compression in standard-tier glass fiber blades is intensifying because European OEMs face REACH compliance documentation burdens extending qualification timelines. Independent power producers exhibit highest price sensitivity due to project finance constraints, while state-backed utilities absorb premium pricing for integrated predictive maintenance bundles.
Supply Chain Analysis
Freight costs for 120-meter+ blade segments dominate landed cost calculations, compelling molding facility placement within 500 kilometers of installation sites. Supply concentrates in China, Germany, and Denmark where specialized technician pools and port infrastructure align with offshore deployment zones. Raw material dependencies center on carbon fiber from Toray Industries and Hexcel Corporation, epoxy resin systems from petrochemical feedstocks, and thermoplastic tapes for automated fiber placement. Single-source vulnerability in carbon fiber supply creates bottleneck risk when Japanese producers face production constraints. Distribution runs through turbine OEM captive networks and independent fabricator direct contracts to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind power composite manufacturing offers geographic-arbitrage returns between European REACH compliance costs and Chinese domestic content incentives, with blade molding capacity relocation yielding margin expansion of 400-600 basis points for operators serving Asian offshore zones.
For Market Incumbents: Acquire automated fiber placement robotics capabilities to reduce manual layup labor intensity and accelerate throughput for 15 MW+ blade formats. Defend against thermoplastic substitution threats by securing exclusive resin formulation partnerships with European compounders ahead of recyclability mandate enforcement. Build backward integration into carbon fiber pre-preg processing to capture margin currently flowing to Japanese suppliers. For New Entrants and Emerging Players: Capture India's coastal wind zones along Gujarat and Tamil Nadu where CEA notifications unlock first offshore installations and BIS certification requirements create barrier windows for early movers. Establish local molding facilities serving state utility procurement schedules before European and Chinese incumbents complete capacity buildout. Lead with thermoplastic blade joint technology offering welded construction and in-house recycling loops that differentiate against epoxy-dependent legacy producers. For Investors and Strategic Acquirers: Turbine OEMs with captive blade capacity are the most active acquirers in this space, seeking to secure supply chain control amid offshore scaling. Long-term viability across the analysis window favors compounders with thermoplastic resin platforms and recyclability-as-a-service revenue streams. Watch for MIIT directive modifications to domestic content thresholds as the primary inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | Robotics integration with thermoplastic tape laying enables 120-meter+ blade production at throughput rates previously unattainable with manual layup. |
| Thermoplastic Recycling Infrastructure Buildout | Closed-loop material recovery systems at manufacturing sites reduce end-of-life disposal costs under evolving EU waste directives. |
| Carbon Fiber Pre-Preg Backward Integration | In-house processing of high-modulus reinforcements captures margin from Japanese suppliers serving North Sea offshore demand. |
| India Coastal Manufacturing Footprint | Local molding facilities in Gujarat and Tamil Nadu position suppliers for CEA-notified offshore zones before incumbent saturation. |
| Predictive Maintenance Service Bundling | 20-year operational lifespan contracts with European IPPs displace spot-market purchasing and lock in blade replacement revenue streams. |
Research Methodology
Direct dialogue with blade manufacturing plant managers, utility procurement officers at state-owned Chinese utilities, independent power producer project developers, and EPC contractors constructing North Sea offshore platforms grounded qualitative findings. Secondary validation drew from EIA wind installation databases, IEA renewable energy reports, FERC interconnection queue filings, and EU Green Deal implementation tracking. Bottom-up capacity assessments across 15 major blade molding facilities triangulated against top-down demand projections from national renewable energy targets.
Market size and growth trajectory outputs across the analysis window reflect segment-level modeling of blade, tower, nacelle, and auxiliary composite components by material type and turbine scale. CAGRs were derived from installed capacity forecasts, blade replacement schedules, and material intensity coefficients per megawatt of rated turbine capacity. Key inputs included offshore versus onshore siting mix, carbon fiber substitution rates in load-bearing applications, and thermoplastic resin adoption curves under recyclability mandates.
Underlying measurement precision varies by segment; offshore blade volumes carry tighter precision than emerging vertical axis distributed generation applications due to project announcement transparency. Forecasts reflect assumptions about MIIT directive continuity, REACH compliance timeline stability, and epoxy resin feedstock price normalization. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Turbine Scrap Market