
 Large Scale LNG Terminal Market | 2026-2036
Large Scale LNG Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Large Scale LNG Terminal Market Intelligence
Buyer concentration among power generation utilities is shifting toward fewer, larger offtakers seeking multi-decade supply security. Shell PLC leverages integrated trading desks to capture margin across liquefaction, shipping, and regasification. Cheniere Energy anchors North American export capacity with brownfield expansion at existing Gulf Coast sites. TotalEnergies SE competes through equity stakes in upstream gas fields tied to dedicated terminal capacity.
Large scale LNG terminals are cryogenic facilities engineered to receive, store, and regasify liquefied natural gas at temperatures below minus 162 degrees Celsius, with single-train liquefaction capacity typically exceeding five million tonnes per annum for export installations. Their primary purpose is to bridge geographically stranded gas reserves with demand centers lacking pipeline connectivity. Import terminals dominate existing installed base but export terminals represent the fastest-growing category as producer nations monetize stranded reserves. Floating Storage Regasification Units capture niche opportunities where onshore siting faces political or environmental opposition. Maritime bunkering applications are expanding fastest among end-use segments as IMO regulations tighten marine fuel sulfur limits.
The US Federal Energy Regulatory Commission governs siting and environmental review for coastal export facilities, while the EPA enforces methane performance standards under Clean Air Act authority. Europe's F-Gas Regulation and CSRD disclosure requirements are raising capital costs for terminals with unabated emissions profiles. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with long-term offtake contract structures.
Market Dynamics
Capital allocation in the Large Scale LNG Terminal Market is pivoting toward methane abatement infrastructure as the EU F-Gas Regulation and parallel EPA standards harden emission thresholds for new capacity. This regulatory compression is redrawing project economics and financing structures.
Growth Catalysts
- Power generation offtake:Japanese and South Korean utilities are locking multi-decade supply contracts. These commitments de-risk greenfield liquefaction investments.
- F-Gas Regulation:Europe's tightening methane leakage standards are accelerating terminal retrofits. Engineering procurement contracts now embed continuous emissions monitoring.
- US Gulf Coast corridor:Brownfield expansion at existing sites compresses permitting timelines. FERC precedent reduces environmental review uncertainty for adjacent capacity.
Market Restraints
- Nickel alloy supply concentration:Cryogenic storage tank fabrication depends on specialized 9% nickel steel from limited blast furnace capacity. Japanese and Korean mills command pricing premiums.
- Carbon border adjustment exposure:Unabated liquefaction trains face import tariff risk under EU CBAM implementation. Long-term offtake contracts lack standardized pass-through clauses.
- FSRU substitution:Floating Storage Regasification Units offer faster deployment where onshore siting faces political opposition. Coastal import markets are diverting capital from permanent terminals.
Strategic Opportunities
- Maritime bunkering infrastructure:IMO sulfur regulations are creating demand for LNG-fueled vessel refueling at hub ports. Singapore and Rotterdam are anchoring early network development.
- CCUS integration:Post-combustion capture at liquefaction trains qualifies for US IRA tax credits. Project sponsors are restructuring equity to capture 45Q benefits.
- Small-scale distribution:Bunkering and industrial off-grid supply in Southeast Asia lacks regasification access. Modular satellite terminals address stranded demand clusters.
Industry Challenges
- Cryogenic welding certification:Qualified 9% nickel welders command premium wages. Training pipeline lag extends construction schedules.
- Integrated control system complexity:Terminal automation must interface with vessel loading arms, storage inventory, and pipeline nomination systems. Legacy SCADA architectures require expensive retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Scale LNG Terminal Market |
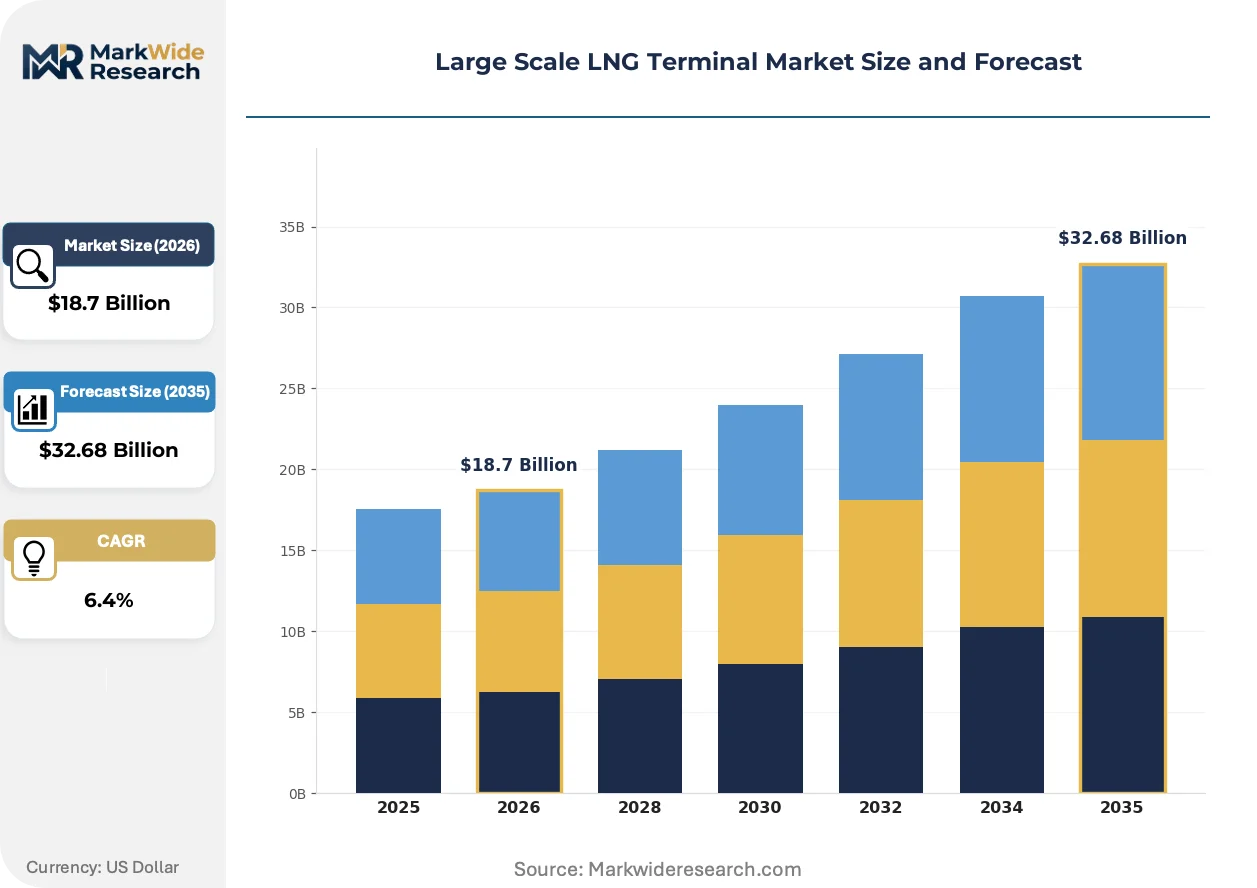
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Import Terminals, Export Terminals, Re-Export Terminals, Floating Storage Regasification Units Technology: Double Mixed Refrigerant, Cascade Cycle, Single Mixed Refrigerant, Expander Cycle, Open Rack Vaporizer Application: Power Generation, Residential Supply, Commercial Usage, Industrial Fuel, Maritime Bunkering End User: Utility Companies, Marine Transport Firms, Petrochemical Manufacturers, Energy Traders |
| Companies Covered | Shell PLC, ExxonMobil Corporation, Chevron Corporation, Linde plc, TotalEnergies SE, Petronas, Cheniere Energy, BP PLC, Technip Energies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Scale LNG Terminal Market Strategic Shifts & Innovations
Modular liquefaction technology and digital twin deployment are compressing project development cycles. These advances are redistributing competitive advantage toward engineering firms with standardized design libraries.
Small-scale modular liquefaction trains are decentralizing capacity deployment away from mega-train greenfield sites. Remote gas field operators in East Africa and the Eastern Mediterranean are adopting these units to monetize stranded reserves without pipeline dependency. This technology is decentralizing the traditional hub-and-spoke supply architecture that concentrated investment along established corridors.
The EPA's methane performance standards under Clean Air Act authority are mandating optical gas imaging and continuous monitoring at compressor stations. Liquefaction project sponsors must budget for leak detection hardware and third-party verification protocols. Export terminals targeting European offtake are responding by embedding certified low-methane supply clauses into term sheets.
Utility procurement committees are unbundling engineering, procurement, and construction contracts from long-term operations and maintenance agreements. This separation allows power generators to negotiate fuel supply and terminal access independently. The pattern is most visible in Japanese buyer negotiations for US Gulf Coast capacity, where trading desk expertise now shapes contracting structures.
Large Scale LNG Terminal Market Segmentation
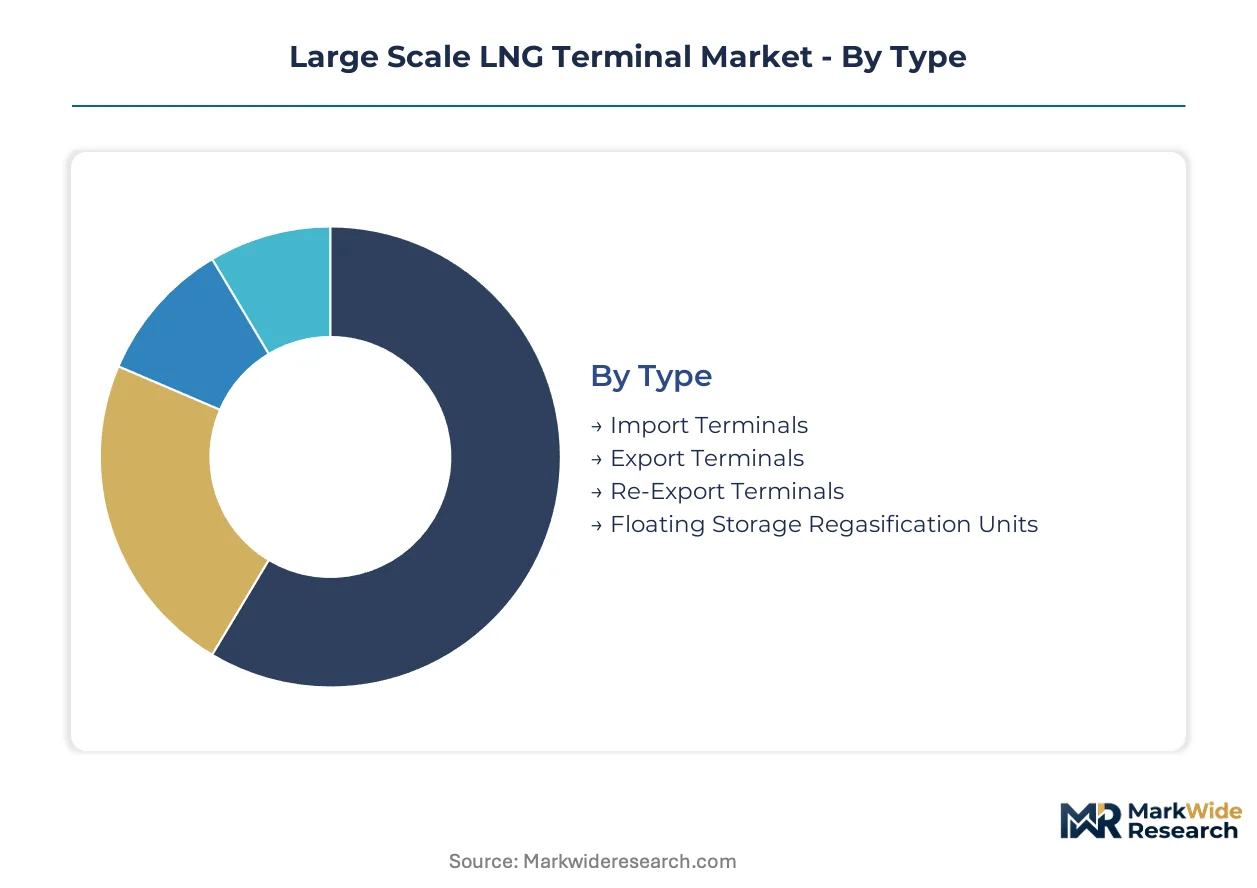
Cryogenic infrastructure investment follows distinct technical and commercial logics across terminal configurations. Each segmentation axis reveals divergent capital intensity, regulatory exposure, and offtake risk profiles that shape project finance structures.
Type:
Terminal classification by trade flow direction determines siting constraints, storage scale, and vessel traffic patterns.
- Import Terminals:Onshore regasification facilities with cryogenic storage tanks receiving carrier-delivered LNG for pipeline injection. Japanese and South Korean utility procurement committees dominate contracting activity as they seek supply security through dedicated berth access.
- Export Terminals:Liquefaction trains converting pipeline gas to LNG for seaborne export, typically sited near stranded reserves or pipeline interconnections. Brownfield expansion along the US Gulf Coast compresses permitting timelines through FERC precedent.
- Re-Export Terminals:Hub facilities enabling cargo redirection without regasification, capturing arbitrage between Atlantic and Pacific basin pricing. Singapore and Rotterdam anchor network development for this intermediary function.
- Floating Storage Regasification Units:Offshore vessels combining storage and vaporization where onshore siting faces political opposition. Bangladesh and Pakistan have deployed FSRUs to bypass land acquisition disputes.
Mature deployment sits with Import Terminals. Newer deployment is concentrated in Export Terminals.
Technology:
Refrigeration cycle selection governs energy efficiency, feed gas flexibility, and equipment count.
- Double Mixed Refrigerant:Dual-loop propane and methane-ethane mixtures optimizing thermodynamic efficiency across variable ambient temperatures. Qatari mega-trains employ this configuration for baseload scale.
- Cascade Cycle:Sequential propane-ethylene-methane cooling stages delivering high purity with complex equipment footprint. US Gulf Coast projects favor this proven architecture for financing certainty.
- Single Mixed Refrigerant:Simplified loop reducing compressor count and maintenance burden. Modular deployments in East Africa adopt this technology for stranded field monetization.
- Expander Cycle:Turboexpander-driven cooling for nitrogen-rich or lean gas feeds. Remote Arctic developments leverage this tolerance for feed gas variability.
- Open Rack Vaporizer:Seawater heat exchange systems dominating import terminal regasification. Japanese coastal facilities deploy this mature technology for reliability.
Proven reliability sits with Cascade Cycle. Fastest capacity addition is occurring in Single Mixed Refrigerant.
Application:
End-use destination shapes storage sizing, sendout flexibility, and seasonal demand patterns.
- Power Generation:Baseload and peaking gas turbine fuel requiring high-pressure pipeline injection and rapid ramp capability. Japanese utilities are locking multi-decade terminal access agreements.
- Residential Supply:Seasonal heating demand with peak winter sendout requirements driving storage tank sizing. South Korean city gas distributors anchor this segment.
- Commercial Usage:Distributed heating and cooling loads with moderate pressure requirements. Urban regasification terminals in Spain and Italy serve this demand cluster.
- Industrial Fuel:Process heat and feedstock for ceramics, glass, and metallurgy. Indian fertilizer manufacturers represent concentrated offtake risk in this category.
- Maritime Bunkering:LNG-fueled vessel refueling at hub ports responding to IMO sulfur regulations. Singapore and Rotterdam are anchoring early network development for this expanding use case.
Contracted volume sits with Power Generation. Steepest expansion trajectory is occurring in Maritime Bunkering.
End User:
Counterparty credit quality and procurement sophistication determine terminal financing terms.
- Utility Companies:Investment-grade power generators with long-term offtake capacity and integrated pipeline networks. Japanese and South Korean utilities dominate greenfield liquefaction contracting.
- Marine Transport Firms:Shipping lines and vessel operators securing bunkering infrastructure under decarbonization mandates. Mediterranean and Baltic port authorities are licensing dedicated berths.
- Petrochemical Manufacturers:Feedstock buyers with process-specific purity requirements and interruptible demand profiles. US Gulf Coast ethylene producers anchor this segment.
- Energy Traders:Merchant offtakers without physical pipeline assets, requiring storage and reload flexibility. Shell PLC and TotalEnergies SE trading desks capture margin across this category.
Credit-backed demand sits with Utility Companies. Merchant risk concentration is expanding fastest among Energy Traders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stranded gas reserves in Qatar, Australia, and the US Permian Basin anchor liquefaction investment geography. Pipeline interconnections, maritime chokepoint proximity, and regulatory clarity determine terminal siting economics across producer and consumer nations.
United States
Gulf Coast brownfield expansion compresses FERC permitting timelines at existing sites. The EPA enforces methane performance standards under Clean Air Act authority for new liquefaction capacity. Cheniere Energy anchors export infrastructure development across Louisiana and Texas coastal corridors.
Qatar
North Field expansion underpins mega-train liquefaction scaling toward expanded Asian offtake. The national petroleum regulator mandates continuous emissions monitoring for all new cryogenic infrastructure. Ras Laffan Industrial City concentrates engineering procurement and specialized welding certification programs.
Japan
Power generation utilities lock multi-decade terminal access agreements for baseload gas turbine fuel. METI oversees siting approvals and safety inspections for coastal regasification facilities. Chubu Electric and Tokyo Gas anchor demand concentration across the Pacific coastal industrial belt.
South Korea
KOGAS procurement committees negotiate integrated liquefaction and shipping contracts for supply security. The Ministry of Trade, Industry and Energy enforces methane leakage standards aligned with EU F-Gas Regulation benchmarks. Incheon and Pyeongtaek host the densest concentration of cryogenic storage tank fabrication yards.
Germany
Industrial fuel substitution drives floating and onshore regasification deployment following pipeline supply disruption. The EU F-Gas Regulation and national implementation through BImSchG tighten methane emission thresholds for terminal approvals. Wilhelmshaven and Brunsbüttel anchor North Sea import infrastructure development.
Large Scale LNG Terminal Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular liquefaction and CCUS integration pathways. The market structures around integrated majors with captive upstream reserves, independent terminal operators with brownfield expansion rights, and engineering contractors with proprietary refrigeration cycle technology. Competitive dynamics center on liquefaction train scale economies and offtake contract duration. Capacity expansion and strategic partnerships dominate competitive moves as players secure feedstock supply and berth access.
Among integrated energy majors, Shell PLC and TotalEnergies SE exemplify trading-anchored terminal strategies that capture margin across liquefaction, shipping, and regasification. Cheniere Energy occupies a position as the scale-driven independent focused on Gulf Coast brownfield expansion. These three entities represent distinct archetypes: the integrated trading house, the upstream-integrated major, and the pure-play liquefaction developer.
| Leading Market Players |
|---|
| Shell PLC |
| ExxonMobil Corporation |
| Chevron Corporation |
| Linde plc |
| TotalEnergies SE |
| Petronas |
| Cheniere Energy |
| BP PLC |
| Technip Energies |
| Others |
Cost & Logistics Intelligence
9% nickel steel from Japanese and Korean blast furnaces feeds through cryogenic storage tank fabricators to terminal developers, with alloy premiums compressing margins for contractors lacking long-term mill contracts. This input concentration creates pricing power asymmetry between integrated majors with captive steel procurement and independent developers exposed to spot alloy markets.
Pricing Analysis
Warranty and commissioning service bundling separates integrated EPC providers from unbundled engineering contractors competing on capital cost alone. Long-term offtake contracts employ take-or-pay structures indexed to Henry Hub or JKM benchmarks, with creditworthy utility buyers securing price discounts unavailable to merchant traders. Cost compression in modular liquefaction trains is intensifying as standardized designs reduce engineering hours. Price sensitivity concentrates among independent power producers lacking integrated trading desks, while national oil companies prioritize supply security over unit economics.
Supply Chain Analysis
Cryogenic compressor supply rests on German and Japanese precision engineering houses with multi-year order backlogs. Specialized 9% nickel steel, brazed aluminum heat exchangers, and magnetic bearing turbomachinery constitute critical path items with limited qualified suppliers. Single-source vulnerability in cryogenic welding certification programs extends construction schedules when qualified labor pools exhaust. Distribution runs through EPC contractors with proprietary refrigeration cycle technology licensing downstream to project sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated majors with captive upstream reserves and brownfield expansion rights, as F-Gas Regulation compliance costs force weaker developers toward asset sales.
For Market Incumbents: Cement feedstock supply security through equity stakes in Permian Basin or Eastern Mediterranean gas fields before greenfield liquefaction FID. Expand Gulf Coast brownfield capacity at existing FERC-approved sites to compress permitting timelines against emerging modular competitors. Prioritize CCUS integration to capture IRA 45Q tax credits and secure European offtake preference. For New Entrants and Emerging Players: Begin with small-scale modular liquefaction deployments in stranded East African gas fields where pipeline economics fail. Target maritime bunkering infrastructure at Singapore and Rotterdam where port authority licensing creates defendable positions. Pursue satellite terminal opportunities in Southeast Asian industrial clusters lacking regasification access. For Investors and Strategic Acquirers: FSRU deployment acceleration in Germany and Bangladesh is the leading indicator that floating solutions are capturing permanent market share from onshore terminals. Long-term viability favors developers with integrated carbon capture pathways and certified low-methane supply chains. Watch for EU CBAM implementation triggering contract renegotiation clauses in Atlantic basin offtake agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Capacity Expansion | FERC precedent at existing Gulf Coast sites compresses environmental review timelines for adjacent trains. |
| CCUS Technology Integration | Post-combustion capture qualifies for IRA tax credits and satisfies EU methane performance standards. |
| Long-term Offtake Contracting | Japanese utility procurement committees de-risk greenfield investments through multi-decade supply commitments. |
| Floating Regasification Deployment | FSRUs bypass land acquisition disputes in Bangladesh and Pakistan coastal markets. |
| Maritime Bunkering Infrastructure | Singapore and Rotterdam port authorities anchor IMO-compliant LNG refueling network development. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with LNG project developers, EPC contracting officers, utility procurement managers, and shipping line fuel buyers. FERC environmental impact statements, EPA methane performance standard dockets, and EU F-Gas Regulation implementation guidance provided regulatory boundary conditions. Bottom-up capacity buildout tracking triangulated against top-down demand modeling from power generation and industrial fuel substitution forecasts.
Segment-level modeling disaggregated terminal type, refrigeration cycle technology, and end-use application across the projection horizon. CAGRs derived from facility-by-facility construction timeline analysis and offtake contract commencement dates. Modeled inputs included liquefaction train capacity factors, regasification sendout utilization rates, and maritime bunkering throughput assumptions at hub ports.
Underlying measurement precision varies by segment; export terminal greenfield tracking carries tighter precision than FSRU deployment forecasting. Projections reflect assumptions on regulatory enforcement intensity and carbon border adjustment mechanism scope. EU F-Gas Regulation implementation pace, IRA credit permanence, and IMO marine fuel sulfur enforcement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Mud Balance Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Netherlands LNG Bunkering Market