
 Global Completion Equipment and Services Market | 2026-2036
Global Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Completion Equipment and Services Market Analysis
The EPA methane emissions rules for new and modified oil and gas facilities is pivoting completion equipment procurement toward leak-tight wellhead assemblies and vapor recovery units. Schlumberger leverages integrated well construction portfolios to sustain premium positioning in intelligent completions. Halliburton anchors North American pressure pumping through vertical control of proppant logistics and frac fleet deployment. Baker Hughes differentiates via turbomachinery and electrification solutions for offshore tiebacks.
Completion equipment and services encompass the hardware, fluids, and technical services required to prepare a drilled well for hydrocarbon production, including packers rated to 15,000 psi, multi-stage fracturing tools, and specialized brines for reservoir compatibility. This apparatus enables zonal isolation, controlled fracture initiation, and optimized inflow from target formations. Packers and frac equipment command the largest share of product revenues due to repeat consumption in horizontal shale programs. Smart well technology and monitoring systems represent the fastest-expanding technology category as operators pursue remote choke control and real-time production diagnostics. Onshore operations absorb the dominant application volume, though deepwater drilling commands substantially higher equipment values per wellbore.
The US EPA and state-level regulators such as the Texas Railroad Commission shape equipment specifications through methane intensity thresholds and casing integrity mandates. API standards govern material grades and pressure ratings for wellhead and downhole components. The EU Green Deal and national carbon border mechanisms are beginning to filter into offshore project sanctioning criteria. Stakeholders must weigh capital allocation between conventional fleet maintenance and digital-physical integration platforms that promise operating expenditure reductions.
Market Dynamics
The EPA methane emissions rules are compressing procurement cycles toward leak-tight wellhead assemblies and vapor recovery units, forcing operators to retire legacy equipment ahead of depreciation schedules.
Growth Catalysts
- API 19AC wellhead standards:Tightening material certification requirements across the Permian Basin and other major producing regions are mandating equipment upgrades that expand addressable market volume.
- Unconventional shale operators:Horizontal drilling programs in West Texas and southeastern New Mexico are driving repeat consumption of multi-stage fracturing tools and high-pressure packers.
- Electrification of offshore tiebacks:Turbomachinery and subsea power distribution systems are opening new equipment categories for deepwater developments in the Gulf of Mexico and Brazil's pre-salt fields.
Market Restraints
- Specialty alloy supply concentration:Forged components rated to 15,000 psi depend on a limited supplier base concentrated in Germany and Japan, creating input bottlenecks.
- Proppant logistics volatility:Northern White Sand mining concentration in Wisconsin and Minnesota exposes pressure pumping operations to rail freight cost swings and weather disruptions.
- EU carbon border mechanisms:The EU Green Deal's emerging offshore project criteria are extending sanctioning timelines for North Sea developments, deferring equipment orders.
Strategic Opportunities
- Remote choke control systems:Smart well technology convergence with real-time production diagnostics is creating premium pricing power in the Norwegian Continental Shelf and Australian offshore basins.
- Argentina Vaca Muerta:Underpenetrated shale formations are attracting capital commitments for pad drilling programs that will require imported completion hardware and technical services.
- US Inflation Reduction Act methane fees:The IRA's emissions-based penalties are accelerating replacement demand for vapor recovery units and sealed wellhead configurations.
Industry Challenges
- Downhole electronics reliability:Permian Basin operators report premature failure rates in smart well sensors deployed in high-temperature, high-pressure formations, eroding confidence in remote monitoring value propositions.
- Cross-certification complexity:Equipment qualified to API standards requires redundant testing for NORSOK offshore deployment, extending time-to-revenue for multi-basin service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Completion Equipment and Services Market |
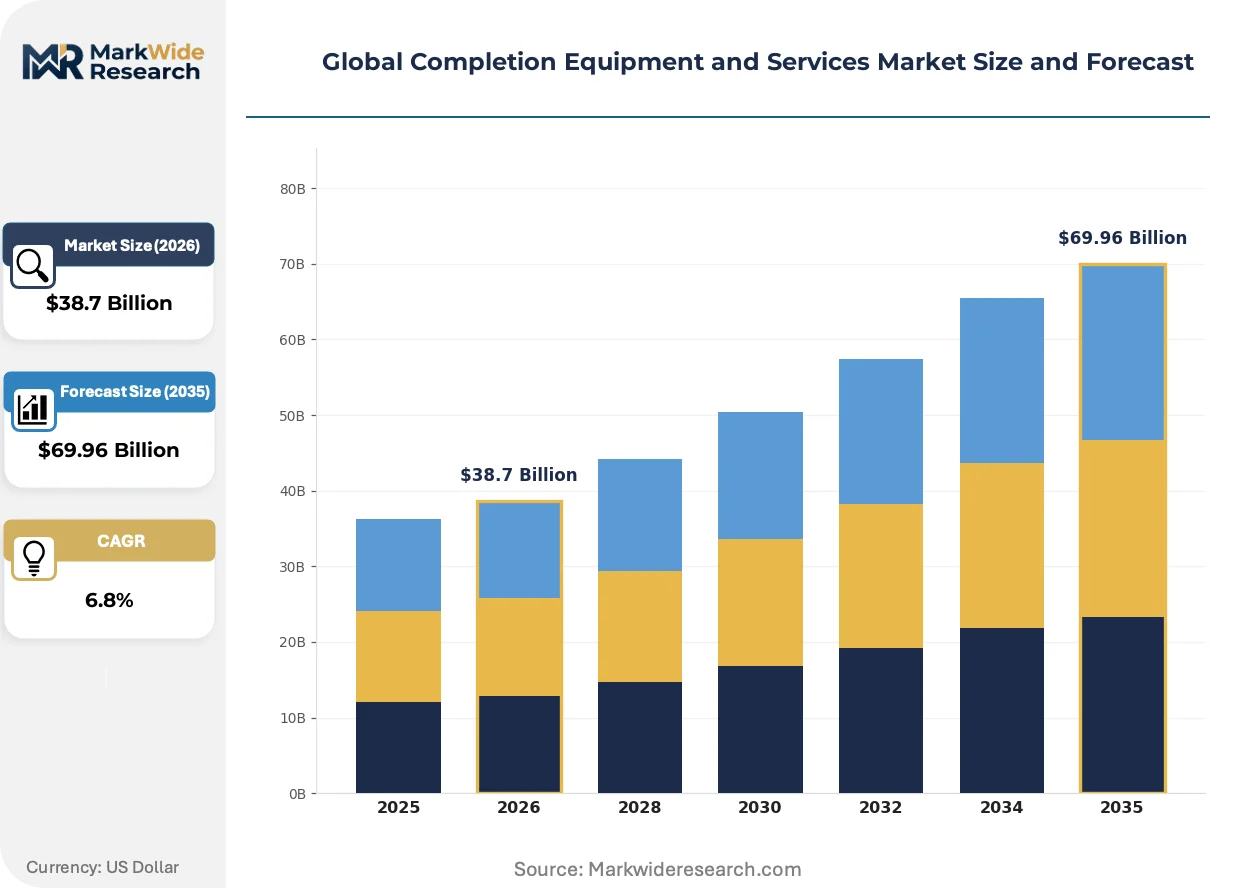
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packers, Frac Equipment, Tubing, Completion Fluids Technology: Smart Well Technology, Artificial Lift, Composite Materials, Monitoring Systems End User: Independent Operators, National Oil Companies, Service Companies, Oilfield Contractors Application: Onshore Operations, Offshore Operations, Deepwater Drilling, Shale Gas Extraction |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford International, National Oilwell Varco, TechnipFMC, Aker Solutions, Superior Energy Services, Oceaneering International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Completion Equipment and Services Market Emerging Trajectories
Intelligent completion systems are compressing the traditional separation between drilling and production operations, enabling real-time reservoir management that was previously technically inaccessible.
Automated frac fleet coordination platforms are automating proppant delivery scheduling, blender sequencing, and pump synchronization across multi-well pads. Permian Basin operators with 50-plus well programs are deploying these systems to reduce non-productive time between stages. The technology is automating manual dispatch decisions that previously required 24-hour command center staffing, compressing labor cost structures while improving stage consistency.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon use in offshore platform refrigeration and gas processing modules. Equipment suppliers serving North Sea developments are retrofitting turbomachinery with alternative working fluids and lower-global-warming-potential seal technologies. Subsea compression projects in Norway and the UK are absorbing the highest compliance costs, with operators selecting vendors based on demonstrated emissions certification rather than historical relationships.
Integrated service contracts are displacing discrete equipment procurement in North American shale plays. Operators are bundling wellhead supply, installation, and post-completion monitoring under single-vendor arrangements that transfer performance risk. The model is most visible among supermajors with standardized pad development programs in the Permian, where equipment uptime guarantees now determine contract awards more than unit pricing.
Global Completion Equipment and Services Market Segmentation
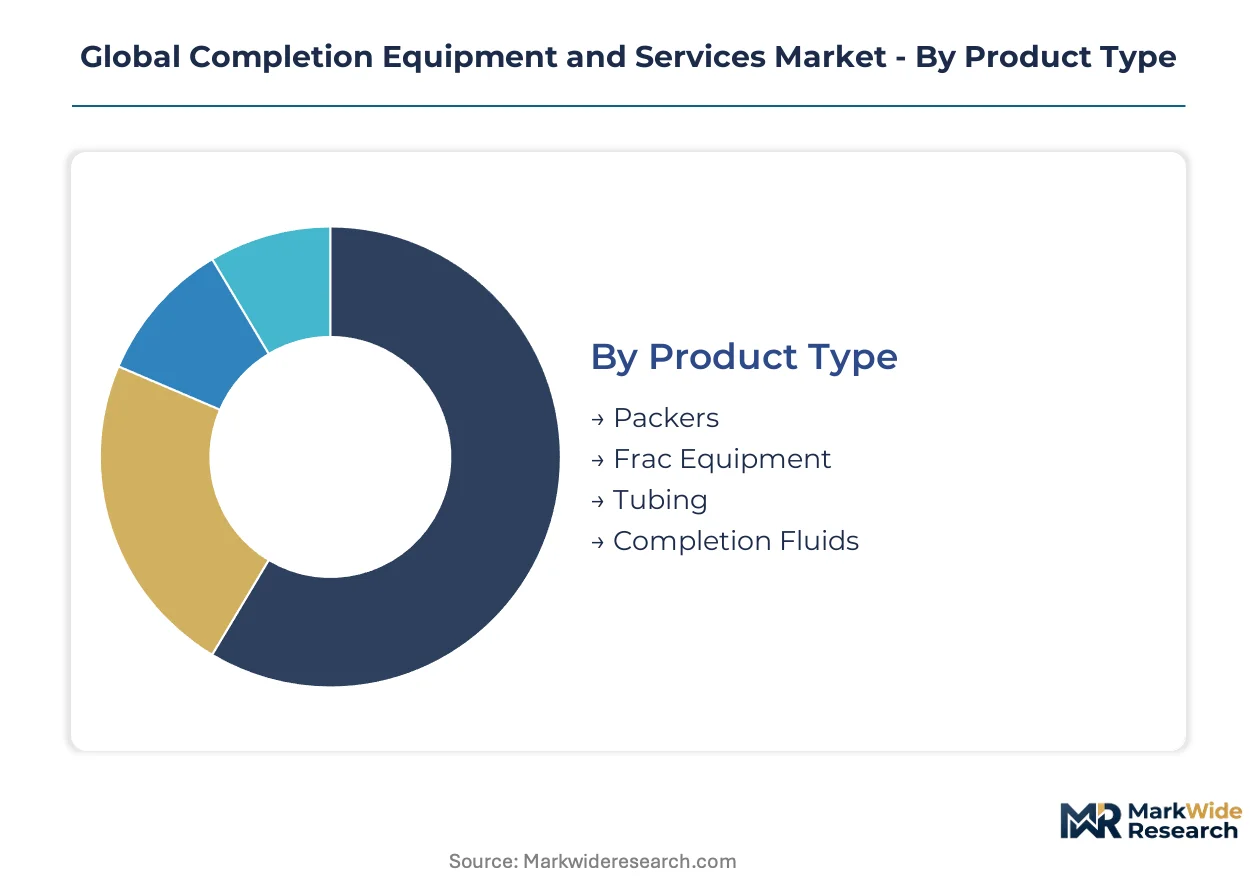
Completion equipment and services segmentation reveals how procurement priorities diverge between high-volume shale programs and capital-intensive offshore developments. Understanding these divides illuminates where technology premiums command pricing power versus where standardization drives cost competition.
Product Type:
Buyers in this category separate by pressure rating requirements and replacement frequency rather than initial capital outlay alone.
- Packers:Mechanical and inflatable seals rated to 15,000 psi isolate production zones and protect casing integrity. Permian Basin operators consume these repeatedly in multi-stage horizontal completions, with API 19AC material certifications now mandatory across West Texas and southeastern New Mexico.
- Frac Equipment:High-pressure pumps, blenders, and missile manifolds execute controlled formation fracturing. Demand concentrates with independent operators running 50-plus well pad programs where equipment utilization rates determine per-stage economics.
- Tubing:Corrosion-resistant production conduit strings withstand sour gas exposure and thermal cycling. National oil companies in the Middle East specify premium alloys for extended well life.
- Completion Fluids:Specialized brines and weighted spacers maintain reservoir compatibility during perforation and gravel pack operations. Brine chemistry varies by formation salinity and clay sensitivity.
Packers lead volumes today; smart well-integrated packer systems are gaining share fastest.
Technology:
Technology selection tracks reservoir complexity and remote operability needs across mature versus frontier basins.
- Smart Well Technology:Downhole sensors and surface-controlled chokes enable real-time zonal management without well intervention. Norwegian Continental Shelf operators deploy these for subsea tiebacks where intervention costs exceed equipment premiums by an order of magnitude.
- Artificial Lift:Rod pumps, electrical submersible pumps, and gas lift systems maintain flow rates as reservoir pressure declines. Mature onshore fields in the US Mid-Continent and Venezuela's Lake Maracaibo depend on lift optimization for marginal barrel economics.
- Composite Materials:Carbon fiber and glass-reinforced polymers reduce weight in offshore riser and tendons. Deepwater projects in Brazil's pre-salt absorb these for buoyancy-critical applications.
- Monitoring Systems:Distributed temperature and acoustic sensing fibers track inflow profiles along laterals. Australian coal seam gas operators use these to identify water breakthrough and optimize drawdown.
Artificial lift dominates installed base; smart well technology shows the steepest expansion trajectory.
End User:
End user type determines contract structure, with integrated service agreements displacing discrete procurement among the largest buyers.
- Independent Operators:Privately held and publicly traded E&P companies without downstream integration. These buyers prioritize frac fleet availability and proppant logistics reliability over equipment ownership in Permian and Bakken shale plays.
- National Oil Companies:State-controlled producers in Saudi Arabia, Norway, and Brazil. NOCs specify vendor qualification programs that lock out smaller service providers and favor long-term framework agreements.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes bundle equipment supply with technical execution. These firms cross-sell monitoring and diagnostics to capture recurring revenue streams.
- Oilfield Contractors:Drilling and completion specialists operating on day-rate or turnkey contracts. Contractors in the US Gulf of Mexico face compressed margins that limit technology uptake to client-mandated specifications.
Independent operators absorb the dominant procurement volume; national oil companies are consolidating supplier relationships fastest.
Application:
Application segmentation separates by well economics, with offshore developments commanding equipment values an order of magnitude above shale wells.
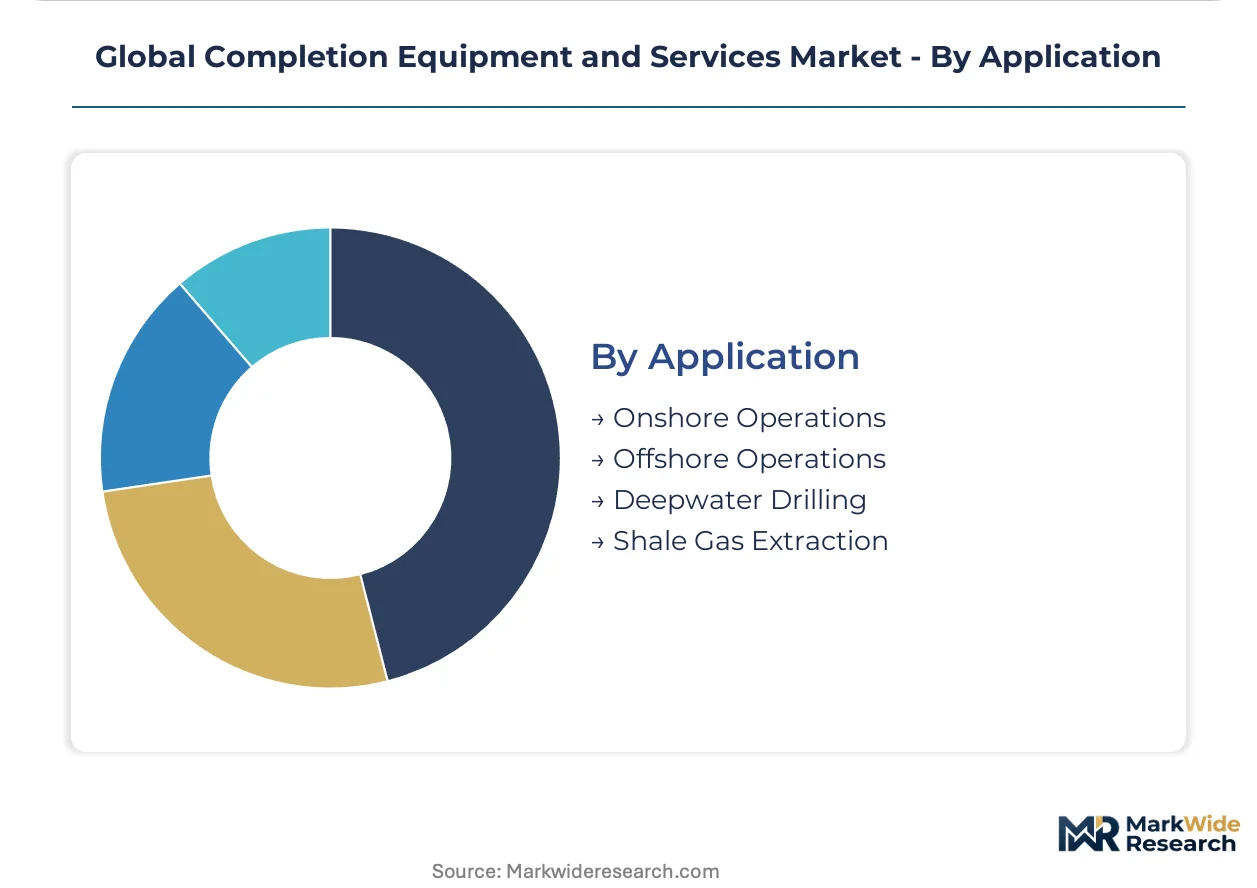
- Onshore Operations:Conventional and unconventional drilling across accessible terrain. US land rigs execute 70% of global well completions by count, driving standardized equipment specifications and price competition.
- Offshore Operations:Platform-based development in shallow to medium water depths. North Sea and Gulf of Mexico installations require explosion-proof electrical systems and marine corrosion protection.
- Deepwater Drilling:Subsea completions below 1,000 feet of water. Brazil's pre-salt and Angola's lower Congo basin absorb subsea trees, manifolds, and tieback systems with decade-long project cycles.
- Shale Gas Extraction:Horizontal drilling with multi-stage hydraulic fracturing in low-permeability formations. Argentina's Vaca Muerta and US Appalachian basins drive repeat consumption of plug-and-perf tools and slickwater systems.
Onshore operations lead well counts; deepwater drilling captures the highest equipment values per completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Houston, Stavanger, and Aberdeen anchor the industry's technical workforce concentration. These petroleum engineering hubs supply the specialized labor required for high-pressure well design and subsea system integration. Regional procurement patterns diverge sharply between shale-driven land markets and capital-intensive offshore developments.
United States
Horizontal drilling programs in the Permian Basin of West Texas and southeastern New Mexico consume the majority of global multi-stage fracturing tools and high-pressure packers. The EPA methane emissions rules are compressing procurement cycles toward leak-tight wellhead assemblies and vapor recovery units. Midland-Odessa serves as the primary equipment distribution cluster, with frac fleet deployment coordinated through centralized logistics hubs.
Norway
Subsea tieback developments on the Norwegian Continental Shelf command premium pricing for smart well technology and remote choke control systems. The country's petroleum regulator enforces stringent NORSOK standards that extend equipment qualification timelines but lock out lower-tier competitors. Stavanger anchors the engineering workforce for subsea compression and electrification projects in the North Sea.
Brazil
Pre-salt deepwater drilling below 1,000 feet of water absorbs subsea trees, manifolds, and tieback systems with decade-long project cycles. ANP regulatory frameworks mandate local content requirements that shape vendor selection for foreign equipment suppliers. Rio de Janeiro hosts the primary project management and engineering coordination centers for Santos Basin developments.
Saudi Arabia
National oil company drilling programs in the Ghawar and Safaniya fields specify premium alloy tubing and corrosion-resistant completion fluids for sour gas exposure. The national regulator enforces vendor qualification programs that favor long-term framework agreements over spot procurement. Dhahran concentrates the technical specification and supply chain management functions for Middle East completions.
China
Shale gas extraction in the Sichuan Basin is expanding consumption of plug-and-perf tools and slickwater systems for low-permeability formations. MEE environmental standards are tightening wellhead emissions monitoring requirements for new drilling permits. Chengdu serves as the equipment manufacturing and technical services coordination hub for domestic unconventional programs.
Global Completion Equipment and Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: integrated service providers bundling equipment with technical execution, equipment-focused fabricators supplying standardized wellhead and downhole components, and technology specialists capturing premiums in smart well and monitoring segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with equipment uptime guarantees displacing unit pricing in contract awards.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes occupy positions that exemplify the convergence of equipment supply with digital-physical integration platforms. These Houston-based entities anchor the premium segment through captive technical workforces and standardized pad development programs. Their market presence reflects the structural advantage of bundling wellhead supply, installation, and post-completion monitoring under single-vendor arrangements that transfer performance risk.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| National Oilwell Varco |
| TechnipFMC |
| Aker Solutions |
| Superior Energy Services |
| Oceaneering International |
| Others |
Supply Flow & Price Mechanics
Petroleum engineering talent clusters in Houston, Stavanger, and Aberdeen generate labor-cost differentials that widen pricing spreads between premium integrated service bundles and commoditized equipment-only transactions. API 19AC certification requirements and NORSOK qualification timelines add compliance premiums that separate tier-1 vendors from regional fabricators serving standard wellhead markets.
Pricing Analysis
The bundled-versus-unbundled service split dominates pricing architecture across the completion equipment market. Integrated service contracts combining wellhead supply, installation, and post-completion monitoring command premium positioning through performance-risk transfer, while discrete equipment procurement in North American shale plays competes on unit economics and fleet availability. Price differentiation rests on API certification tier and after-sales service bundling, with supermajors in the Permian Basin least sensitive to unit pricing and independent operators most responsive to per-stage cost compression. Pricing pressure stems from automated frac fleet coordination platforms reducing labor intensity and compressing margins for traditional service delivery models.
Supply Chain Analysis
Direct-to-operator channels handle supermajor demand in the Permian Basin, while distributor networks serve independent operators with fragmented procurement footprints. Geographic supply concentration centers on Germany and Japan for forged components rated to 15,000 psi, with Northern White Sand proppant sourcing anchored in Wisconsin and Minnesota. Raw material dependencies include specialty chromium-molybdenum alloys, high-purity ceramic proppants, and advanced elastomer compounds for downhole seals. Supply chain risk manifests in rail freight volatility exposing pressure pumping operations to weather disruptions and carrier capacity constraints. Distribution runs through Midland-Odessa logistics hubs for North American land markets and Stavanger-Rio de Janeiro coordination centers for offshore developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where the EPA methane emissions rules and EU Green Deal criteria create regulatory-cost differentials between North American shale and North Sea offshore developments. Operators and suppliers can exploit these divergent compliance timelines to optimize capital deployment across regulatory jurisdictions.
For Market Incumbents: Extend integrated service contract penetration in the Permian Basin by bundling vapor recovery unit retrofits with wellhead replacement programs, countering independent equipment fabricators competing on unit pricing. Add captive proppant logistics capacity in West Texas to defend against rail freight volatility eroding pressure pumping margins. Backward integration into specialty alloy forging through partnerships with German and Japanese suppliers reduces single-source vulnerability for high-pressure components.
For New Entrants and Emerging Players: The mid-tier pricing gap between Schlumberger-Halliburton bundled offerings and regional wellhead fabricators creates entry space for smart well technology specialists targeting Norwegian Continental Shelf subsea tiebacks. Argentina Vaca Muerta pad drilling programs offer the most penetrable geography for imported completion hardware, with underdeveloped local supply chains forcing operators toward foreign technical service partnerships. A go-to-market angle anchored in remote choke control system deployment, bypassing NORSOK qualification through joint ventures with established offshore contractors, accelerates revenue recognition.
For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-focused fabricators without digital-physical integration platforms, as integrated service providers capture scarcity premiums for bundled performance-risk contracts. Long-term viability across the analysis window hinges on exposure to IRA methane fee acceleration and EU carbon border mechanism implementation. Acquisition targets should screen for API 19AC certification readiness and Vaca Muerta or pre-salt Brazil regional presence. The signal to watch is Permian Basin operator consolidation into 50-plus well pad programs, which concentrates procurement authority and favors vendors with automated fleet coordination capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Expansion | Bundling wellhead supply with post-completion monitoring transfers performance risk and locks out unit-price competitors in Permian Basin supermajor programs. |
| Specialty Alloy Backward Integration | Captive supply of 15,000 psi forged components from German and Japanese suppliers reduces input bottlenecks and secures margin control. |
| Automated Frac Fleet Coordination | Proppant delivery scheduling and pump synchronization platforms compress labor costs and improve stage consistency for multi-well pad operators. |
| Smart Well Technology Certification | NORSOK qualification for remote choke control systems opens Norwegian Continental Shelf subsea tiebacks where intervention costs justify equipment premiums. |
| Vaca Muerta Market Entry Partnership | Joint ventures with Argentine operators pad drilling programs address underpenetrated shale formations requiring imported completion hardware. |
Methodological Framework
Multiple input streams — executive interviews with petroleum engineering directors, procurement leads at independent operators, subsea project managers, and frac fleet coordinators; regulatory filing analysis from EPA, Texas Railroad Commission, and EU Green Deal documentation; and equipment utilization databases from North American land rig operators — were reconciled against API standards documentation and NORSOK qualification records. Secondary validation drew from SEC 10-K filings of integrated service providers, EIA drilling productivity reports, and ANP regulatory frameworks for Brazil pre-salt developments. Bottom-up well count and equipment consumption estimates were triangulated with top-down market value assessments across product type, technology, and application segments.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling volume and value outputs through segmentation dimensions spanning pressure rating tier, well complexity class, regulatory jurisdiction cluster, and offshore-versus-onshore development type. CAGRs were derived from equipment replacement cycle analysis and capital commitment trajectories in shale and deepwater basins. Industry-specific forecast inputs included EPA methane rule implementation timelines, IRA emissions-based penalty schedules, and EU F-Gas Regulation phase-down curves affecting offshore platform refrigeration modules.
The model assumes a particular technology adoption path; alternative pathways for electrification of subsea tiebacks or premature failure resolution in smart well sensors would alter the outlook for premium equipment categories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, commodity price thresholds sustaining horizontal drilling economics, and specialty alloy supply expansion from existing forging capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Mud Balance Market