
 Indonesia Oil and Gas Midstream Market | 2026-2036
Indonesia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oil and Gas Midstream Market Foresight
Power generation utilities are broadening their offtake from domestic gas processing facilities. PT Pertamina leverages its integrated refining and distribution network to capture margin across the value chain. PT Perusahaan Gas Negara Tbk anchors national pipeline infrastructure with exclusive rights on strategic transmission corridors. Medco Energi International specializes in gas processing and pipeline operations tied to mature fields in South Sumatra.
Indonesia oil and gas midstream encompasses the transportation, storage, and processing of hydrocarbons between upstream extraction and downstream refining, involving pipeline systems operating at pressures up to 100 bar, cryogenic LNG storage at minus 162 degrees Celsius, and gas processing plants removing contaminants before commercial distribution. The service type dimension shows transportation and pipeline segments commanding established revenue pools while processing capacity expansion is accelerating fastest to handle rising associated gas volumes. Technology segmentation reveals LNG and virtual pipeline systems gaining share as archipelago geography limits fixed pipeline economics across eastern provinces.
BPH Migas enforces domestic market obligation regulations that mandate priority supply to designated local buyers before export clearance, reshaping allocation decisions for every midstream operator. The Ministry of Energy and Mineral Resources sets national gas infrastructure master plans that determine pipeline licensing and storage facility permitting timelines. Stakeholders must monitor regulatory shifts around carbon capture integration requirements at processing facilities, as these rules will reshape capital deployment priorities across the midstream asset base.
Market Dynamics
BPH Migas domestic market obligation rules are redirecting LNG flows toward local industrial buyers, compressing export arbitrage margins while deepening pipeline connectivity to Java Sea gas fields.
Growth Catalysts
- Domestic Market Obligation Enforcement:BPH Migas mandates priority supply to designated local buyers before export clearance, anchoring throughput for processing facilities.
- East Java Manufacturing Corridor:Power generation utilities are broadening offtake from domestic gas processing facilities to serve industrial load centers.
- Virtual Pipeline Systems:LNG and virtual pipeline technology gains share as archipelago geography limits fixed pipeline economics across eastern provinces.
Market Restraints
- Archipelago Infrastructure Costs:Fixed pipeline economics face constraints across 17,000 islands, elevating unit transportation costs versus continental markets.
- Associated Gas Volume Volatility:Processing capacity must absorb fluctuating upstream yields from mature fields in South Sumatra.
- Carbon Capture Integration Timelines:Pending Ministry of Energy and Mineral Resources requirements for processing facility emissions controls delay capital deployment.
Strategic Opportunities
- Eastern Province Virtual Networks:Cryogenic LNG storage at minus 162 degrees Celsius enables distribution where pipeline construction is uneconomical.
- Gas Processing Expansion:Rising associated gas volumes from upstream extraction accelerate processing capacity additions.
- Integrated Refining Networks:Captive pipeline and storage infrastructure captures margin across transportation, processing, and distribution functions.
Industry Challenges
- Cryogenic Handling Expertise Shortage:LNG storage and regasification operations require specialized technical skills in limited supply across the domestic labor pool.
- Pipeline Licensing Delays:Ministry of Energy and Mineral Resources master plan approvals extend permitting timelines for strategic transmission corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oil and Gas Midstream Market |
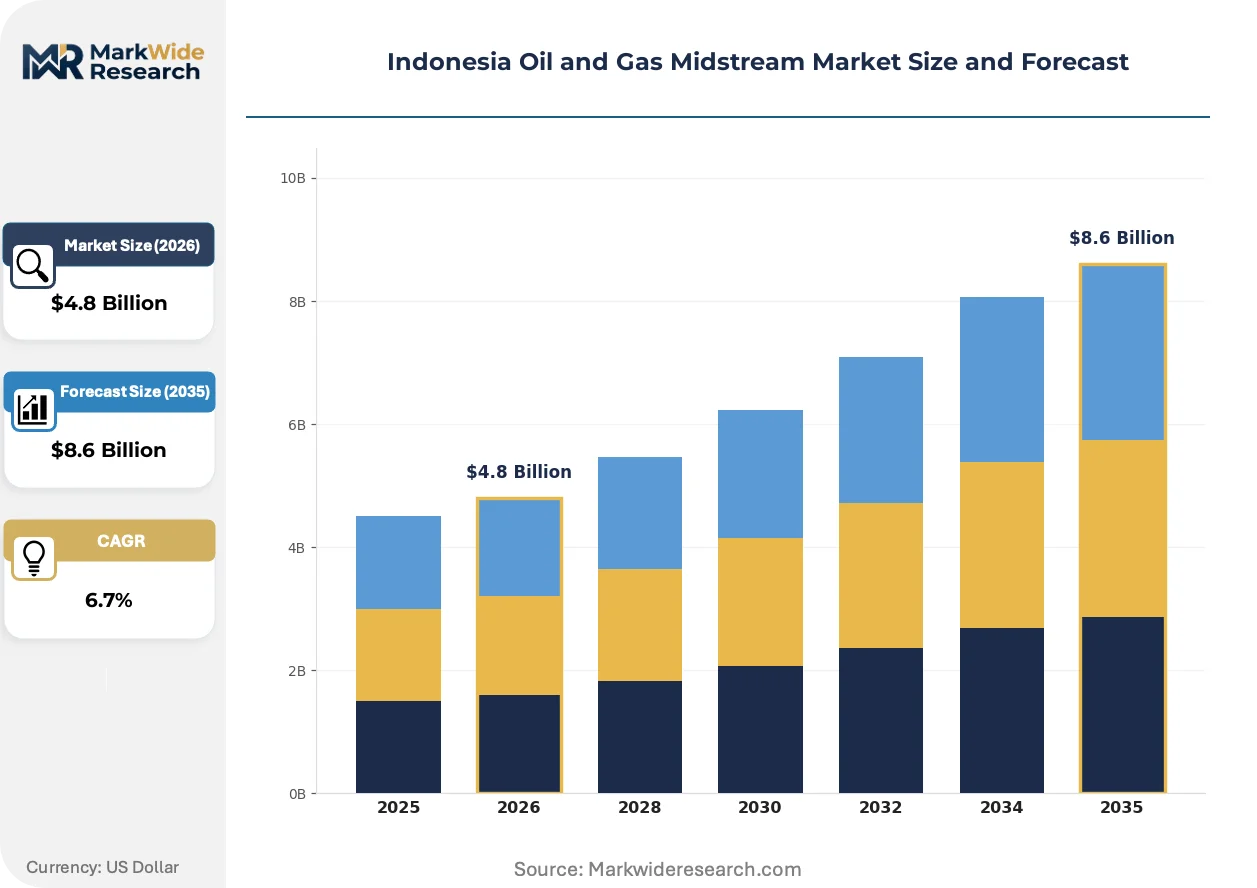
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Pipeline, Processing Technology: Virtual Pipeline, LNG, Compression, Pumping End User: Refineries, Distributors, Utilities, E&P Companies Capacity: Small Scale, Medium Scale, Large Scale, Mega Scale |
| Companies Covered | PT Pertamina, PT Perusahaan Gas Negara Tbk, PT Connusa Energindo, ConocoPhillips Company, Chevron Corporation, Pertamina EP, Medco Energi International, ExxonMobil Indonesia, Shell Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oil and Gas Midstream Market Shifts & Advancements
Technology segmentation across Indonesia's midstream infrastructure is absorbing digital monitoring systems and modular processing units that reshape asset deployment economics.
Modular gas processing units are absorbing stranded associated gas volumes from mature fields. Independent operators in South Sumatra deploy these systems to monetize gas previously flared or reinjected. The technology is absorbing capital that would otherwise flow to greenfield pipeline construction, compressing project timelines from years to months.
BPH Migas enforcement of domestic market obligation regulations intensifies scrutiny of export allocation decisions. Industrial buyers in East Java's manufacturing corridor now receive contractual priority over spot LNG cargoes. Processing facilities are responding by reconfiguring offtake agreements to secure local purchase commitments before production ramp-up.
Power generation procurement patterns favor long-term gas supply agreements over spot market exposure. Utilities negotiate directly with processing facilities, disintermediating traditional trading intermediaries. This behavioral shift concentrates demand negotiation leverage in East Java's manufacturing corridor where pipeline connectivity to Java Sea gas fields is deepest.
Indonesia Oil and Gas Midstream Market Segmentation
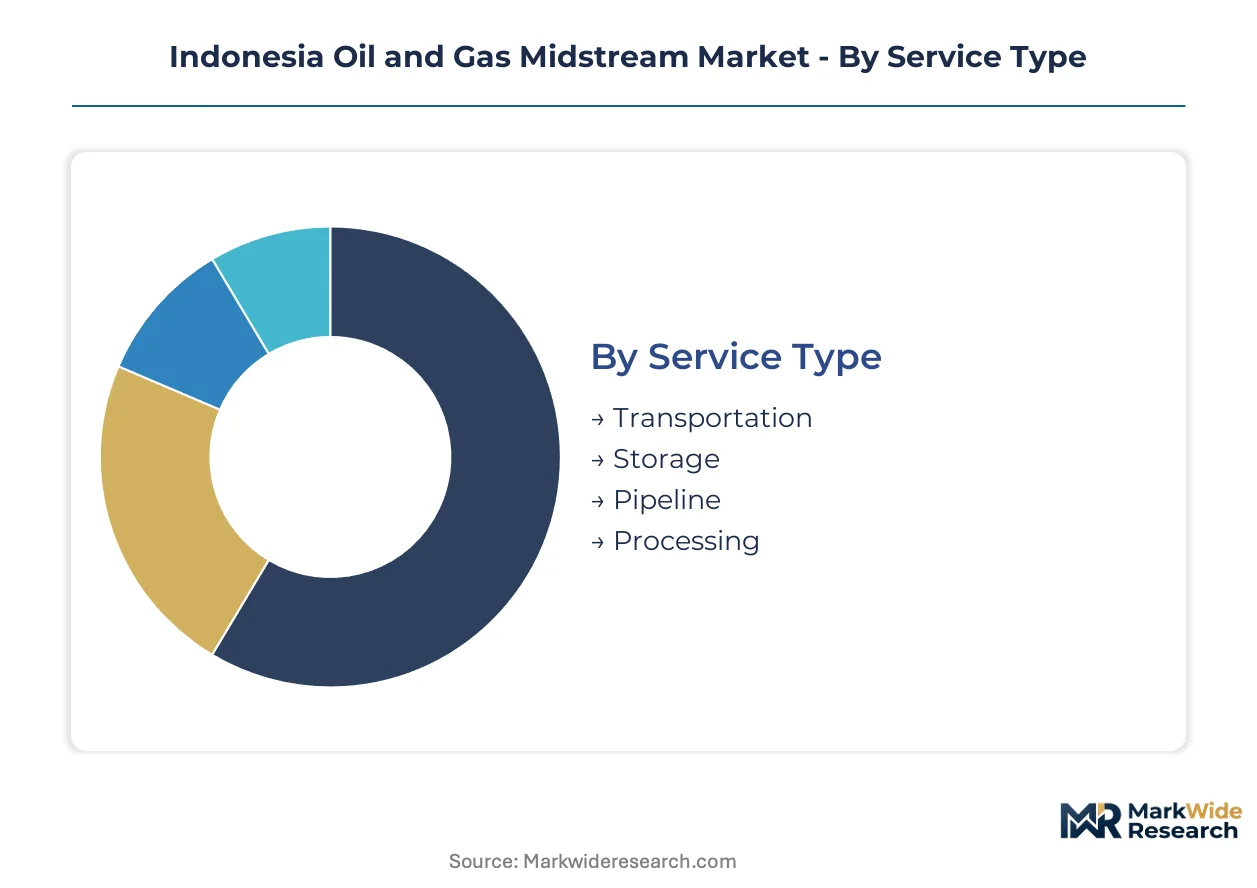
Midstream segmentation in Indonesia reflects the archipelago's infrastructure constraints and regulatory mandates. Each dimension carries distinct licensing burdens from BPH Migas and the Ministry of Energy and Mineral Resources. Operators must align asset scale with specific domestic market obligation thresholds.
Service Type:
Transportation and pipeline operations require BPH Migas transmission corridor licenses, while processing facilities face Ministry of Energy and Mineral Resources emissions permitting. Storage assets trigger additional hazardous materials certifications.
- Transportation:Marine vessel and truck-based hydrocarbon movement across 17,000 islands. Demand concentrates in East Java's manufacturing corridor where road and port access connects to Java Sea gas fields, though maritime logistics costs exceed pipeline unit economics by substantial margins.
- Storage:Above-ground tank farms and underground caverns for crude and product holding. Refineries in Java and Sumatra anchor demand, with BPH Migas mandating minimum strategic reserve levels that shape tankage sizing decisions.
- Pipeline:Fixed transmission infrastructure operating at pressures up to 100 bar. PT Perusahaan Gas Negara Tbk holds exclusive rights on strategic corridors, limiting third-party access to secondary distribution networks.
- Processing:Gas treatment plants removing contaminants before commercial distribution. Rising associated gas volumes from mature South Sumatra fields accelerate capacity additions, though carbon capture integration timelines delay capital deployment.
Leading the category by volume: Pipeline. Growing fastest: Processing.
Technology:
Technology selection hinges on geography and scale economics. Eastern provinces favor modular cryogenic solutions over fixed infrastructure due to dispersed demand patterns.
- Virtual Pipeline:ISO containerized LNG and compressed natural gas distribution by road and sea. Industrial buyers in Sulawesi and Papua receive supply where pipeline construction is uneconomical, with BPH Migas domestic market obligation rules prioritizing these flows to local offtakers.
- LNG:Cryogenic storage at minus 162 degrees Celsius and regasification terminals. East Java's manufacturing corridor hosts the deepest terminal infrastructure, with power generation utilities broadening offtake through direct long-term agreements.
- Compression:Gas pressurization for pipeline injection and transport. Mature field operators in South Sumatra deploy mobile compression to maintain throughput as reservoir pressures decline.
- Pumping:Liquid hydrocarbon movement through pipeline networks. Crude oil trunk lines from Sumatra to Java refineries depend on staged pumping stations with Ministry of Energy and Mineral Resources master plan licensing.
Widest deployment: Virtual Pipeline. Steepest expansion trajectory: LNG.
End User:
End-user categories reflect distinct procurement patterns and contract tenors. Utilities negotiate longest terms; distributors operate on shorter trading cycles.
- Refineries:Integrated processing and conversion facilities consuming crude feedstock. PT Pertamina's refining network captures margin across transportation, processing, and distribution through captive pipeline and storage infrastructure.
- Distributors:Wholesale and retail marketers of refined products. BPH Migas domestic market obligation rules reshape allocation decisions, compressing export arbitrage margins while deepening local supply commitments.
- Utilities:Power generation companies procuring gas for electricity production. East Java's manufacturing corridor concentrates demand negotiation leverage where pipeline connectivity to Java Sea gas fields is deepest.
- E&P Companies:Upstream producers requiring midstream services for field development. Associated gas volume volatility from mature South Sumatra fields forces processing capacity flexibility.
Highest contract value: Utilities. Fastest procurement growth: Refineries.
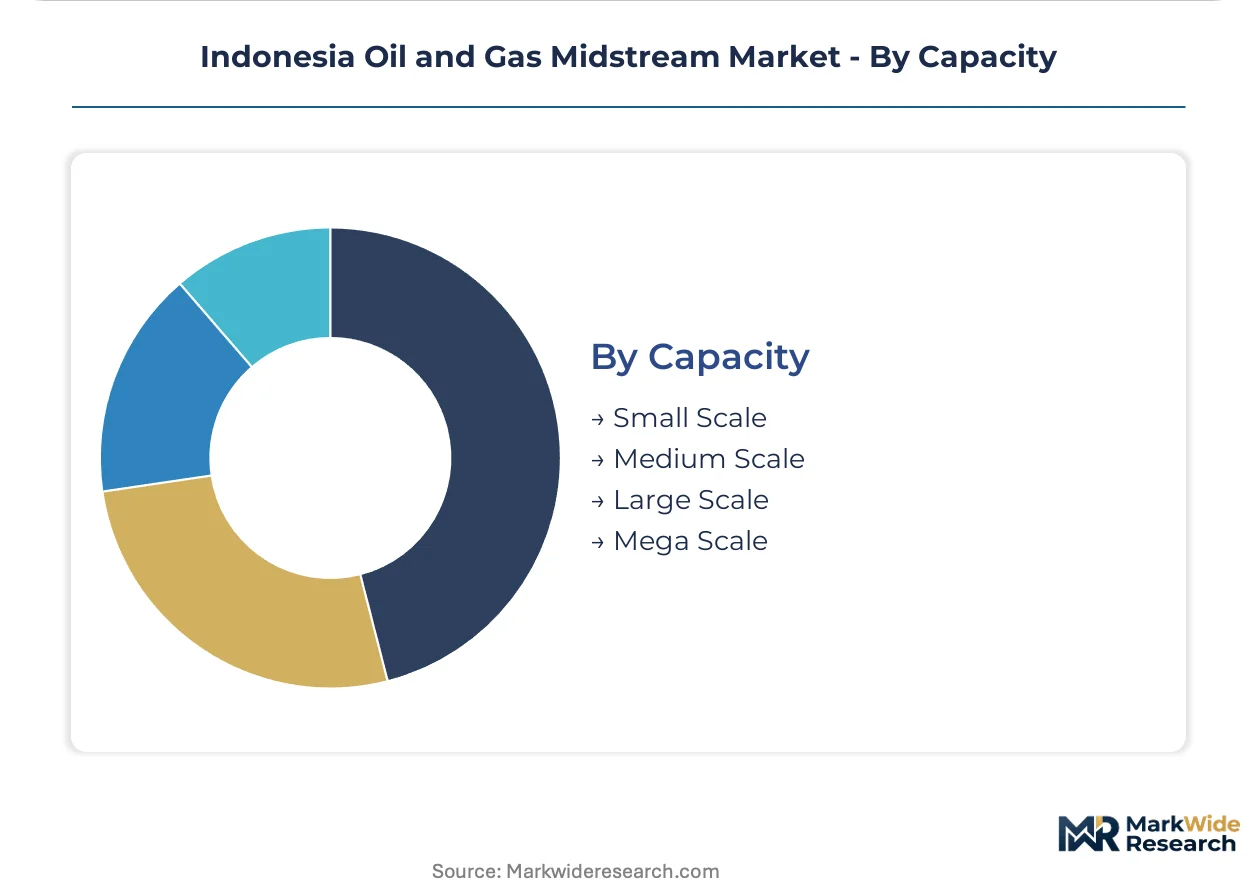
Capacity:
Capacity tiers align with BPH Migas licensing thresholds and domestic market obligation minimums. Scale determines regulatory scrutiny intensity.
- Small Scale:Distributed storage and processing below master plan permitting thresholds. Independent operators in South Sumatra deploy modular units to monetize stranded associated gas previously flared.
- Medium Scale:Regional pipeline branches and intermediate storage. Java's industrial corridors host the densest medium-scale network with direct utility connections.
- Large Scale:Strategic transmission corridors and major processing hubs. PT Perusahaan Gas Negara Tbk anchors national infrastructure at this tier with exclusive rights on priority routes.
- Mega Scale:Integrated LNG export terminals and cross-archipelago pipeline systems. BPH Migas export allocation decisions concentrate at this level, with domestic market obligation rules mandating priority supply to designated local buyers before clearance.
Dominant by throughput: Mega Scale. Gaining share fastest: Small Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Java's Special Economic Zone for energy infrastructure anchors national midstream investment, with tax incentives concentrating processing capacity and pipeline terminals in the manufacturing corridor.
East Java
Power generation utilities broaden offtake from domestic gas processing facilities to serve industrial load centers. BPH Migas domestic market obligation rules mandate priority supply to designated local buyers before export clearance. The manufacturing corridor from Surabaya to Gresik deepens pipeline connectivity to Java Sea gas fields.
South Sumatra
Rising associated gas volumes from mature fields accelerate processing capacity additions. The Ministry of Energy and Mineral Resources sets national gas infrastructure master plans determining pipeline licensing timelines. Independent operators deploy modular gas processing units around Palembang to monetize stranded gas previously flared.
West Java
Refinery complexes consume captive pipeline and storage infrastructure capturing margin across transportation functions. BPH Migas enforces minimum strategic reserve levels that shape tankage sizing decisions. The Cilacap refining cluster anchors demand for crude trunk lines from Sumatra.
East Kalimantan
LNG export terminals face compressed arbitrage margins as domestic market obligation rules redirect flows toward local industrial buyers. The Ministry of Energy and Mineral Resources carbon capture integration requirements delay capital deployment at processing facilities. The Bontang industrial zone concentrates cryogenic storage infrastructure serving archipelago distribution.
Papua
Virtual pipeline systems gain share as archipelago geography limits fixed pipeline economics across eastern provinces. ISO containerized LNG distribution by road and sea reaches industrial buyers where pipeline construction is uneconomical. The Timika corridor hosts modular cryogenic solutions for dispersed demand patterns.
Indonesia Oil and Gas Midstream Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated national oil companies controlling strategic transmission corridors while independent operators capture modular processing niches. State-linked entities hold exclusive rights on priority pipeline routes, compressing third-party access to secondary distribution networks. Two strategic archetypes dominate: vertically integrated majors leveraging captive infrastructure across the value chain, and specialized gas processors monetizing stranded associated gas volumes. Competitive moves concentrate on processing capacity expansion and virtual pipeline network deployment.
Within the integrated major tier, PT Pertamina and PT Perusahaan Gas Negara Tbk occupy positions anchoring national infrastructure through exclusive corridor rights and refining networks. Medco Energi International exemplifies the specialized processor archetype, with operations tied to mature field gas processing in South Sumatra.
| Leading Market Players |
|---|
| PT Pertamina |
| PT Perusahaan Gas Negara Tbk |
| PT Connusa Energindo |
| ConocoPhillips Company |
| Chevron Corporation |
| Pertamina EP |
| Medco Energi International |
| ExxonMobil Indonesia |
| Shell Indonesia |
| Others |
Supply & Pricing Matrix
Captive pipeline infrastructure integration anchors both supply positioning and pricing power across Indonesia's midstream sector. PT Pertamina's control of refining and distribution networks compresses third-party margin capture while BPH Migas domestic market obligation rules reshape allocation premiums.
Pricing Analysis
Short lead-time premiums command pricing advantages for spot LNG cargoes against long-term offtake contracts. Contract-based long-term offtake structures dominate utility procurement, with price differentiation resting on volume scale and pipeline connectivity depth. Cost compression in export arbitrage tiers is intensifying because BPH Migas redirects flows toward local industrial buyers. Distributors exhibit highest price sensitivity due to thin trading margins, while integrated refiners show least sensitivity through captive infrastructure.
Supply Chain Analysis
Dual-sourcing requirements from power utilities mandate multi-supplier qualification for pipeline gas and LNG regasification terminals. Geographic supply concentration centers on Indonesia's Java Sea gas fields, Singapore's trading hub, and Malaysia's pipeline interconnections. Raw material dependencies include cryogenic storage equipment, high-pressure pipeline steel, and modular gas processing skids. Single-source vulnerability runs through PT Perusahaan Gas Negara Tbk's exclusive corridor rights. Distribution runs through marine vessel networks, road-based ISO containers, and fixed transmission pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
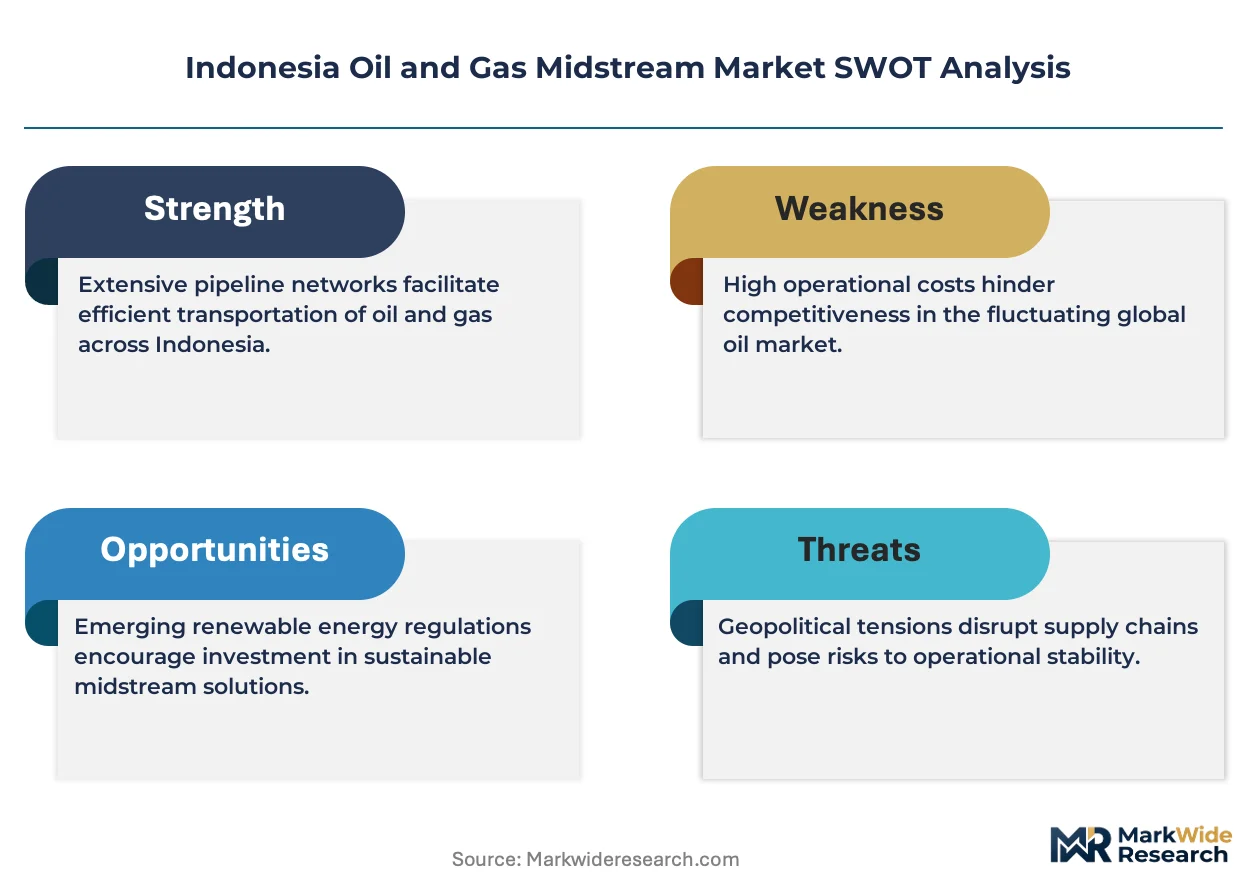
Indonesia's midstream sector reads as a consolidation play where BPH Migas licensing burdens and carbon capture compliance costs force weaker independent operators toward exit.
For Market Incumbents: Deploy modular processing technology to absorb stranded associated gas volumes from South Sumatra's mature fields. Deepen pipeline connectivity into East Java's manufacturing corridor before virtual pipeline competitors establish ISO container networks. Carbon capture integration requirements at processing facilities threaten capital deployment timelines for laggards.
For New Entrants and Emerging Players: Cryogenic LNG distribution systems offer technology-first entry where fixed pipeline economics fail across Papua and eastern Sulawesi. Target industrial buyers in Timika and Bontang corridors where PT Perusahaan Gas Negara Tbk lacks transmission coverage. Pursue direct long-term supply agreements with power generation utilities disintermediating traditional trading intermediaries.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated majors seeking processing capacity in South Sumatra. Long-term viability favors operators with BPH Migas transmission corridor licenses and Ministry of Energy and Mineral Resources emissions permits in hand. Watch for carbon capture integration rule finalization as inflection indicator for capital deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Processing Capacity Expansion | Modular gas processing units monetize stranded associated gas volumes from mature South Sumatra fields. |
| Virtual Pipeline Network Deployment | ISO containerized LNG distribution reaches industrial buyers across Papua where pipeline construction is uneconomical. |
| Carbon Capture Integration | Pending Ministry of Energy and Mineral Resources requirements reshape capital deployment priorities at processing facilities. |
| Long-term Supply Agreement | Power generation utilities negotiate directly with processing facilities in East Java's manufacturing corridor. |
| Strategic Corridor Licensing | BPH Migas transmission corridor rights anchor national infrastructure control for priority pipeline routes. |
Research Methodology
Ministry of Energy and Mineral Resources master plan documents, BPH Migas regulatory filings, and IEA Southeast Asia energy outlooks formed the secondary backbone for this analysis. Primary interviews with gas processing facility operators, utility procurement officers, EPC contractors, and pipeline infrastructure planners combined with customs trade data and project development databases. Bottom-up and top-down triangulation validated segment-level estimates across service type, technology, and capacity tiers.
Bottom-up modeling anchored volume projections while top-down macroeconomic calibration ensured consistency with national energy demand trajectories across the analysis window. Segmentation dimensions modeled include service type, technology format, end-user category, and capacity tier alongside regional pipeline connectivity depth. CAGRs derived from historical throughput trends, regulatory enforcement intensity, and announced capacity expansion timelines. Forecast inputs incorporated associated gas volume projections from mature field operators and power generation fuel-switching patterns.
Several conditions sit outside the modeled scope, including unannounced carbon capture integration rule changes, upstream discovery timelines in frontier basins, and geopolitical disruptions to maritime LNG trade routes. Forecasts reflect assumptions around BPH Migas domestic market obligation enforcement continuity and Ministry permitting timeline stability. Deviation in carbon capture compliance cost thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Natural Gas Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Smart Well Market
Oil & Gas
Canada Oil and Gas Upstream Market