
 Subsea Boosting Systems Market | 2026-2036
Subsea Boosting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Boosting Systems Market Analysis
Buyer concentration among national oil companies and integrated majors is realigning procurement leverage across the subsea boosting value chain. Baker Hughes leverages its integrated turbomachinery portfolio to anchor long-term service contracts in deepwater basins. SLB competes through proprietary permanent magnet motor technology that extends operational run-life in high-pressure reservoirs. Aker Solutions specializes in modular boosting architectures that reduce field development cycle times for marginal field tiebacks.
Subsea boosting systems encompass electrically or hydraulically driven pumps and compressors installed on the seabed to maintain or restore production flow from subsea wells to surface facilities, typically operating at pressures exceeding 300 bar and depths beyond 1,500 meters. Electric boosting systems dominate capital deployment due to superior efficiency in deepwater tiebacks, while hydraulic boosting systems retain share in brownfield retrofits where topside power constraints limit electrification. Flow assurance applications command premium pricing as operators prioritize hydrate management and wax deposition prevention in long-distance subsea tiebacks.
Brazil's national petroleum regulator ANP mandates equipment qualification under N-2,790 standards for subsea production systems, while Norway's Petroleum Safety Authority enforces functional safety requirements under IEC 61511 for seabed processing equipment. The US Bureau of Safety and Environmental Enforcement requires subsea safety systems to meet API RP 14C and 30 CFR 250 specifications for offshore operations. Stakeholders must monitor evolving decommissioning liability frameworks and carbon intensity benchmarks that increasingly influence field development sanctioning timelines.
Market Dynamics
Deepwater operators are compressing field development timelines by mandating modular boosting architectures that slash installation windows from months to weeks. API 17Q qualification requirements and ISO 13628-7 specifications are tightening certification cycles, forcing equipment suppliers to front-load engineering validation costs.
Growth Catalysts
- Pre-salt reservoir development:Brazil's ANP N-2,790 standards are accelerating qualification of electric submersible systems for ultra-deepwater tiebacks exceeding 2,000 meters.
- Flow assurance mandates:Hydrate management regulations across North Sea jurisdictions are expanding procurement of subsea processing equipment with integrated chemical injection capabilities.
- Permanent magnet motor advances:High-torque density designs are extending mean time between failures in high-pressure, high-temperature reservoir conditions.
Market Restraints
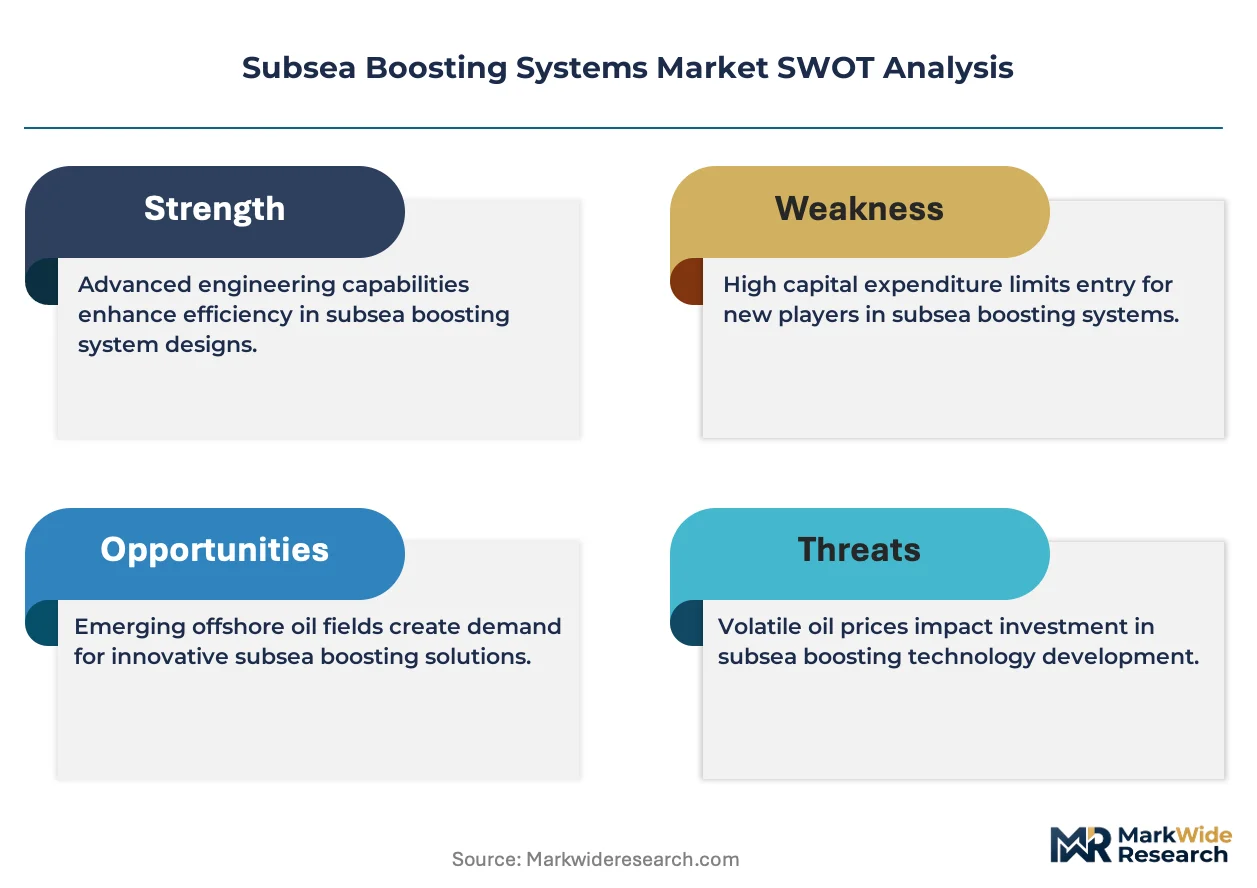
- Specialized alloy supply concentration:Duplex stainless steel and Inconel sourcing clusters in Scandinavian forging facilities create vulnerability to capacity constraints.
- Qualification cost escalation:IEC 61511 functional safety certification for seabed processing equipment demands multi-year validation programs that lock working capital.
- Topside power infrastructure gaps:Brownfield platforms in mature North Sea basins lack electrical capacity for electrified boosting retrofits.
Strategic Opportunities
- Decommissioning liability arbitrage:Norway's Petroleum Safety Authority is incentivizing subsea tieback solutions that defer platform abandonment obligations.
- Electrification of marginal fields:All-electric boosting systems eliminate hydraulic umbilical requirements, unlocking stranded reserves in remote West African basins.
- Digital twin integration:Real-time predictive maintenance algorithms are converging with subsea sensor networks to enable condition-based service models.
Industry Challenges
- Subsea systems engineering talent scarcity:Deepwater turbomachinery specialization requires decade-long apprenticeship pipelines that outpace university output.
- Legacy hydraulic architecture integration:Brownfield tiebacks demand complex interface engineering between existing umbilical infrastructure and new electric boosting modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Boosting Systems Market |
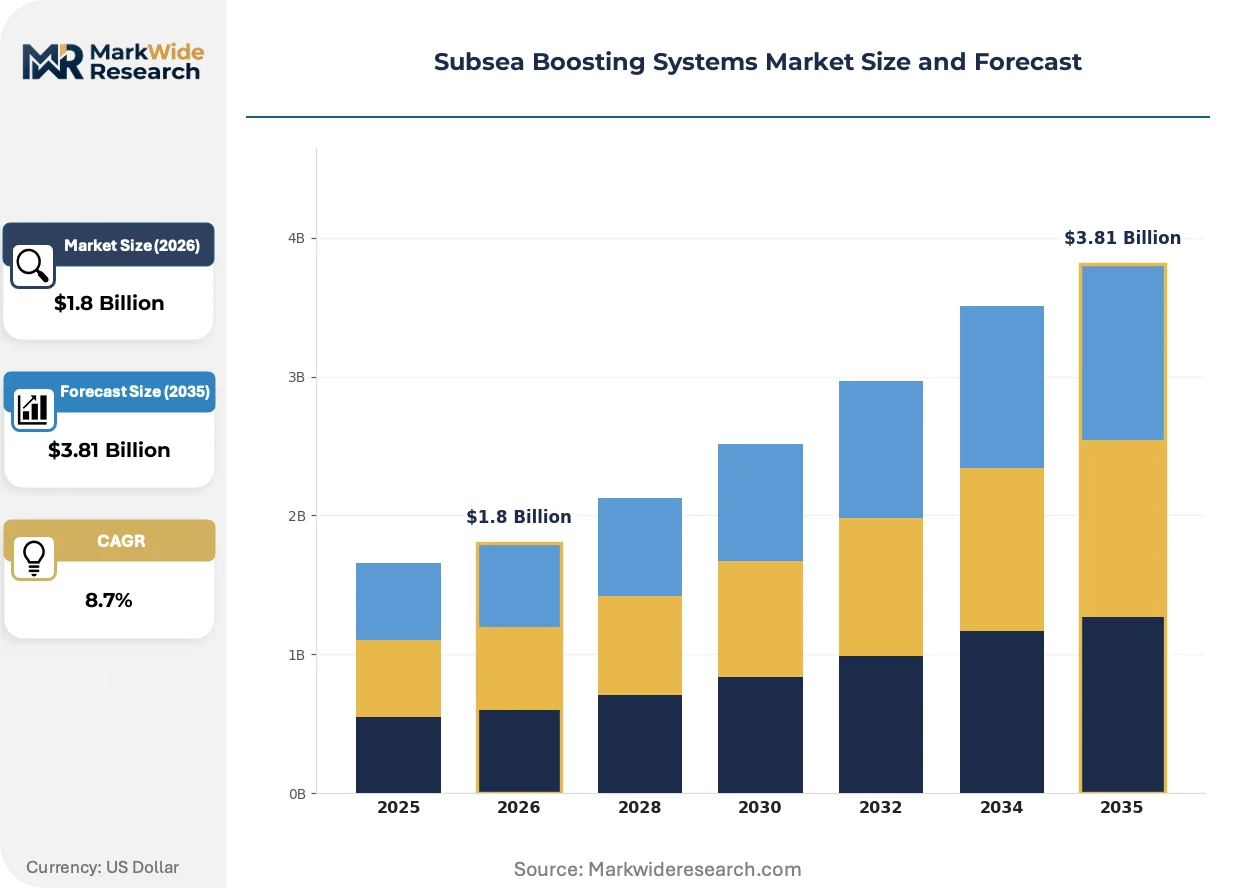
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Boosting Systems, Hydraulic Boosting Systems, Mechanical Boosting Systems, Pneumatic Boosting Systems Application: Oil Extraction, Gas Transportation, Water Injection, Flow Assurance Installation Type: Fixed Platforms, Floating Platforms, Subsea Trees, Pipeline Systems End User: Oil & Gas Companies, Exploration Firms, Utility Providers, Contractors |
| Companies Covered | Baker Hughes, Halliburton, SLB, NOV Inc, Oceaneering International, Subsea 7, Aker Solutions, Sulzer, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Boosting Systems Market Emerging Trajectories
Subsea boosting technology is pivoting from hydraulic to all-electric architectures as operators prioritize power efficiency and reduced umbilical complexity. Digitalization and modular design philosophies are compressing deployment cycles while expanding addressable reservoir types.
Permanent magnet motor technology is overtaking conventional induction designs in deepwater boosting applications. These motors deliver superior power density and thermal performance in high-pressure housings. Petrobras and international majors in Brazil's Santos Basin are specifying permanent magnet systems for new pre-salt tiebacks. This shift is overtaking legacy hydraulic boosting in greenfield developments by eliminating subsea hydraulic distribution networks.
Norway's Petroleum Safety Authority is enforcing stricter IEC 61511 functional safety requirements for seabed processing equipment with automated shutdown capabilities. Operators must demonstrate fault-tolerant control architectures through third-party validation. Deepwater projects in the Norwegian Continental Shelf are most affected, with engineering contractors expanding safety instrumented system verification teams.
Long-term service agreements are displacing discrete equipment procurement in major deepwater basins. National oil companies now contract operational availability rather than capital hardware, transferring performance risk to OEM service organizations. This model is most visible in Brazil, where Petrobras structures subsea boosting contracts around guaranteed uptime metrics and integrated maintenance obligations.
Subsea Boosting Systems Market Segmentation
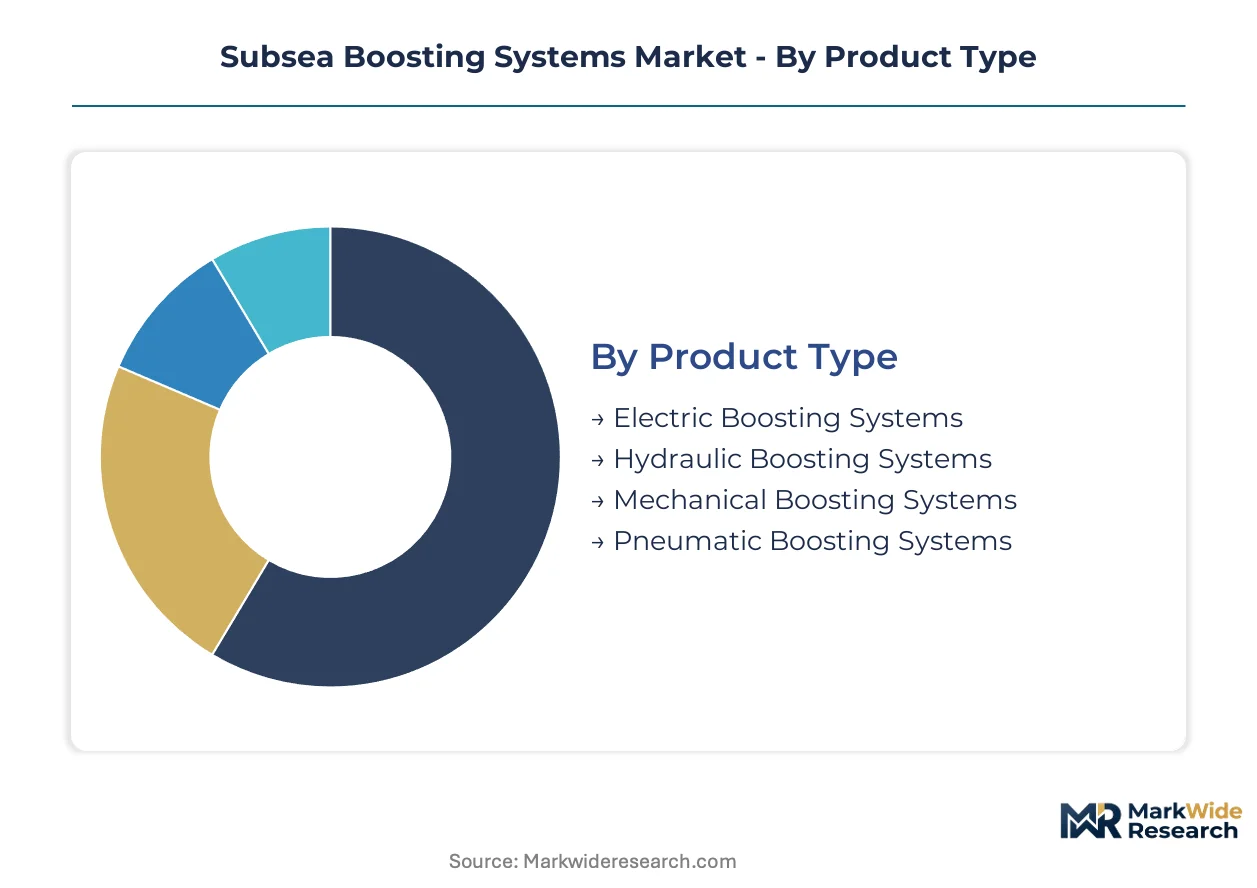
Segmentation in subsea boosting systems reflects divergent engineering requirements across water depths, reservoir pressures, and tieback distances. Equipment specifications vary sharply between greenfield pre-salt developments and brownfield retrofits, with upgrade cycles driving replacement demand in mature North Sea basins.
Product Type:
Replacement cycles in subsea boosting equipment are accelerating as operators retire first-generation hydraulic systems in favor of electrified architectures with superior power density and reduced umbilical complexity.
- Electric Boosting Systems:Permanent magnet motor designs deliver high-torque density in pressure-compensated housings rated beyond 300 bar. Petrobras specifies these systems for Santos Basin pre-salt tiebacks exceeding 2,000 meters, where efficiency advantages compound across long-distance power transmission.
- Hydraulic Boosting Systems:Conventional turbine-driven pumps rely on subsea hydraulic distribution networks with surface power fluid injection. These systems retain installed base in mature North Sea fields where topside electrification remains capital-prohibitive for marginal asset life extensions.
- Mechanical Boosting Systems:Direct-drive seabed pumps powered by subsea turbines bypass electrical infrastructure entirely, finding niche deployment in remote West African developments with limited platform power availability.
- Pneumatic Boosting Systems:Compressed gas-driven boosters serve specialized gas-lift applications and hydrate remediation scenarios requiring rapid deployment without electrical commissioning.
Electric Boosting Systems sit at the top of the volume ranking, with Mechanical Boosting Systems climbing the fastest in frontier basin applications.
Application:
Cost tier differentiation across application segments separates capital-intensive flow assurance infrastructure from operational expenditure-driven production maintenance.
- Oil Extraction:Subsea multiphase pumps maintain reservoir drawdown in declining fields, with demand concentrating in Brazil's pre-salt carbonate reservoirs where high gas-oil ratios challenge conventional artificial lift.
- Gas Transportation:Seabed compression systems extend field life in high-pressure gas condensate developments. Norway's Ormen Lange and Aasta Hansteen fields deploy wet gas compressors that eliminate platform processing entirely.
- Water Injection:Subsea seawater injection pumps support pressure maintenance in deepwater oil developments, with specifications tightening under NORSOK standards for Norwegian Continental Shelf deployments.
- Flow Assurance:Integrated boosting with chemical injection capabilities prevents hydrate and wax deposition in long subsea tiebacks, commanding premium pricing in Gulf of Mexico and West African deepwater corridors.
Oil Extraction commands the largest capital allocation, though Flow Assurance is gaining share fastest as tieback distances extend beyond 100 kilometers.
Installation Type:
Customer type segmentation reveals divergent procurement patterns between integrated majors with in-house installation capabilities and independent contractors supplying modular deployment services.
- Fixed Platforms:Steel-jacket structures in shallow to mid-water depths accommodate topside boosting equipment with subsea pump modules deployed through platform moonpools, prevalent in Gulf of Mexico shelf developments.
- Floating Platforms:FPSO and semisubmersible vessels require seabed boosting to overcome riser hydrostatic head in ultra-deepwater, with Petrobras operating the largest fleet of electrically boosted FPSO tiebacks in Santos Basin.
- Subsea Trees:Wellhead-integrated boosting modules eliminate flowline routing complexity for single-well developments, deployed through drillship intervention in remote frontier basins.
- Pipeline Systems:Midline boosting stations extend subsea pipeline reach across challenging bathymetry, with Angola's Block 17 developments pioneering this architecture for distance-to-shore optimization.
Floating Platforms anchor procurement volume, while Pipeline Systems are expanding most quickly as basin-scale infrastructure matures.
End User:
Supply concentration among forging and subsea umbilical suppliers shapes procurement leverage differently across end-user categories with varying vertical integration depth.
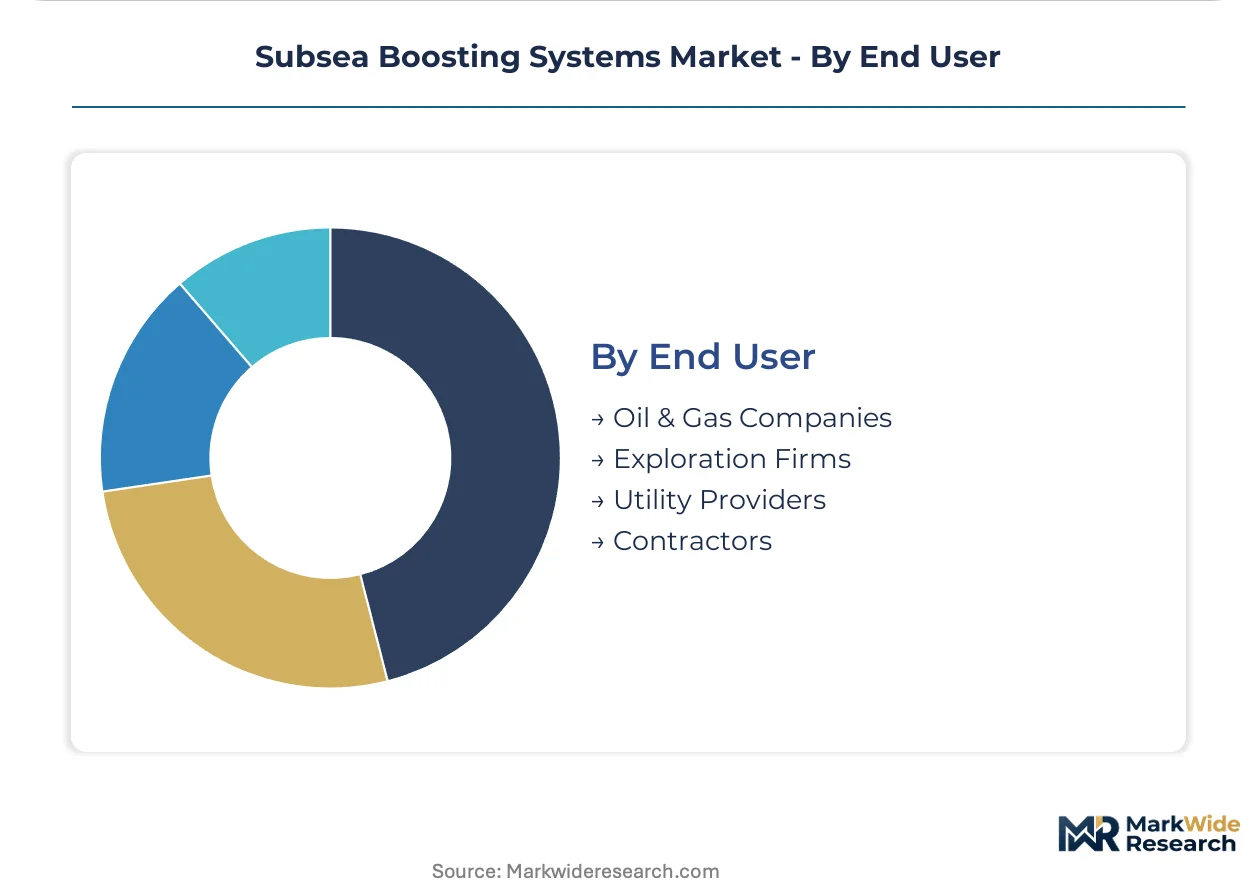
- Oil & Gas Companies:Integrated majors and national oil companies structure long-term service agreements around guaranteed uptime metrics, transferring operational risk to OEM service organizations in Brazil and Norway.
- Exploration Firms:Independent operators prioritize modular boosting architectures with compressed installation windows to accelerate first-oil timelines in pre-salt and ultra-deepwater frontiers.
- Utility Providers:Power generation and transmission entities entering offshore electrification partnerships specify subsea boosting compatibility with floating wind and hybrid energy platforms.
- Contractors:Subsea installation and maintenance specialists procure boosting equipment for lease or integrated service contracts, with demand tied to regional drilling campaign intensity.
Oil & Gas Companies dominate contract value, though Exploration Firms are driving the steepest technology specification changes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys more electric submersible boosting capacity than any other single market, while Norway concentrates the highest density of seabed compression installations per offshore block.
Brazil
Petrobras operates over 70 electrically boosted FPSO tiebacks in the Santos Basin pre-salt fairway, where carbonate reservoirs at 2,000-plus meters demand multiphase pumping. ANP N-2,790 standards mandate third-party validation of subsea production equipment. Rio de Janeiro hosts the largest cluster of turbomachinery engineering contractors serving Atlantic margin developments.
Norway
Equinor and Aker BP deploy wet gas compressors at Ormen Lange and Aasta Hansteen to eliminate platform processing entirely. The Petroleum Safety Authority enforces IEC 61511 functional safety certification for seabed processing with automated shutdown capabilities. Stavanger anchors the European subsea engineering cluster, with specialized forging facilities supplying duplex stainless steel components.
United States
Deepwater operators in the Gulf of Mexico specify integrated boosting with chemical injection for hydrate management across tiebacks exceeding 100 kilometers. BSEE requires subsea safety systems to meet API RP 14C and 30 CFR 250 specifications. Houston hosts the primary procurement and project management functions for Atlantic and ultra-deepwater frontier developments.
United Kingdom
North Sea brownfield operators face topside power constraints that limit electrification of legacy hydraulic boosting systems. The Health and Safety Executive enforces offshore safety case requirements for subsea processing modifications. Aberdeen maintains specialist engineering capacity for marginal field tieback architectures and decommissioning deferral solutions.
Angola
Block 17 operators pioneered midline boosting stations to extend pipeline reach across challenging bathymetry to shore. The national petroleum regulator mandates equipment qualification aligned with international standards. Luanda serves as the coordination hub for West African deepwater developments requiring modular deployment capabilities.
Subsea Boosting Systems Market Vendor Landscape
US-based energy technology conglomerates anchor one tier; Scandinavian engineering specialists hold differentiated positions in modular architectures. The market structures around integrated turbomachinery portfolios, permanent magnet motor technology, and subsea installation capabilities. Three archetypes dominate: full-service OEMs with service-contract business models, component specialists with proprietary motor or pump technologies, and installation-heavy contractors with integrated EPCI capabilities. Competitive moves concentrate on long-term service agreement structures and qualification cost sharing with national oil companies.
Among US-based technology providers, Baker Hughes and Halliburton occupy positions defined by integrated turbomachinery and service scale. SLB represents the permanent magnet motor technology archetype with emphasis on operational run-life extension. Aker Solutions exemplifies the modular boosting architecture specialist, targeting compressed field development cycles for marginal field economics.
| Leading Market Players |
|---|
| Baker Hughes |
| Halliburton |
| SLB |
| NOV Inc |
| Oceaneering International |
| Subsea 7 |
| Aker Solutions |
| Sulzer |
| TechnipFMC |
| Others |
Supply Flow & Price Mechanics
Permanent magnet motor adoption in deepwater boosting systems simultaneously compresses lifecycle operating costs and concentrates procurement leverage among turbomachinery OEMs with captive motor manufacturing. This technology transition rewards suppliers that internalize high-torque density production while penalizing pure-play hydraulic component vendors facing stranded asset risk.
Pricing Analysis
Capacity additions in Norway and Brazil are reshaping price floors for subsea boosting equipment as localized engineering clusters expand qualification capacity. Three-tier pricing structure across API 17Q-certified, ISO 13628-7-compliant, and pre-standard tiers separates Petrobras long-term service contracts from spot procurement by independent exploration firms. Cost compression in hydraulic system retrofits is intensifying because brownfield operators prioritize capital discipline over electrification premiums. National oil companies exhibit lowest price sensitivity due to operational availability guarantees, while marginal field developers in West Africa drive hardest bargain on modular deployment packages.
Supply Chain Analysis
Refurbishment flows for first-generation hydraulic boosting systems are creating secondary parts markets that compete with OEM spare parts pricing in mature North Sea basins. Duplex stainless steel forging concentrates in Norway, Sweden, and Finland, while permanent magnet motor winding feeds from Japanese and German precision manufacturing. Single-source vulnerability sits with Scandinavian metallurgical facilities supplying pressure-compensated housings rated beyond 300 bar. Distribution runs through integrated EPCI contractors that bundle boosting equipment with installation vessels and subsea intervention assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in subsea boosting systems rests on electrification-driven premium tiering and modular architecture standardization that collapses field development cycle costs.
For Market Incumbents: Extend long-term service agreement structures to lock out emerging turbomachinery competitors by embedding predictive maintenance algorithms into operational availability guarantees. Deepen backward integration into permanent magnet motor manufacturing to defend against SLB's proprietary high-torque density technology. Prioritize qualification cost-sharing partnerships with ANP and Norway's Petroleum Safety Authority to erect regulatory barriers for capital-constrained entrants. For New Entrants and Emerging Players: Subsea installation contractors represent the most accessible channel for technology licensing without captive vessel fleets. Target West African frontier basins where modular electric boosting eliminates hydraulic umbilical infrastructure and Petrobras-style service contracts have not yet standardized procurement. Pursue joint qualification programs with national petroleum regulators seeking to diversify supplier bases beyond incumbent oligopoly. For Investors and Strategic Acquirers: Roll-up economics work for specialized motor-winding and pressure-housing fabrication shops because API 17Q certification creates scarcity value that scales across multiple OEM customer relationships. Mid-cap engineering firms with IEC 61511 safety system expertise command premium multiples in an environment where functional safety validation timelines stretch to multiple years. Watch for inflection when Brazil's ANP accelerates pre-salt field sanctioning timelines beyond current Petrobras fleet deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Manufacturing Scale-Up | Captive production of high-torque density motors secures supply security for Santos Basin pre-salt tiebacks. |
| API 17Q Qualification Partnership | Shared validation costs with Petrobras reduce front-loaded engineering investment for electric boosting architectures. |
| Digital Twin Platform Integration | Real-time predictive maintenance algorithms enable condition-based service contracts displacing discrete equipment sales. |
| Modular Deployment Capability Buildout | Compressed installation windows from months to weeks unlock marginal field economics in remote West African basins. |
| Scandinavian Forging Supply Agreement | Long-term offtake contracts for duplex stainless steel mitigate capacity constraints at Norwegian metallurgical facilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with subsea project engineers, turbomachinery procurement leads at national oil companies, EPC contractors, offshore installation vessel operators, and aftermarket service directors with secondary validation. Regulatory filing analysis drew from ANP qualification databases, Norway Petroleum Safety Authority safety case registers, BSEE incident reports, and ISO certification body disclosures. Trade data, customs records for subsea umbilical and forging exports, and SEC filings from listed OEMs anchored bottom-up equipment deployment estimates against top-down field development sanctioning announcements.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across electric, hydraulic, mechanical, and pneumatic boosting technologies; oil extraction, gas transportation, water injection, and flow assurance applications; fixed platform, floating platform, subsea tree, and pipeline system installations; and oil and gas companies, exploration firms, utility providers, and contractor end users. CAGRs derived from equipment deployment trajectories in named deepwater basins, weighted by water depth complexity and tieback distance assumptions.
Revisions become necessary when pre-salt field sanctioning timelines shift, permanent magnet motor supply constraints emerge, or decommissioning liability frameworks alter marginal field investment thresholds. Forecasts reflect documented assumptions regarding electrification adoption curves and qualification cycle durations. Periodic stress-testing of base assumptions against actual Petrobras FPSO deployment rates and Norway seabed compression project awards is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Wellhead System Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
United States Oil and Gas Midstream Market